
 Suborbital Space Tourism Market | 2026-2036
Suborbital Space Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Suborbital Space Tourism Market Insights
Affluent individuals are restructuring the customer base as research organizations scale their flight manifests for microgravity experiments. Virgin Galactic leverages its air-launched vehicle architecture to control coastal launch pad access. Blue Origin sustains vertical landing capabilities that dominate reusable rocket operations. SpaceX anchors its broader orbital expertise to extend suborbital training missions for prospective astronauts.
Suborbital space tourism encompasses brief flights reaching altitudes between 80 and 100 kilometers, where passengers experience several minutes of weightlessness before atmospheric re-entry; vehicles typically employ rocket-powered spaceplanes or reusable vertical-launch systems with thermal protection systems rated for multiple cycles per month. The vehicle type dimension concentrates margin pools around reusable rockets and spaceplanes, where refurbishment economics outperform balloon-based alternatives. Customer type segmentation shows adventure seekers and affluent individuals driving near-term booking volumes, while research organizations command premium pricing for dedicated payload integration.
The FAA mandates commercial spaceflight operator licenses and experimental permits under 51 U.S.C. Chapter 509, while the U.S. Department of Transportation oversees spaceport infrastructure grants that shape launch site availability. ISO 14620-1 safety standards and the FAA's informed consent framework for spaceflight participants govern vehicle design and passenger liability protocols. Stakeholders must monitor how evolving payload classification rules and international airspace coordination agreements will reshape route planning and cross-border operational permissions.
Market Dynamics
The FAA's streamlined commercial spaceflight licensing framework is compressing operator certification timelines and concentrating operational gravity around established spaceports with proven infrastructure and regulatory relationships.
Growth Catalysts
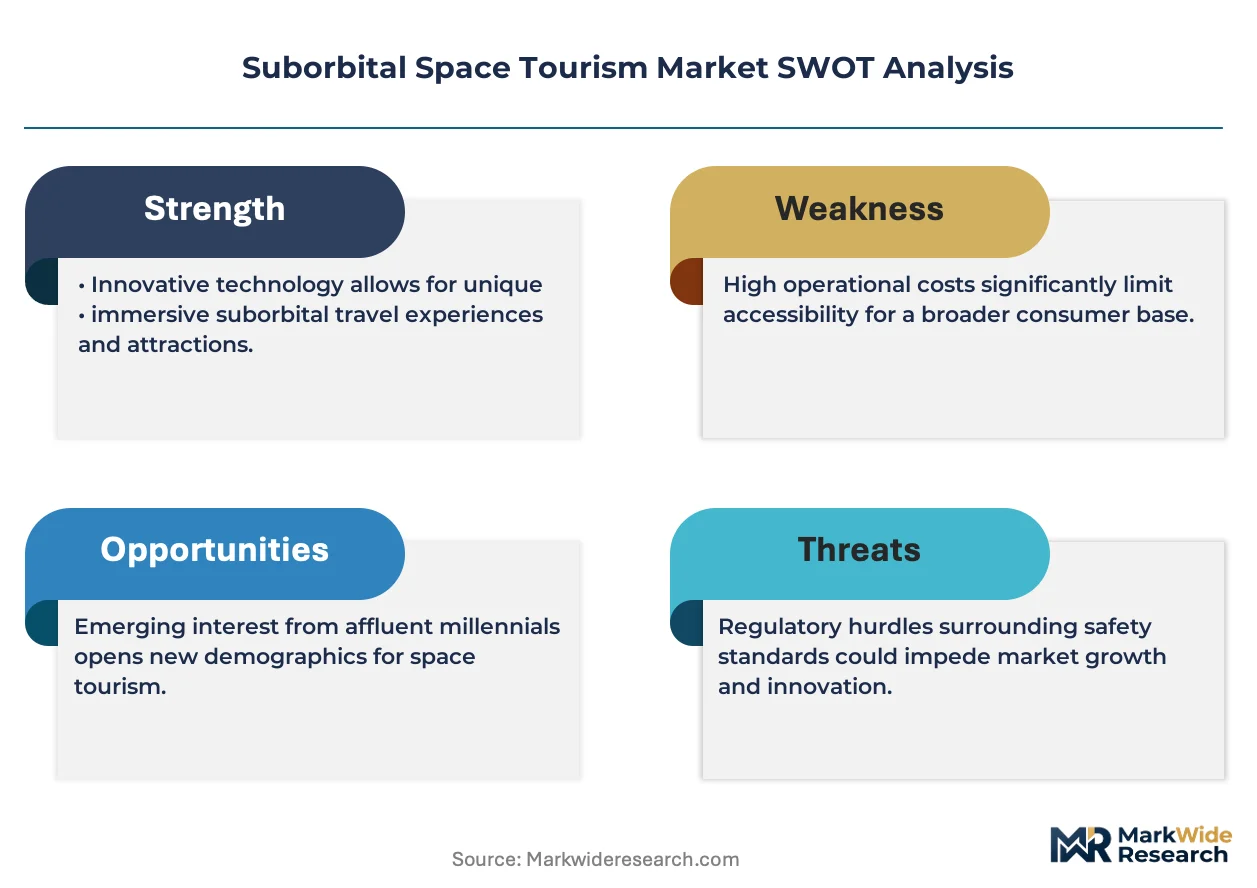
- FAA Licensing Acceleration:The FAA's experimental permit pathway under 51 U.S.C. Chapter 509 reduces pre-flight approval cycles, enabling operators to scale flight cadence faster than European counterparts constrained by EASA's nascent space tourism protocols.
- Research Payload Integration:Microgravity experiment demand from pharmaceutical developers and materials science laboratories is diversifying revenue streams beyond passenger ticket sales, with dedicated rack space commanding premium utilization rates.
- Coastal Spaceport Clustering:Launch site concentration in New Mexico, Texas, and Florida creates operational density that drives down per-flight logistics costs through shared range services and consolidated supply chains.
Market Restraints
- Propellant Cost Volatility:Liquid oxygen and RP-1 kerosene price swings directly compress per-flight margins, with spot market spikes in hydrocarbon feedstocks translating to unpredictable operating expenditure trajectories.
- Vehicle Supplier Concentration:Thermal protection system fabrication relies on a narrow base of aerospace composite specialists, creating single-source vulnerability for ablative heat shield refurbishment cycles.
- Altitude Ceiling Limitation:Suborbital trajectories cap at approximately 100 kilometers, preventing orbital velocity experiences that would command substantially higher pricing power against orbital tourism alternatives.
Strategic Opportunities
- Underpenetrated Asia-Pacific Demand:Japan's METI space commercialization roadmap and Australia's emerging spaceport infrastructure in Queensland present first-mover positioning for operators establishing regional training and departure hubs.
- Hybrid Training-Experience Bundles:Convergence of centrifuge-based pre-flight conditioning with actual suborbital missions creates tiered product architectures that extend customer lifetime value through multi-touch engagement models.
- Spaceport Infrastructure Grants:The U.S. Department of Transportation's discretionary funding for launch site development is expanding available departure points beyond current coastal concentrations into interior mountain west corridors.
Industry Challenges
- Astronaut Corps Recruitment Bottleneck:Pilot-astronaut certification requirements exceed commercial aviation training depth, with experienced test pilots commanding compensation premiums that strain fixed-cost structures.
- Vehicle Airworthiness Recertification:FAA mandate for post-flight inspection and component replacement cycles creates downtime intervals that compress achievable annual flight rates per operational vehicle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suborbital Space Tourism Market |
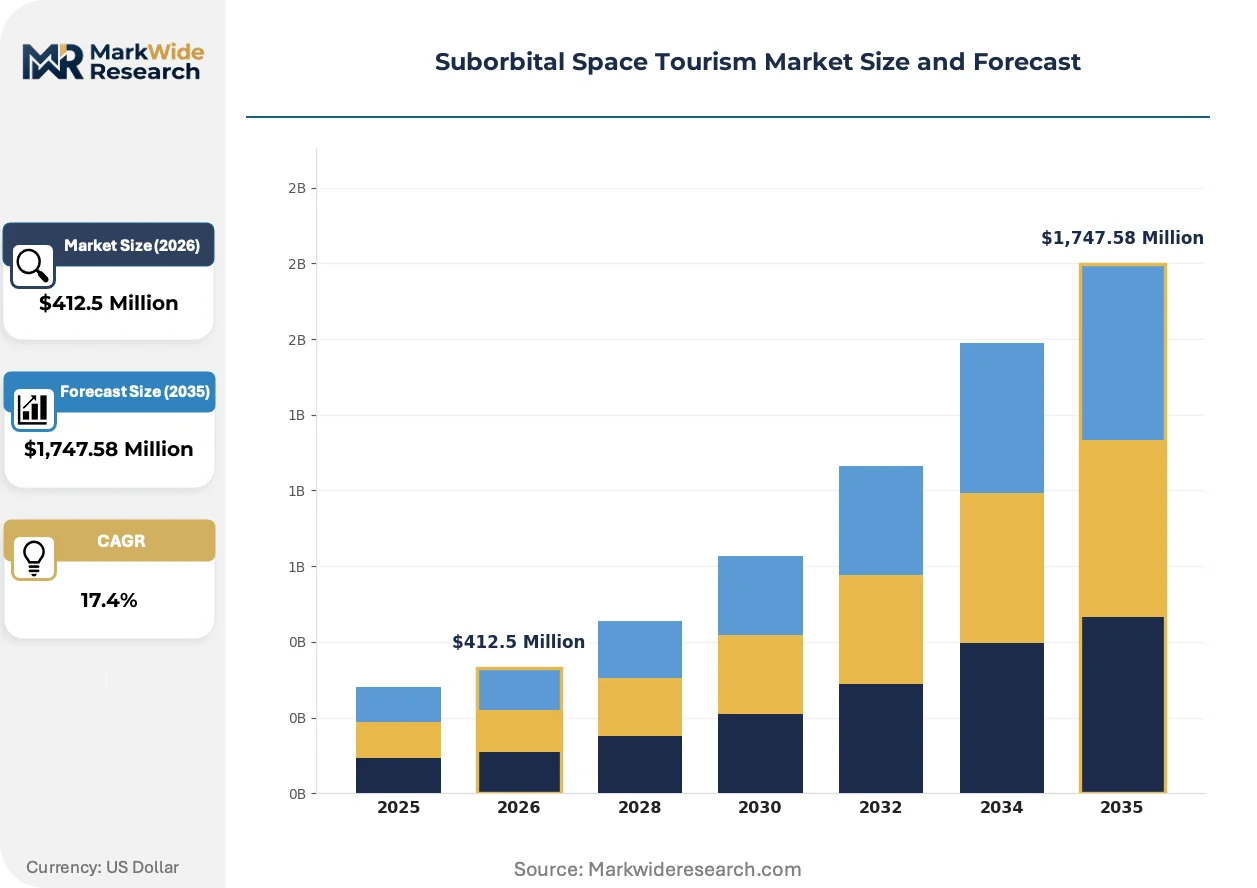
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,747.58 Million |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Brief Flight, Parabolic Flight, Zero-Gravity Experience, Suborbital Jump, Spacewalk Training Vehicle Type: Reusable Rocket, Spaceplane, Balloon, Hybrid Rocket, Air-Launched Vehicle Customer Type: Affluent Individuals, Adventure Seekers, Research Organizations, Corporate Clients, High-Net-Worth Collectors Launch Site Type: Coastal Launch Pad, Desert Facility, Mountain Range Base, Island Platform, Inland Spaceport |
| Companies Covered | Virgin Galactic, Blue Origin, SpaceX, Space Adventures, Axiom Space, Sierra Space, Space Perspective, Zero 2 Infinity, World View Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suborbital Space Tourism Market Trends and Innovations
Automation is penetrating vehicle operations, regulatory compliance, and passenger management systems simultaneously, creating efficiency gains that reshape unit economics across the value chain.
Autonomous flight control systems are automating trajectory optimization and abort decision protocols during powered ascent and re-entry phases. Operators with established flight heritage are retrofitting existing spaceplanes with upgraded avionics packages that reduce crew workload requirements. This automation is compressing training timelines for flight personnel while enabling higher-frequency operational cadences that approach commercial aviation turnaround standards.
REACH regulatory alignment discussions in Europe are forcing vehicle manufacturers to disclose chemical composition of propellants, thermal protection materials, and life support consumables. The industrial consequence is accelerated substitution of legacy ablative materials toward ceramic matrix composites with cleaner environmental profiles. Suborbital operators targeting eventual European departure points are front-loading material qualification programs to preempt market access barriers.
Research organizations are consolidating flight manifests through shared payload arrangements rather than dedicated mission purchases. This buyer aggregation disrupts traditional single-customer flight economics and forces operators to develop modular rack systems compatible with multi-experiment configurations. The shift is most visible in United States university consortiums pooling National Science Foundation grants for standardized microgravity access.
Suborbital Space Tourism Market Segmentation
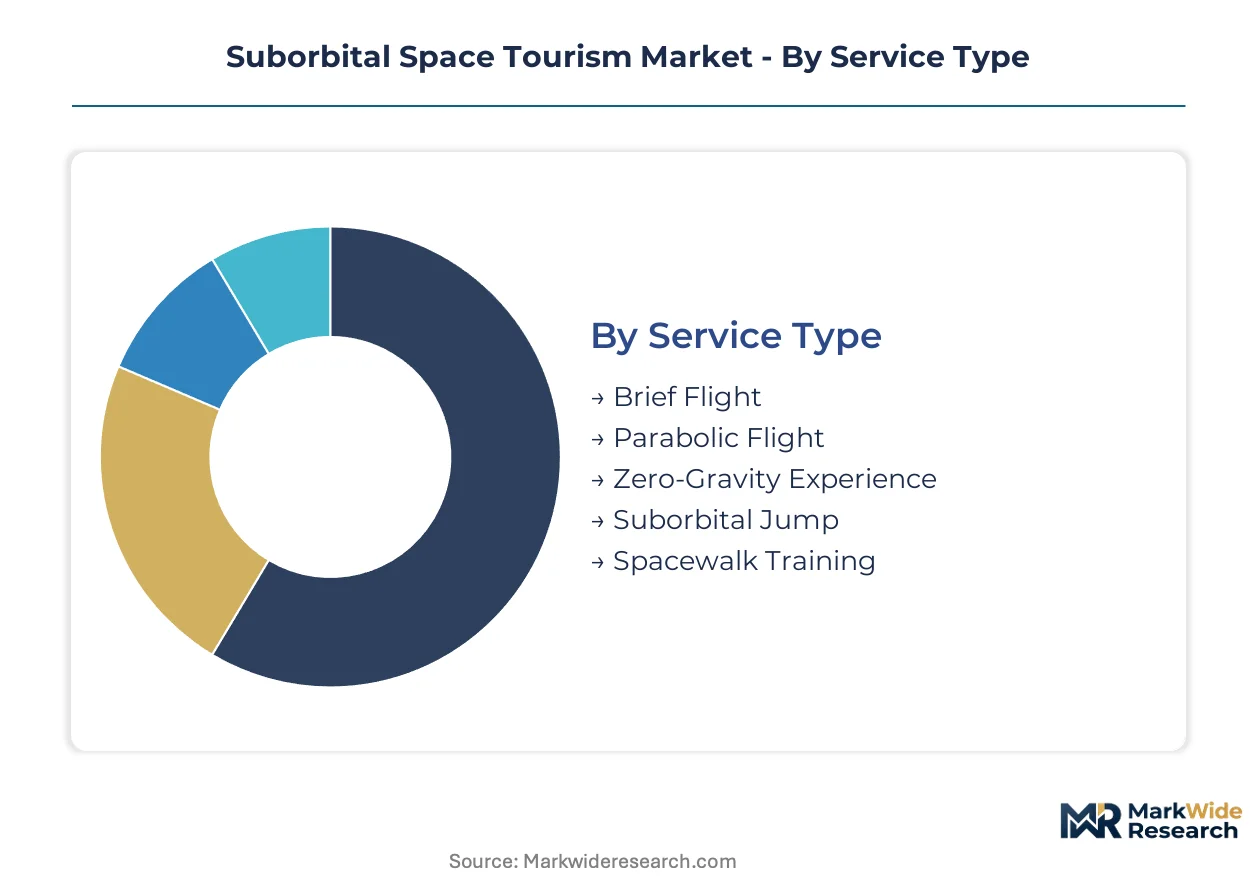
Suborbital space tourism operators must align vehicle capabilities, service duration, and customer expectations across distinct purchasing profiles. Segmentation reveals where premium pricing power concentrates versus where volume scaling becomes necessary.
Service Type:
Price sensitivity and experience depth separate buyers across this category, with mission duration directly correlating to preparation requirements and liability exposure.
- Brief Flight:Compressed ascents to 80-100 kilometers delivering 4-6 minutes of weightlessness. Demand clusters in the United States from affluent individuals seeking entry-level space access without multi-day training protocols.
- Suborbital Jump:Extended trajectory profiles with controlled atmospheric re-entry sequences. Research organizations in Texas and New Mexico command dedicated manifests for pharmaceutical microgravity trials, paying utilization premiums for rack space allocation.
- Parabolic Flight:Aircraft-based zero-gravity simulation through repeated pitch maneuvers. Corporate training programs purchase bulk seats for astronaut candidate screening.
- Zero-Gravity Experience:Neutral buoyancy pool training combined with reduced-gravity aircraft flights. Aviation regulators in the United States classify these under Part 121 commercial aviation rules rather than spaceflight licensing.
- Spacewalk Training:Pressurized suit operations in vacuum chambers preceding actual flight. Government space agencies purchase these modules for astronaut preparation.
Volume sits with Brief Flight; growth tilts toward Suborbital Jump.
Vehicle Type:
Refurbishment economics and flight cadence potential determine operator preference, with thermal protection durability separating profitable platforms from cost-drain architectures.
- Reusable Rocket:Vertical launch and powered landing systems rated for monthly flight cycles. Blue Origin's New Shepard operations in Texas demonstrate turnaround intervals under 30 days between missions.
- Spaceplane:Horizontal runway takeoff and glide landing with hybrid propulsion. Virgin Galactic's air-launched architecture from Spaceport America enables coastal departure flexibility that ground-launched systems cannot match.
- Balloon:High-altitude pressurized capsules lifted by helium or hydrogen envelopes. Swiss Stratospheric balloon operators target luxury tourism with extended duration but lower altitude ceilings.
- Hybrid Rocket:Solid fuel boosters combined with liquid oxidizer systems for throttle control. Safety certification complexity limits FAA licensing velocity for new entrants.
- Air-Launched Vehicle:Carrier aircraft deployment at altitude before rocket ignition. Reduced atmospheric drag improves payload efficiency for research missions.
Margin concentrates in Reusable Rocket; capability differentiation favors Spaceplane.
Customer Type:
Purchasing authority and mission customization requirements create distinct sales cycle lengths, with institutional buyers demanding payload integration that individual tourists cannot justify.
- Research Organizations:Universities and pharmaceutical developers purchasing dedicated flight segments with experiment rack specifications. National Science Foundation grant recipients in the United States consolidate manifests through consortium arrangements.
- High-Net-Worth Collectors:Individuals with liquid assets exceeding $30 million seeking exclusive experience ownership. These buyers purchase full vehicle charters rather than individual seats.
- Affluent Individuals:Upper-income consumers financing personal spaceflight through installment programs. Virgin Galactic's reservation backlog demonstrates this segment's scale.
- Adventure Seekers:Experience-driven consumers comparing suborbital flight against polar expeditions and deep-sea dives. Price elasticity exceeds that of collector segments.
- Corporate Clients:Technology and aerospace firms purchasing employee reward programs and executive development experiences. Bulk purchasing agreements include pre-flight conditioning packages.
Booking volume sits with Affluent Individuals; expansion trajectory is steepest for Research Organizations.
Launch Site Type:
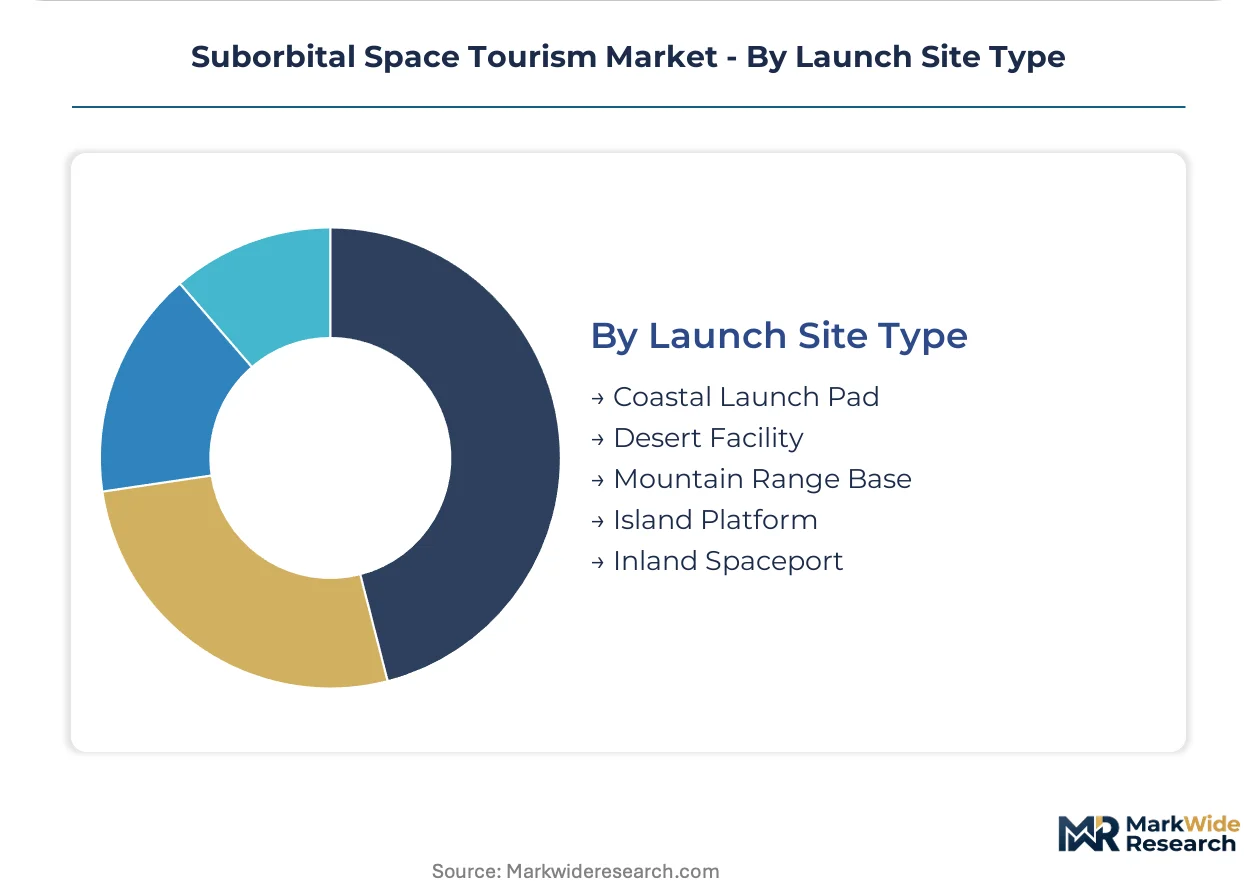
Infrastructure maturity and regulatory pre-clearance status determine operator site selection, with coastal locations offering overwater abort corridors that interior facilities cannot provide.
- Coastal Launch Pad:Eastern and western seaboard facilities with established FAA range safety protocols. Florida's Space Coast and California's Vandenberg complex anchor operational density.
- Desert Facility:Isolated southwestern terrain with restricted airspace and predictable weather windows. Spaceport America in New Mexico operates under FAA commercial spaceport license.
- Mountain Range Base:High-altitude departure points reducing atmospheric drag during initial ascent. Colorado and Wyoming sites remain pre-commercial due to infrastructure gaps.
- Island Platform:Pacific and Atlantic locations offering 360-degree abort corridors. Hawaii and Puerto Rico sites face environmental review delays.
- Inland Spaceport:Interior facilities targeting cargo and eventual point-to-point suborbital transport. Texas Midland development receives Department of Transportation infrastructure grants.
Operational gravity centers on Coastal Launch Pad; Desert Facility gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch infrastructure concentrates in the United States while demand formation spreads across affluent consumer clusters in Asia-Pacific and the Middle East. Production capacity for suborbital vehicles and spaceport facilities remains anchored in North America, with consumption interest emerging faster in non-operational geographies lacking indigenous launch capabilities.
United States
New Mexico's Spaceport America and Texas launch corridors anchor operational infrastructure, with Virgin Galactic and Blue Origin maintaining active flight programs. The FAA's streamlined licensing under 51 U.S.C. Chapter 509 compresses operator certification timelines. Coastal spaceport clustering in Florida and California drives per-flight logistics costs downward through shared range services.
United Arab Emirates
High-net-worth collector demand from Dubai and Abu Dhabi is accelerating faster than indigenous infrastructure development. The UAE Space Agency's commercial spaceflight framework remains under development, creating regulatory lag. Dubai-based investment vehicles are purchasing full vehicle charters from US operators pending regional spaceport completion.
Japan
METI's space commercialization roadmap is channeling public-private partnerships toward suborbital training hub development. The national aerospace regulator is adapting aviation safety protocols for spaceflight participant liability. Kyushu and Hokkaido sites are advancing environmental assessments for prospective launch facilities.
Australia
Queensland's emerging spaceport infrastructure targets first-mover positioning for Asia-Pacific departure hubs. The Australian Space Agency's launch facility licensing framework attracted Sierra Space for regional training operations. Whitsunday and Bowen corridors offer overwater abort profiles comparable to Florida's Space Coast.
United Kingdom
Scottish spaceport development in Sutherland and Shetland is advancing vertical launch capability for suborbital research missions. The UK Space Agency's regulatory framework under the Space Industry Act 2018 is maturing toward commercial licensing. Cornwall's horizontal launch facility exemplifies air-launched vehicle compatibility for coastal operations.
Suborbital Space Tourism Market Competitive Landscape
Top-tier vendors anchor integrated spaceflight operations, while mid-tier specialists concentrate on balloon-based experiences and training modules. The competitive structure stratifies across three tiers: vertically integrated operators controlling vehicle manufacturing and launch infrastructure; experience aggregators packaging third-party capacity; and component suppliers selling thermal protection and life support systems. Consolidation pressure is accelerating through strategic partnerships between vehicle developers and spaceport operators, alongside technology licensing arrangements for reusable rocket architectures.
Within the integrated operator tier, Virgin Galactic, Blue Origin, and SpaceX exemplify distinct technical archetypes. Virgin Galactic represents air-launched spaceplane architecture with horizontal runway operations. Blue Origin occupies a position centered on vertical launch and powered landing reusability. SpaceX anchors the premium training segment, leveraging orbital expertise for suborbital astronaut preparation programs. These three entities collectively define competitive intensity through divergent vehicle economics and customer access models.
| Leading Market Players |
|---|
| Virgin Galactic |
| Blue Origin |
| SpaceX |
| Space Adventures |
| Axiom Space |
| Sierra Space |
| Space Perspective |
| Zero 2 Infinity |
| World View Enterprises |
| Others |
Pricing and Supply Chain Analysis
Vehicle certification tiers bifurcate the suborbital market into FAA-licensed commercial operators and experimental permit holders, with that divergence manifesting in both ticket pricing spreads and supply chain qualification requirements. Premium operators command five-figure seat pricing through captive thermal protection fabrication, while experimental-tier competitors face supplier exclusion from aerospace-grade composite networks.
Pricing Analysis
Lead-time-driven pricing angles dominate seat allocation, with 90-day advance bookings commanding premium positioning versus spot inventory released within 30 days of flight windows. Three-tier pricing structure across premium, standard, and economy levels segments buyers by pre-flight conditioning depth and payload integration rights. Pricing pressure stems from propellant cost volatility in liquid oxygen and RP-1 kerosene spot markets, compressing per-flight margins for operators without long-term fuel offtake contracts. Adventure seekers exhibit highest price elasticity, while research organizations demonstrate lowest sensitivity given grant-funded mission budgets.
Supply Chain Analysis
Direct-to-operator channels handle vehicle component procurement for integrated manufacturers, bypassing distribution intermediaries for thermal protection systems and propulsion assemblies. Geographic supply concentration centers on the United States, Germany, and Japan for aerospace-grade composites, avionics packages, and life support consumables. Raw material dependencies include carbon fiber prepregs, ablative cork composites, and cryogenic valve assemblies. Single-source vulnerability characterizes thermal protection system fabrication, where qualified suppliers number fewer than five globally. Distribution runs through long-term master service agreements rather than spot purchasing for flight-critical components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA licensing under 51 U.S.C. Chapter 509 erects a cost-of-compliance barrier that protects certified incumbents from rapid competitive entry, creating durable moats around established operator permits and spaceport relationships.
For Market Incumbents: Extend flight cadence capabilities through automation retrofits that compress post-flight inspection intervals mandated by FAA airworthiness recertification protocols. Consolidate thermal protection system suppliers through equity positions or exclusive offtake arrangements, defending against single-source vulnerability that could ground fleets during refurbishment bottlenecks. Prioritize vertical integration into propellant storage infrastructure at coastal spaceport clusters to capture margin pools currently leaking to third-party logistics providers.
For New Entrants and Emerging Players: The pricing gap between full-vehicle charters and individual seat sales creates white-space positioning for fractional ownership models targeting high-net-worth collectors with liquid assets below full-charter thresholds. Target Asia-Pacific training hub development in Queensland and Kyushu, where regulatory frameworks remain under construction and first-mover positioning is achievable. Pursue go-to-market angles through university consortium partnerships for shared payload arrangements, leveraging National Science Foundation grant flows to underwrite initial flight manifests.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated operators possessing both vehicle manufacturing and launch infrastructure control, given FAA licensing acceleration compressing certification timelines for compliant players. Long-term viability favors entities with demonstrated flight heritage exceeding ten missions, where insurance underwriters recognize actuarial data sufficient for premium reduction. Acquisition target archetype: mid-scale spaceplane developers with air-launched vehicle architecture and coastal spaceport access agreements. Signal to watch: FAA issuance of reusable launch vehicle operator licenses to second-tier applicants, indicating regulatory capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Operator License Expansion | Accelerated certification timelines under 51 U.S.C. Chapter 509 compress competitive entry barriers for compliant applicants. |
| Coastal Spaceport Clustering | Concentrated launch infrastructure in Florida, Texas, and New Mexico drives per-flight logistics cost reduction through shared range services. |
| Automation Retrofit Programs | Avionics upgrades reducing crew workload requirements enable turnaround intervals approaching commercial aviation standards. |
| Research Payload Integration | Modular rack systems compatible with multi-experiment configurations capture pharmaceutical and materials science laboratory demand. |
| Asia-Pacific Hub Development | Queensland and Kyushu training facilities address underpenetrated demand from Japan's METI commercialization roadmap participants. |
Research Methodology
Multi-period observation of flight cadence metrics, vehicle refurbishment intervals, and regulatory approval timelines anchored the trend analysis, supplemented by interviews with suborbital vehicle program managers, FAA commercial spaceflight licensing officers, spaceport operations directors, and thermal protection system procurement leads at aerospace composite manufacturers. Secondary validation drew from FAA commercial spaceflight license databases, Department of Transportation spaceport infrastructure grant disclosures, National Science Foundation microgravity research award records, and ISO 14620-1 safety standard documentation. Bottom-up triangulation across operator flight manifests converged with top-down market sizing through customer segment wallet analysis.
Segment-weighting approaches distributed value estimates across service type, vehicle architecture, customer category, and launch site geography dimensions throughout the projection horizon. CAGRs were derived from fitted growth curves calibrated to historical flight rate trajectories and announced vehicle production schedules. Industry-specific forecast inputs included propellant cost indices for liquid oxygen and RP-1 kerosene, thermal protection system refurbishment cycle durations, and pilot-astronaut certification pipeline throughput estimates.
Inputs from FAA licensing databases and operator flight manifest disclosures were available through the study window; gaps in proprietary vehicle cost structures and insurance premium pricing introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding sustained regulatory streamlining, propellant supply stability, and research organization funding continuity. Periodic stress-testing of base assumptions is recommended against propellant price volatility scenarios and alternative orbital tourism competitive threats.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Rocket Launchpad Market
Space
Space Sensors Market
Space
US Space Electronics Market
Space
Mexico Space Electronics Market
Space
Space Technology (Spacetech) Market
Space
South Korea Space Electronics Market
Space
Carrier Rocket Market
Space
Space on Board Computing Platform Market
Space
Space in Orbit Refueling Market
Space
Spain Space Electronics Market
Space
Space As a Service Market
Space
Japan Space Electronics Market
Space
Asia-Pacific Space Electronics Market
Space
Space Colonization Market
Space
Near Space Robotics Market
Space
France Space Electronics Market