
 LAMEA Space As a Service Market | 2026-2036
LAMEA Space As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Space As a Service Market Analytics
Market Context
Ground station operators across Latin America, the Middle East, and Africa are realigning capital deployment toward sovereign cloud infrastructure. SpaceX leverages its reusable launch architecture to undercut legacy providers on cost per kilogram to orbit. Microsoft sustains competitive positioning through Azure Orbital and dedicated ground station partnerships in the UAE and South Africa. Huawei Technologies anchors regional presence via data center integrations that comply with local data residency mandates.
Technical Definition and Segment Structure
Space As a Service denotes the commercial provision of space infrastructure capabilities—including satellite bandwidth, launch capacity, ground segment operations, and downstream analytics—delivered through subscription or pay-per-use models rather than asset ownership. The offering eliminates capital intensity for end users while embedding artificial intelligence and big data processing layers that transform raw telemetry into actionable intelligence for telecom network optimization and agricultural monitoring. Launch Services currently dominates revenue composition due to backlog from constellation deployment programs, while Data Services represents the fastest-expanding margin pool as AI-driven predictive analytics command premium pricing from government agencies and research institutions. Ground Services maintains steady growth trajectories across the Middle East, where desert geography favors optical ground station siting.
Regulatory Framework and Outlook
Brazil's national space regulator and the UAE's telecommunications authority impose frequency coordination and orbital slot registration requirements that filter market access for non-compliant operators. South Africa's adherence to ISO satellite operations standards and data protection frameworks shapes procurement specifications for research institutions. Stakeholders must monitor evolving spectrum allocation policies and cross-border data transfer restrictions as sovereign cloud mandates proliferate across the region.
Market Dynamics
Sovereign data residency mandates across Latin America, the Middle East, and Africa are forcing ground station operators to deploy localized cloud infrastructure rather than rely on foreign-hosted processing facilities.
Growth Catalysts
- Precision agriculture telemetry:Commercial farming enterprises in Brazil and South Africa are subscribing to satellite imagery analytics for crop yield optimization and irrigation management.
- UAE sovereign wealth deployment:Abu Dhabi-based infrastructure funds are financing optical ground station networks to capture geostationary and low-Earth orbit traffic.
- ISO satellite operations standards:South African research institutions now require compliance with these frameworks, standardizing procurement specifications and expanding addressable vendor pools.
Market Restraints
- Launch capacity concentration:Reusable vehicle providers based in North America control pricing for rideshare missions, limiting margin negotiation for regional constellation operators.
- Optical ground station siting constraints:Desert geography in the Middle East creates favorable atmospheric conditions, yet fiber backhaul infrastructure gaps in remote locations inflate connectivity costs.
- Frequency coordination delays:Brazil's national space regulator imposes extended orbital slot registration timelines that stall service activation for non-domestic operators.
Strategic Opportunities
- Sub-Saharan Africa connectivity gaps:Nigeria and Kenya present underpenetrated addressable markets for satellite broadband services targeting unconnected rural populations.
- AI-driven predictive analytics:Government agencies in the UAE are commissioning subscription-based intelligence layers that transform raw telemetry into actionable forecasting for infrastructure monitoring.
- Brazilian data sovereignty requirements:Updated national space policy mandates local processing for sensitive government contracts, creating procurement preference for domestic-integrated ground segment providers.
Industry Challenges
- RF engineering talent scarcity:The Middle East lacks sufficient specialized workforce for optical ground station calibration and phased array antenna maintenance.
- Cross-border spectrum harmonization:Divergent national allocation policies between South Africa and neighboring states complicate seamless satellite handoff protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Space As a Service Market |
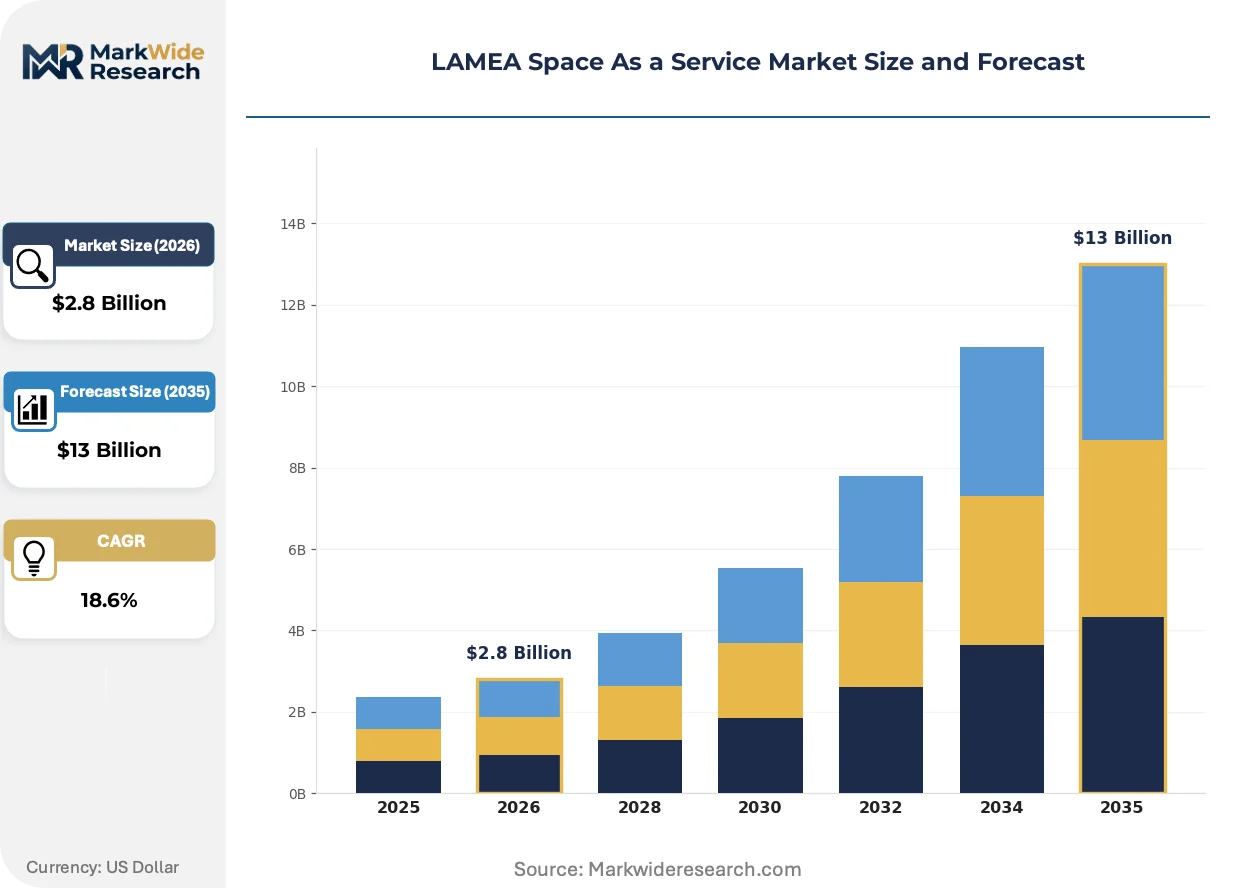
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Launch Services, Satellite Services, Ground Services, Data Services End User: Telecom Companies, Government Agencies, Research Institutions, Commercial Enterprises Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology: Artificial Intelligence, Internet of Things, Blockchain, Big Data |
| Companies Covered | Amazon Web Services, Google, Microsoft, IBM, Oracle, Huawei Technologies, SpaceX, Alibaba Cloud, SAP, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Space As a Service Market Evolving Landscape
Artificial intelligence integration into downstream analytics is compressing the value chain between raw satellite data and client-ready intelligence products.
Hyperspectral imaging sensors are expanding into agricultural monitoring and mineral exploration applications across Brazil's Cerrado and the UAE's desert interior. Mining conglomerates and agribusiness operators are subscribing to weekly revisit frequencies for subsurface moisture and ore body detection. This capability expansion is compressing the competitive advantage of traditional aerial survey providers who cannot match orbital revisit economics.
Brazil's updated national space policy imposes mandatory local data processing for government contracts involving classified or sensitive territorial information. The regulation forces foreign operators to establish domestic ground station partnerships or forfeit public sector revenue streams. Satellite imagery providers are responding by licensing technology to Brazilian infrastructure partners rather than operating direct service arms.
Subscription-based procurement is displacing capital-intensive satellite ownership among research institutions and mid-sized agricultural enterprises. Annual service contracts with guaranteed uptime tiers are replacing multi-million dollar spacecraft procurement cycles. This behavioral shift is most visible in South Africa, where universities now prioritize operational expenditure budgets over grant-funded asset acquisition.
LAMEA Space As a Service Market Segmentation
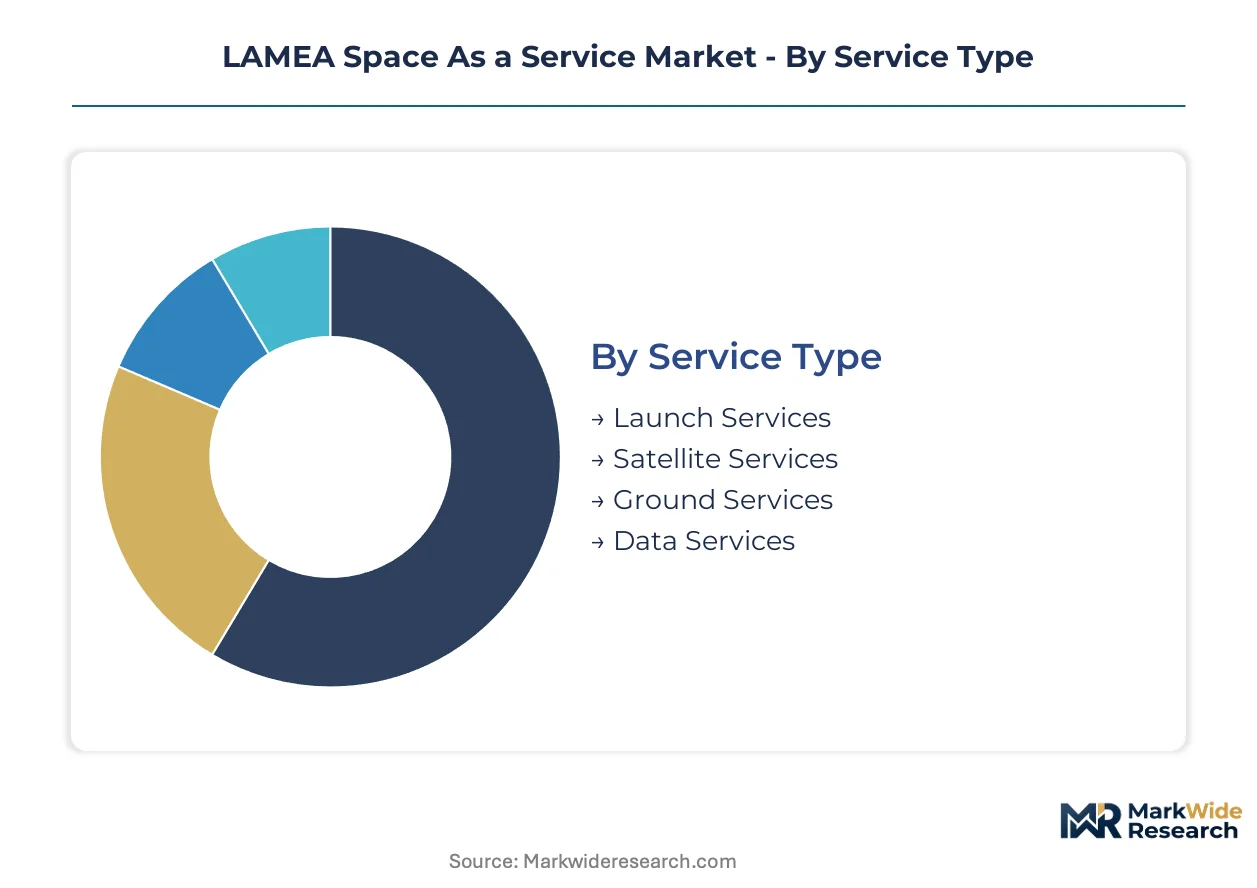
Segmentation in the LAMEA Space As a Service market reveals divergent procurement priorities across sovereign and commercial buyers. Service delivery models, deployment architectures, and technology stacks fragment according to data residency mandates and capital intensity preferences.
Service Type:
Buyers differentiate by their tolerance for capital expenditure versus operational flexibility, with constellation operators and government agencies occupying opposite ends of this spectrum.
- Launch Services:Reusable vehicle capacity and rideshare mission economics define this segment. Demand concentrates among constellation deployment programs in Brazil and the UAE, where backlog from low-Earth orbit satellite networks sustains pricing power for providers with demonstrated flight heritage.
- Data Services:AI-driven predictive analytics and downstream intelligence layers command premium subscription pricing. Government agencies across the UAE are commissioning infrastructure monitoring forecasts, expanding addressable margins faster than raw telemetry provisioning.
- Satellite Services:Bandwidth leasing and hosted payload arrangements serve telecom operators seeking to avoid spacecraft procurement cycles.
- Ground Services:Optical ground station networks and phased array antenna operations anchor regional presence for sovereign cloud compliance.
Volume sits with Launch Services; growth tilts toward Data Services.
End User:
Procurement authority and budget cycles create distinct buying behaviors across institutional categories.
- Government Agencies:Sovereign data residency requirements and classified information handling protocols shape vendor selection. Brazil's updated national space policy mandates local processing for sensitive contracts, filtering market access to domestically integrated providers.
- Commercial Enterprises:Agribusiness operators and mining conglomerates subscribe to weekly hyperspectral revisit frequencies for crop yield and subsurface mineral detection. Precision agriculture telemetry in Brazil's Cerrado drives recurring revenue expansion.
- Telecom Companies:Rural connectivity gaps in Nigeria and Kenya attract satellite broadband procurement for unconnected populations.
- Research Institutions:South African universities now prioritize operational expenditure budgets over grant-funded asset acquisition, favoring subscription models.
Revenue concentrates with Government Agencies; margin expansion favors Commercial Enterprises.
Deployment Model:
Infrastructure location decisions hinge on cross-border data transfer restrictions and latency requirements for real-time telemetry.
- Private Cloud:Dedicated ground station partnerships with localized processing capacity satisfy Brazilian data sovereignty mandates and UAE sovereign wealth project specifications. Foreign operators license technology to domestic infrastructure partners rather than operate direct service arms.
- Hybrid Cloud:Split architectures allow sensitive processing on-premises while leveraging scalable analytics in sovereign-hosted environments. South African research institutions favor this model for ISO satellite operations compliance.
- Public Cloud:Microsoft Azure Orbital and similar platforms serve customers without data residency constraints.
- On-Premises:Fully captive infrastructure supports defense and intelligence community requirements.
Adoption clusters around Private Cloud; Hybrid Cloud climbs the fastest.
Technology:
Integration depth separates commodity connectivity providers from value-added intelligence vendors.
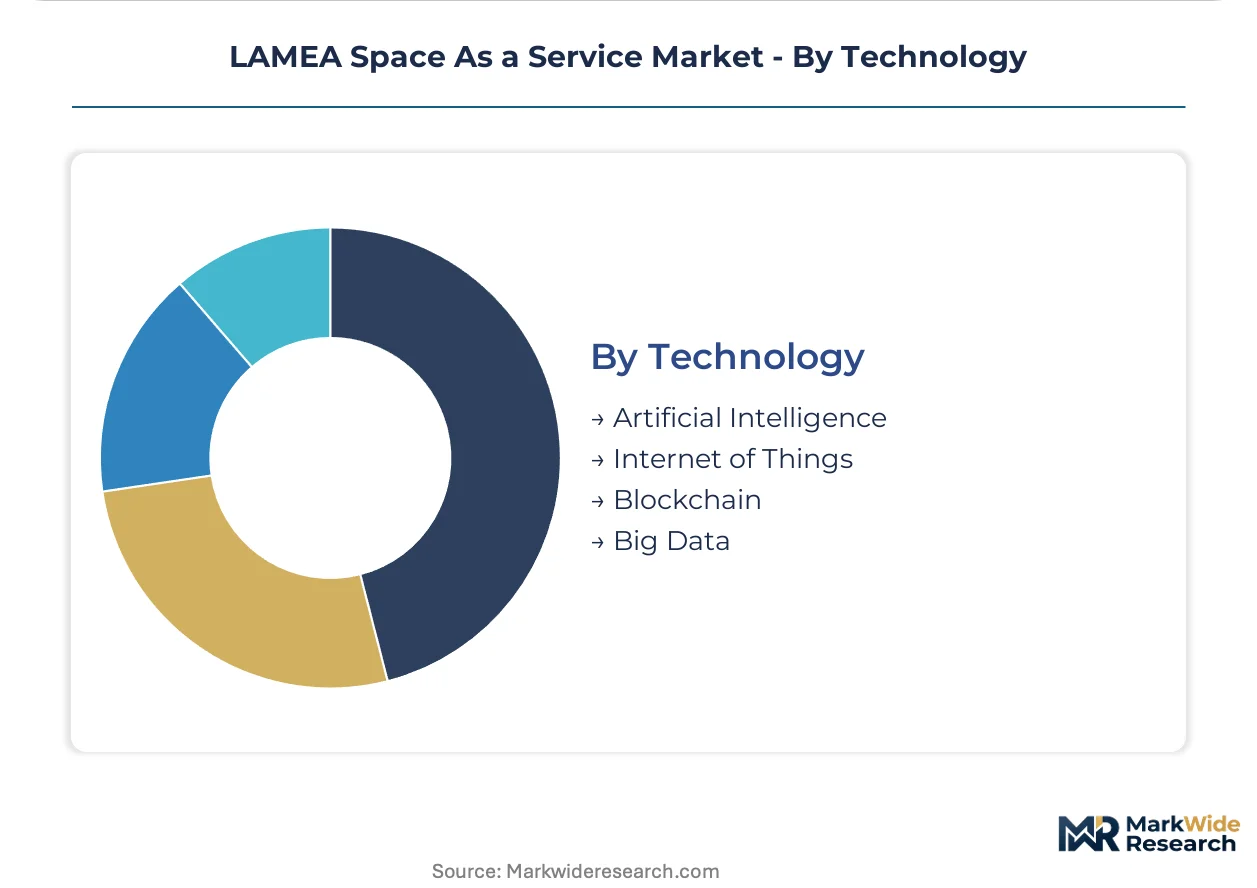
- Artificial Intelligence:Machine learning pipelines transform raw satellite imagery into client-ready intelligence products, compressing value chain margins previously captured by manual analytics providers. AI integration enables predictive infrastructure monitoring for UAE government contracts.
- Big Data:Telemetry aggregation at constellation scale requires specialized storage and query architectures. Desert geography in the Middle East favors optical ground station siting, though fiber backhaul gaps inflate connectivity costs for distributed processing.
- Internet of Things:Sensor network integration extends satellite connectivity to remote agricultural and industrial monitoring endpoints.
- Blockchain:Distributed ledger applications address data provenance and contract automation for multi-party satellite resource sharing.
Investment prioritizes Artificial Intelligence; Blockchain trails in commercial deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Satellite ground station infrastructure concentrates in desert geographies with favorable atmospheric conditions. Fiber backhaul availability and sovereign data residency mandates determine operational viability across national markets.
United Arab Emirates
Abu Dhabi-based sovereign wealth funds finance optical ground station networks capturing geostationary and low-Earth orbit traffic. The country's telecommunications authority imposes frequency coordination requirements that filter market access. Dubai hosts hyperspectral imaging analytics clusters serving mining and agricultural monitoring contracts.
Brazil
Precision agriculture telemetry drives commercial demand across the Cerrado biome for crop yield optimization. ANVISA and national space regulators mandate local data processing for sensitive government contracts. São Paulo anchors domestic ground station partnerships licensing foreign technology to comply with procurement rules.
South Africa
Research institutions prioritize subscription models over grant-funded satellite asset acquisition. ISO satellite operations standards shape procurement specifications for university and government buyers. Cape Town clusters optical ground station calibration facilities serving Southern Hemisphere orbital coverage.
Saudi Arabia
Desert geography creates optimal atmospheric conditions for optical ground station siting with minimal cloud interference. The national telecommunications regulator coordinates spectrum allocation for satellite broadband serving remote populations. Riyadh concentrates sovereign cloud infrastructure deployments meeting data residency requirements.
Nigeria
Rural connectivity gaps attract satellite broadband procurement targeting unconnected agricultural and remote communities. The national communications commission manages orbital slot registration timelines affecting service activation. Lagos hosts ground segment partnerships bridging fiber backhaul gaps in distributed processing networks.
LAMEA Space As a Service Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and ground segment deployment. North American technology conglomerates leverage hyperscale platforms while Middle Eastern and Asian providers emphasize sovereign compliance. Three archetypes dominate: hyperscale cloud operators with orbital partnerships, launch services specialists with reusable vehicle architectures, and regional infrastructure integrators meeting data residency mandates. Capacity expansion through dedicated ground station networks and technology licensing to domestic partners represent the prevailing competitive vectors.
Within the hyperscale cloud tier, Microsoft exemplifies orbital-ground integration through Azure partnerships in South Africa and the UAE. SpaceX occupies a position as the launch services archetype with reusable vehicle cost structures undercutting legacy providers. Huawei Technologies anchors the regional infrastructure segment, embedding data center integrations that satisfy local residency mandates across Middle Eastern and African markets.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| IBM |
| Oracle |
| Huawei Technologies |
| SpaceX |
| Alibaba Cloud |
| SAP |
| Others |
Value Network & Pricing Analysis
ISO satellite operations standards gate qualified supply access and anchor premium-tier pricing for compliant ground station operators across South Africa and the UAE. Brazil's ANVISA data residency mandates further bifurcate the supplier base, forcing foreign operators into domestic partnerships that inflate service delivery costs while creating protected pricing tiers for certified local integrators.
Pricing Analysis
Warranty and uptime guarantee bundling separates premium ground station contracts from unbundled raw telemetry provisioning. The dominant structure stratifies across mission-critical infrastructure monitoring, standard agricultural analytics, and economy-tier connectivity leases. Price differentiation rests on ISO certification tier and guaranteed latency thresholds. Cost compression in the economy tier intensifies as SpaceX reusable launch economics cascade downstream. Government agencies in the UAE exhibit lowest price sensitivity due to sovereign wealth backing, while Nigerian rural connectivity projects face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with optical component suppliers concentrated in Germany, Japan, and the United States for precision ground station hardware. The supply chain draws from rare earth elements for phased array antennas, specialized fiber optics for backhaul, and radiation-hardened semiconductors for satellite payloads. Tariff exposure on Chinese-manufactured RF components creates procurement risk for Middle Eastern operators. Distribution runs through technology licensing arrangements where foreign vendors partner with domestic infrastructure holders to satisfy data residency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's updated national space policy functions as a cost-of-compliance moat, filtering market access to operators with domestic ground station partnerships and creating sustainable margin pools for certified integrators.
For Market Incumbents: Acquire optical ground station assets in desert geographies with favorable atmospheric conditions to lock in low-latency service differentiation. Consolidate phased array antenna maintenance capabilities through targeted hiring in South Africa to counter RF engineering talent scarcity. Deepen backward integration into hyperspectral sensor calibration to capture analytics margins currently flowing to third-party providers. For New Entrants and Emerging Players: Begin with subscription-based data services targeting South African research institutions transitioning from grant-funded asset ownership. Nigeria's rural connectivity gaps present the most penetrable geography for satellite broadband market entry. Pursue technology licensing to Brazilian domestic partners as the fastest path to government contract eligibility under local processing mandates. For Investors and Strategic Acquirers: UAE sovereign wealth deployment into optical ground station networks is the leading indicator that infrastructure-heavy segments will consolidate around state-backed capital pools. Target acquisition profiles should emphasize regional integrators with established data center partnerships and existing ANVISA or ISO compliance certifications. Monitor frequency coordination timeline announcements from Brazil's national space regulator as the signal for service activation velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing to Domestic Partners | Enables foreign operators to access Brazilian government contracts under ANVISA data residency mandates. |
| Optical Ground Station Network Expansion | Captures geostationary and low-Earth orbit traffic for UAE sovereign wealth-backed infrastructure projects. |
| AI-Driven Predictive Analytics Development | Commands premium subscription pricing from government agencies commissioning infrastructure monitoring forecasts. |
| RF Engineering Workforce Investment | Addresses specialized talent scarcity for phased array antenna maintenance across Middle Eastern markets. |
| Subscription Model Transition | Aligns with South African research institutions prioritizing operational expenditure over grant-funded asset acquisition. |
Research Methodology
Regulatory filings from Brazil's national space regulator, UAE telecommunications authority spectrum allocation records, and South African ISO certification databases formed the secondary backbone for market sizing. Primary interviews with ground station operators, satellite bandwidth procurement leads at agribusiness conglomerates, cloud infrastructure architects, and regulatory compliance officers validated demand assumptions. Bottom-up constellation deployment forecasts and top-down sovereign cloud spending estimates were triangulated against disclosed contract values.
Historical trendline analysis of launch services backlog and data services subscription growth informed the projection framework across the analysis window. Segmentation modeling incorporated service type, end user procurement authority, deployment architecture, and AI integration depth. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion timelines. Forecast inputs included hyperspectral sensor deployment schedules and fiber backhaul infrastructure buildout announcements.
Underlying measurement precision varies by segment; Launch Services carry tighter precision due to disclosed backlog visibility while Data Services projections reflect greater uncertainty around AI adoption velocity. Forecasts embed assumptions regarding frequency coordination timeline stability and cross-border spectrum harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Designing Market
Space
Space-Based Solar Power Market
Space
Space As a Service Market
Space
Space Debris Monitoring and Removal Market
Space
Rocket Launchpad Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
China Space Electronics Market
Space
Space Lander and Rover Market
Space
Space Frame Market
Space
North America Spacesuit Market
Space
Orbital Spaceflight Market
Space
Space Mobile Service Market
Space
UK Space Propulsion System Market
Space
Africa Space Electronics Market
Space
Space Rover Market
Space
Europe Space Logistics Market