
 Space Transportation Market | 2026-2036
Space Transportation Market Size, Share, and Industry Trends Forecast 2026-2036
Space Transportation Market Analysis
Modular payload adapter configurations and rideshare bundling is expanding buyer choice in the Space Transportation Market. SpaceX leverages its Falcon 9 rideshare program to dominate small-satellite access. United Launch Alliance anchors national security missions through vertical integration into solid rocket motor production. Blue Origin competes via heavy-lift specialization and in-house engine manufacturing.
Space transportation encompasses the systems, vehicles, and infrastructure required to move payloads and crew from Earth's surface into orbit or beyond, utilizing propulsion technologies generating thrust-to-weight ratios exceeding one and thermal protection systems rated for atmospheric reentry velocities above Mach 25. Its primary purpose is to enable orbital insertion for satellites, resupply of space stations, and eventual crewed interplanetary transit. Reusable rockets within the vehicle type category now capture the dominant share of commercial launch contracts due to amortized per-flight economics. Satellite deployment services lead the service type segment, though space tourism exhibits the fastest trajectory as suborbital platforms achieve operational cadence. Liquid propulsion systems anchor the technology segment through restartable engines enabling precision orbital insertion.
FAA launch licensing governs commercial orbital and suborbital operations from US territory, while FCC spectrum and debris-mitigation rules shape constellation business models and launch demand volumes. NASA's Human Rating Requirements and the Artemis Accords framework influence international partnership structures and technology transfer boundaries. Stakeholders must monitor how ITAR export controls and emerging national space traffic management regimes reshape supplier eligibility and launch site access conditions.
Market Dynamics
Reusable rocket architectures are compressing launch economics and redistributing contract volumes toward providers with proven flight-proven hardware, forcing expendable launch vehicle operators into niche payload segments or exit.
Growth Catalysts
- FCC Spectrum Licensing:The FCC's streamlined broadband constellation approvals are generating sustained launch demand from commercial operators seeking orbital slots for LEO networks.
- Artemis Accords Framework:This multilateral agreement is expanding international partnership structures and creating technology transfer pathways for lunar infrastructure missions.
- Small-Satellite Rideshare:Dedicated smallsat launchers and secondary payload adapters are democratizing orbital access for university and commercial CubeSat developers.
Market Restraints
- Propellant Supply Concentration:Liquid oxygen and RP-1 refining capacity concentrates in Gulf Coast petrochemical corridors, exposing launch schedules to regional weather and refining disruptions.
- Launch Site Bottlenecks:Eastern Range and Western Range capacity constraints at Cape Canaveral and Vandenberg limit achievable launch cadence regardless of vehicle availability.
- Human-Rating Certification Burden:NASA's Human Rating Requirements impose extensive design verification and fault-tolerance mandates that extend development timelines for crew-capable vehicles.
Strategic Opportunities
- In-Space Servicing:Orbital refueling and satellite life-extension missions represent an emerging service category with limited incumbent competition.
- Suborbital Point-to-Point:Hypersonic cargo delivery concepts are attracting defense procurement interest for time-critical logistics applications.
- India's Space Reforms:ISRO's commercialization of launch facilities and private participation frameworks are opening previously restricted launch capacity to international payloads.
Industry Challenges
- Workforce Pipeline Gaps:Aerospace engineering programs are producing insufficient propulsion and thermal protection specialists relative to vehicle development programs.
- Debris Mitigation Compliance:FCC and international guidelines for post-mission disposal and collision avoidance are adding operational complexity and fuel margin requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Transportation Market |
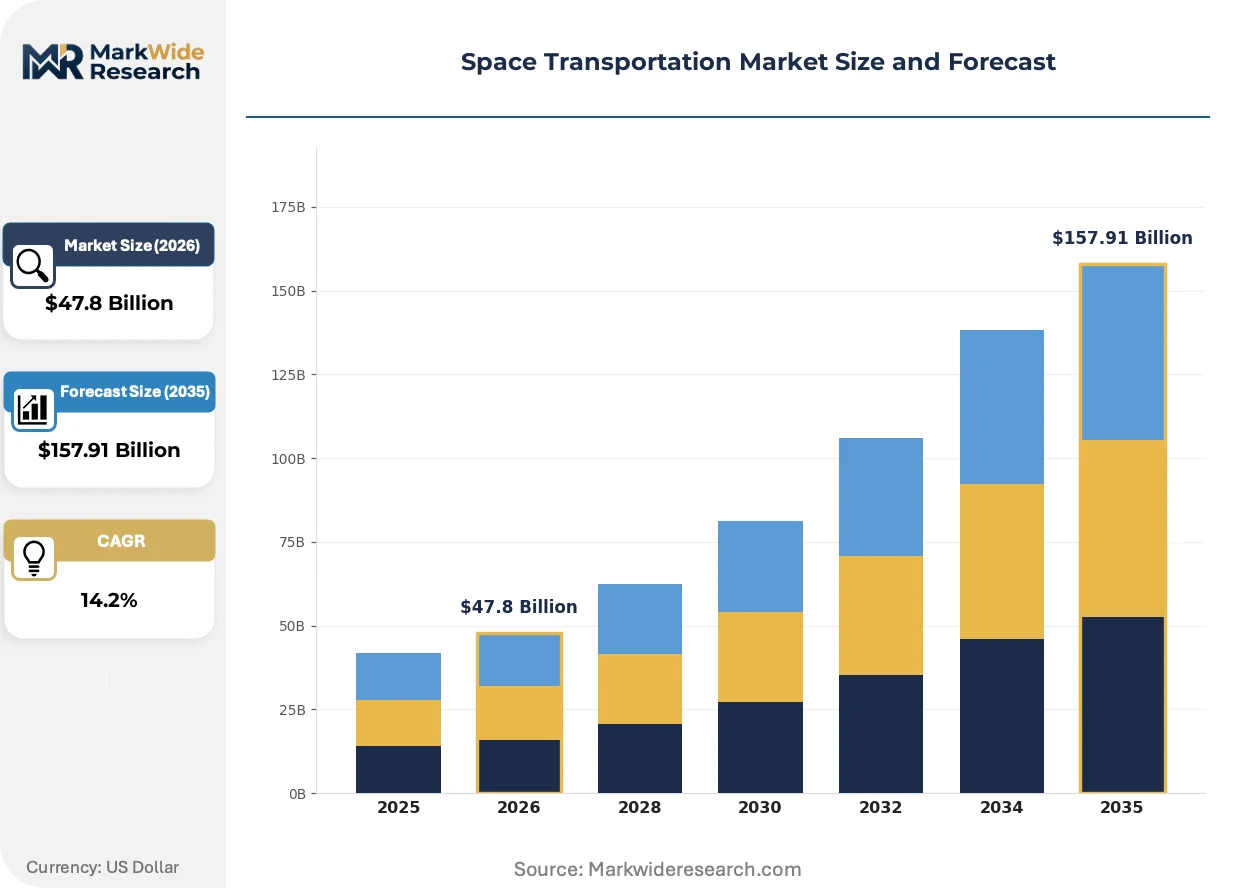
| Market Size in 2026 | $47.8 Billion |
| Market Size in 2035 | $157.91 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Launch Vehicle, Space Shuttle, Reusable Rocket, Spaceplane Service Type: Satellite Deployment, Cargo Transport, Human Spaceflight, Space Tourism Technology: Liquid Propulsion, Solid Propulsion, Hybrid Propulsion, Ion Propulsion End User: Government Agencies, Commercial Providers, Research Institutions, Space Startups |
| Companies Covered | Northrop Grumman Innovation Systems, Impulse Space, SpaceX, Firefly Aerospace, Stoke Space, Blue Origin, Axiom Space, Sierra Space, United Launch Alliance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Transportation Market Emerging Trajectories
Propulsion architecture convergence and regulatory clarity around orbital traffic management are reshaping how launch services are packaged, priced, and integrated into satellite operator business models.
Additive manufacturing is unifying engine component production by consolidating dozens of traditionally machined parts into single printed assemblies. Propulsion teams at emerging launch ventures are adopting this approach to compress development cycles and reduce part count. The structural consequence is collapsing supplier networks and shifting value capture toward in-house metallurgy capabilities.
FAA launch licensing reforms are streamlining commercial orbital and suborbital approval pathways through consolidated safety reviews and experimental permit frameworks. This regulatory evolution reduces pre-flight documentation burdens for reusable vehicle operators. Small-satellite launch providers with high flight cadence are the primary beneficiaries, adapting their operations to leverage faster turnaround between missions.
Fixed-price launch contracting is displacing cost-plus reimbursement structures that historically dominated government procurement. Defense and intelligence agencies are now accepting milestone-based payment terms previously restricted to commercial satellite operators. This behavioral shift is most pronounced in United States national security missions, where the Space Development Agency and Space Force are driving terms toward commercial-style risk allocation.
Space Transportation Market Segmentation
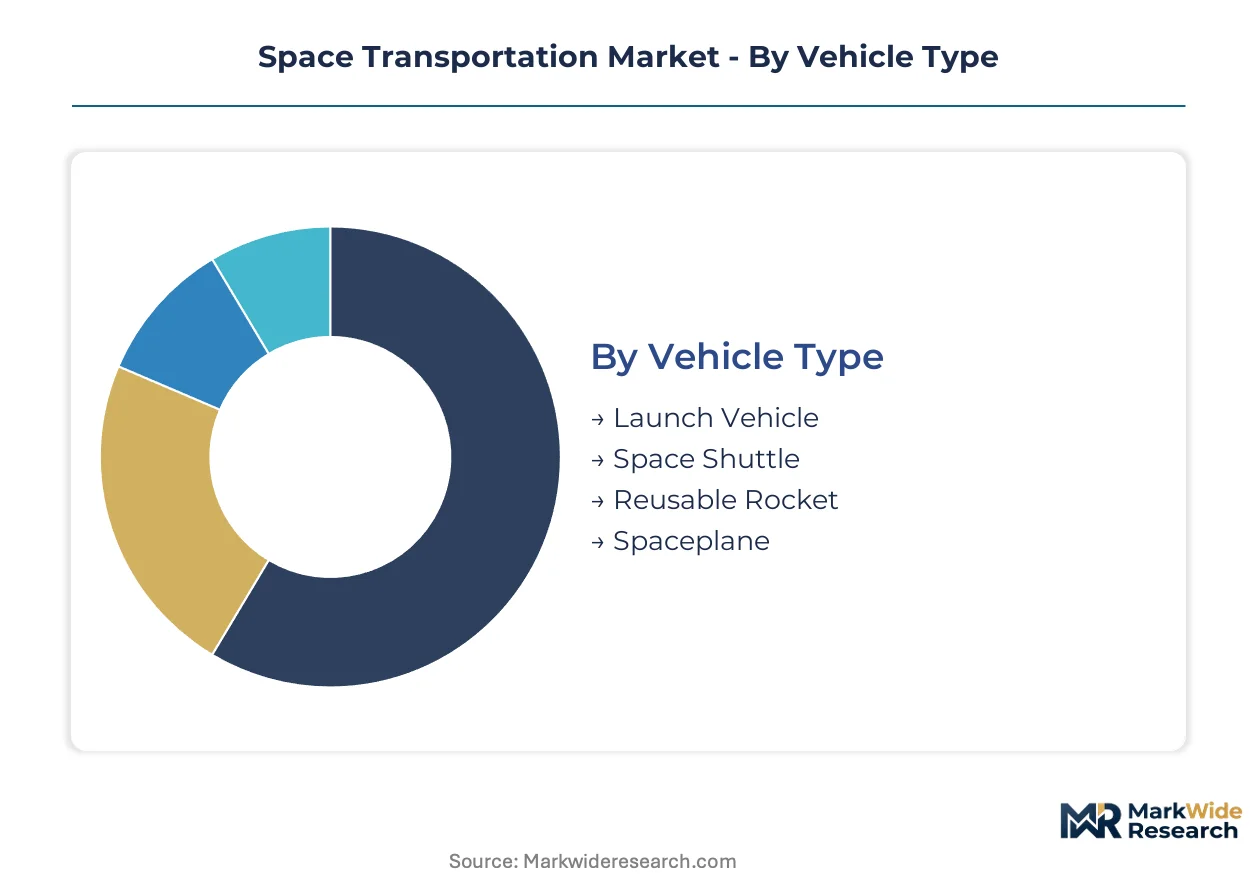
Segmentation in space transportation reveals how regulatory requirements, technical specifications, and procurement patterns fragment contract volumes across vehicle architectures and service categories. Each segment carries distinct certification burdens that shape supplier eligibility and customer access.
Vehicle Type:
FAA launch licensing applies orbital and suborbital categories differently, with expendable vehicles facing lighter operational oversight than reusable systems requiring extensive flight-history documentation.
- Reusable Rocket:These systems utilize flyback boosters and powered landing architectures to achieve multiple flight cycles per vehicle. NASA's Human Rating Requirements and FAA reentry permits dominate certification pathways for crew-capable variants. Demand concentrates in the United States through SpaceX Falcon 9 and Blue Origin New Glenn programs, driven by amortized per-flight economics and constellation deployment schedules.
- Launch Vehicle:Expendable multi-stage rockets with jettisoned boosters and core stages remain essential for heavy national security payloads and interplanetary missions. ITAR export controls constrain international sales of vehicles with solid motor heritage. Government Agencies in the United States anchor procurement through NRO and Space Force contracts, though unit economics face pressure from reusable competition.
- Space Shuttle:Retired NASA fleet exemplifies winged orbital vehicle architecture with crew and cargo dual capability. No operational vehicles exist; segment relevance lies in heritage technology transfer to commercial spaceplane developers.
- Spaceplane:Horizontal takeoff and landing systems with runway compatibility for rapid turnaround. Virgin Galactic and Sierra Space pursue FAA commercial spaceflight licenses for suborbital tourism and point-to-point cargo concepts.
Leading the category by volume: Reusable Rocket. Expanding most quickly: Spaceplane.
Service Type:
Service differentiation tracks payload mass, orbital destination, and crew safety requirements, with pricing tiers reflecting insurance and liability structures.
- Satellite Deployment:Orbital insertion services for communications, Earth observation, and navigation constellations. FCC spectrum licensing timelines drive launch scheduling for LEO broadband operators. Commercial Providers in the United States generate sustained demand through Starlink and Amazon Kuiper deployment campaigns.
- Human Spaceflight:Crew transport to ISS, lunar orbit, and eventual surface missions. NASA's Human Rating Requirements mandate fault-tolerant avionics and abort systems. Government Agencies dominate procurement through Artemis program contracts, with Boeing Starliner and SpaceX Dragon competing for operational slots.
- Cargo Transport:Pressurized and unpressurized logistics to orbital platforms. ISS resupply contracts anchor demand through NASA Commercial Resupply Services agreements.
- Space Tourism:Suborbital and orbital passenger experiences. FAA commercial spaceflight participant regulations govern informed consent frameworks. Blue Origin and Virgin Galactic compete for high-net-worth individual bookings.
Climbing the fastest: Space Tourism. Dominating contract value: Satellite Deployment.
Technology:
Propulsion selection determines restart capability, thrust vectoring precision, and supply chain exposure to propellant refining concentration.
- Liquid Propulsion:Cryogenic and storable liquid engines enable throttle control and multiple ignition cycles for precision orbital insertion. RP-1 and liquid oxygen supply concentrates in Gulf Coast refining corridors, exposing schedules to regional weather disruptions. SpaceX Merlin and Blue Origin BE-4 engines anchor commercial and national security missions.
- Solid Propulsion:Cast composite motors with pre-loaded propellant grains deliver high thrust-to-weight ratios for initial ascent stages. United Launch Alliance maintains captive supply through in-house motor production for Atlas V and Vulcan vehicles.
- Hybrid Propulsion:Combined liquid oxidizer and solid fuel systems offering throttle modulation with simplified fuel handling. Virgin Galactic SpaceShipTwo utilizes hybrid motors for suborbital tourist flights.
- Ion Propulsion:Electric thrusters with xenon or krypton propellant for high-efficiency orbital transfer and station-keeping. NASA and ESA science missions deploy ion systems for deep-space trajectory optimization.
Highest flight rate: Liquid Propulsion. Steepest R&D investment trajectory: Ion Propulsion.
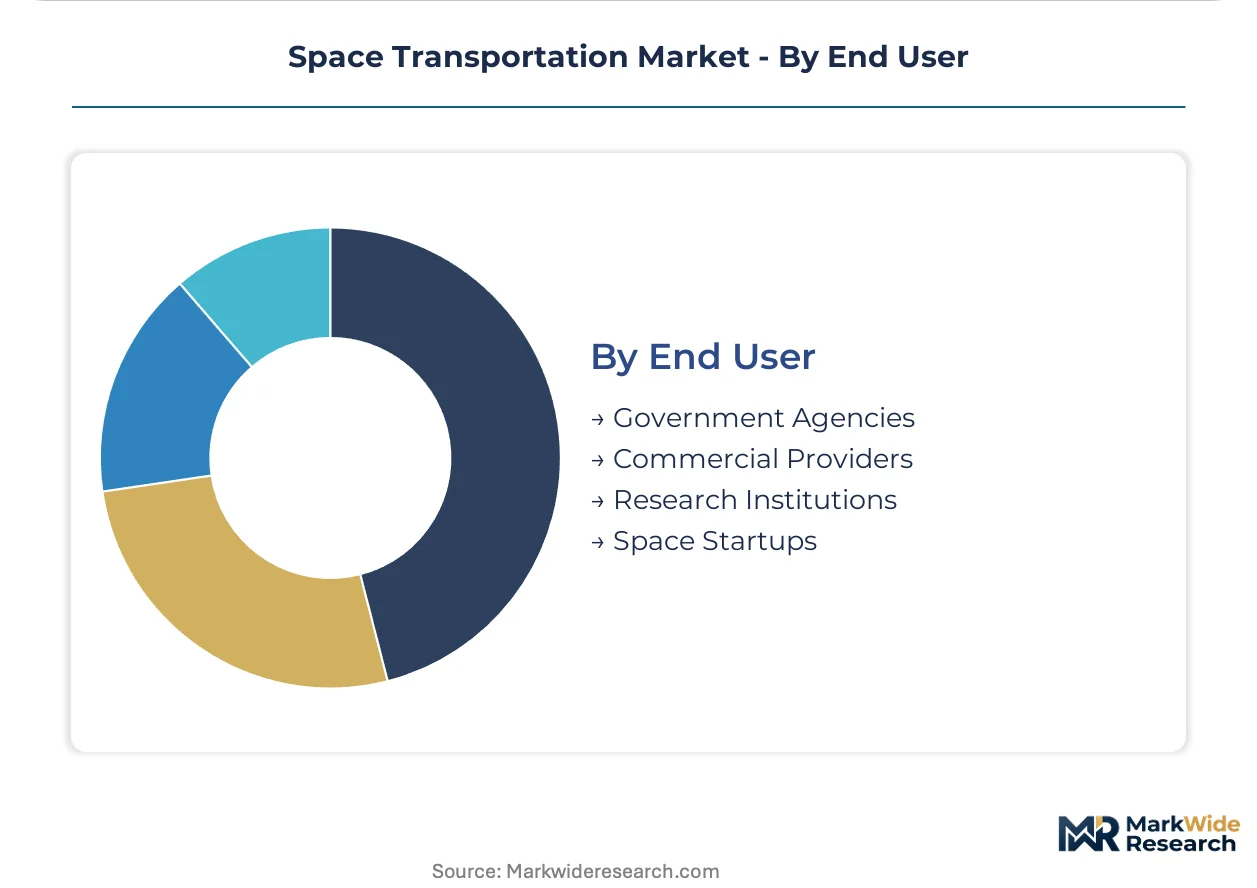
End User:
Customer type determines contract structure, with government procurement favoring cost-plus terms shifting toward fixed-price milestones.
- Government Agencies:NASA, DoD, and intelligence community missions requiring assured access to space with mission assurance protocols. National security launches mandate domestic launch site utilization and supply chain provenance verification.
- Commercial Providers:Constellation operators and satellite service companies procuring launch capacity through multi-manifest agreements. FCC licensing compliance shapes fleet deployment timelines and launch demand profiles.
- Research Institutions:University and laboratory payloads accessing orbit through rideshare adapters and dedicated smallsat launchers. NASA CubeSat Launch Initiative provides subsidized access for educational missions.
- Space Startups:Emerging ventures with venture-funded vehicle development programs. FAA experimental permits and commercial space transportation licenses enable suborbital test campaigns prior to orbital certification.
Contract volume leader: Government Agencies. Gaining share fastest: Space Startups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Launch production concentrates in coastal corridors with established propellant refining and range infrastructure, while satellite operator demand disperses across jurisdictions with spectrum licensing regimes. This geographic split shapes procurement patterns and regulatory compliance burdens.
United States
NASA procurement and FCC broadband constellation licensing drive sustained launch demand from Cape Canaveral and Vandenberg. FAA commercial space transportation regulations govern launch licensing and reentry permits for reusable systems. The Gulf Coast petrochemical corridor anchors liquid oxygen and RP-1 refining capacity, exposing schedules to regional weather disruptions.
China
State-owned constellation deployment and lunar infrastructure programs generate captive demand for Long March vehicle families. MIIT satellite licensing and national space traffic management frameworks shape operator compliance requirements. The Wenchang Satellite Launch Center on Hainan Island supports heavy-lift missions with equatorial launch advantages.
France
Arianespace commercial launch services and ESA science missions sustain demand through Guiana Space Centre access. EU space surveillance and tracking regulations influence debris mitigation compliance for constellation operators. The Paris-Saclay cluster hosts satellite manufacturers and ground segment providers integrated with launch procurement.
India
ISRO commercialization reforms and private launch participation frameworks are opening previously restricted capacity to international payloads. Department of Space guidelines and Antrix Corporation commercial arrangements govern foreign satellite access. The Sriharikota launch range and emerging private spaceports in Gujarat concentrate vehicle development activity.
United Arab Emirates
Mohammed bin Rashid Space Centre lunar exploration initiatives and commercial satellite procurement generate emerging launch demand. UAE Space Agency licensing frameworks and international partnership structures shape technology transfer boundaries. Dubai's space services corridor aggregates ground operations and mission control capabilities for regional operators.
Space Transportation Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across vehicle development, launch operations, and in-space services. The market exhibits tiered consolidation with a dominant reusable launch provider, several mid-scale national security contractors, and numerous emerging ventures seeking dedicated small-satellite niches. Strategic archetypes include vertically integrated engine manufacturers, rideshare platform operators, and specialized human-rating certification holders. Competitive moves center on fixed-price contract terms displacement and captive propulsion supply chain construction.
Within the established launch tier, SpaceX exemplifies reusable platform economics through Falcon 9 cadence and rideshare program scale. Blue Origin occupies a position in heavy-lift specialization with in-house engine manufacturing capabilities. United Launch Alliance anchors national security mission assurance through solid rocket motor supply chain control. These three entities represent distinct strategic postures: rapid reusability, vertical engine integration, and mission assurance heritage.
| Leading Market Players |
|---|
| Northrop Grumman Innovation Systems |
| Impulse Space |
| SpaceX |
| Firefly Aerospace |
| Stoke Space |
| Blue Origin |
| Axiom Space |
| Sierra Space |
| United Launch Alliance |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing adoption in propulsion component production is collapsing traditional supplier networks while compressing development timelines, simultaneously shifting value capture toward in-house metallurgy capabilities and concentrating cost leverage among vertically integrated engine manufacturers. This technical transition feeds directly into pricing power redistribution across the launch services tier.
Pricing Analysis
Cost-down pressure on dedicated small-satellite launches accelerates as rideshare bundling and secondary payload adapters proliferate, forcing single-manifest providers toward premium pricing for rapid-response or custom orbital insertion missions. Three-tier pricing structure across premium assured-access, standard rideshare, and economy slot-reservation levels separates NASA Human Rating certification holders from commercial cargo operators and experimental permit holders. FCC spectrum licensing timelines amplify buyer price sensitivity among LEO constellation developers facing orbital slot expiration risks, while national security missions exhibit lowest sensitivity due to mission assurance requirements.
Supply Chain Analysis
ITAR qualification requirements and NASA Human Rating certification gates restrict engine component sourcing to domestic or treaty-allied suppliers, fragmenting international procurement options for crew-capable vehicles. Liquid oxygen and RP-1 refining capacity concentrates in United States Gulf Coast corridors, with solid motor propellant casting anchored in Utah and Alabama production facilities. Single-source vulnerability persists in domestic titanium forging and superalloy powder metallurgy for turbine components. Distribution runs through captive vertical integration at major launch providers rather than merchant supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Eastern Range and Western Range capacity constraints at Cape Canaveral and Vandenberg prop sustained pricing premiums for available launch slots, creating a supply-constrained market structure favoring incumbent cadence advantages.
For Market Incumbents: Deepen captive propellant supply arrangements through backward integration into Gulf Coast LOX production or long-term offtake agreements with regional refiners, insulating launch schedules from weather-driven supply disruptions. Fortify human-rating certification moats against emerging reusable vehicle entrants by accelerating fault-tolerance demonstration campaigns under NASA oversight. For New Entrants and Emerging Players: University and research institution payload aggregators represent the most penetrable channel partner type for dedicated small-satellite launchers seeking initial flight heritage, with NASA CubeSat Launch Initiative providing subsidized access pathways. Target India's emerging private launch facilities through ISRO commercialization frameworks as a regulatory-favorable geography for international payload accumulation. Position around rapid-response dedicated launch as the differentiated go-to-market angle against rideshare commoditization. For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor acquisition of propulsion technology specialists, with strategic buyers seeking in-house engine manufacturing capabilities to reduce reliance on merchant suppliers. Long-term viability hinges on demonstration of reusable flight cadence meeting constellation deployment timelines. Watch FAA launch licensing reform implementation velocity as the inflection signal indicating regulatory barrier reduction for new vehicle certification.| Strategic Initiative | Industry Significance |
|---|---|
| Reusable Flight Cadence Expansion | SpaceX Falcon 9 amortization economics force expendable vehicle operators into niche payload segments or exit. |
| In-House Engine Manufacturing | Blue Origin BE-4 and SpaceX Merlin production insulates against RP-1 supply concentration in Gulf Coast corridors. |
| Small-Satellite Rideshare Platform | Secondary payload adapters democratize orbital access for university CubeSat developers and commercial constellation operators. |
| FAA Launch Licensing Streamlining | Consolidated safety reviews reduce pre-flight documentation burdens for reusable vehicle operators with high flight cadence. |
| Human-Rating Certification Investment | NASA fault-tolerance mandates extend development timelines but create procurement preference for crew transport missions. |
Methodological Framework
Document review covered FAA launch licensing databases, FCC spectrum allocation records, NASA procurement disclosures, and ESA member state space budgets, complemented by interviews with launch vehicle program managers, propulsion engineering directors, constellation operator procurement leads, and commercial spaceport operations executives. Secondary validation drew from trade association filings, customs propellant import records, and defense agency budget justifications. Bottom-up segment sizing triangulated against top-down market aggregation.
Cross-referencing historical launch manifest data against industry panel input informed the analytical framework across vehicle type, service category, propulsion technology, and end-user segmentation dimensions. CAGRs were derived from trajectory fitting to disclosed contract values and announced constellation deployment schedules. Industry-specific forecast inputs included FCC broadband licensing pipeline volumes and Artemis program milestone commitments.
Caveats apply where Eastern Range capacity expansion delays, propellant refining disruptions, or ITAR regulatory tightening could materially shift the outlook for launch availability and provider economics. A model refresh is warranted upon material change in FAA commercial space transportation licensing velocity or NASA Human Rating Requirements revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Debris Monitoring and Removal Market
Space
Mexico Space Electronics Market
Space
Space Burial Service Market
Space
Space Robots Market
Space
Space Colonization Market
Space
Space As a Service Market
Space
Space Robotics Market
Space
South Korea Space Electronics Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space-Based Smart Sensors Market
Space
UK Space Electronics Market
Space
Space Tourism Market
Space
Space in Orbit Refueling Market
Space
Space Travel Market
Space
Space Oscillator Market
Space
Space Designing Market