
 Drone Docking Station Market | 2026-2036
Drone Docking Station Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Docking Station Market Analysis
Market Context
IP-rated outdoor docking enclosures is rotating toward higher ingress-protection tiers as enterprise buyers specify NEMA 4X and IP67 ratings for year-round deployment. DJI leverages its manufacturing scale to dominate consumer-adjacent enterprise tiers while extending into ruggedized dock hardware. Skydio competes through its autonomous flight stack, which anchors premium positioning in defense and public safety channels. Hextronics specializes in modular, payload-agnostic docking architectures that differentiate its offering for third-party drone integrators.
Technical Definition and Segment Structure
A drone docking station is a fixed or mobile ground infrastructure unit that provides automated landing alignment, battery charging or swapping, data offload, and shelter for unmanned aerial vehicles, typically incorporating precision positioning within 2-centimeter accuracy and environmental sealing against dust and moisture ingress. The product type dimension shows automated docks capturing the fastest expansion as end-users eliminate manual retrieval labor, while fixed docks remain the mature volume base in perimeter security applications. Vision-based technology leads GPS-based alternatives in urban canyon environments where satellite signal degradation occurs, and the inspection application category sustains the deepest margin pools due to recurring utility contracts and regulatory-mandated infrastructure assessment cycles.
Regulatory Framework and Outlook
FAA Part 107 and emerging BVLOS frameworks in the United States, EASA drone regulation amendments across Europe, and CAAC unmanned aerial system certification pathways in China collectively shape product certification requirements and operational radius permissions for docking station deployments. The EU AI Act and GDPR impose additional algorithmic transparency and data residency constraints on vision-based landing systems processing biometric or surveillance footage. Stakeholders must monitor which regulatory jurisdictions first standardize fully unattended docking operations, as these markets will concentrate procurement authority and set de facto technical specifications for export-oriented manufacturers.
Market Dynamics
FAA BVLOS rulemaking and EASA drone regulation amendments are compressing operational permission timelines, forcing docking station architectures toward fully unattended designs that eliminate on-site human oversight requirements.
Growth Catalysts
- Transmission line inspection mandates:Energy utilities across the United States face FERC-mandated reliability assessments that favor autonomous drone fleets with automated battery swapping. This creates procurement pull for IP67-rated outdoor docking enclosures.
- Vision-based landing systems:Urban canyon environments with GPS signal degradation accelerate adoption of computer-vision alignment technologies that achieve 2-centimeter landing precision without satellite dependency.
- China infrastructure digitization:CAAC unmanned aerial system certification pathways enable scaled deployment of inspection drones along power corridors and rail networks, concentrating demand in Guangdong and Jiangsu provinces.
Market Restraints
- Lithium battery supply concentration:Cell production for hot-swappable docking modules concentrates in Chinese manufacturing zones, exposing procurement to export control volatility and freight cost spikes.
- Precision positioning hardware costs:RTK-GNSS modules and machine-vision sensors required for centimeter-grade landing accuracy comprise 35-45% of bill-of-materials costs, compressing margin at volume price points.
- EU AI Act algorithmic transparency:Vision-based landing systems processing surveillance footage must document training data provenance and decision logic, extending certification timelines for European deployments.
Strategic Opportunities
- German industrial corridor automation:Manufacturing clusters in Bavaria and Baden-Württemberg seek perimeter security drones with automated docking, creating white space for payload-agnostic station architectures.
- 5G network slicing convergence:Ultra-reliable low-latency communication (URLLC) slices enable real-time telemetry for remote docking operations, opening rural inspection markets previously unreachable via conventional connectivity.
- India PLI scheme localization:Production-linked incentives for electronics manufacturing attract docking station assembly capacity, positioning the country as an export hub for Southeast Asian utility markets.
Industry Challenges
- Systems integration complexity:Docking stations must interface with legacy utility SCADA networks and proprietary fleet management software, requiring custom middleware development that extends deployment timelines.
- IP67 certification bottlenecks:Third-party testing capacity for ingress protection validation is backlogged 8-12 months at accredited laboratories, delaying product launches regardless of engineering readiness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Docking Station Market |
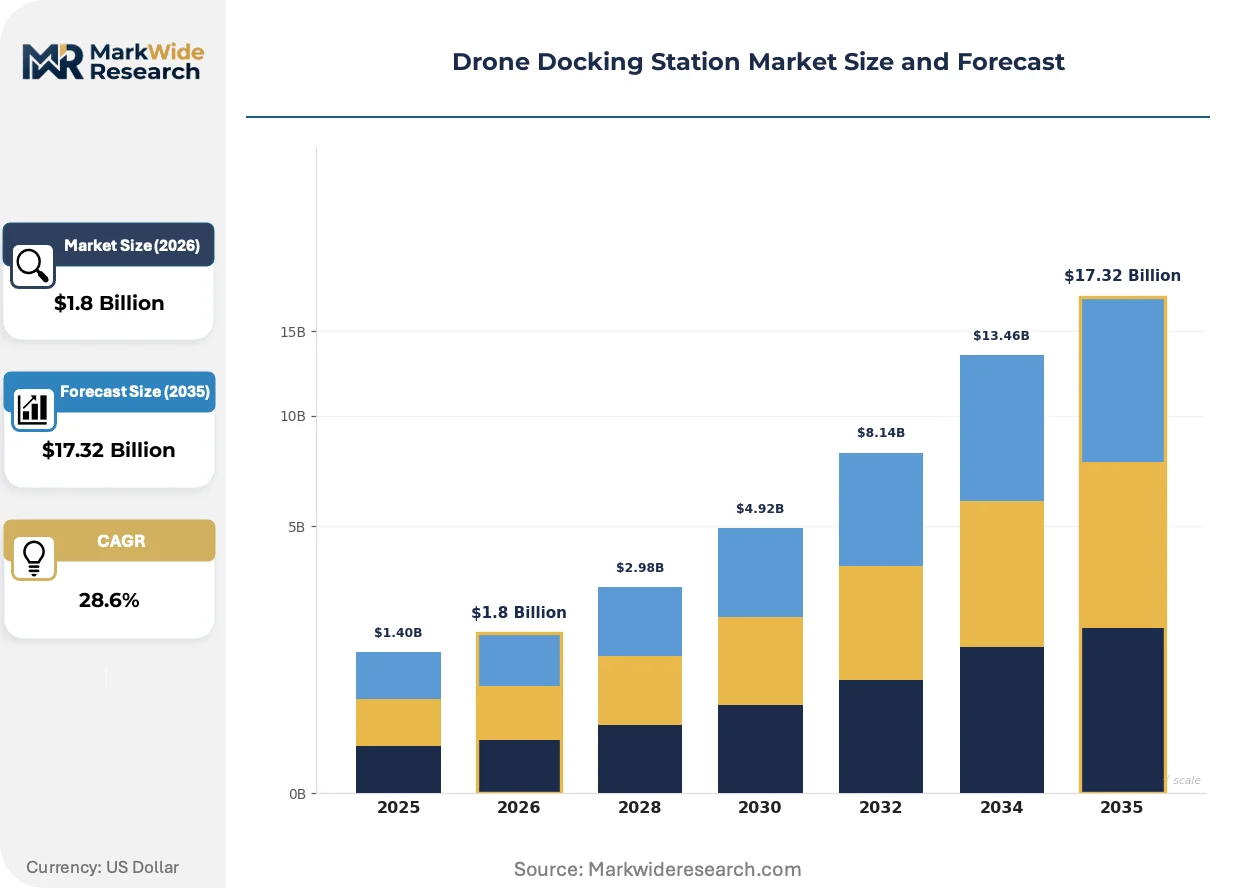
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Dock, Mobile Dock, Automated Dock, Charging Dock End User: Aerospace, Agriculture, Infrastructure, Surveillance Technology: GPS-Based, Vision-Based, Electromagnetic, Hybrid Application: Delivery, Monitoring, Inspection, Emergency Response |
| Companies Covered | Freefly Systems, Parrot, DJI, Delair, Autel Robotics, Hextronics, Skydio, Insitu, Azur Drones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Docking Station Market Emerging Trajectories
Docking station architectures are pivoting from manual-retrieval accessories to autonomous infrastructure nodes. Three concurrent developments—hardware specialization, regulatory permission expansion, and procurement model transformation—are restructuring competitive requirements.
Vision-based precision landing is bifurcating docking station design philosophy. GPS-denied alignment systems using stereo cameras and LiDAR are displacing RTK-GNSS dependency in urban deployments. Security and defense buyers in Germany and the United States specify these configurations for contested electromagnetic environments. The technology is compressing addressable market differentiation between premium autonomous docks and basic fixed installations.
EASA drone regulation amendments and FAA BVLOS frameworks are synchronizing operational permission standards across Atlantic markets. Both jurisdictions now permit fully unattended docking without visual observers for predefined corridor inspections. European energy utilities are responding fastest, rewriting procurement specifications to mandate BVLOS-ready station architectures that lock out legacy manual-retrieval systems.
Utility procurement departments are unbundling hardware acquisition from fleet management subscriptions. Buyers in the United States and China now favor capital-light leasing structures where docking station vendors retain ownership and charge per-flight fees. This compresses upfront procurement cycles from 18-month capital appropriations to 90-day operational expenditure approvals, favoring vendors with balance-sheet capacity to carry deployed assets.
Drone Docking Station Market Segmentation
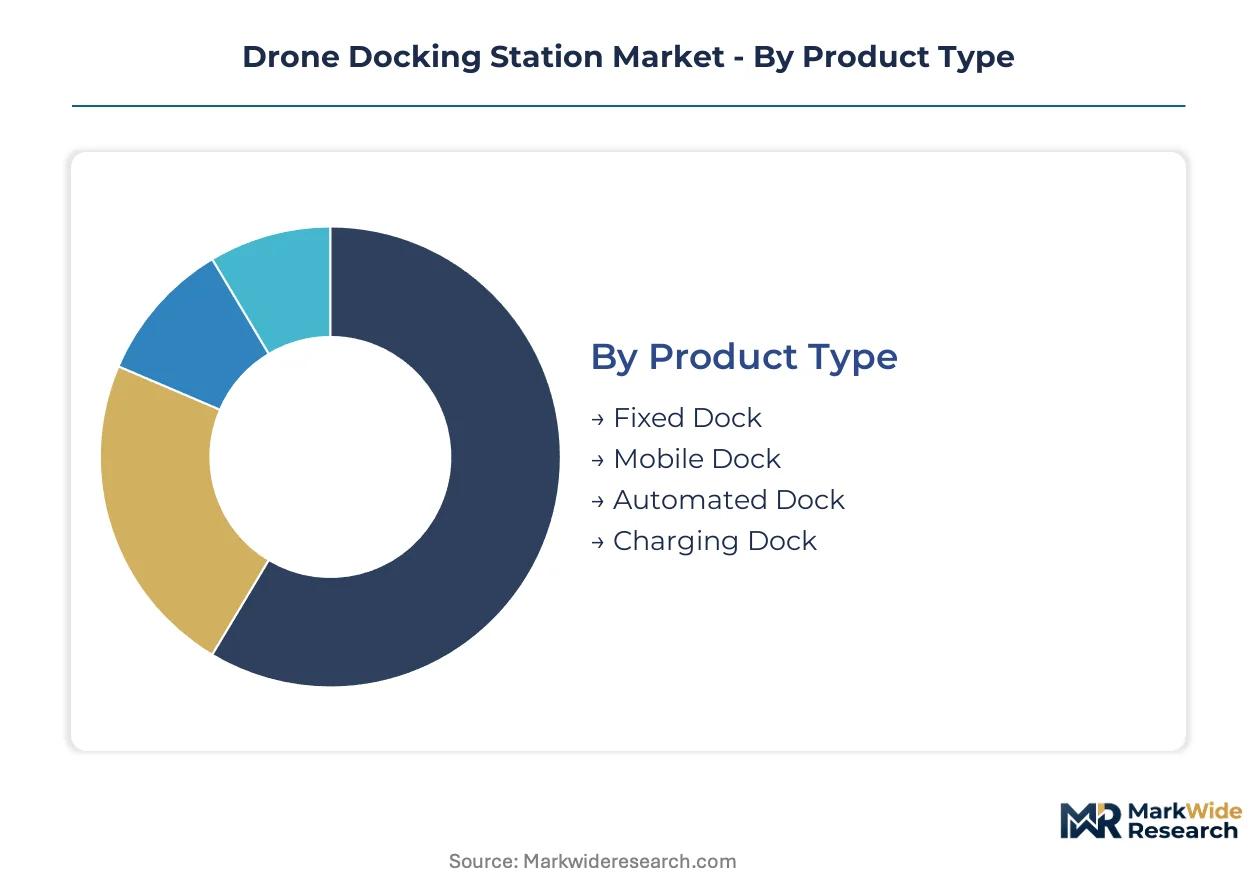
Segmentation in drone docking stations reveals how procurement authority distributes across operational models and technical specifications. Buyers prioritize architectures that eliminate manual intervention while satisfying regulatory mandates for unattended flight operations.
Product Type:
Margin pools concentrate in architectures that remove human retrieval from operational workflows, with premium pricing attached to environmental sealing and precision alignment systems.
- Fixed Dock:Permanent installations anchor perimeter security deployments at industrial facilities and critical infrastructure sites. Demand concentrates in Germany and the United States where manufacturing clusters and energy utilities require 24/7 autonomous coverage without on-site personnel.
- Automated Dock:Self-contained units execute battery swapping and data offload without operator presence, incorporating IP67-rated enclosures and centimeter-grade landing precision. Procurement from United States energy utilities is accelerating under FERC-mandated transmission line inspection programs that specify fully unattended operation.
- Mobile Dock:Transportable platforms serve temporary deployment scenarios including emergency response staging and construction site monitoring.
- Charging Dock:Basic conductive charging stations support consumer-adjacent enterprise tiers with lower ingress protection requirements.
Fixed Dock holds installed capacity. Automated Dock is rotating up the share rankings.
End User:
Volume distribution follows regulatory-mandated inspection cycles rather than discretionary technology adoption, concentrating procurement in sectors with compliance-driven replacement schedules.
- Infrastructure:Power transmission operators and rail networks deploy docking stations along corridor routes for continuous structural assessment. Procurement in China concentrates in Guangdong and Jiangsu provinces under CAAC certification pathways that enable scaled unmanned aerial system deployment.
- Surveillance:Defense and public safety agencies specify vision-based landing systems for contested electromagnetic environments. German security buyers drive premium positioning through requirements for GPS-denied operation in urban canyon and electronic warfare scenarios.
- Aerospace:MRO facilities and airfield operators utilize docking for fleet logistics and runway inspection.
- Agriculture:Large-scale farming operations deploy seasonal monitoring with lower durability requirements than industrial counterparts.
Infrastructure commands procurement volume. Surveillance is climbing the fastest on margin contribution.
Technology:
Cost tier stratification separates satellite-dependent systems from sensor-fusion architectures, with urban deployment constraints pushing adoption toward higher-complexity alignment methods.
- Vision-Based:Stereo camera and LiDAR configurations achieve 2-centimeter landing precision without GNSS signal dependency. Demand concentrates in United States urban deployments where FAA BVLOS frameworks now permit fully unattended corridor inspection without visual observers.
- GPS-Based:RTK-GNSS modules provide cost-effective alignment in rural and suburban environments with unobstructed satellite visibility. Procurement favors this tier for agricultural and perimeter security applications across the United States and Germany where electromagnetic interference is minimal.
- Electromagnetic:Inductive positioning systems serve specialized defense applications requiring emission-controlled landing.
- Hybrid:Sensor-fusion architectures combine multiple alignment modalities for fail-safe operation in variable conditions.
GPS-Based retains volume leadership. Vision-Based is gaining share fastest as urban deployment expands.
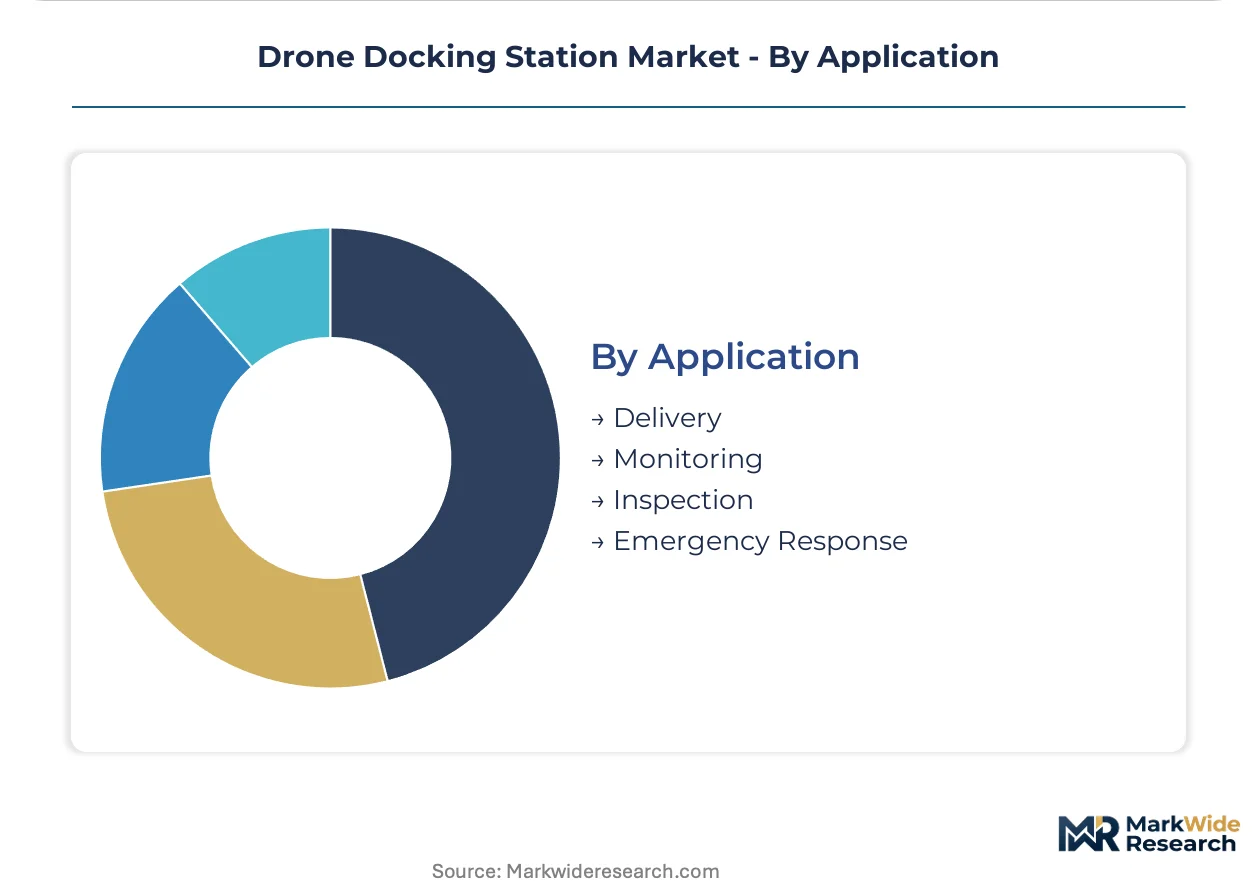
Application:
Recurring revenue potential distinguishes inspection workflows from episodic deployment models, with utility contracts sustaining multi-year docking station leases.
- Inspection:Transmission line, pipeline, and structural assessment programs generate recurring flight demand with predefined route libraries. United States energy utilities favor per-flight leasing structures that compress procurement cycles from capital appropriations to operational expenditure approvals.
- Monitoring:Continuous perimeter surveillance and environmental sensing require persistent docking availability with rapid launch readiness. Chinese infrastructure digitization programs concentrate deployment along power corridors and rail networks in provincial manufacturing zones.
- Delivery:Last-mile logistics pilots drive mobile dock experimentation with shorter equipment amortization periods.
- Emergency Response:Disaster relief and search operations utilize temporary docking installations with rapid redeployment requirements.
Inspection anchors recurring revenue. Monitoring is expanding most quickly on deployment scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement markets. United States utilities prioritize BVLOS-ready architectures regardless of cost, while agricultural buyers in Brazil and Southeast Asia favor basic charging docks with minimal environmental sealing.
United States
FERC-mandated transmission line inspections and FAA BVLOS rulemaking drive demand for fully unattended docking stations. The FAA Part 107 waiver pathway accelerates deployment permissions for automated battery swapping systems. Procurement concentrates in Texas and California utility corridors where energy operators lease docking infrastructure under per-flight models.
Germany
Industrial perimeter security requirements and defense sector specifications anchor demand for GPS-denied vision-based landing systems. EASA drone regulation amendments and the EU AI Act impose algorithmic transparency requirements on surveillance-processing docks. Bavaria and Baden-Württemberg manufacturing clusters deploy payload-agnostic stations for 24/7 facility monitoring.
China
CAAC unmanned aerial system certification enables scaled deployment along power transmission and rail networks. Infrastructure digitization programs concentrate procurement in Guangdong and Jiangsu provinces. Domestic cell production for hot-swappable modules supports cost-competitive automated dock manufacturing for utility corridor applications.
India
Production-linked incentive schemes for electronics manufacturing attract docking station assembly capacity targeting Southeast Asian export markets. Central Electricity Authority guidelines promote drone-based transmission line assessment. Telangana and Karnataka emerging as assembly hubs for utility-grade docking enclosures.
United Arab Emirates
Smart city initiatives and critical infrastructure protection programs generate demand for desert-hardened IP67 docking enclosures. Dubai and Abu Dhabi municipal authorities specify vision-based landing systems for GPS-contested environments. Procurement favors leasing structures that minimize upfront capital deployment for perimeter security applications.
Drone Docking Station Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market separates between integrated drone-dock system vendors and pure-play docking hardware specialists. Three archetypes dominate: manufacturing-scale diversified technology conglomerates, autonomous flight stack specialists, and modular payload-agnostic fabricators. Competitive moves center on strategic partnerships with utility fleet operators and vertical integration into precision positioning sensor supply.
Within the autonomous flight stack tier, Skydio exemplifies premium positioning through software-defined navigation capabilities. DJI occupies the manufacturing-scale archetype with integrated system offerings spanning consumer through enterprise tiers. Hextronics represents the modular specialist position with payload-agnostic architectures designed for third-party integration workflows.
| Leading Market Players |
|---|
| Freefly Systems |
| Parrot |
| DJI |
| Delair |
| Autel Robotics |
| Hextronics |
| Skydio |
| Insitu |
| Azur Drones |
| Others |
Supply Flow & Price Mechanics
FAA Part 107 waivers and BVLOS rulemaking in the United States gate both supply qualification and price differentiation by mandating IP67 certification and centimeter-grade precision for fully unattended operation, compressing margins for uncertified tiers while enabling premium capture for compliant architectures.
Pricing Analysis
Per-flight leasing contracts and extended fleet management subscriptions drive lifetime value beyond hardware margins. Three-tier pricing structure across premium autonomous docks, standard fixed installations, and economy charging stations stratifies by certification grade and environmental sealing. Cost compression in the economy tier is intensifying because Chinese cell production for hot-swappable modules faces export control volatility. Agricultural buyers in Brazil and Southeast Asia exhibit highest price sensitivity, while United States energy utilities prioritize BVLOS-ready architectures regardless of upfront cost.
Supply Chain Analysis
Strait of Malacca transit underwrites lithium-ion cell delivery schedules for battery swapping modules. Manufacturing concentrates in China, South Korea, and Taiwan for precision positioning sensors, with RTK-GNSS modules and machine-vision components feeding from Taiwanese fabs and Korean sensor foundries. Single-source vulnerability in Chinese cell production for hot-swappable docking modules exposes procurement to freight cost spikes and regulatory restriction. Distribution runs through direct OEM relationships with utility fleet operators and systems integrators, bypassing traditional industrial distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drone docking infrastructure is shifting toward platform economics as utility procurement departments unbundle hardware from fleet management subscriptions, creating interoperability requirements that favor vendors with open API architectures and multi-drone compatibility.
For Market Incumbents: Compound installed base advantages through backward integration into precision positioning sensor supply and captive certification laboratory capacity. IP67 validation bottlenecks at third-party laboratories threaten product launch timelines for competitors without in-house testing infrastructure. Capacity addition in Telangana and Karnataka assembly hubs secures cost position for Southeast Asian export markets. For New Entrants and Emerging Players: FAA Part 107 waiver fast-tracks enable rapid market entry for BVLOS-ready architectures without the 18-month capital appropriation cycles burdening legacy vendors. German industrial corridor automation in Bavaria and Baden-Württemberg represents the most penetrable white space, with manufacturing clusters seeking payload-agnostic stations for 24/7 facility monitoring. Go-to-market angle should emphasize per-flight leasing structures that compress procurement approval to 90-day operational expenditure cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated dock manufacturing as IP67-rated enclosures and precision positioning hardware comprise 35-45% of bill-of-materials costs. Five-to-ten year viability favors vendors with balance-sheet capacity to carry deployed assets under leasing models. Acquisition target archetype: modular payload-agnostic fabricators with CAAC certification pathways and existing utility relationships in Guangdong and Jiangsu provinces. Signal to watch: EASA standardization of fully unattended docking operations, which would concentrate procurement authority and set de facto technical specifications for export-oriented manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| IP67 Certification Fast-Track | Accelerates product launch timelines by bypassing 8-12 month third-party laboratory backlogs. |
| Backward Integration into RTK-GNSS Supply | Captures 35-45% bill-of-materials cost compression from precision positioning sensor production. |
| Per-Flight Leasing Model Deployment | Compresses United States utility procurement cycles from 18-month capital appropriations to 90-day approvals. |
| CAAC Certification Pathway Completion | Unlocks scaled deployment along Guangdong and Jiangsu power corridors and rail networks. |
| 5G URLLC Network Slicing Partnership | Enables real-time telemetry for rural inspection markets previously unreachable via conventional connectivity. |
Methodological Framework
Initial hypotheses were tested against primary input from utility fleet operations directors, docking station engineering leads, FAA certification consultants, and energy utility procurement officers and refined through secondary validation against FAA Part 107 waiver databases, EASA drone regulation amendment filings, FERC transmission reliability assessment records, and CAAC unmanned aerial system certification disclosures. Bottom-up unit deployment estimates triangulated with top-down infrastructure digitization program budgets across the analysis window.
Variance-decomposition across product type, technology modality, application workflow, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level deployment trajectories and replacement cycle assumptions throughout the forecast period. Industry-specific inputs included BVLOS permission timeline compressions, IP67 certification backlog durations, and utility per-flight leasing adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable FAA BVLOS rulemaking progression and continued Chinese cell export availability; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EASA standardization timelines and India PLI scheme localization incentives evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Autonomous Technology Market
Unmanned Systems
Middle East and Africa Unmanned Surface Vehicle (USV) Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
Europe Unmanned Systems Market
Unmanned Systems
US Autonomous Navigation Market
Unmanned Systems
Explosive Ordnance Disposal (EOD) Robot Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market
Unmanned Systems
Autonomous Pods Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Autonomous Drone Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Unmanned Sea System Market
Unmanned Systems
Autonomous BVLOS Drones Market
Unmanned Systems
Drone Tethered Stations Market