
 Europe Remote Sensing Satellites Market | 2026-2036
Europe Remote Sensing Satellites Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Remote Sensing Satellites Market Insights
Platform licensing revenue is rewriting profitability profiles across the value chain. Airbus SE leverages end-to-end mission design capabilities to anchor high-margin sovereign contracts. Thales Alenia Space sustains dual-use optical and radar portfolios that dominate European institutional procurement. OHB SE competes through specialized small-satellite platforms that reduce time-to-orbit for commercial operators.
Remote sensing satellites are spacecraft equipped with passive or active sensors—operating across visible, infrared, microwave, or radio-frequency spectra—to capture Earth-surface data at resolutions from sub-meter to kilometer scale, with revisit cycles ranging from minutes to weeks depending on orbital configuration. Synthetic aperture radar payloads penetrate cloud cover and darkness, serving defense and maritime surveillance where optical systems fail. Data-as-a-Service deployment models are capturing margin pools previously held by hardware manufacturers, while environmental monitoring applications drive the fastest growth in subscription-based analytics. Government end users still occupy the largest budget share through Copernicus and national programmes.
The European Space Agency coordinates Copernicus programme standards, while national regulators in France and Germany enforce ITAR-aligned export controls on sensitive sensor technologies. REACH and RoHS frameworks constrain material selection for satellite manufacturing, pushing suppliers toward lead-free soldering and restricted-substance compliance. Stakeholders must monitor how the EU AI Act classifies autonomous image-processing algorithms, as this will reshape liability structures for analytics providers and downstream users.
Market Dynamics
The EU Green Deal and Copernicus programme expansions are compressing procurement cycles while sovereign capability mandates force national space agencies to accelerate domestic satellite deployment timelines.
Growth Catalysts
- Copernicus programme expansion:The European Space Agency is expanding Sentinel constellation coverage, creating sustained institutional demand for synthetic aperture radar and optical payloads across member states.
- Precision agriculture adoption:French and German farming cooperatives are deploying satellite-derived crop analytics to meet EU Farm to Fork sustainability targets and optimize nitrogen application rates.
- Dual-use technology convergence:Defense ministries in Italy and Spain are funding Earth observation capabilities that serve both military surveillance and environmental monitoring missions.
Market Restraints
- Export control friction:ITAR-aligned restrictions enforced by France and Germany block technology transfer for sub-meter resolution sensors, limiting commercial partnerships with non-European operators.
- Launch capacity scarcity:European institutional reliance on Arianespace and emerging national launch providers creates bottlenecks for small-satellite constellation deployment schedules.
- Substitute data sources:Stratospheric balloon platforms and high-altitude pseudo-satellites are capturing point-observation contracts at lower cost for localized monitoring applications.
Strategic Opportunities
- Eastern European sovereign programs:Poland and Romania are establishing national Earth observation capabilities with EU cohesion fund support, creating first-mover advantages for platform suppliers.
- Carbon credit verification services:The EU Emissions Trading System expansion is generating demand for satellite-based forest carbon stock monitoring and emissions verification at project sites.
- AI-driven analytics unbundling:Machine learning inference at the edge is enabling new subscription revenue models where downstream providers capture value previously retained by hardware manufacturers.
Industry Challenges
- Specialized workforce scarcity:Phased array antenna design and onboard processing architecture expertise concentrates in Toulouse, Munich, and Bremen clusters, creating recruitment competition.
- REACH material compliance:Lead-free soldering mandates and restricted substance frameworks are forcing redesigns of thermal management systems and radiation-hardened electronics.
- Legacy ground segment integration:National agencies operate incompatible data reception and processing architectures, complicating multi-mission service delivery for commercial analytics providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Remote Sensing Satellites Market |
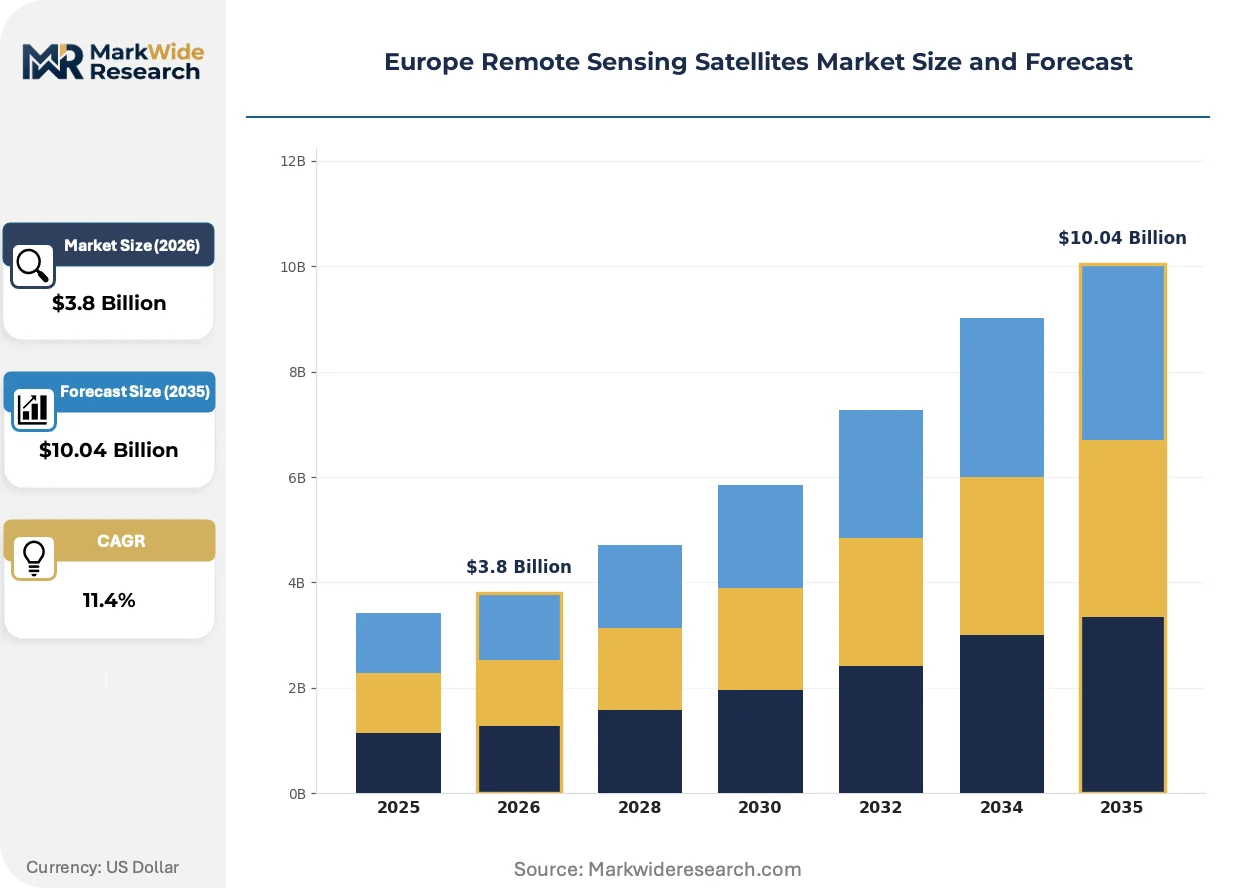
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical, Synthetic Aperture Radar, Multispectral, Hyperspectral Application: Agriculture, Urban Planning, Disaster Management, Environmental Monitoring End User: Government, Civil Engineering, Energy, Research Institutions Deployment: On-orbit, Ground-based, Data-as-a-Service, Hybrid |
| Companies Covered | Airbus SE, Thales Alenia Space, ROSCOSMOS, RSC Energia, NPO Lavochkin, OHB SE, Surrey Satellite Technology Ltd, GomSpace, BAE Systems, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Remote Sensing Satellites Market Trends and Innovations
Satellite miniaturization and software-defined payloads are collapsing traditional mission economics while regulatory frameworks accelerate autonomous system deployment across European institutional programs.
Software-defined radio payloads are collapsing the hardware-software boundary in synthetic aperture radar missions. Italian and Spanish defense procurement offices are mandating reconfigurable waveforms for dual-use maritime surveillance. This compression enables single satellites to serve multiple mission profiles, reducing constellation size requirements for persistent coverage.
The EU AI Act classification framework for autonomous image-processing algorithms is reshaping liability allocation across the value chain. Analytics providers operating inference engines aboard satellites must now document risk management systems for high-risk AI applications. French and German environmental monitoring contracts are incorporating algorithmic audit requirements that favor established suppliers with compliance infrastructure.
Subscription-based Data-as-a-Service models are displacing traditional hardware-plus-licensing contracts in commercial Earth observation. Agricultural input distributors in France and Germany are bundling satellite-derived prescription maps with seed and fertilizer sales. This channel shift concentrates buyer power among agritech platforms while fragmenting direct satellite operator relationships with end users.
Europe Remote Sensing Satellites Market Segmentation
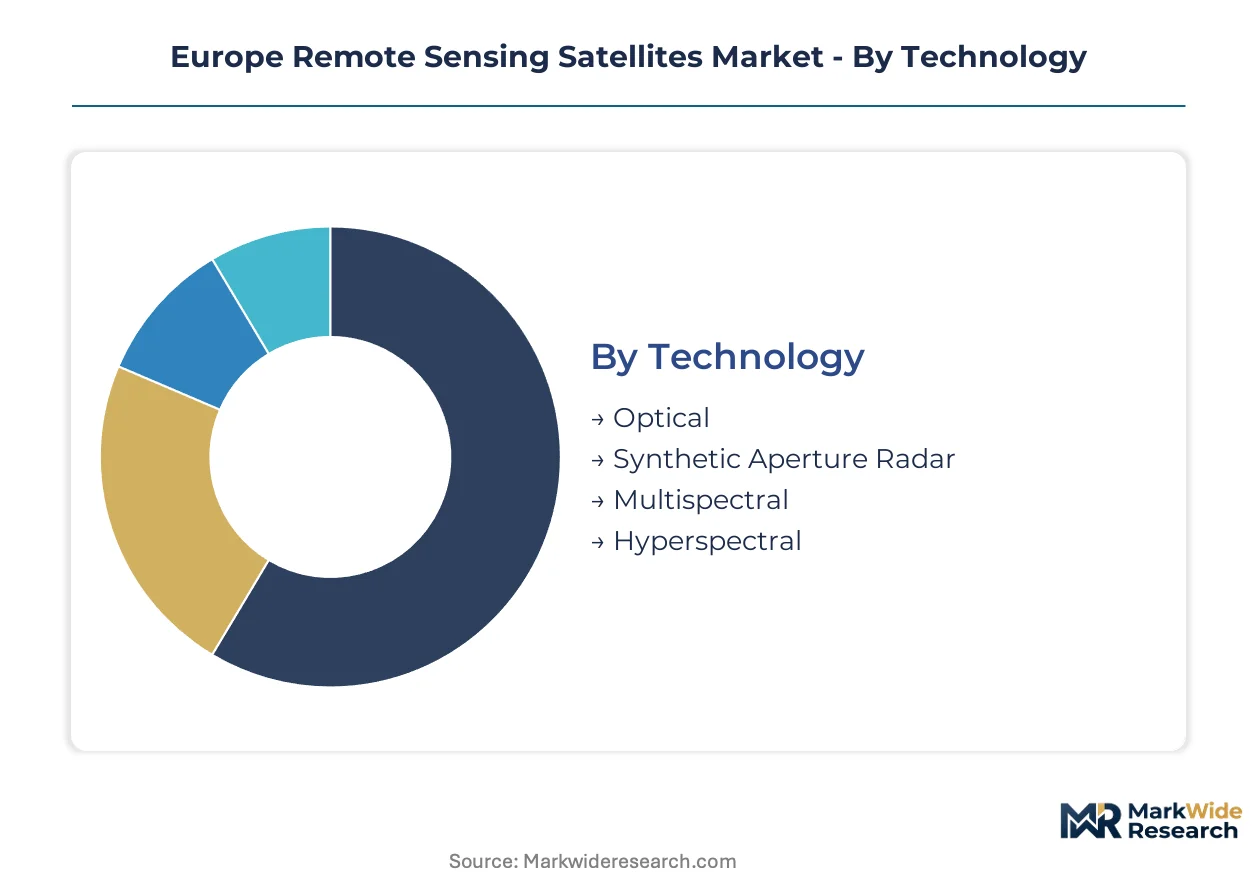
Technology diversity across European remote sensing satellites creates distinct procurement patterns. Payload specifications determine institutional budget allocation, commercial service pricing, and regulatory compliance obligations across member states.
Technology:
Mature optical systems coexist with emerging hyperspectral architectures across European institutional programmes.
- Optical:Passive sensors capture reflected visible and near-infrared light at sub-meter resolution for cartography and land-use classification. French and German defense ministries anchor procurement through Copernicus Contributing Missions, though cloud-dependency limits tropical zone utility.
- Synthetic Aperture Radar:Active microwave systems penetrate cloud cover and darkness using phase-coherent signal processing. Italian and Spanish maritime surveillance programmes drive demand for all-weather vessel detection and oil spill monitoring capabilities.
- Multispectral:Discrete wavelength bands support vegetation index calculation and mineral mapping for agricultural cooperatives.
- Hyperspectral:Continuous narrow-band coverage enables material identification for precision agriculture and environmental contamination tracking.
Optical retains volume leadership; Hyperspectral holds the steepest expansion curve.
Application:
Cost tier differentiation separates sovereign mandates from commercial subscription services.
- Agriculture:Satellite-derived prescription maps optimize nitrogen application and irrigation scheduling for French and German farming cooperatives meeting EU Farm to Fork targets. Bundled agritech platform sales concentrate buyer power among input distributors.
- Environmental Monitoring:Forest carbon stock assessment and emissions verification serve EU Emissions Trading System compliance. Polish and Romanian cohesion fund programmes are expanding procurement for national ecosystem accounting.
- Urban Planning:Infrastructure change detection and informal settlement mapping support municipal zoning enforcement.
- Disaster Management:Rapid damage assessment and flood extent mapping activate under Civil Protection Mechanism protocols.
Environmental Monitoring commands the largest institutional budget share; Agriculture is expanding most quickly through commercial channel partnerships.
End User:
Customer type determines contract structure, with sovereign programmes favoring hardware procurement and commercial operators preferring service subscriptions.
- Government:National space agencies and EU institutions deploy dedicated satellites through Copernicus and bilateral arrangements. ESA coordination standards ensure interoperability across French, German, and Italian ground segments.
- Energy:Pipeline route planning and methane leak detection serve grid operators and renewable site developers.
- Civil Engineering:Terrain stability monitoring and construction progress tracking support infrastructure megaprojects.
- Research Institutions:Academic consortia access archived data through Copernicus Open Access Hub for climate and geoscience studies.
Government dominates absolute spending; Energy is gaining share fastest through emissions compliance mandates.
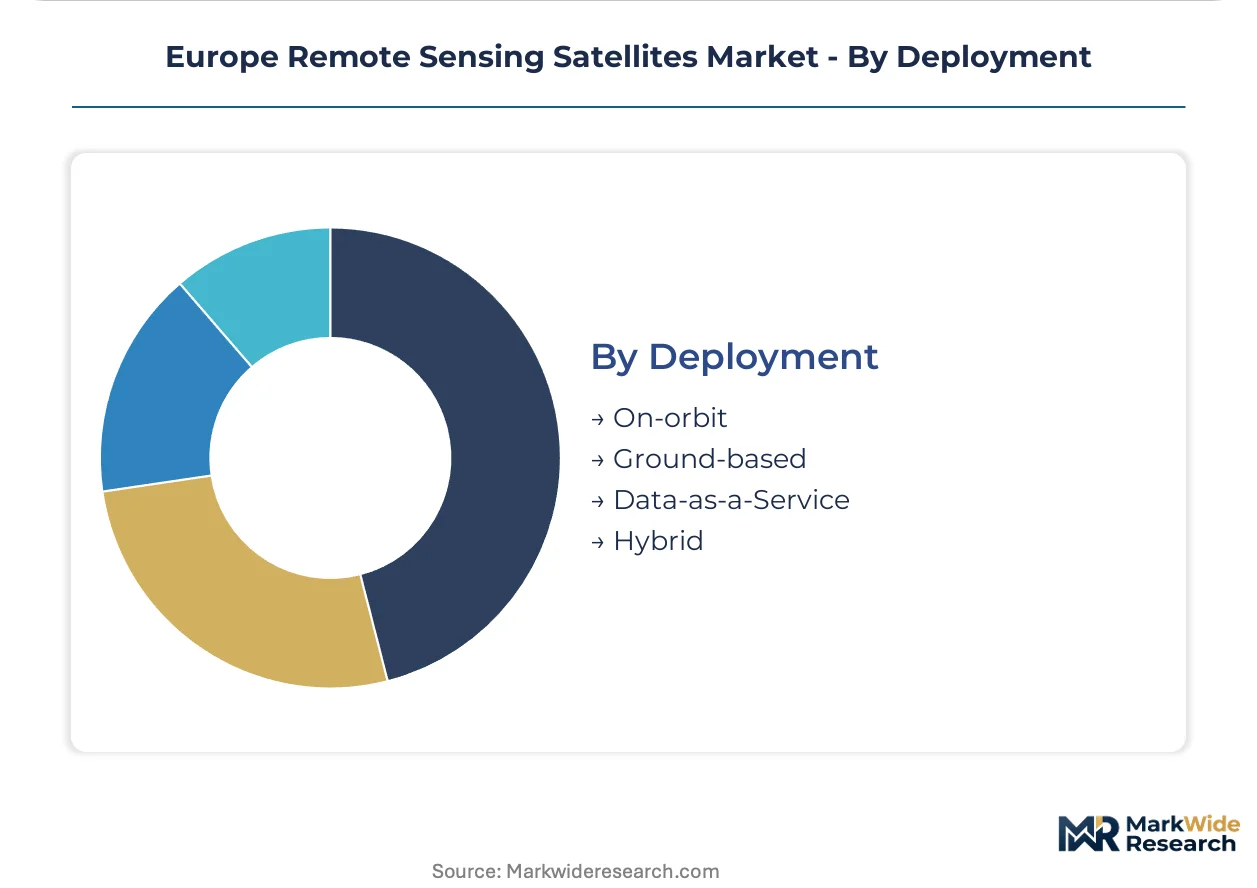
Deployment:
Supply concentration in legacy hardware manufacturers is fragmenting as platform licensing models proliferate.
- Data-as-a-Service:Subscription analytics bundles displace direct satellite ownership for agricultural and insurance verticals. French and German agritech platforms now intermediate end-user relationships previously held by operators.
- On-orbit:Dedicated satellite ownership persists for sovereign missions requiring assured access and classified processing.
- Ground-based:Direct downlink and national processing centers serve defense and intelligence communities with data residency requirements.
- Hybrid:Combined ownership and service contracts balance control with cost flexibility for mid-tier institutional users.
On-orbit retains volume leadership for sovereign missions; Data-as-a-Service climbs the fastest as commercial adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across European procurement frameworks. Commercial agritech operators in France and Germany negotiate aggressively on per-hectare analytics pricing, while sovereign missions in Italy and Spain prioritize assured access over unit cost.
France
Precision agriculture cooperatives in the Île-de-France and Hauts-de-France regions drive commercial demand for subscription-based crop analytics. CNES anchors national Earth observation policy through bilateral Copernicus Contributing Missions. Toulouse hosts the dominant satellite manufacturing cluster where Airbus SE designs end-to-end mission architectures.
Germany
Environmental monitoring contracts for forest carbon verification expand fastest in Bavaria and Baden-Württemberg under EU Emissions Trading System mandates. The national space agency enforces ITAR-aligned export controls on sub-meter resolution sensor technologies. Munich and Bremen concentrate phased array antenna design expertise for next-generation radar payloads.
Italy
Dual-use maritime surveillance programs fund synthetic aperture radar procurement for Mediterranean vessel detection and oil spill monitoring. The defense ministry coordinates requirements with environmental agencies under converged mission profiles. Rome and Turin anchor optical payload integration facilities serving institutional buyers.
Spain
Civil Protection Mechanism activation protocols drive demand for rapid damage assessment capabilities after flood and wildfire events. National regulators align procurement with EU AI Act algorithmic audit requirements for autonomous image processing. Madrid hosts emerging ground segment operators competing on multi-mission service delivery.
Poland
EU cohesion fund allocations support establishment of first national Earth observation capabilities for agricultural and border surveillance applications. The national space agency issues tenders for small-satellite platforms with accelerated deployment timelines. Warsaw clusters emerging analytics providers targeting Eastern European sovereign programs.
Europe Remote Sensing Satellites Market Competitive Landscape
Full-service mission integrators and specialized platform suppliers split the market along capability depth versus deployment velocity lines. The vendor base concentrates in France, Germany, and Italy where national space agencies anchor procurement. Three archetypes dominate: end-to-end sovereign contractors, dual-use technology houses, and small-satellite specialists. Competitive moves center on platform licensing revenue capture and constellation deployment partnerships.
Within the full-service tier, Airbus SE and Thales Alenia Space occupy positions defined by sovereign contract anchoring and dual-use portfolio breadth. OHB SE exemplifies the specialized platform archetype competing on reduced time-to-orbit for commercial operators. These three entities represent the competitive core around which procurement patterns and pricing benchmarks consolidate across European institutional and commercial segments.
| Leading Market Players |
|---|
| Airbus SE |
| Thales Alenia Space |
| ROSCOSMOS |
| RSC Energia |
| NPO Lavochkin |
| OHB SE |
| Surrey Satellite Technology Ltd |
| GomSpace |
| BAE Systems |
| Others |
Pricing and Supply Chain Analysis
Launch capacity underutilization at Arianespace and emerging national providers is compressing satellite deployment costs while simultaneously extending lead times for commercial operators, creating divergent pricing postures between sovereign missions prioritizing assured access and agritech platforms negotiating per-hectare analytics rates.
Pricing Analysis
Platform licensing and extended service contracts drive lifetime value capture across the European remote sensing value chain. Three-tier pricing structure across premium sovereign-grade, standard institutional, and economy commercial tiers reflects payload resolution capabilities and data latency guarantees. Cost compression in commercial satellite imagery is intensifying because agritech platforms intermediate end-user relationships and consolidate buyer power. French and German farming cooperatives exhibit highest price sensitivity on per-hectare subscription rates, while Italian and Spanish defense ministries prioritize mission assurance over unit cost.
Supply Chain Analysis
Specialized semiconductor substrates and radiation-hardened electronics feed from concentrated manufacturing clusters in France, Germany, and the Netherlands. Synthetic aperture radar components draw from Munich and Bremen design houses, while optical payload integration centers on Toulouse and Turin facilities. Single-source vulnerability in phased array antenna supply creates procurement risk for radar constellation programs. Distribution runs through national space agency procurement frameworks for sovereign missions and agritech platform aggregators for commercial analytics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where regulatory entrenchment through ITAR-aligned export controls and Copernicus programme standards creates substantial barriers to technology transfer and non-European supplier participation.
For Market Incumbents: Harden sovereign contract anchoring through accelerated Copernicus Contributing Mission certifications and captive supply of sub-meter resolution sensor production. Emerging small-satellite specialists threaten margin compression in commercial segments, requiring selective capacity addition in Eastern European markets to preempt Polish and Romanian national programme awards. For New Entrants and Emerging Players: Carbon credit verification services for EU Emissions Trading System compliance represent the most penetrable entry point, with Polish and Romanian cohesion fund programmes offering first-mover positioning for analytics providers. Software-defined payload licensing to mid-tier institutional users enables channel bypass of established hardware manufacturers. For Investors and Strategic Acquirers: Capital is best deployed toward platform-software hybrids with AI-driven analytics capabilities and established EU AI Act compliance infrastructure. Long-term viability rests on subscription revenue capture in agricultural and environmental monitoring verticals. The signal to watch is Arianespace launch cost trajectories and their impact on small-satellite constellation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Payload Development | Reconfigurable radar waveforms enable single satellites to serve multiple Italian and Spanish dual-use mission profiles. |
| AI Act Compliance Infrastructure | Algorithmic audit capabilities secure French and German environmental monitoring contracts requiring documented risk management. |
| Eastern European Market Entry | Polish and Romanian cohesion fund programmes create first-mover advantages for small-satellite platform suppliers. |
| Carbon Verification Service Launch | EU Emissions Trading System expansion generates satellite-based forest carbon stock monitoring demand. |
| Ground Segment Modernization | Multi-mission service delivery capabilities address legacy architecture fragmentation across national agencies. |
Research Methodology
The analysis maps optical payload, synthetic aperture radar, multispectral, and hyperspectral technology segments, each validated through satellite platform engineers, national space agency procurement officers, agritech platform product managers, and defense ministry requirements specialists. Primary interview findings triangulate against ESA programme documentation, Copernicus data access records, EU Green Deal implementation reports, and REACH compliance filings. Bottom-up segment sizing and top-down institutional budget reconciliation anchor value estimates.
Forecasts assume stable EU Green Deal funding trajectories and Copernicus programme expansion timelines across the analysis window, with technology adoption curves, application penetration rates, and end-user procurement patterns modeled by segment. CAGRs derive from satellite deployment schedules, platform licensing revenue migration, and Data-as-a-Service subscription growth. Industry-specific inputs include Arianespace launch manifest capacity and EU AI Act implementation timelines.
Practitioners should monitor launch cost volatility, cohesion fund allocation shifts, and AI Act enforcement patterns for early signals of forecast deviation. Quarterly review of national space agency tender awards and agritech platform partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
China Satellite Connectivity Market
Satellite
United Kingdom Satellite Communications Market
Satellite
Asia-Pacific Satellite IoT Market
Satellite
Satellite Parts and Components Market
Satellite
Japan Satellite Connectivity Market
Satellite
Asia-Pacific Satellite Launch Vehicle Market
Satellite
Sudan Satellite Transponder Market
Satellite
North America Military Satellite Market
Satellite
North America Remote Sensing Services Market
Satellite
Global Enterprise VSAT System Market
Satellite
Europe Satellite Manufacturing and Launch Systems Market
Satellite
Satellite Communication (SATCOM) Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
Medium and Large Satellite Market
Satellite
Satellite Data Analytics Services Market