
 Reusable Satellite Launch Vehicle (RSLV) Market | 2026-2036
Reusable Satellite Launch Vehicle (RSLV) Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Satellite Launch Vehicle (RSLV) Market Analytics
Aftermarket service revenue is narrowing as a margin pool as operators internalize refurbishment and vertical launchers capture recurring flight economics. SpaceX sustains cost leadership through rapid booster turnaround and fleet standardization. Blue Origin competes via heavy-lift architectures and engine reusability. Rocket Lab specializes in small-lift recovery, anchoring a niche that larger vehicles cannot address profitably.
A reusable satellite launch vehicle is a space transportation system designed to perform multiple orbital missions through controlled return and refurbishment of core components, typically incorporating propulsive landing, thermal protection systems, and structural hardening for repeated aerothermal loading. Its primary commercial purpose is to reduce per-launch costs below expendable alternatives while maintaining payload reliability for satellite deployment. Vertical launchers dominate current flight manifests due to proven propulsive descent and ocean platform recovery, while recovery systems represent the fastest-improving technology segment as autonomous guidance and grid fin control mature. Horizontal launchers remain developmental, with air-breathing engine integration posing longer lead times but promising runway flexibility for responsive space access.
The FAA regulates commercial launch licensing and safety oversight in the United States, while NASA sets technical standards for crew-rated systems and mission assurance. ESA and national European regulators coordinate under EU Space Law frameworks that increasingly mandate debris mitigation and end-of-life disposal for constellation operators. Stakeholders must monitor how ITU spectrum coordination and national export control revisions affect cross-border component flows and launch site access as fleet scale accelerates.
Market Dynamics
Booster turnaround velocity now determines competitive position as SpaceX's sub-30-day refurbishment cycles compress pricing benchmarks across all payload classes. Fleet standardization and propulsive landing maturation have shifted procurement criteria from per-mission reliability to cumulative cost-per-kilogram economics.
Growth Catalysts
- Orbital debris mitigation mandates:The FAA and NASA have tightened end-of-life disposal requirements for constellation operators, creating procurement preference for launch systems with demonstrated recovery and refurbishment protocols that reduce upper-stage debris generation.
- Small satellite constellation deployment:Commercial Earth observation and communications operators are procuring dedicated small-lift services rather than rideshare arrangements, expanding addressable flight rate for reusable architectures below five-ton payload classes.
- Grid fin and autonomous guidance maturation:Terminal descent precision improvements enable ocean platform recovery in higher sea states, expanding launch windows and reducing weather scrub rates for vertical launchers.
Market Restraints
- Specialized alloy supply concentration:Nickel-based superalloys for reusable engine combustion chambers source primarily from US and Russian suppliers, creating input cost volatility and export control exposure.
- Range safety infrastructure limitations:Eastern and Western Range launch corridors face capacity constraints, capping annual flight rate regardless of vehicle availability.
- Horizontal launcher technical barriers:Air-breathing propulsion integration and thermal protection for winged return impose longer development timelines than vertical alternatives, delaying competitive entry.
Strategic Opportunities
- Responsive space access for defense:The US Space Force is soliciting rapid-reconstitution capabilities for orbital assets, creating procurement channels for vehicles with sub-24-hour call-up and launch readiness.
- India's emerging launch ecosystem:ISRO's reusable launch vehicle program and private sector entrants like Skyroot Aerospace present partnership and technology transfer opportunities for established recovery system suppliers.
- On-orbit servicing convergence:Integration of reusable launch with satellite life-extension and refueling missions creates bundled service models that capture recurring revenue beyond deployment.
Industry Challenges
- Propulsion engineering talent scarcity:Full-flow staged combustion and reusable turbopump design expertise concentrates at a handful of US and Russian organizations, constraining workforce expansion for new entrants.
- Human-rating certification timelines:NASA's Crew Transportation System standards require extensive flight heritage and anomaly resolution, extending development schedules for crew-capable reusable architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Satellite Launch Vehicle (RSLV) Market |
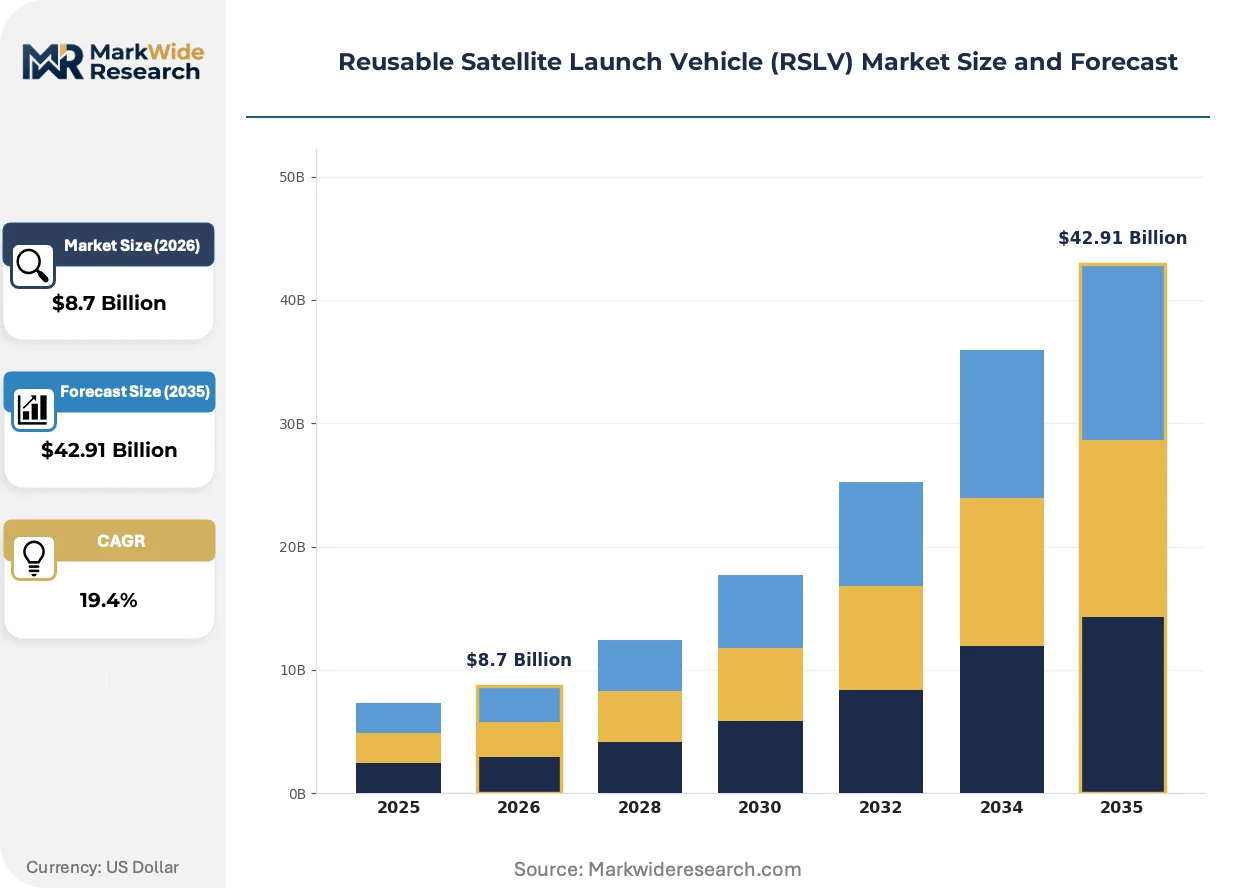
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Launchers, Horizontal Launchers, Hybrid Systems, Reusable Boosters Technology: Rocket Propulsion, Air-Breathing Engines, Stage Separation, Recovery Systems End User: Government Agencies, Private Enterprises, Research Institutions, Defense Contractors Application: Communication Satellites, Earth Observation, Scientific Research, Space Exploration |
| Companies Covered | SpaceX, Blue Origin, Rocket Lab, Relativity Space, ArianeGroup, United Launch Alliance, Northrop Grumman, Lockheed Martin, ISRO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Satellite Launch Vehicle (RSLV) Market Evolving Landscape
Active recovery system evolution now dominates engineering resource allocation as autonomous landing precision and rapid refurbishment protocols reshape cost structures. Three developmental trajectories are compressing competitive differentiation windows.
Stainless steel primary structures with active cooling layers are collapsing the mass penalty traditionally associated with reusable thermal protection. SpaceX's Starship program and several Chinese developmental vehicles have adopted this architecture, eliminating carbon-fiber layup bottlenecks and enabling in-field repair. The approach is collapsing capital requirements for new vehicle programs while extending operational life expectancy beyond fifty flights.
The FAA's updated Part 450 commercial launch regulations are streamlining licensing for reusable vehicles with demonstrated flight history. Operators meeting specific anomaly resolution and reliability thresholds qualify for reduced safety review scope, compressing pre-launch authorization timelines. This regulatory evolution most benefits US-based vertical launchers with established recovery records, widening their scheduling advantage over developmental competitors.
Constellation operators are consolidating procurement around vertically integrated launch-service providers that bundle manufacturing, launch, and on-orbit commissioning. This behavioral shift displaces traditional satellite prime contractor arrangements and places payload integration expertise within launch organizations. The pattern is most visible in US low Earth orbit communications deployments, where operators negotiate multi-launch blocks directly with recovery-capable providers.
Reusable Satellite Launch Vehicle (RSLV) Market Segmentation
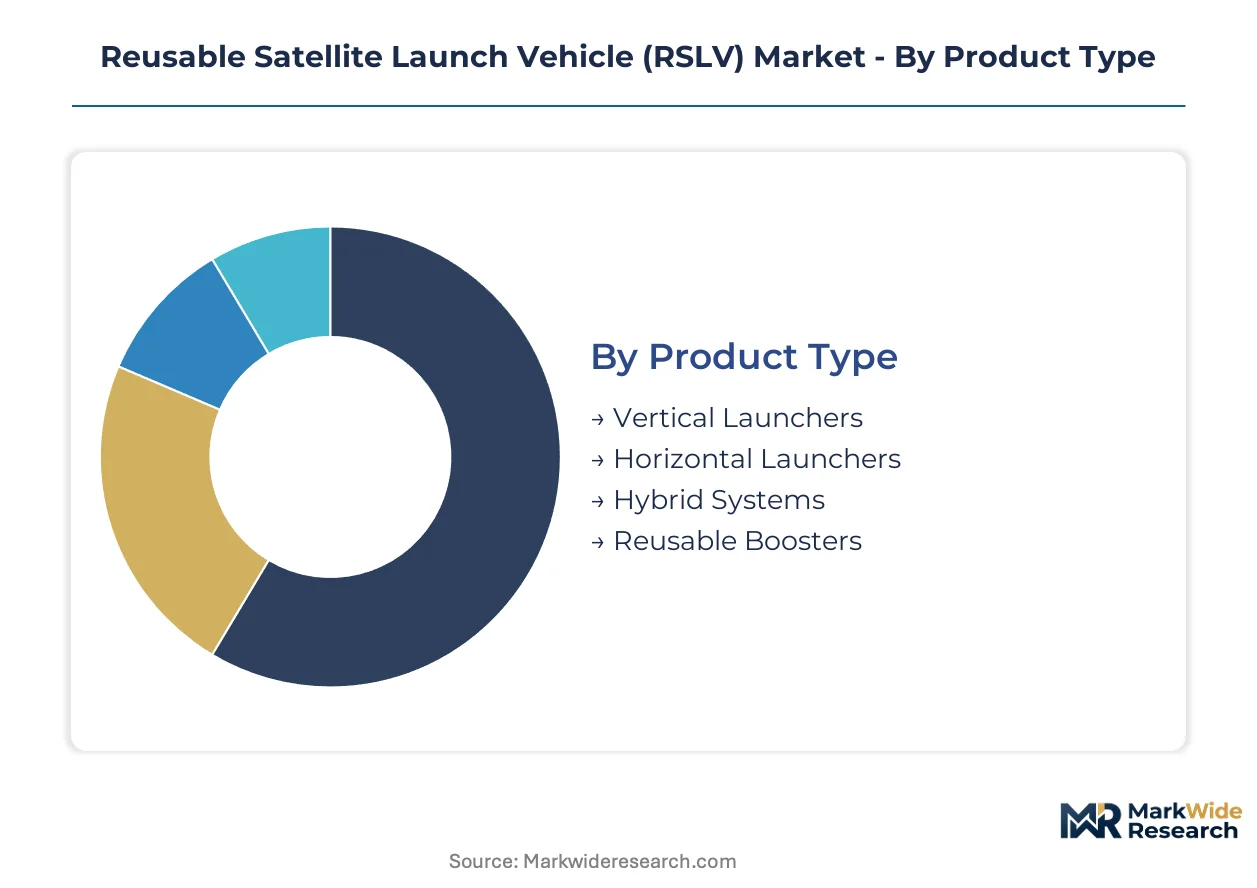
Segmentation in the RSLV market reveals how technical architecture, operational model, and customer procurement patterns create distinct competitive arenas. Each dimension carries implications for capital intensity, regulatory pathway, and margin structure that shape provider strategy.
Product Type:
Mature vertical architectures dominate flight-proven economics while emerging horizontal and hybrid configurations pursue runway flexibility and rapid reconstitution capabilities.
- Vertical Launchers:Propulsive descent with grid fin guidance enables ocean platform recovery in sea states up to 3.5 meters. Demand concentrates with US commercial constellation operators seeking sub-30-day turnaround and cumulative cost-per-kilogram below expendable alternatives. The FAA's streamlined Part 450 licensing for demonstrated recovery history reinforces this segment's scheduling advantage.
- Horizontal Launchers:Winged return with air-breathing propulsion integration promises runway landing and rapid payload swap. Developmental timelines extend 4-7 years beyond vertical alternatives due to thermal protection complexity for aerodynamic surfaces and scramjet/ramjet propulsion maturation.
- Hybrid Systems:Combined air-launch and rocket propulsion architectures under evaluation for responsive defense applications requiring sub-24-hour call-up from dispersed basing.
- Reusable Boosters:Strap-on first stage modules designed for separate recovery and refurbishment, enabling partial reusability on otherwise expendable vehicles without full vehicle redesign.
Vertical Launchers retain volume leadership; Hybrid Systems hold the steepest expansion curve as defense procurement prioritizes responsive space access.
Technology:
Cost tier differentiation separates mature propulsion from emerging recovery autonomy, with mid-tier stage separation capturing volume from rideshare optimization.
- Rocket Propulsion:Full-flow staged combustion and reusable turbopump designs concentrate expertise at US and Russian organizations. Nickel-based superalloy supply constraints from limited US and Russian suppliers create input cost volatility for combustion chamber production.
- Air-Breathing Engines:Scramjet and combined-cycle propulsion for atmospheric acceleration phases remain developmental, with thermal management and mode transition reliability extending qualification timelines.
- Stage Separation:Precision timing and clean mechanical separation systems enable rideshare optimization and upper-stage debris minimization under tightening FAA and NASA orbital debris rules.
- Recovery Systems:Autonomous landing guidance, deployable aerodynamic surfaces, and thermal protection hardening represent the fastest-improving technology segment as grid fin control and terminal descent precision mature.
Rocket Propulsion anchors current cost structures; Recovery Systems are climbing the fastest as autonomous precision reshapes refurbishment economics.
End User:
Customer type segmentation tracks procurement concentration from institutional anchor demand through emerging commercial volume.
- Government Agencies:NASA crew-rating standards and mission assurance requirements drive procurement toward vehicles with extensive flight heritage and anomaly resolution documentation. Certification timelines extend development schedules for crew-capable architectures.
- Private Enterprises:Commercial constellation operators are consolidating procurement around vertically integrated launch-service providers that bundle manufacturing, launch, and on-orbit commissioning, displacing traditional satellite prime contractor arrangements.
- Research Institutions:Academic and scientific payload operators prioritize schedule flexibility and dedicated launch windows over pure cost minimization.
- Defense Contractors:US Space Force rapid-reconstitution solicitations create procurement channels for vehicles with sub-24-hour readiness and responsive basing.
Private Enterprises command the largest share of flight rate expansion; Defense Contractors are gaining share fastest as national security space priorities reconstitute.
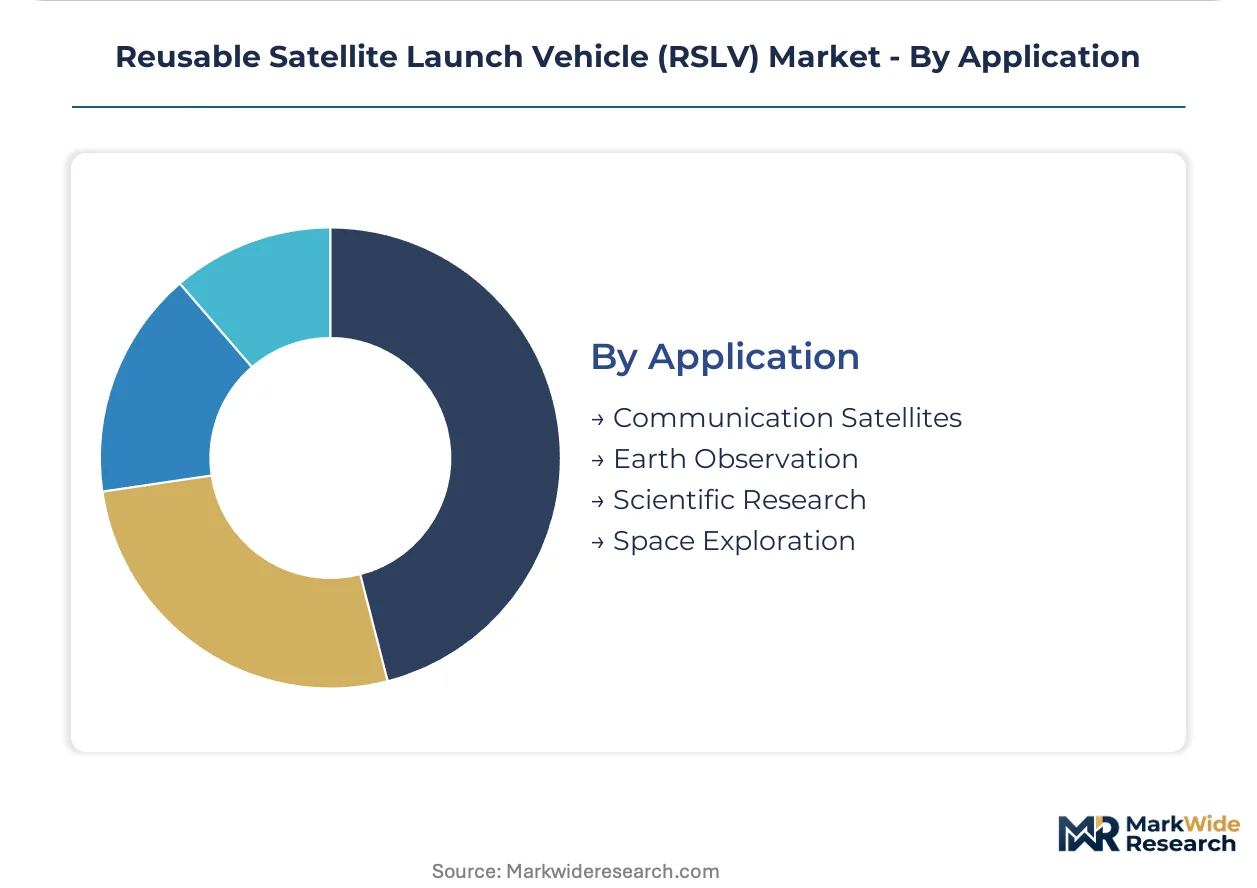
Application:
Application segmentation follows payload mass and orbit requirements, with communications volume contrasting against exploration's technical complexity premium.
- Communication Satellites:Low Earth orbit broadband constellations drive the highest flight rate demand, with operators negotiating multi-launch blocks directly with recovery-capable providers for deployment cadence.
- Earth Observation:Commercial remote sensing operators are procuring dedicated small-lift services rather than rideshare arrangements, expanding addressable flight rate for architectures below five-ton payload classes.
- Scientific Research:Precision orbit insertion and contamination avoidance requirements favor vehicles with demonstrated upper-stage reliability and clean payload fairing environments.
- Space Exploration:Crew-rated systems and deep-space injection impose the most stringent NASA technical standards and extended human-rating certification timelines.
Communication Satellites retain volume leadership; Earth Observation holds the steepest expansion curve as dedicated small-lift procurement displaces rideshare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial operators in the United States demonstrate the highest price elasticity, negotiating multi-launch blocks based on cumulative cost-per-kilogram economics, while institutional buyers in Europe and Asia accept moderate premiums for mission assurance and schedule flexibility.
United States
Low Earth orbit broadband constellation operators drive procurement volume through vertically integrated launch-service contracts. The FAA's Part 450 streamlined licensing rewards demonstrated recovery history with reduced safety review scope. SpaceX's Boca Chica and Cape Canaveral facilities anchor booster refurbishment and rapid turnaround operations.
China
State-backed constellation programs and commercial remote sensing ventures expand addressable flight rate for domestic reusable architectures. The national space administration coordinates debris mitigation mandates under evolving technical standards. Developmental stainless steel vehicle programs in Jiangsu and Shaanxi provinces pursue active cooling architectures to collapse thermal protection mass penalties.
India
ISRO's reusable launch vehicle program and private sector entrants like Skyroot Aerospace create partnership opportunities for recovery system suppliers. The national space regulator aligns orbital debris rules with tightening international frameworks. Bengaluru and Sriharikota host propulsion testing and launch site infrastructure development.
Germany
Earth observation operators and scientific payload missions prioritize precision orbit insertion over pure cost minimization. ESA coordination under EU Space Law frameworks mandates debris mitigation and end-of-life disposal for constellation operators. Bremen and Munich industrial clusters concentrate satellite manufacturing and launch service procurement expertise.
Japan
Commercial communications and remote sensing operators seek dedicated small-lift services below five-ton payload classes. METI oversees national space industrial policy and export control alignment with international technology transfer restrictions. Tanegashima and Uchinoura launch facilities support domestic and rideshare mission manifests.
Reusable Satellite Launch Vehicle (RSLV) Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: rapid-turnaround vertical launcher specialists, heavy-lift engine reusability developers, and small-lift recovery niche operators. Consolidation pressure favors providers with demonstrated flight heritage and autonomous landing precision. Dominant competitive moves include fleet standardization for refurbishment economics and regulatory pathway optimization for licensing timeline compression.
Among US-based operators, SpaceX and Blue Origin exemplify scale-driven and heavy-lift archetypes respectively, while Rocket Lab occupies a position within the small-lift recovery tier. SpaceX represents the rapid-turnaround vertical launcher model through sub-30-day booster refurbishment cycles. Blue Origin anchors the heavy-lift engine reusability category with propulsion architectures designed for sustained flight rates. Rocket Lab sits within the dedicated small-lift segment where larger vehicles cannot address payload classes profitably.
| Leading Market Players |
|---|
| SpaceX |
| Blue Origin |
| Rocket Lab |
| Relativity Space |
| ArianeGroup |
| United Launch Alliance |
| Northrop Grumman |
| Lockheed Martin |
| ISRO |
| Others |
Value Network & Pricing Analysis
Single-source nickel-based superalloy dependency from US and Russian suppliers compresses margin spreads across refurbishment tiers while forcing launch providers toward captive alloy stockpiling and alternative combustion chamber architectures. This input concentration simultaneously widens pricing gaps between flight-proven vehicles with established supply relationships and new entrants facing volatile procurement costs.
Pricing Analysis
Aftermarket refurbishment service contracts now drive lifetime value capture as operators internalize turnaround capabilities and reduce third-party dependency. Three-tier pricing structure across premium rapid-turnaround, standard refurbishment, and economy deferred-maintenance levels separates SpaceX's sub-30-day cycles from competitors requiring 60-90 days. Cost compression in the economy tier is intensifying because vertical launcher operators are achieving fleet-wide amortization below expendable alternatives. Commercial constellation operators demonstrate highest price sensitivity, negotiating multi-launch blocks based on cumulative cost-per-kilogram, while NASA crew-rated missions accept substantial premiums for anomaly resolution documentation.
Supply Chain Analysis
Extended payment terms from prime contractors to superalloy processors now finance inventory buffers against export control disruptions. Nickel-based superalloy supply concentrates in the United States, Russia, and select European specialty foundries. Recovery system manufacturing draws from precision machining clusters in Germany, Japan, and the United States. Single-source vulnerability for full-flow staged combustion turbopump castings creates chokepoint exposure. Distribution runs through vertically integrated launch-service providers that have absorbed payload integration and on-orbit commissioning functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable launch economics increasingly hinge on recurring refurbishment revenue streams expanding faster than initial vehicle sales as fleet scale accumulates flight heritage. The attach rate for rapid-turnaround service contracts now exceeds hardware margin contribution for established operators.
For Market Incumbents: Build regulatory pathway moats through FAA Part 450 anomaly resolution documentation that compresses licensing timelines for demonstrated recovery history. Incumbents should anchor capacity addition at Boca Chica and Cape Canaveral to maintain sub-30-day turnaround leadership against emerging vertical launcher competition. Certification investment in crew-rated systems creates defensive segmentation from commercial-only entrants. For New Entrants and Emerging Players: India's ISRO program and private sector entrants like Skyroot Aerospace represent the most penetrable entry point for recovery system technology transfer partnerships. Small-lift dedicated services below five-ton payload classes offer white-space refuge from SpaceX's cost leadership in medium-to-heavy lift. A go-to-market angle anchored in responsive defense procurement with sub-24-hour call-up capabilities bypasses direct commercial price competition. For Investors and Strategic Acquirers: The market sits at a fleet-scale accumulation phase that favors vertically integrated providers with demonstrated autonomous landing precision. Long-term viability over the next decade rests on refurbishment cycle compression and regulatory pathway optimization rather than vehicle development alone. Acquisition targets should display recovery system engineering depth and existing FAA flight history. The signal to watch is FAA licensing timeline compression for operators meeting reliability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Standardization Program | Unified booster architectures collapse refurbishment training costs and parts inventory requirements. |
| Autonomous Landing Precision Investment | Grid fin control maturation enables ocean platform recovery in higher sea states, expanding launch windows. |
| Stainless Steel Structure Transition | Active cooling layers eliminate carbon-fiber layup bottlenecks and enable in-field thermal protection repair. |
| Regulatory Pathway Optimization | FAA Part 450 qualification reduces safety review scope for demonstrated recovery history. |
| Responsive Defense Capability Development | Sub-24-hour call-up systems capture US Space Force rapid-reconstitution procurement channels. |
Research Methodology
Operator-level perspectives from launch operations directors, propulsion engineering leads, constellation procurement managers, and FAA licensing officials anchored the qualitative base. Primary interviews combined with secondary validation from FAA Part 450 regulatory filings, NASA mission assurance documentation, ESA debris mitigation technical standards, and customs records for nickel-based superalloy trade flows. Bottom-up flight rate modeling and top-down market sizing triangulated volume estimates.
Scenario-bracketing around regulatory acceleration, supply disruption, and constellation deployment delays framed uncertainty bands across the projection horizon. Segmentation dimensions modeled include launcher architecture, payload mass class, end-user procurement type, and refurbishment cycle tier. CAGRs derived from flight rate elasticity to cost-per-kilogram thresholds and fleet amortization schedules. Industry-specific inputs incorporated grid fin guidance maturation curves and superalloy price volatility indices.
Practitioners should monitor FAA licensing backlog expansion, nickel superalloy export control revisions, and constellation operator bankruptcy filings for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
North America Satellite Attitude and Orbit Control System Market
Satellite
UK Satellite-Based Earth Observation Market
Satellite
India Satellite Connectivity Market
Satellite
Commercial Satellite Launch Service Market
Satellite
South Korea Satellite Imagery Services Market
Satellite
Saudi Arabia Satellite-Based Earth Observation Market
Satellite
Europe Satellite Launch Vehicle Market
Satellite
All-Electric Satellites Market
Satellite
South Korea Satellite-Based Earth Observation Market
Satellite
Saudi Arabia Satellite Communications Market
Satellite
Global Dish Antennas Market
Satellite
North America Remote Sensing Satellites Market
Satellite
India Satellite Communication Market
Satellite
Asia-Pacific Military Satellite Market
Satellite
LEO and GEO Satellite Market
Satellite
Brazil Satellite Imagery Services Market