
 Artificial Intelligence in Space Market | 2026-2036
Artificial Intelligence in Space Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Space Market Insights
The EU AI Act is restructuring the cost-of-entry calculus for vendors selling autonomous decision-making systems into European satellite programs. Lockheed Martin Corporation leverages decades of classified space heritage to anchor its position in orbital AI payloads. Northrop Grumman Corporation sustains R&D intensity through its integration of neural networks into satellite servicing architectures. Boeing competes by extending its terrestrial aviation AI stack into spacecraft autonomy domains.
Artificial Intelligence in Space encompasses machine learning algorithms, neural networks, and computer vision systems deployed across orbital and deep-space platforms to process sensor data, optimize trajectories, and enable autonomous operations without continuous ground control. These systems typically operate with sub-watt to multi-kilowatt power budgets, radiation-hardened processors, and latency constraints measured in milliseconds for low-Earth orbit to hours for interplanetary missions. Satellite imaging applications currently dominate value capture due to commercial Earth observation demand, while reinforcement learning for spacecraft autonomy represents the fastest-expanding technology segment as operators pursue reduced ground-station dependency. Edge computing deployments aboard satellites concentrate margin pools at the hardware-software interface, whereas ground-station AI services face commoditization from cloud platform entrants.
NASA, the FAA, and the EU AI Act collectively shape market access through mission assurance requirements, commercial launch licensing, and algorithmic transparency mandates for autonomous space systems. The FAA's streamlined commercial space regulations reduce barriers for AI-enabled smallsat constellations, while NASA's technology readiness level standards enforce rigorous validation protocols for flight-qualified machine learning models. Stakeholders must monitor how emerging national space laws in multiple jurisdictions fragment compliance obligations for cross-border satellite data processing.
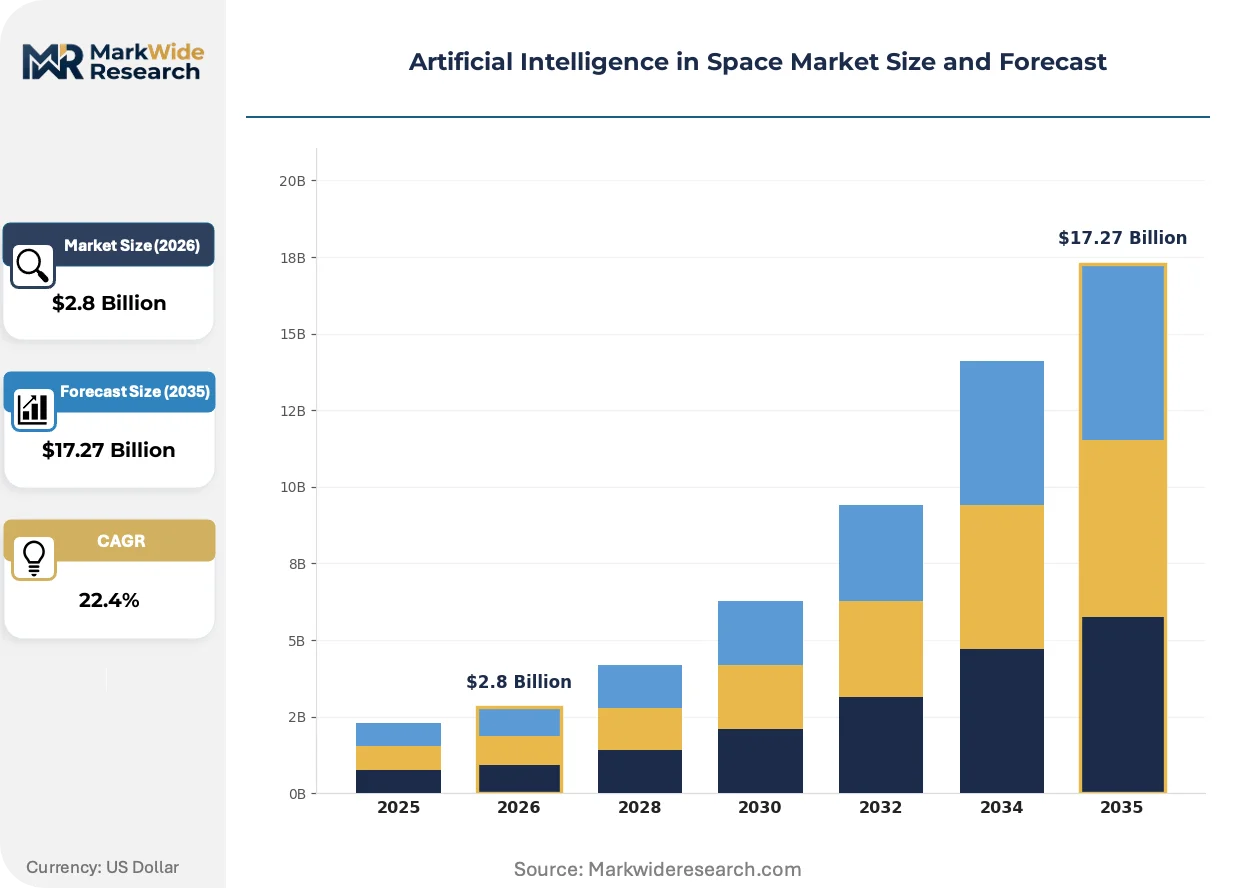
Market Dynamics
Onboard edge computing architectures are compressing latency constraints for satellite operators, forcing ground-station AI services toward commoditization as value migrates to radiation-hardened processors and orbital autonomy stacks.
Growth Catalysts
- Artemis program acceleration:NASA's lunar exploration timeline is pulling forward procurement of autonomous navigation systems for crewed and robotic missions, creating dedicated demand for flight-qualified neural networks.
- EU AI Act compliance mandates:Algorithmic transparency requirements for autonomous space systems are creating vendor qualification barriers that favor established suppliers with classified heritage and documentation protocols.
- Debris tracking urgency:Low-Earth orbit congestion is compelling satellite operators to deploy real-time machine learning for collision avoidance, driving hardware refresh cycles across commercial constellations.
Market Restraints
- Radiation-hardened processor scarcity:Foundry capacity for space-qualified semiconductors concentrates among a handful of defense-tier suppliers, creating input bottlenecks for AI payload manufacturers.
- Technology readiness level validation costs:NASA's TRL standards impose multi-year qualification timelines for machine learning models, compressing margins for vendors without amortized heritage systems.
- Ground-station service substitution:Cloud platform entrants are commoditizing terrestrial AI processing for satellite downlink data, eroding pricing power for traditional ground-segment providers.
Strategic Opportunities
- Cislunar infrastructure gap:Autonomous logistics for lunar orbit and surface operations represent underpenetrated demand, with no incumbent suppliers holding validated positions beyond Earth orbit.
- Space Force modernization:Department of Defense satellite servicing initiatives are creating procurement channels for neural network-enabled rendezvous and proximity operations systems.
- Reinforcement learning convergence:Advances in terrestrial autonomous vehicle algorithms are transferable to spacecraft trajectory optimization, enabling technology spillover from automotive and aviation sectors.
Industry Challenges
- Flight software certification timelines:FAA commercial launch licensing and NASA mission assurance requirements impose parallel validation tracks for AI-enabled smallsat constellations, stretching engineering resources.
- Cross-border data processing fragmentation:Emerging national space laws in multiple jurisdictions are creating compliance complexity for satellite operators with globally distributed ground stations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Space Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $17.27 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Satellite Imaging, Space Exploration, Orbital Debris Management, Space Traffic Control, Planetary Research, Astrobiology Technology: Machine Learning, Neural Networks, Computer Vision, Natural Language Processing, Reinforcement Learning, Expert Systems End User: Space Agencies, Aerospace Manufacturers, Research Institutes, Satellite Operators, Telemetry Providers, Launch Service Companies Deployment: Onboard Systems, Ground Stations, Cloud Platforms, Edge Computing, Hybrid Solutions, Data Centers |
| Companies Covered | SpaceX, NASA, Lockheed Martin Corporation, Northrop Grumman Corporation, Boeing, Airbus Defense and Space, Blue Origin, Maxar Technologies, Planet Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Space Market Trends and Innovations
Neural network deployment patterns are bifurcating between edge-native orbital processing and ground-based inference, with hardware-software co-design emerging as the critical capability differentiator for payload suppliers.
Reinforcement learning for spacecraft autonomy is automating trajectory optimization and fault recovery sequences previously requiring continuous ground control intervention. Satellite operators in the United States and Europe are accelerating procurement of these systems to reduce station-keeping costs and extend operational lifespans. This compression of ground dependency is automating mission control staffing models and shifting value capture toward onboard compute hardware.
The EU AI Act's algorithmic transparency mandates are imposing documentation burdens on vendors selling autonomous decision-making systems into European satellite programs. Industrial consequence includes restructuring of vendor qualification requirements, with emphasis on explainability frameworks for orbital machine learning models. Smallsat constellation operators targeting European government contracts are most affected, responding by integrating European payload suppliers with established compliance infrastructure.
Buyer concentration among national space agencies and defense departments is compressing procurement cycles and unbundling traditional integrated service contracts. Prime contractors are responding by disaggregating AI software licenses from hardware payloads, enabling direct vendor relationships with satellite operators. This pattern is most visible in United States Department of Defense programs, where Space Force acquisition reform is enabling software-defined payload upgrades independent of bus procurement.
Artificial Intelligence in Space Market Segmentation
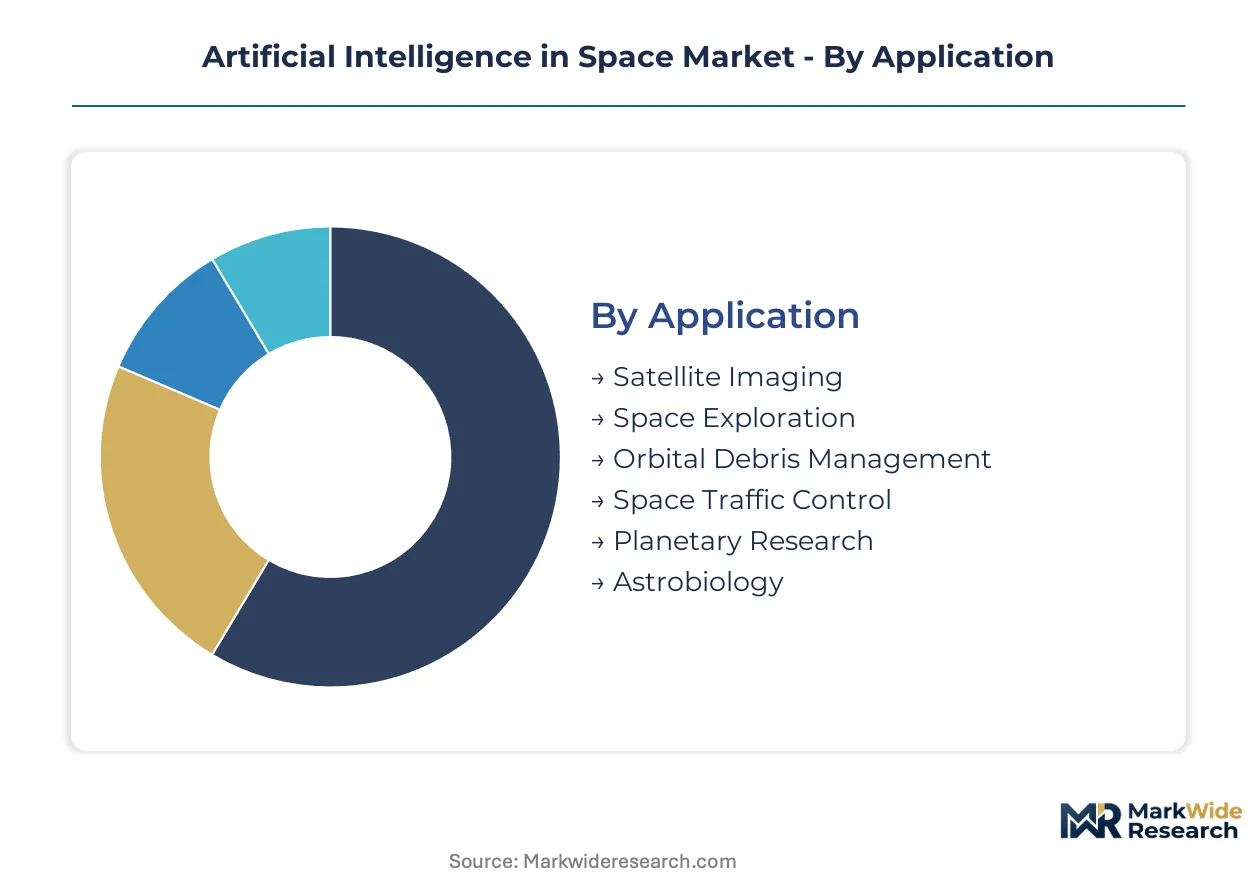
Artificial Intelligence in Space Market segmentation reveals how certification burdens, deployment architectures, and end-user procurement power concentrate value across distinct technology-application pairings. Understanding these partitions exposes where NASA TRL validation, EU AI Act compliance, and radiation-hardening requirements create divergent margin structures for payload suppliers.
Application:
Satellite Imaging and Orbital Debris Management carry the heaviest certification loads, requiring FAA commercial launch licensing plus NASA mission assurance for flight-qualified neural networks, while Astrobiology faces lighter algorithmic transparency mandates under current EU AI Act interpretations.
- Satellite Imaging:Earth observation constellations deploy convolutional neural networks for real-time feature extraction and change detection. Demand clusters with United States commercial operators and European government programs seeking autonomous tasking capabilities. NASA's Artemis program is pulling forward procurement of flight-qualified models for lunar surface mapping.
- Orbital Debris Management:Collision avoidance systems process radar and optical sensor feeds through onboard machine learning for maneuver planning without ground intervention. Low-Earth orbit congestion is compelling hardware refresh cycles across commercial constellations. EU AI Act documentation requirements favor established vendors with classified heritage.
- Space Exploration:Autonomous navigation for crewed and robotic missions beyond Earth orbit.
- Space Traffic Control:Coordination algorithms for constellation density management and conjunction assessment.
- Planetary Research:Spectral analysis and terrain classification for unmanned surface missions.
- Astrobiology:Pattern recognition for biosignature detection in spectroscopic data.
Leading the category by volume: Satellite Imaging. Growing fastest: Orbital Debris Management.
Technology:
Cost tiers separate radiation-tolerant implementations from terrestrial-adapted stacks, with Reinforcement Learning commanding premium pricing for spacecraft autonomy while Expert Systems occupy legacy maintenance contracts at compressed margins.
- Reinforcement Learning:Trajectory optimization and fault recovery sequences automate sequences previously requiring continuous ground control. Space Force modernization initiatives are creating procurement channels for neural network-enabled rendezvous systems. Technology spillover from automotive autonomous vehicles is accelerating algorithm development.
- Machine Learning:Supervised and unsupervised methods for sensor data classification and anomaly detection aboard orbital platforms. Satellite operators across North America and Europe are accelerating procurement to reduce station-keeping costs. NASA TRL validation timelines compress margins for vendors without amortized heritage.
- Neural Networks:Deep learning architectures for image processing and predictive maintenance.
- Computer Vision:Object detection and tracking for proximity operations and docking maneuvers.
- Natural Language Processing:Voice and text interfaces for astronaut-assistive systems.
- Expert Systems:Rule-based diagnostics for legacy spacecraft with deterministic failure modes.
Highest margin capture: Reinforcement Learning. Steepest volume expansion: Machine Learning.
End User:
Procurement concentration among national space agencies and defense departments is compressing cycles and unbundling traditional integrated service contracts, with Space Agencies and Satellite Operators driving divergent specification requirements.
- Space Agencies:NASA, ESA, and national programs demand flight-proven systems with complete documentation trails. NASA's technology readiness level standards enforce rigorous validation protocols. EU AI Act compliance is restructuring vendor qualification for European satellite programs.
- Satellite Operators:Commercial constellation managers prioritize cost-per-bit optimization and autonomous operations to minimize ground segment overhead. SmallSat operators face parallel FAA and NASA validation tracks stretching engineering resources. Cloud platform entrants are commoditizing terrestrial AI processing for downlink data.
- Aerospace Manufacturers:Prime contractors integrating AI payloads into bus and instrument packages.
- Research Institutes:Academic and government laboratories advancing algorithmic frontiers without flight qualification burdens.
- Telemetry Providers:Ground-station operators adding value through data processing and distribution.
- Launch Service Companies:Providers optimizing manifest allocation and trajectory planning.
Dominant procurement volume: Space Agencies. Fastest contract cycle compression: Satellite Operators.
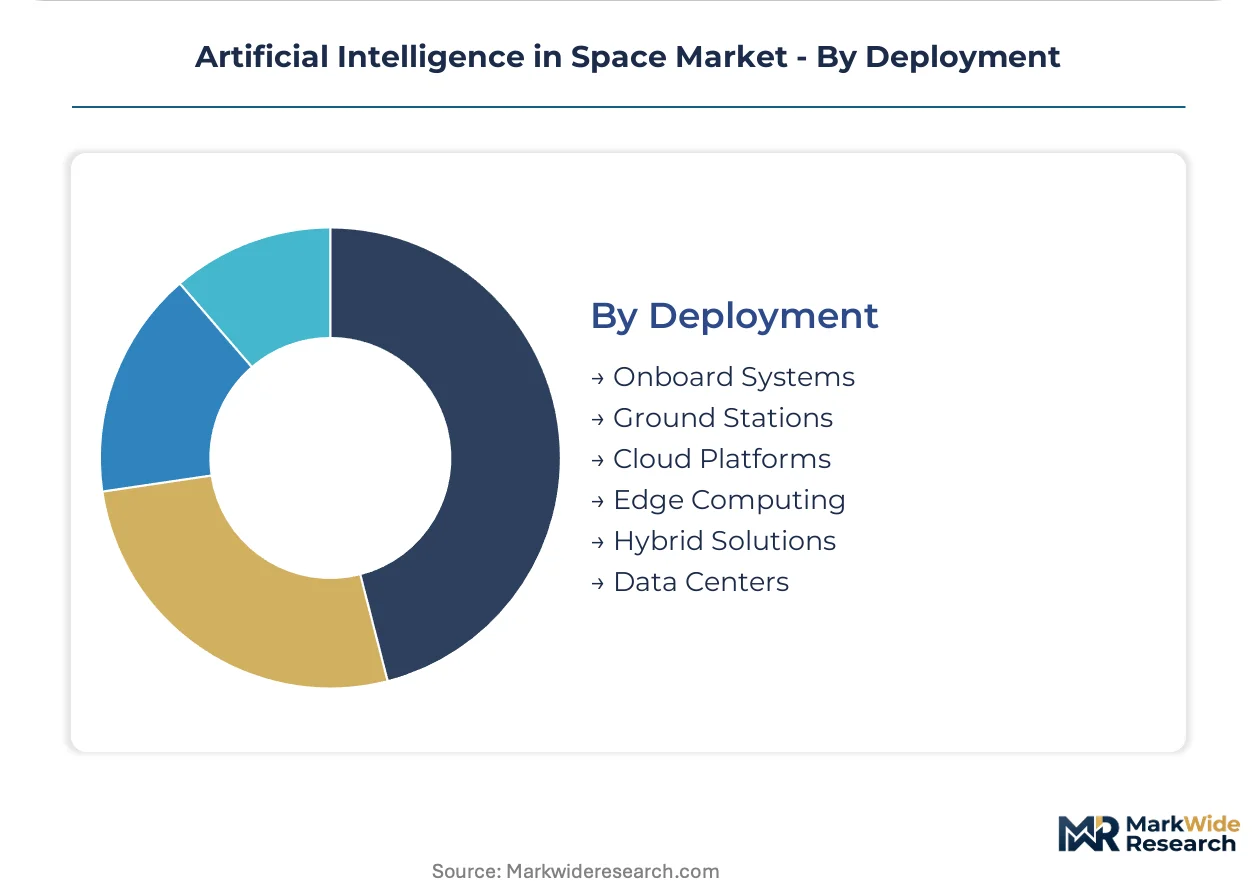
Deployment:
Margin pools concentrate at the hardware-software interface for orbital deployments while ground-based processing faces commoditization from cloud entrants, with Hybrid Solutions capturing integration premiums.
- Onboard Systems:Radiation-hardened processors executing inference at the sensor edge with sub-watt to multi-kilowatt budgets. Foundry capacity bottlenecks concentrate supply among defense-tier semiconductor suppliers. Value migration toward orbital autonomy stacks is automating mission control staffing models.
- Edge Computing:Distributed processing architectures aboard satellite constellations enabling real-time decision-making. Latency constraints measured in milliseconds for low-Earth orbit drive hardware-software co-design requirements. Edge deployments compress pricing power for traditional ground-segment providers.
- Ground Stations:Terrestrial facilities for downlink processing and model training.
- Cloud Platforms:Hyperscale infrastructure for batch inference and dataset curation.
- Hybrid Solutions:Split architectures partitioning training and inference across orbital and terrestrial nodes.
- Data Centers:Centralized facilities for archival storage and retrospective analysis.
Highest value capture: Onboard Systems. Fastest commoditization pressure: Ground Stations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spaceport tax incentives and orbital launch licensing zones in the United States are concentrating AI payload development along coastal corridors. Satellite operators and defense contractors cluster near FAA-licensed facilities and NASA centers. Regulatory frameworks in Europe and Asia are fragmenting procurement patterns for autonomous space systems.
United States
NASA's Artemis program and Space Force modernization are pulling forward procurement of flight-qualified neural networks for lunar and orbital operations. FAA commercial launch licensing streamlines smallsat constellation approvals while imposing parallel validation tracks. The California-Florida corridor anchors development, with Hawthorne and Cape Canaveral housing integrated design-to-launch facilities for autonomous spacecraft.
France
Airbus Defense and Space leverages Toulouse-based manufacturing heritage to supply ESA programs with orbital AI payloads. EU AI Act algorithmic transparency mandates are restructuring vendor qualification for European satellite procurement. The Occitanie region concentrates subcontractors specializing in radiation-hardened processor integration for autonomous navigation systems.
Germany
Deutsche Bahn and automotive autonomy spillover are accelerating reinforcement learning research transferable to spacecraft trajectory optimization. ESA mission assurance requirements enforce rigorous documentation trails for flight-qualified machine learning models. Bavaria's Munich-Stuttgart corridor hosts precision engineering suppliers feeding into satellite servicing architectures.
United Kingdom
Surrey Satellite Technology and emerging launch sites in Scotland are creating demand for edge computing payloads in smallsat constellations. UK Space Agency funding prioritizes autonomous debris tracking systems for low-Earth orbit congestion management. Harwell Science Campus anchors R&D concentration for orbital AI applications targeting commercial Earth observation.
Japan
METI's space industry revitalization roadmap is channeling investment into onboard autonomy for lunar exploration missions. JAXA technology readiness level standards compress procurement cycles for domestic satellite operators. Tokyo-Osaka industrial corridors concentrate precision electronics manufacturers supplying radiation-tolerant components for AI inference at the orbital edge.
Artificial Intelligence in Space Market Competitive Landscape
United States producers anchor the prime contractor tier; European specialists hold subsystem and payload integration positions. Market structure bifurcates between classified heritage suppliers serving national security programs and commercial constellation operators pursuing cost-optimized autonomy stacks. Strategic archetypes include defense-tier integrators with amortized flight qualification, commercial pure-plays leveraging terrestrial AI spillover, and emerging launch-service providers vertically integrating into payload software. Dominant competitive moves center on disaggregating software licenses from hardware procurement and securing foundry capacity for radiation-hardened semiconductors.
Within the classified heritage tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify vendors with decades of flight-proven documentation trails satisfying NASA and Space Force mission assurance requirements. Boeing occupies a position bridging defense and commercial procurement channels, extending terrestrial aviation autonomy stacks into spacecraft domains. These three anchors represent how vendor qualification barriers under EU AI Act and NASA technology readiness level standards concentrate contract awards among suppliers with amortized validation infrastructure.
| Leading Market Players |
|---|
| SpaceX |
| NASA |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| Boeing |
| Airbus Defense and Space |
| Blue Origin |
| Maxar Technologies |
| Planet Labs |
| Others |
Pricing and Supply Chain Analysis
Radiation-hardening certification under NASA's technology readiness level standards gates both qualified semiconductor supply and premium-tier pricing access for AI payload manufacturers, compressing margins for vendors without amortized flight heritage while concentrating pricing power among defense-tier foundry partners.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited procurement of flight-qualified neural networks from discounted spot inventory of terrestrial-adapted stacks. Three-tier pricing structure across radiation-hardened premium, mission-assured standard, and commercial-off-the-shelf economy levels reflects certification depth and documentation completeness. Cost compression in the economy tier intensifies because cloud platform entrants commoditize ground-station AI services. Satellite operators exhibit highest price sensitivity, while Space Agencies accept premium positioning for validated autonomous systems.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Space Force modernization programs, while specialized distributors serve smallsat constellation operators with lower volume requirements. Foundry capacity concentrates in the United States, France, and Japan for radiation-hardened processors. Supply draws from gallium arsenide substrates, cobalt-60 radiation testing facilities, and ceramic packaging substrates. Single-source vulnerability runs through defense-qualified semiconductor fabrication lines. Distribution runs through prime contractor integration hubs co-located with FAA-licensed spaceports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reinforcement learning for spacecraft autonomy is displacing rule-based expert systems across trajectory optimization and fault recovery applications, compressing the window for legacy stack maintenance revenues.
For Market Incumbents: Extend classified documentation trails into EU AI Act compliance frameworks to defend European procurement access against emerging commercial pure-plays. Secure captive foundry capacity for radiation-hardened processors through long-term offtake agreements with defense-tier suppliers, as semiconductor scarcity threatens margin stability. For New Entrants and Emerging Players: FAA streamlined commercial launch regulations in the United States open a window for AI-enabled smallsat constellations to bypass traditional prime contractor channels. Target orbital debris management applications for commercial constellation operators facing hardware refresh cycles, leveraging terrestrial autonomous vehicle algorithm spillover to accelerate development timelines. For Investors and Strategic Acquirers: Space Force software-defined payload acquisition reform is the leading indicator that hardware-software disaggregation will concentrate value capture at the edge computing interface. Position for five-to-ten year exposure through specialists with radiation-hardened processor integration capabilities and validated NASA technology readiness level documentation. Watch for cislunar infrastructure contract awards as the inflection signal for beyond-Earth-orbit capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Radiation-Hardened Processor Supply Agreement | Lockheed Martin and Northrop Grumman anchor procurement through defense-tier foundry partnerships. |
| EU AI Act Compliance Certification | Airbus Defense and Space leverages Toulouse documentation infrastructure for European satellite programs. |
| Reinforcement Learning Platform Integration | Boeing extends terrestrial aviation autonomy stacks into NASA Artemis lunar navigation systems. |
| Edge Computing Hardware-Software Co-Design | SpaceX vertical integration captures margin pools at the orbital inference layer. |
| Geographic Expansion to Cislunar Infrastructure | Blue Origin positions for autonomous logistics beyond Earth orbit where no incumbent holds validated supply. |
Research Methodology
NASA technology readiness level documentation databases, ESA mission assurance filings, and FAA commercial launch licensing records formed the secondary backbone for validation. Primary interviews with satellite program directors, radiation-hardened semiconductor procurement leads, and Space Force acquisition officers combined with secondary source triangulation. Bottom-up modeling of AI payload unit economics and top-down reconciliation against agency budget appropriations anchored value estimates.
Historical trendline analysis of neural network flight qualification timelines informed projection frameworks across the modeling period. Segmentation dimensions modeled include application type, technology architecture, end-user procurement channel, and deployment topology. CAGRs derived from fitted growth curves adjusted for technology readiness level validation bottlenecks and foundry capacity constraints. Inputs incorporated Artemis program procurement schedules and EU AI Act implementation timelines.
The model assumes a particular technology adoption path for reinforcement learning deployment; alternative pathways for supervised learning would alter the outlook for ground-station service demand. Forecasts incorporate assumptions regarding radiation-hardened processor yield rates and debris tracking mandate enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace & Defense AI
Global Artificial Intelligence (AI) Defence Market
Aerospace & Defense AI
AI in Modern Warfare Market
Aerospace & Defense AI
Linear Particle Accelerators Market
Aerospace & Defense AI
AI in Military Market
Aerospace & Defense AI
Global Artificial Intelligence and Analytics in Defense Market
Aerospace & Defense AI
Aerospace and Defence MLCC Market
Aerospace & Defense AI
Aerospace TIC Market
Aerospace & Defense AI
Artificial Intelligence and Robotics in Aerospace and Defense Market
Aerospace & Defense AI
Artificial Intelligence in Aviation Market
Aerospace & Defense AI
Mexico Aerospace Market
Aerospace & Defense AI
Virtual Reality in Aerospace and Defense Market
Aerospace & Defense AI
Stealth Technology Market
Aerospace & Defense AI
Aerospace Consulting Services Market
Aerospace & Defense AI
Aerospace Accumulator Market
Aerospace & Defense AI
AI in Defense Market
Aerospace & Defense AI
Global Military Artificial Intelligence (AI) Market