
 Military Autonomous Robot Market | 2026-2036
Military Autonomous Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Military Autonomous Robot Market Insights
Aftermarket service revenue for autonomous platform fleets is narrowing as original equipment manufacturers shift toward bundled lifecycle contracts. Northrop Grumman Corporation leverages its integrated logistics networks to capture recurring sustainment value across naval drone programs. Lockheed Martin Corporation anchors its position through classified R&D pipelines targeting next-generation collaborative autonomy. Elbit Systems Ltd. specializes in terrain-adaptive navigation suites that reduce operator cognitive load during contested operations.
Military autonomous robots are self-directed weapons platforms integrating LiDAR, thermal imaging, and edge-computing processors to execute missions without continuous human control across ground, air, and maritime domains. Unmanned Aerial Vehicles dominate current procurement volumes due to mature supply chains and proven ISR utility, while Swarm Robotics configurations represent the fastest-expanding autonomy category as militaries test distributed coordination algorithms. Defense Forces remain the primary end-user segment, though Border Patrol Units are emerging as a distinct demand channel for perimeter surveillance applications.
The US Department of Defense's autonomous weapons directive and NATO's emerging AI governance framework shape certification requirements for lethal autonomous systems, constraining market access for non-compliant vendors. Israel's Ministry of Defense and the UK Ministry of Defence operate parallel review processes for operational deployment authority, creating a fragmented regulatory landscape that favors contractors with multi-jurisdictional compliance expertise. Stakeholders must monitor evolving rules of engagement protocols and export control harmonization between allied defense ministries to anticipate procurement eligibility shifts.
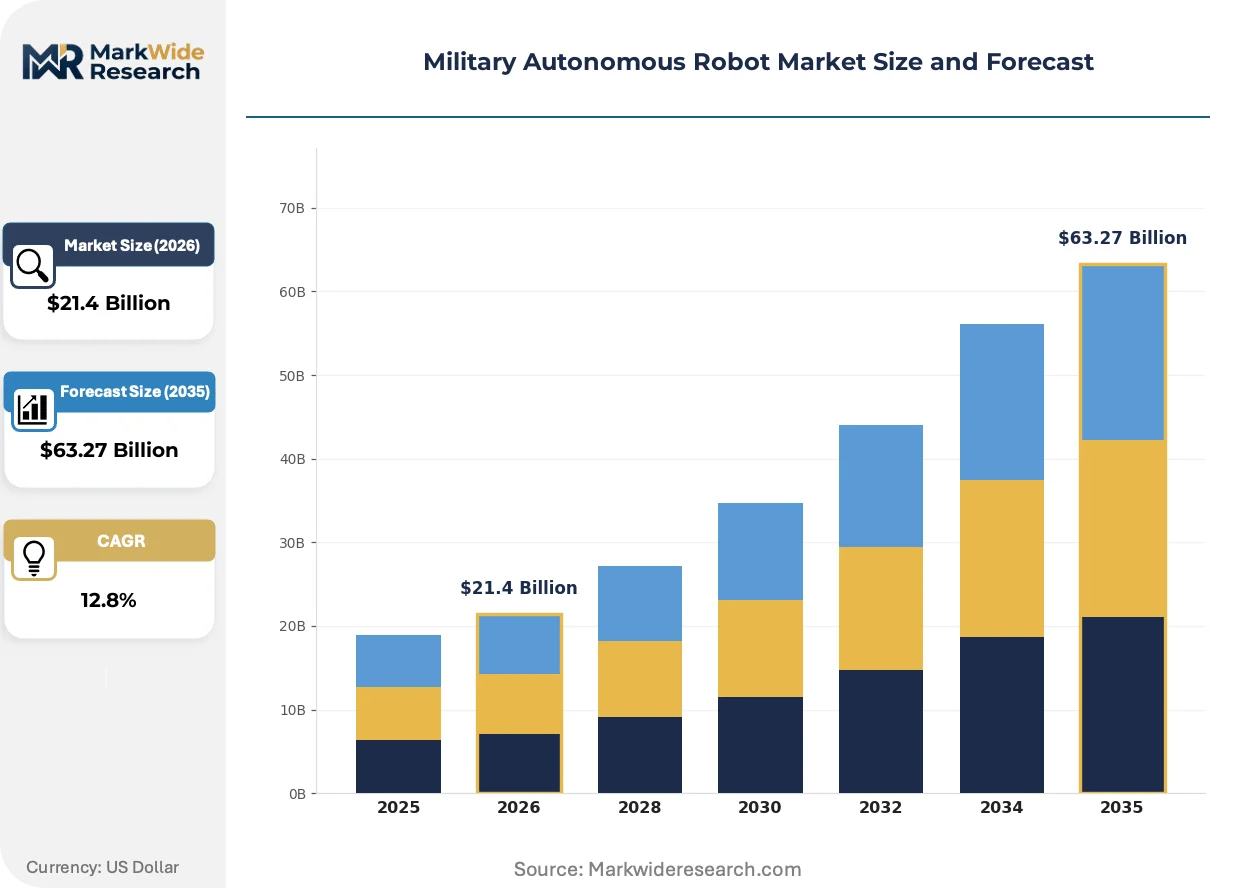
Market Dynamics
Defense ministries are consolidating procurement authority under centralized AI governance offices, compressing vendor qualification timelines while elevating algorithmic transparency requirements above hardware specifications.
Growth Catalysts
- NATO AI Governance Framework:Allied defense ministries are harmonizing certification protocols for lethal autonomous systems, creating cross-border procurement eligibility for compliant contractors.
- Swarm Robotics:Distributed coordination algorithms enable saturation attacks with reduced unit costs, attracting special operations commands seeking force multiplication.
- Israeli Defense Procurement:The Ministry of Defense's accelerated operational deployment authority for terrain-adaptive navigation suites is validating autonomous ground platforms in contested environments.
Market Restraints
- Export Control Fragmentation:Non-harmonized munitions lists between the US State Department and UK Export Control Organisation create compliance duplication for dual-use autonomy components.
- LiDAR Supply Concentration:Military-grade sensor production clusters in specific East Asian manufacturing hubs expose programs to single-source vulnerability.
- Edge Processor Thermal Limitations:Current silicon architectures constrain sustained computational throughput in desert and arctic operating conditions.
Strategic Opportunities
- UK Border Patrol Modernization:The Home Office's perimeter surveillance procurement pipeline represents a distinct demand channel separate from defense ministry acquisition streams.
- Maritime Mine Countermeasures:Naval forces are substituting autonomous underwater vehicles for crewed minehunters, opening vessel-class displacement opportunities.
- US DoD Autonomous Weapons Directive:Updated guidelines mandate human-machine teaming protocols, creating retrofit and upgrade revenue for existing platform fleets.
Industry Challenges
- AI Ethics Review Bottlenecks:Multi-layered approval chains for lethal decision algorithms extend program development cycles beyond traditional hardware timelines.
- Legacy System Integration:C4ISR architectures designed for remotely piloted systems require middleware redevelopment to accommodate full autonomy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Autonomous Robot Market |
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $63.27 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Unmanned Ground Vehicles, Unmanned Aerial Vehicles, Unmanned Sea Vehicles, Hybrid Systems Autonomy Level: Remote Controlled, Semi-Autonomous, Fully Autonomous, Swarm Robotics Application: Reconnaissance, Surveillance, Combat Support, Rescue Operations End User: Defense Forces, Border Patrol Units, Special Operations Groups, Defense Contractors |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, General Dynamics Corporation, BAE Systems, Thales Group, Elbit Systems Ltd., Israel Aerospace Industries Ltd., AeroVironment Inc., Saab AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Autonomous Robot Market Trends and Innovations
Autonomous warfare architectures are converging around distributed decision-making nodes rather than centralized command hierarchies, compressing engagement timelines while complicating accountability structures.
Multi-spectral sensor fusion is hybridizing electro-optical, thermal, and synthetic aperture radar inputs into unified threat detection pipelines. Special operations commands in the United States and Israel are field-testing these integrated perception stacks for denied-area reconnaissance. The technology is hybridizing platform design requirements, forcing airframe and ground vehicle architects to standardize around common data bus architectures rather than mission-specific sensor pods.
The EU AI Act's risk classification framework for autonomous weapons systems is creating extraterritorial compliance obligations for non-EU contractors seeking NATO interoperability certification. Defense procurement offices in France and Germany are incorporating these algorithmic audit requirements into national tender specifications. Naval drone programs face the steepest compliance burden due to extended deployment durations that exceed standard review cycles.
Service contract unbundling is fragmenting traditional bundled lifecycle agreements into discrete software update, hardware sustainment, and training modules. Original equipment manufacturers are resisting this decomposition while systems integrators capture margin from modular service tiers. The UK Ministry of Defence's Fleet Solid Support program exemplifies this tension, with autonomy subsystem vendors negotiating separate liability frameworks from prime contractors.
Military Autonomous Robot Market Segmentation
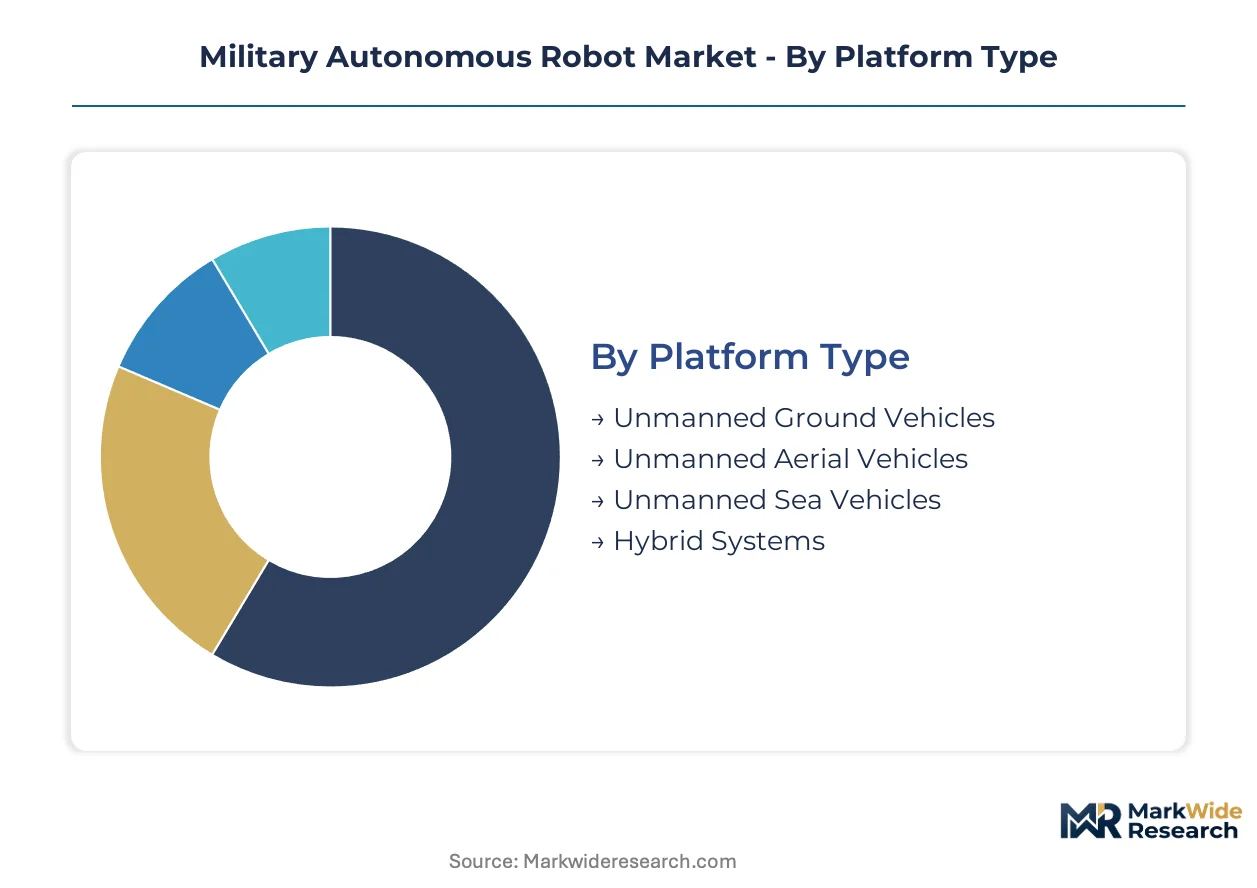
Military autonomous robot segmentation reveals how procurement priorities diverge between proven platforms and experimental architectures. Defense ministries allocate budgets across maturity tiers, balancing operational reliability against transformative capability.
Platform Type:
Maturity spans established aerial supply chains to experimental maritime architectures.
- Unmanned Aerial Vehicles:Fixed-wing and rotary-wing configurations dominate current procurement volumes through mature ISR integration and proven beyond-line-of-sight communication protocols. The United States and Israel concentrate demand for persistent surveillance missions requiring extended loiter times.
- Unmanned Ground Vehicles:Tracked and wheeled platforms execute route clearance, logistics transport, and direct fire support in contested terrain. Israeli Defense Forces validate terrain-adaptive navigation suites in urban warfare conditions, accelerating operational deployment authority for ground autonomy.
- Unmanned Sea Vehicles:Surface and underwater craft perform mine countermeasures and anti-submarine warfare with reduced crew exposure.
- Hybrid Systems:Cross-domain platforms transition between aerial and ground modes for denied-area insertion missions.
Unmanned Aerial Vehicles retain volume leadership; Hybrid Systems hold the steepest expansion curve.
Autonomy Level:
Cost tiers separate human-dependent systems from algorithm-intensive architectures requiring extensive certification investment.
- Remote Controlled:Operator-tethered platforms maintain continuous data link for direct command execution with minimal onboard decision processing. Budget-constrained defense forces in Eastern Europe prioritize these systems to avoid AI governance compliance costs.
- Fully Autonomous:Self-directed systems execute mission profiles without human intervention using edge-computing processors and multi-spectral sensor fusion. The US Department of Defense's updated autonomous weapons directive mandates human-machine teaming protocols, constraining full autonomy deployment to non-lethal support roles.
- Semi-Autonomous:Human-on-the-loop architectures blend operator oversight with automated waypoint navigation and threat detection.
- Swarm Robotics:Distributed coordination algorithms enable saturation tactics through collective behavior without centralized command.
Remote Controlled systems retain volume leadership; Swarm Robotics holds the steepest expansion curve.
Application:
Customer mission profiles determine sensor payload requirements and rules of engagement complexity.
- Reconnaissance:Deep-penetration platforms collect signals intelligence and imagery across denied territories using low-observable propulsion and passive sensing arrays. United Kingdom Special Operations Groups field these systems for pre-assault area familiarization.
- Combat Support:Armed platforms deliver precision effects including direct fire, electronic attack, and logistics resupply under human authorization frameworks. Israeli Ministry of Defense procurement prioritizes these applications for urban combat force multiplication.
- Surveillance:Persistent monitoring systems secure borders and critical infrastructure through automated pattern recognition.
- Rescue Operations:Personnel recovery platforms navigate hazardous environments to extract casualties without risking additional crew.
Reconnaissance retains volume leadership; Combat Support holds the steepest expansion curve.
End User:
Procurement authority fragmentation creates distinct qualification pathways across defense ministry and civilian security hierarchies.
- Defense Forces:National military services operate the largest fleet concentrations with classified requirements driving custom platform development. NATO member states harmonize certification protocols, creating cross-border procurement eligibility for compliant autonomy vendors.
- Border Patrol Units:Civilian security agencies deploy perimeter surveillance systems with reduced lethality constraints and faster acquisition timelines. UK Home Office modernization programs represent a distinct demand channel separate from defense ministry streams.
- Special Operations Groups:Elite units field experimental architectures for denied-area missions requiring rapid technology refresh cycles.
- Defense Contractors:Private military companies and system integrators acquire platforms for training, testing, and subcontracted operational support.
Defense Forces retain volume leadership; Border Patrol Units hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries deploy autonomous systems through fundamentally different acquisition frameworks, with some prioritizing rapid operational validation while others emphasize multi-year certification protocols.
United States
The Department of Defense channels procurement through centralized AI governance offices that compress vendor timelines while elevating algorithmic transparency requirements. The updated autonomous weapons directive mandates human-machine teaming protocols, constraining full autonomy deployment to non-lethal support roles. Defense contractors in the Washington DC-Virginia corridor concentrate classified R&D pipelines targeting next-generation collaborative autonomy.
Israel
The Ministry of Defense accelerates operational deployment authority for terrain-adaptive navigation suites, validating autonomous ground platforms in urban warfare conditions. Parallel review processes for lethal autonomous systems create distinct certification pathways favoring contractors with multi-jurisdictional compliance expertise. Haifa and Tel Aviv host specialized clusters developing multi-spectral sensor fusion for denied-area reconnaissance.
United Kingdom
The Ministry of Defence operates fragmented procurement streams between defense ministry acquisition and Home Office border patrol modernization programs. Fleet Solid Support program negotiations exemplify service contract unbundling, with autonomy subsystem vendors negotiating separate liability frameworks from prime contractors. London and the Southeast concentrate systems integrators capturing margin from modular service tiers.
Germany
The Defense Ministry incorporates EU AI Act algorithmic audit requirements into national tender specifications, creating extraterritorial compliance obligations for NATO interoperability certification. Naval drone programs face the steepest compliance burden due to extended deployment durations exceeding standard review cycles. Munich and Stuttgart host industrial clusters developing middleware for legacy C4ISR architecture integration.
France
The Direction Générale de l'Armement classifies autonomous weapons systems under EU AI Act risk frameworks, mandating documentation trails for lethal decision algorithms. Procurement offices prioritize swarm robotics configurations for saturation tactics with reduced unit costs. Toulouse and Paris-Saclay concentrate aerospace contractors adapting distributed coordination algorithms for collaborative autonomy.
Military Autonomous Robot Market Competitive Landscape
Capability concentration sits with specialized autonomy developers; scale advantage sits with diversified defense primes. The vendor base organizes into three tiers: integrated primes with classified R&D pipelines, mid-tier specialists in terrain-adaptive navigation or sensor fusion, and emerging swarm coordination vendors. Strategic moves center on bundled lifecycle contracts displacing aftermarket service revenue, and middleware redevelopment for legacy system integration.
Within the integrated prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify divergent positioning. Northrop Grumman leverages integrated logistics networks to capture recurring sustainment value, while Lockheed Martin anchors its position through classified R&D pipelines. Elbit Systems Ltd. occupies a specialist position in terrain-adaptive navigation suites that reduce operator cognitive load during contested operations.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| General Dynamics Corporation |
| BAE Systems |
| Thales Group |
| Elbit Systems Ltd. |
| Israel Aerospace Industries Ltd. |
| AeroVironment Inc. |
| Saab AB |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on military-grade LiDAR production clusters in East Asian manufacturing hubs compresses pricing power for Western integrators while amplifying vulnerability premiums across procurement tiers. Defense ministries respond with long-term offtake commitments that lock in supply priority but sacrifice flexibility, creating a bifurcated market where bundled lifecycle contracts command premium positioning against spot-market component purchasing.
Pricing Analysis
Long-term offtake agreements dominate procurement for high-assurance programs, while spot-market sourcing persists for experimental swarm robotics configurations. Three-tier pricing structure across premium certified, standard compliant, and economy remote-controlled tiers reflects algorithmic transparency audit costs and NATO AI Governance Framework compliance investment. Cost compression in the economy tier intensifies as Eastern European defense forces prioritize operator-tethered platforms to avoid certification overhead. Border Patrol Units exhibit highest price sensitivity due to civilian budget constraints, while US Special Operations Groups absorb premium positioning for denied-area mission requirements.
Supply Chain Analysis
US State Department and UK Export Control Organisation dual-use technology restrictions fragment component flows across allied defense programs. Military-grade edge processor fabrication concentrates in Taiwan, South Korea, and the United States, while thermal imaging sensor assembly clusters in Israel and the United Kingdom. Production draws from gallium arsenide substrates, synthetic aperture radar modules, and radiation-hardened silicon architectures. Single-source vulnerability in East Asian LiDAR manufacturing exposes programs to geopolitical disruption. Distribution runs through prime contractor integration facilities rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a defense procurement upswing cycle driven by NATO member state swarm robotics investment, rewarding contractors with multi-jurisdictional compliance infrastructure.
For Market Incumbents: Insulate core revenue through captive supply arrangements for military-grade LiDAR and edge processors, reducing exposure to export control fragmentation. Deepen backward integration into terrain-adaptive navigation software development to capture margin from modular service unbundling. Lockheed Martin Corporation and Northrop Grumman Corporation exemplify this defensive posture through classified R&D pipeline control. For New Entrants and Emerging Players: Establish a beachhead in UK Border Patrol Unit perimeter surveillance procurement, where civilian acquisition timelines bypass defense ministry certification bottlenecks. Target maritime mine countermeasures autonomy subsystems for naval forces substituting crewed minehunters. Pursue joint development agreements with systems integrators rather than prime contractor competition to navigate fragmented liability frameworks. For Investors and Strategic Acquirers: The market sits at a capability consolidation phase that favors mid-tier specialists with terrain-adaptive navigation or multi-spectral sensor fusion expertise. Long-term viability hinges on algorithmic audit infrastructure investment across the projection horizon. Acquisition target archetype: Israeli or UK-based autonomy developers with existing NATO interoperability certification. The signal to watch is harmonization progress between the US DoD autonomous weapons directive and EU AI Act risk classification frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Middleware Redevelopment for Legacy C4ISR Integration | Enables full autonomy protocol accommodation in existing command architectures without greenfield replacement. |
| Algorithmic Audit Infrastructure Investment | Satisfies EU AI Act extraterritorial compliance obligations for NATO interoperability certification eligibility. |
| Multi-Jurisdictional Compliance Certification | Unlocks cross-border procurement eligibility across US DoD, Israeli Ministry of Defense, and UK Ministry of Defence review processes. |
| Bundled Lifecycle Contract Positioning | Captures recurring sustainment value as aftermarket service revenue narrows toward OEM-integrated offerings. |
| Swarm Coordination Algorithm Development | Addresses special operations command demand for saturation tactics with reduced unit costs and distributed resilience. |
Research Methodology
The analysis maps unmanned aerial, ground, maritime, and hybrid platform sub-sectors, each validated through program managers at defense ministries, autonomy subsystem engineers, procurement officers at border patrol agencies, and prime contractor integration leads. Primary interview findings triangulate against NATO cooperative cyber defense center reports, US DoD budget justification documents, UK Defence and Security Equipment International exhibition filings, and Israeli Ministry of Defense operational deployment authority records. Bottom-up platform shipment aggregation reconciles with top-down defense expenditure allocation analysis.
Assumption sets held procurement authority consolidation under centralized AI governance offices as fixed across the modeling period, while varying swarm robotics operational validation timelines by national defense ministry. Segmentation dimensions include platform type, autonomy level, application mission profile, and end-user procurement hierarchy. CAGRs derive from defense budget trajectory analysis weighted by platform replacement cycle timing and algorithmic certification pipeline throughput. Edge processor thermal performance curves and LiDAR unit cost trajectories inform hardware cost modeling.
Stress conditions across export control harmonization progress, EU AI Act enforcement intensity, and East Asian manufacturing hub geopolitical stability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NATO AI Governance Framework adoption velocity and US DoD human-machine teaming protocol implementation scope. Material shifts in Israeli operational deployment authority acceleration or UK Home Office border patrol budget reallocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
Aerospace Robotics Market
Unmanned Systems
Drone Detection Optical Systems Market
Unmanned Systems
Space and Space Station Robotics Market
Unmanned Systems
Global Remote Firing System Market
Unmanned Systems
Unmanned Composites Market
Unmanned Systems
Autonomous Aircraft Market
Unmanned Systems
North America AUV Market
Unmanned Systems
Tethered Drone System Market
Unmanned Systems
Europe Unmanned Surface Vehicle (USV) Market
Unmanned Systems
North America ROV Market
Unmanned Systems
Unmanned Underwater Vehicles (UUV) Market
Unmanned Systems
Low-Noise Drone Propulsion Systems Market
Unmanned Systems
Unattended Ground Sensors (UGS) Market
Unmanned Systems
Dismounted Soldier Systems Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
Asia-Pacific Unmanned Surface Vehicle (USV) Market