
 North America Spacesuit Market | 2026-2036
North America Spacesuit Market Size, Share, and Industry Trends Forecast 2026-2036
North America Spacesuit Market Analytics
The FAA's updated commercial astronaut safety regulations is recalibrating the cost-of-entry calculus for new spacesuit vendors. ILC Dover, LP leverages decades of extravehicular suit heritage to sustain its position in government procurement cycles. Axiom Space, Inc. anchors its strategy in private orbital station construction, competing directly with legacy aerospace suppliers. Space Exploration Technologies Corp. dominates through vertical control over launch-to-suit ecosystem integration.
A spacesuit constitutes a self-contained anthropomorphic spacecraft engineered to sustain human life in the vacuum of space, incorporating multilayer thermal micrometeoroid garments, closed-loop life support with carbon dioxide scrubbing, and differential pressure containment at approximately 4.3 psi. Its primary commercial purpose is enabling crewed extravehicular activity, intravehicular emergency protection, and high-fidelity astronaut training for orbital and cislunar operations. Extravehicular suits command the dominant share of program value due to their complexity and low production volumes, while intravehicular configurations represent a mature segment with replacement-driven demand. Life support systems technology absorbs disproportionate engineering investment as oxygen regeneration and thermal regulation capabilities determine mission duration limits.
NASA's technical standards, the FAA's commercial space launch regulations, and OSHA workplace exposure guidelines collectively shape product certification pathways and operational liability frameworks for North American manufacturers. These requirements elevate non-recurring engineering costs and extend qualification timelines, filtering market access to capital-intensive participants. Stakeholders must monitor how NASA's lunar Gateway procurement architecture reallocates suit development risk between prime contractors and subsystem specialists.
Market Dynamics
NASA's Artemis procurement architecture is redistributing development risk from prime contractors to subsystem specialists, forcing legacy aerospace suppliers to restructure their supplier relationships and cost accounting methodologies.
Growth Catalysts
- Artemis Lunar Surface Operations:NASA's expanded extravehicular activity requirements for cislunar missions are pulling advanced life support development forward. The Gateway station construction timeline accelerates suit qualification cycles.
- FAA Commercial Crew Certification:Tightening safety standards for private astronaut flights are mandating redundant life support architectures. This elevates technical barriers and filters vendor participation toward capitalized incumbents.
- Texas Operational Clustering:Concentrated launch infrastructure around Boca Chica and Houston generates co-located suit testing and refurbishment demand. Proximity to mission control facilities compresses logistics lead times.
Market Restraints
- Specialized Material Supply Concentration:Pressure garment bladder fabrics and ortho-fabric outer layers depend on sole-source domestic suppliers. Disruption risks propagate through qualification-dependent supply chains.
- Non-Recurring Engineering Cost Burden:FAA certification cycles and NASA technical standard compliance absorb capital without guaranteed production volumes. Smaller vendors face insurmountable upfront investment thresholds.
- Low-Volume Production Economics:Extravehicular suit batches rarely exceed single-digit annual quantities. Unit costs resist scale efficiencies, constraining price accessibility for emerging commercial operators.
Strategic Opportunities
- Intra-vehicular Suit Modernization:Aging shuttle-era launch and entry suits require replacement across NASA's contractor fleet. Private orbital station operators seek lighter emergency protection configurations.
- High-Fidelity Training Systems:Neutral buoyancy facility operators and commercial astronaut preparation programs demand accurate suit simulators. This ancillary equipment segment carries lower certification barriers than flight-qualified hardware.
- Canadian Space Agency Partnerships:CSA's lunar robotics and Gateway contributions create subcontracting pathways for life support subsystem vendors. Cross-border supply integration leverages USMCA trade frameworks.
Industry Challenges
- Specialized Workforce Scarcity:Pressure suit seamstress expertise and closed-loop life support engineering experience concentrate among retiring NASA contractor personnel. Knowledge transfer mechanisms remain underdeveloped.
- Integration Complexity with Orion Systems:Suit-to-capsule interface standardization lags behind vehicle development schedules. Last-minute specification changes cascade through subsystem suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Spacesuit Market |
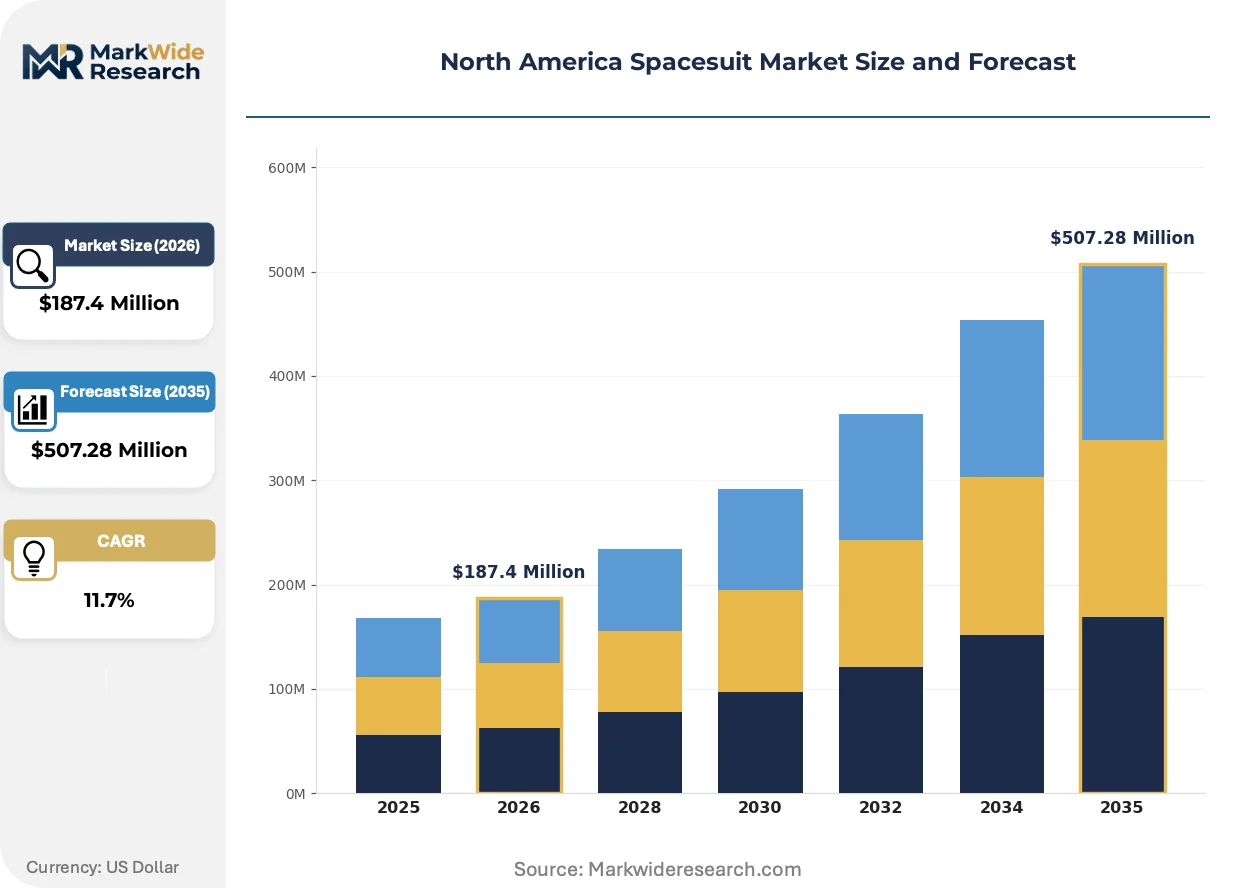
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extravehicular, Intravehicular, Training Suit, Research Suit Technology: Life Support Systems, Thermal Control, Mobility Systems, Communication Systems End User: Government Agencies, Private Corporations, Research Institutions, Defense Organizations Application: Space Exploration, Scientific Research, Astronaut Training, Aerospace Manufacturing |
| Companies Covered | ILC Dover, LP, Axiom Space, Inc., RTX Corporation, David Clark Company, Collins Aerospace, Oceaneering International, Inc., Paragon Space Development Corporation, The Boeing Company, Space Exploration Technologies Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Spacesuit Market Evolving Landscape
Advanced manufacturing methods and modular subsystem architectures are compressing development timelines while elevating performance benchmarks for next-generation lunar exploration suits.
Soft robotics and electroactive polymer actuators are automating joint torque assistance and glove dexterity enhancement. NASA's Exploration Extravehicular Mobility Unit program is integrating these materials for reduced astronaut fatigue during extended surface operations. This automation is displacing purely mechanical bearing systems and enabling longer mission durations without proportional life support mass increases.
OSHA's updated permissible exposure limits for confined space operations are extending to commercial spaceflight analog environments. Industrial hygienists are adapting terrestrial workplace monitoring protocols for pressurized habitat applications. Training facility operators in Florida and California are implementing these standards ahead of formal FAA adoption, creating preemptive compliance investment cycles.
Fixed-price development contracts are displacing cost-plus reimbursement structures for major suit procurements. NASA's Gateway logistics and services framework transfers design risk to prime contractors. Axiom Space and smaller subsystem vendors in Texas are restructuring their cost accounting to absorb this risk transfer, prioritizing modular designs that accommodate specification evolution without complete redesign.
North America Spacesuit Market Segmentation
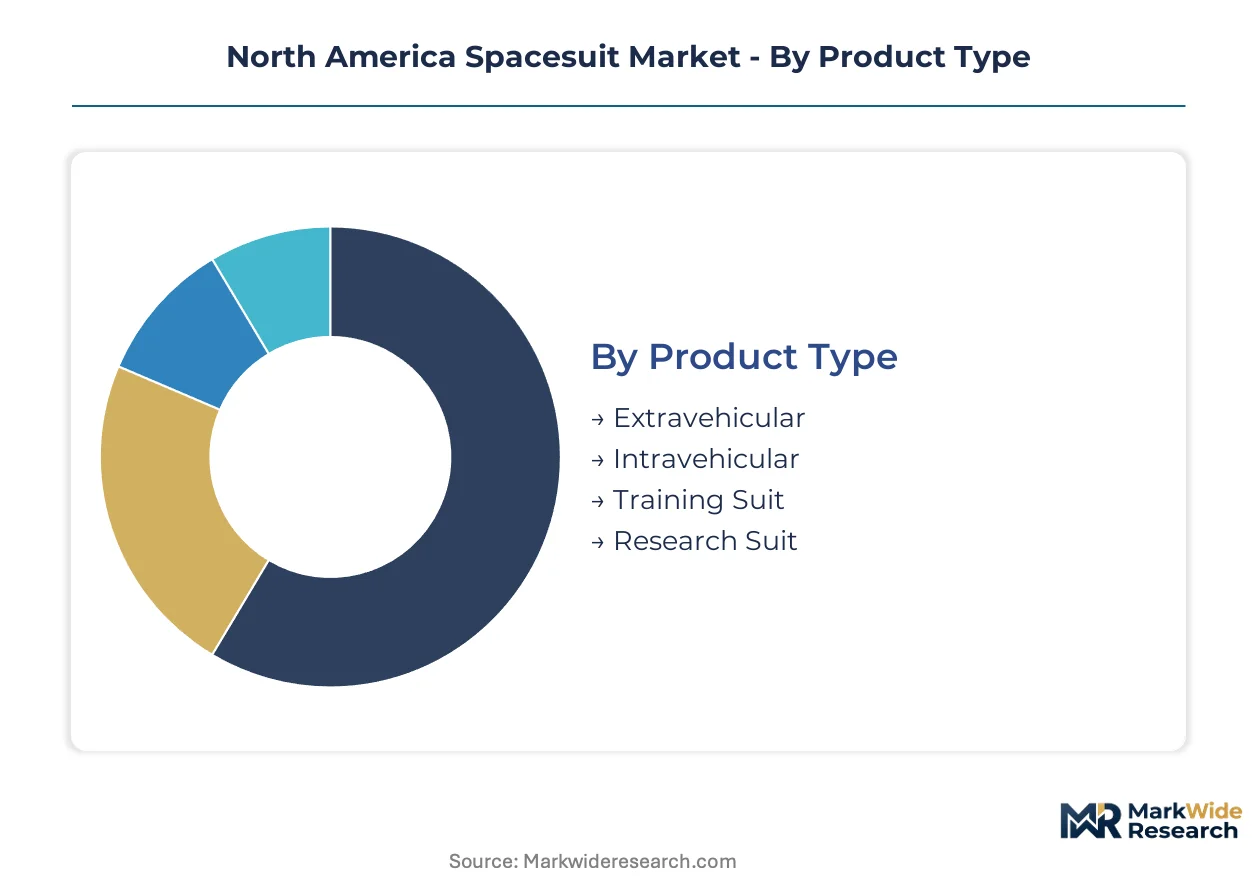
Spacesuit procurement patterns diverge sharply across mission profiles and customer capital structures. Technical specifications for lunar surface operations command fundamentally different engineering investments than orbital emergency configurations. Understanding these segment boundaries clarifies where development risk concentrates and which subsystem vendors capture disproportionate value.
Product Type:
Pressure differential requirements and mobility complexity define the engineering investment axis across suit configurations.
- Extravehicular:Multilayer pressure garments with closed-loop regenerative life support sustain human metabolism in hard vacuum for durations exceeding eight hours. NASA's Artemis lunar surface procurement concentrates demand in Houston and Texas operational clusters, where thermal micrometeoroid garment testing facilities co-locate with mission control infrastructure.
- Intravehicular:Launch and entry suits prioritize emergency cabin depressurization protection through simpler pressure vessel architectures with limited duration oxygen supply. Aging shuttle-era inventory across NASA's contractor fleet drives replacement cycles, while private orbital station operators seek lighter emergency configurations that reduce launch mass penalties.
- Training Suit:Neutral buoyancy facility operators and commercial astronaut preparation programs demand hardware that replicates flight suit kinematics without full flight qualification burdens. Lower certification barriers attract specialized subsystem vendors unable to absorb FAA commercial crew certification costs.
- Research Suit:Academic and institutional users require configurable platforms for microgravity physiology studies and suit technology validation. Modular architectures accommodate rapid iteration without complete redesign cycles.
Mature deployment sits with Intravehicular configurations across established government contractor relationships. Newer deployment is concentrated in Extravehicular segments as lunar surface mission timelines accelerate.
Technology:
Subsystem specialization depth determines vendor margin capture and qualification timeline exposure.
- Life Support Systems:Carbon dioxide scrubbing, oxygen regeneration, and thermal regulation circuits absorb disproportionate engineering investment due to mission duration constraints. FAA commercial crew certification mandates redundant architectures that elevate technical barriers and filter participation toward capitalized incumbents with NASA heritage.
- Thermal Control:Multilayer insulation and liquid cooling garments manage extreme temperature differentials between direct solar exposure and shadowed lunar craters. Artemis cislunar requirements pull advanced development forward as Gateway station construction compresses qualification cycles.
- Mobility Systems:Joint torque assistance and glove dexterity enhancement determine astronaut fatigue during extended surface operations. Soft robotics integration displaces mechanical bearing systems in next-generation lunar exploration prototypes.
- Communication Systems:Suit-to-capsule and suit-to-ground audio interfaces must integrate with Orion vehicle architectures. Last-minute specification changes cascade through subsystem suppliers as suit-to-capsule interface standardization lags vehicle development schedules.
Established deployment concentrates in Life Support Systems among legacy NASA contractors. Emerging deployment clusters in Mobility Systems as electroactive polymer actuators enable longer mission durations without proportional mass increases.
End User:
Capital structure and risk tolerance shape procurement methodology and contract vehicle selection.
- Government Agencies:NASA's fixed-price Gateway logistics contracts transfer design risk to prime contractors, forcing cost accounting restructuring among established suppliers. Artemis procurement architecture redistributes development responsibility from primes to subsystem specialists.
- Private Corporations:Axiom Space and orbital station operators seek lighter emergency protection and training system configurations. Vertical control over launch-to-suit ecosystem integration dominates competitive positioning among integrated operators.
- Research Institutions:Academic users prioritize configurable platforms for microgravity physiology studies over flight-qualified hardware. Lower certification requirements enable participation by specialized vendors excluded from prime contractor tiers.
- Defense Organizations:Classified high-altitude reconnaissance and potential orbital operations drive specialized pressure garment requirements. Procurement runs through distinct security-cleared supply chains with limited overlap to civil space vendors.
Traditional procurement dominance rests with Government Agencies. Steepest expansion trajectory appears in Private Corporations as FAA commercial spaceflight regulations mature and orbital station construction accelerates.
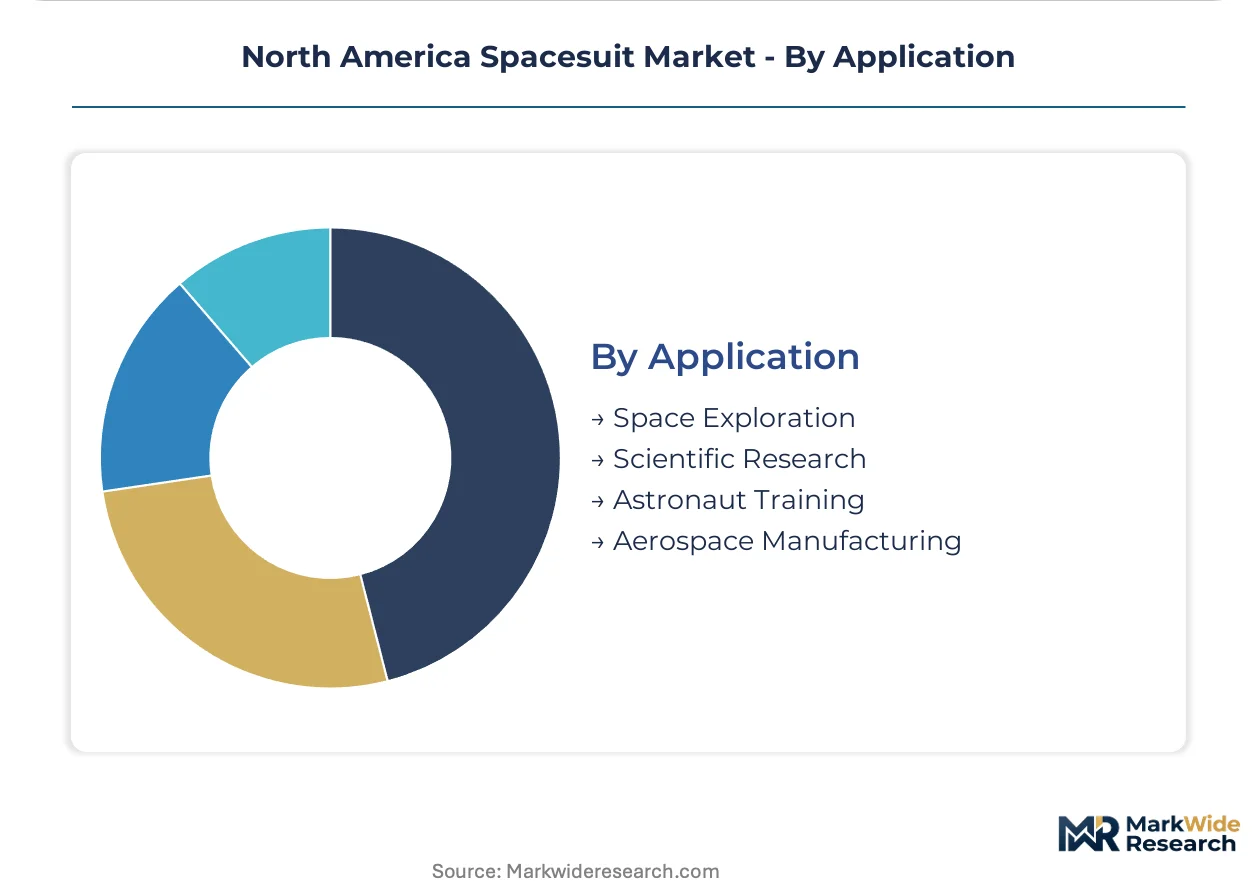
Application:
Mission criticality and operational environment determine qualification rigor and replacement frequency.
- Space Exploration:Lunar surface and cislunar operations demand highest-specification extravehicular configurations with regenerative life support. Artemis program timelines compress development cycles for qualified vendors.
- Scientific Research:Microgravity physiology and material science experiments require configurable suit platforms with instrument integration capabilities. Academic operators prioritize modularity over flight heritage.
- Astronaut Training:Neutral buoyancy facilities and high-fidelity simulators consume suit hardware at rates exceeding flight inventory. Lower certification barriers enable broader vendor participation in this ancillary equipment segment.
- Aerospace Manufacturing:Pressure garment production and subsystem assembly facilities require specialized cleanroom infrastructure concentrated in Texas and Florida operational clusters. Proximity to launch infrastructure compresses logistics lead times for flight hardware delivery.
Established demand concentrates in Space Exploration through NASA prime contractor relationships. Gaining share fastest is Astronaut Training as commercial astronaut preparation programs proliferate and neutral buoyancy facility operators expand capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas Enterprise Zone incentives and Florida Space Coast tax credits concentrate spacesuit development in southern operational corridors. NASA's Artemis procurement flows through Houston mission control infrastructure. FAA commercial crew certification requirements filter vendor participation toward capitalized incumbents with established regulatory relationships.
United States
Artemis lunar surface operations and private orbital station construction drive extravehicular suit demand. FAA commercial spaceflight regulations mandate redundant life support architectures that elevate technical barriers. Texas hosts concentrated testing facilities around Boca Chica and Houston, where SpaceX and Axiom Space maintain co-located suit refurbishment operations.
Canada
Canadian Space Agency Gateway robotics contributions create subcontracting pathways for life support subsystem vendors. USMCA trade frameworks facilitate cross-border supply integration with US prime contractors. Ontario and Quebec host specialized pressure garment fabrication facilities serving NASA contractor tiers.
Mexico
Maquiladora aerospace clusters near the US border supply specialized textile components for thermal micrometeoroid garments. Mexico's federal manufacturing incentives attract tier-2 subsystem vendors seeking proximity to Texas operational hubs. Baja California and Chihuahua concentrate cleanroom assembly capacity for flight-qualified hardware.
North America Spacesuit Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement categories. The vendor structure concentrates around NASA heritage contractors with flight-qualified extravehicular platforms. Three archetypes dominate: legacy aerospace primes with integrated life support capabilities, specialized pressure garment fabricators with decades of EVA heritage, and vertically integrated launch operators controlling end-to-end mission ecosystems. Competitive positioning hinges on fixed-price contract absorption capacity and modular subsystem architectures that accommodate specification evolution.
Within the heritage contractor tier, ILC Dover, LP and David Clark Company exemplify specialized pressure garment expertise accumulated through decades of NASA extravehicular programs. Axiom Space, Inc. occupies a distinct position as a private orbital station operator competing directly with legacy suppliers for Artemis procurement. Space Exploration Technologies Corp. anchors the vertically integrated archetype through captive control over launch-to-suit ecosystem coordination.
| Leading Market Players |
|---|
| ILC Dover, LP |
| Axiom Space, Inc. |
| RTX Corporation |
| David Clark Company |
| Collins Aerospace |
| Oceaneering International, Inc. |
| Paragon Space Development Corporation |
| The Boeing Company |
| Space Exploration Technologies Corp. |
| Others |
Value Network & Pricing Analysis
Captive in-house production of life support subsystems anchors both the supply position and pricing power for vertically integrated operators like SpaceX, while specialized pressure garment vendors absorb qualification-dependent cost premiums without guaranteed production volumes. NASA's fixed-price Gateway contracts transfer design risk downstream, forcing subsystem specialists to restructure cost accounting around modular architectures that accommodate specification evolution without complete redesign cycles.
Pricing Analysis
Premium pricing for accelerated lead times dominates extravehicular suit procurement, with Artemis mission timelines compressing qualification cycles and elevating expedited delivery premiums. Three-tier pricing structure across flight-qualified, training-grade, and research-configured hardware separates certification tiers by FAA commercial crew standards and NASA technical heritage. Cost compression in intravehicular segments is intensifying because private orbital station operators prioritize launch mass reduction over legacy shuttle-era specifications. Research institutions exhibit highest price sensitivity due to limited capital budgets and lower certification requirements, while government agencies demonstrate lowest sensitivity given mission-critical procurement mandates.
Supply Chain Analysis
Domestic-content mandates under NASA's Buy American provisions and USMCA trade frameworks are reshaping sourcing patterns for pressure garment bladder fabrics and ortho-fabric outer layers. Supply concentration centers on the United States, Canada, and Mexico, with Texas hosting co-located testing facilities and Ontario hosting specialized fabrication capacity. Critical inputs draw from sole-source domestic suppliers for multilayer thermal micrometeoroid garments and closed-loop carbon dioxide scrubbing circuits. Single-source vulnerability propagates through qualification-dependent supply chains where alternative vendor qualification timelines exceed program delivery windows. Distribution runs through prime contractor tiers to NASA procurement offices, Axiom Space operational facilities, and neutral buoyancy training operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America spacesuit market constitutes a vertical-integration race where control over launch-to-suit ecosystem coordination determines competitive viability. Players are pursuing downstream captive demand through orbital station construction and lunar surface mission contracts.
For Market Incumbents: Acquire specialized pressure garment fabrication expertise concentrated among retiring NASA contractor personnel to preempt knowledge transfer gaps. Consolidate supplier relationships around modular subsystem architectures that absorb NASA's fixed-price contract risk transfer. Defend against Axiom Space's private orbital station verticality by securing Gateway logistics and services framework positions before specification finalization. For New Entrants and Emerging Players: Begin with training suit configurations and neutral buoyancy facility supply contracts where FAA commercial crew certification barriers are lowest. Target academic research institutions and commercial astronaut preparation programs as the most penetrable demand segment. Establish go-to-market positioning through configurable research platforms that prioritize rapid iteration over flight heritage accumulation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated launch operators seeking captive suit production capabilities. Long-term viability over the coming decade hinges on Artemis program execution and private orbital station deployment timelines. Monitor NASA's lunar Gateway procurement architecture as the critical inflection signal for subsystem vendor consolidation versus prime contractor dominance.| Strategic Initiative | Industry Significance |
|---|---|
| Life Support Subsystem Acquisition | Captures NASA's risk transfer toward specialized vendors with regenerative oxygen expertise. |
| Modular Architecture Development | Enables specification evolution absorption without complete redesign under fixed-price contracts. |
| Neutral Buoyancy Facility Partnership | Opens ancillary equipment segment with lower FAA certification barriers for emerging players. |
| Canadian Space Agency Subcontracting | Leverages USMCA frameworks for cross-border Gateway robotics and life support integration. |
| Soft Robotics Integration | Displaces mechanical bearing systems for extended lunar surface mission durations. |
Research Methodology
Multi-period observation of NASA procurement award patterns, FAA commercial crew certification timelines, and Texas operational facility expansion anchored the trend analysis, supplemented by interviews with spacesuit program managers at prime contractors, life support subsystem engineers, neutral buoyancy facility operators, and commercial astronaut training directors. Secondary validation drew from NASA contract announcements, FAA regulatory dockets, SEC filings by publicly traded aerospace suppliers, and USMCA trade flow documentation. Bottom-up vendor revenue aggregation triangulated against top-down program budget allocation analysis.
Segment-weighting across product type, technology specialization, end-user capital structure, and application mission criticality informed the analytical framework. Modeled dimensions included extravehicular versus intravehicular configurations, life support versus mobility subsystem margins, government agency versus private corporation procurement methodologies, and space exploration versus training application demand profiles. CAGRs were derived from installation base growth curves and replacement cycle analysis across the projection horizon. Industry-specific forecast inputs incorporated Artemis lunar surface mission timelines and FAA regulatory adoption trajectories.
Underlying measurement precision varies by segment; government agency procurement volumes carry tighter precision than emerging commercial operator demand. Forecasts reflect documented assumptions regarding NASA program continuity and FAA regulatory finalization schedules. Unforeseen Artemis delays or commercial spaceflight accident events could materially revise trajectory projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Spain Space Electronics Market
Space
Space Sensors Market
Space
Space Transportation Market
Space
Carrier Rocket Market
Space
Space Colonization Market
Space
Mexico Space Electronics Market
Space
Space Management Solutions Market
Space
Space in Orbit Refueling Market
Space
Italy Space Electronics Market
Space
Space Traffic Management Market
Space
Space Tourism Market
Space
Deep Space Exploration Market
Space
Europe Space Electronics Market
Space
Space Debris Monitoring Market
Space
India Space Electronics Market
Space
US Space Electronics Market