
 China Space Electronics Market | 2026-2036
China Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
China Space Electronics Market Insights
The gap between radiation-hardened premium electronics and commercial-off-the-shelf commodity components is expanding as constellation operators seek cost efficiencies while manned and deep-space missions demand higher reliability grades. China Aerospace Science and Technology Corporation leverages vertical integration across launch vehicles and satellites to dominate upstream supply. China Electronics Technology Group Corporation anchors military and civil aerospace demand through its specialized semiconductor foundries. Spacety Aerospace Co. competes in the small-satellite segment with streamlined procurement models.
Space electronics encompasses electronic systems and components engineered to withstand extreme radiation, thermal cycling, and vacuum conditions encountered beyond Earth's atmosphere, typically operating across temperature ranges from minus 55 to 125 degrees Celsius with total ionizing dose tolerance exceeding 100 kilorads. These systems manage power distribution, data processing, telemetry, and attitude control for spacecraft and launch platforms. Power Systems and Control Systems command the largest share of current procurement as government-backed space station and lunar programs drive volume. Communication Components represent the fastest-expanding category as low Earth orbit broadband constellations multiply satellite counts. Integrated Circuits and FPGA technology segments attract concentrated R&D investment due to import substitution priorities under domestic technology self-sufficiency frameworks.
MIIT establishes mandatory certification protocols for aerospace-grade integrated circuits, while SAMR enforces quality standards that restrict non-qualified suppliers from national mission procurement pools. GB standards for space electronics testing align with but remain distinct from international IEC frameworks, creating compliance complexity for foreign component vendors. Stakeholders must monitor evolving dual carbon implementation timelines that affect cleanroom energy costs and semiconductor fabrication economics.
Market Dynamics
MIIT's tightening GB certification protocols for aerospace-grade semiconductors are forcing component suppliers to retool testing infrastructure and elongating qualification cycles for new entrants seeking national mission procurement access.
Growth Catalysts
- Low Earth orbit broadband constellations:Commercial satellite operators are scaling procurement of radiation-tolerant components to populate megaconstellations, creating sustained demand for power management and communication subsystems.
- Dual carbon goals:China's national decarbonization framework is accelerating cleanroom energy efficiency upgrades, indirectly tightening qualification requirements for semiconductor fabrication facilities serving space-grade production.
- Lunar and space station programs:Government-backed deep-space missions are driving volume procurement of high-reliability control systems with extended temperature-range specifications.
Market Restraints
- Import substitution bottlenecks:Domestic FPGA and high-performance integrated circuit production remains concentrated among state-affiliated foundries with limited commercial capacity.
- Qualification cost escalation:SAMR-enforced quality standards require multi-year total ionizing dose testing cycles that consume capital without guaranteed procurement awards.
- Radiation-hardening premium:The cost gap between commercial-off-the-shelf components and aerospace-grade equivalents limits constellation operators' ability to optimize unit economics at scale.
Strategic Opportunities
- Small-satellite streamlined procurement:Emerging commercial launch providers are adopting tiered supplier qualification frameworks that reduce barrier-to-entry for qualified domestic component vendors.
- Power system integration:Convergence of gallium nitride power electronics with traditional silicon control architectures enables subsystem miniaturization for next-generation spacecraft platforms.
- Shanghai manufacturing corridor expansion:Integrated circuit fabrication clusters in the Yangtze River Delta are attracting space-grade cleanroom investment under regional industrial policy incentives.
Industry Challenges
- Radiation effects engineering talent scarcity:Qualified specialists capable of designing single-event upset mitigation architectures remain concentrated within legacy defense contractors.
- Legacy system integration friction:New semiconductor packaging technologies must interface with established satellite bus architectures without triggering full platform redesign cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Space Electronics Market |
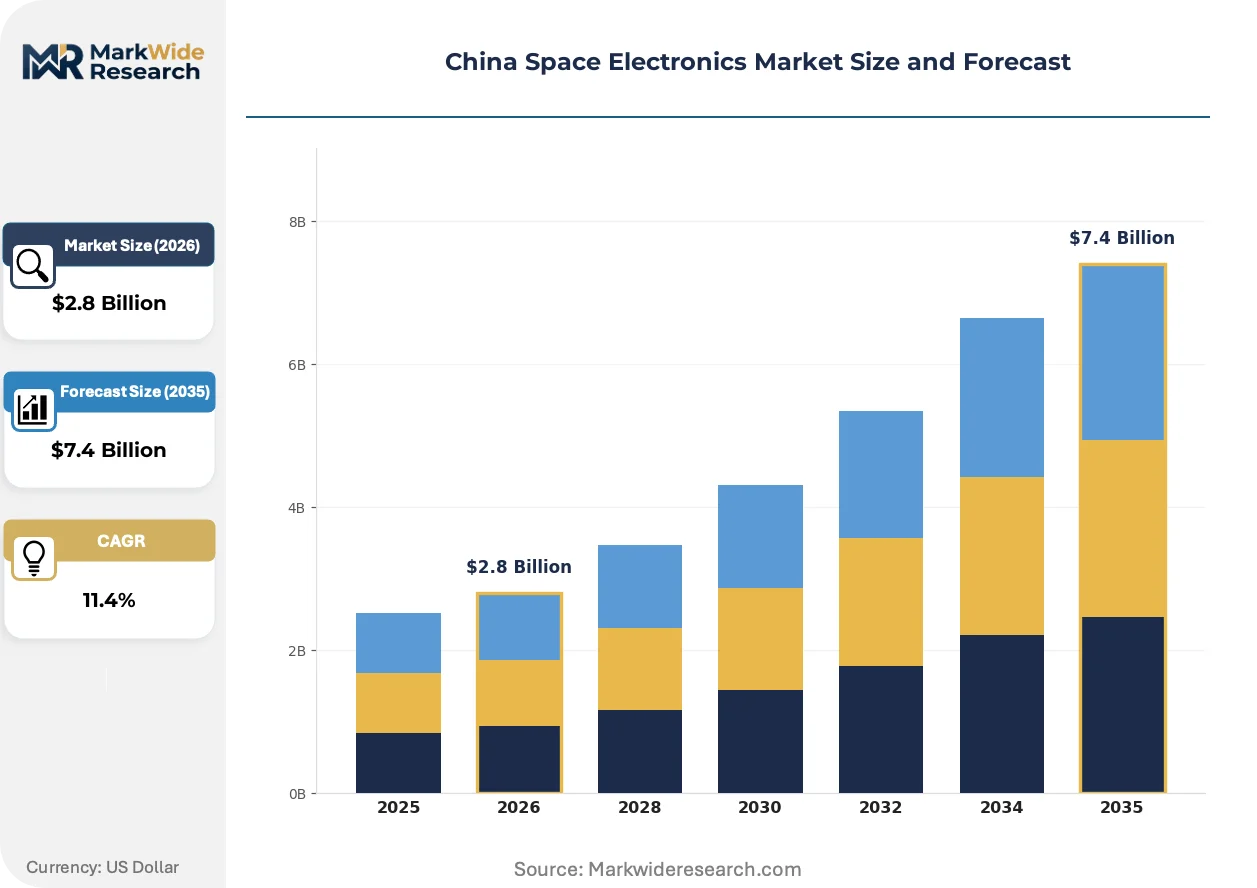
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Systems, Communication Components, Sensors, Control Systems Technology: Digital Processing, Integrated Circuits, FPGA, ASIC Application: Satellite, Launch Vehicles, Space Probes, Space Stations End User: Government Agencies, Commercial Providers, Research Institutions, Defense |
| Companies Covered | China Aerospace Science and Technology Corporation (CASC), China Electronics Technology Group Corporation (CETC), China Aerospace Science & Industry Corporation (CASIC), Aviation Industry Corporation of China (AVIC), Shandong Aerospace Electronic Technology Institute (SISET), Chang Guang Satellite Technology Co. Ltd, China National Electronics Import & Export Corporation (CEIEC), Guodian Gaoke, Spacety Aerospace Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Space Electronics Market Trends and Innovations
Space electronics development is pivoting from centralized defense contractor supply chains toward distributed commercial procurement models, with technology transfer accelerating between terrestrial semiconductor advances and aerospace qualification requirements.
Commercial-off-the-shelf component screening with post-manufacturing radiation hardening is decentralizing procurement authority away from traditional prime contractors toward constellation operators with in-house qualification capabilities. Small-satellite developers in Beijing's Zhongguancun cluster are adopting this approach to compress subsystem delivery timelines. The shift is fragmenting supplier relationships and compressing margins for legacy component distributors.
MIIT's updated GB standards for space electronics testing are mandating traceability documentation that exceeds baseline IEC frameworks, creating compliance complexity for foreign component vendors seeking national mission access. Domestic foundries are investing in parallel certification infrastructure to capture procurement pools restricted under SAMR enforcement. The policy divergence most affects integrated circuit and FPGA segments where import substitution priorities concentrate.
Constellation operators are unbundling subsystem procurement from turnkey satellite contracts, establishing direct relationships with specialized component vendors for power management and attitude control electronics. This disintermediation of traditional prime contractor channels is visible among low Earth orbit broadband ventures with high satellite replenishment rates. The model transfers integration risk to operators while enabling component-level cost optimization.
China Space Electronics Market Segmentation
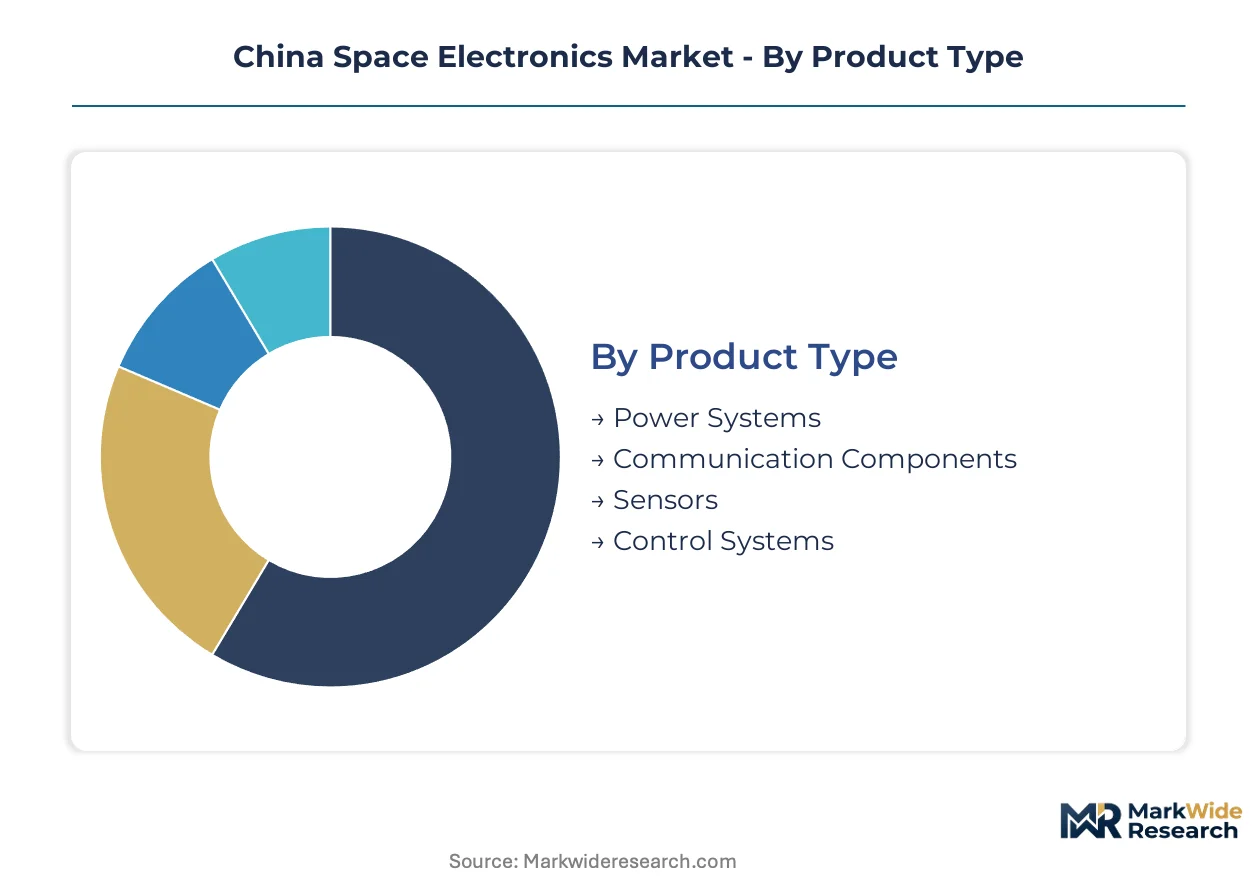
China's space electronics procurement splits sharply between high-reliability government missions and cost-optimized commercial constellations. Component suppliers must navigate divergent qualification requirements across these demand tiers. Understanding where volume concentrates versus where margins expand determines vendor positioning strategy.
Product Type:
Power Systems and Control Systems anchor procurement volume for deep-space missions, while Communication Components capture the steepest demand acceleration from low Earth orbit broadband deployments.
- Power Systems:These subsystems manage voltage regulation, battery charging, and power distribution across temperature extremes from minus 55 to 125 degrees Celsius. Demand concentrates in lunar program contractors and space station module integrators in Beijing's Zhongguancun cluster, driven by MIIT's tightening GB certification protocols for aerospace-grade semiconductors.
- Communication Components:Radio frequency modules, transponders, and antenna control electronics enable telemetry and data downlink. Procurement from Shanghai's integrated circuit manufacturing corridor is accelerating as constellation operators scale megaconstellation deployments, constrained by radiation-hardening cost premiums that limit unit economics optimization.
- Sensors:Star trackers, sun sensors, and inertial measurement units provide attitude determination and orbital positioning data.
- Control Systems:Flight computers and guidance processors execute attitude control algorithms and trajectory corrections with single-event upset mitigation architectures.
Today's leader: Power Systems. Tomorrow's challenger: Communication Components.
Technology:
Digital Processing and FPGA technologies concentrate R&D investment under import substitution frameworks, while Integrated Circuits face qualification bottlenecks at state-affiliated foundries.
- Digital Processing:Radiation-tolerant microprocessors and signal processing units execute mission-critical computations with total ionizing dose tolerance exceeding 100 kilorads. Procurement flows to defense contractors with captive design capabilities, constrained by radiation effects engineering talent scarcity within legacy supply chains.
- FPGA:Field-programmable gate arrays enable reconfigurable logic for payload processing and protocol adaptation. Demand from commercial satellite developers in Beijing is expanding most quickly as constellation operators adopt post-manufacturing radiation hardening to compress subsystem delivery timelines.
- Integrated Circuits:Custom and standard ICs provide analog and mixed-signal functions for power management and sensor interfaces.
- ASIC:Application-specific integrated circuits deliver optimized performance for mature mission profiles with high production volumes.
Digital Processing commands current procurement pools. FPGA is gaining share fastest through commercial constellation adoption.
Application:
Satellite applications dominate procurement volume across government and commercial channels, while Space Stations drive premium-grade component demand with extended qualification cycles.
- Satellite:Earth observation, navigation, and communications spacecraft require electronics spanning power, control, and communication functions. Procurement concentrates among low Earth orbit broadband ventures with high replenishment rates, enabled by tiered supplier qualification frameworks that reduce barrier-to-entry for domestic component vendors.
- Space Stations:Manned orbital platforms demand the highest reliability grades with multi-year operational lifespans. MIIT mandatory certification protocols restrict procurement to qualified suppliers with parallel GB and IEC testing infrastructure, creating compliance complexity for foreign component vendors.
- Launch Vehicles:Booster and upper-stage avionics manage guidance, telemetry, and engine control during ascent phases.
- Space Probes:Lunar and interplanetary missions require extreme temperature-range specifications and deep-space communication capabilities.
Satellite procurement anchors volume today. Space Station programs define premium tier requirements.
End User:
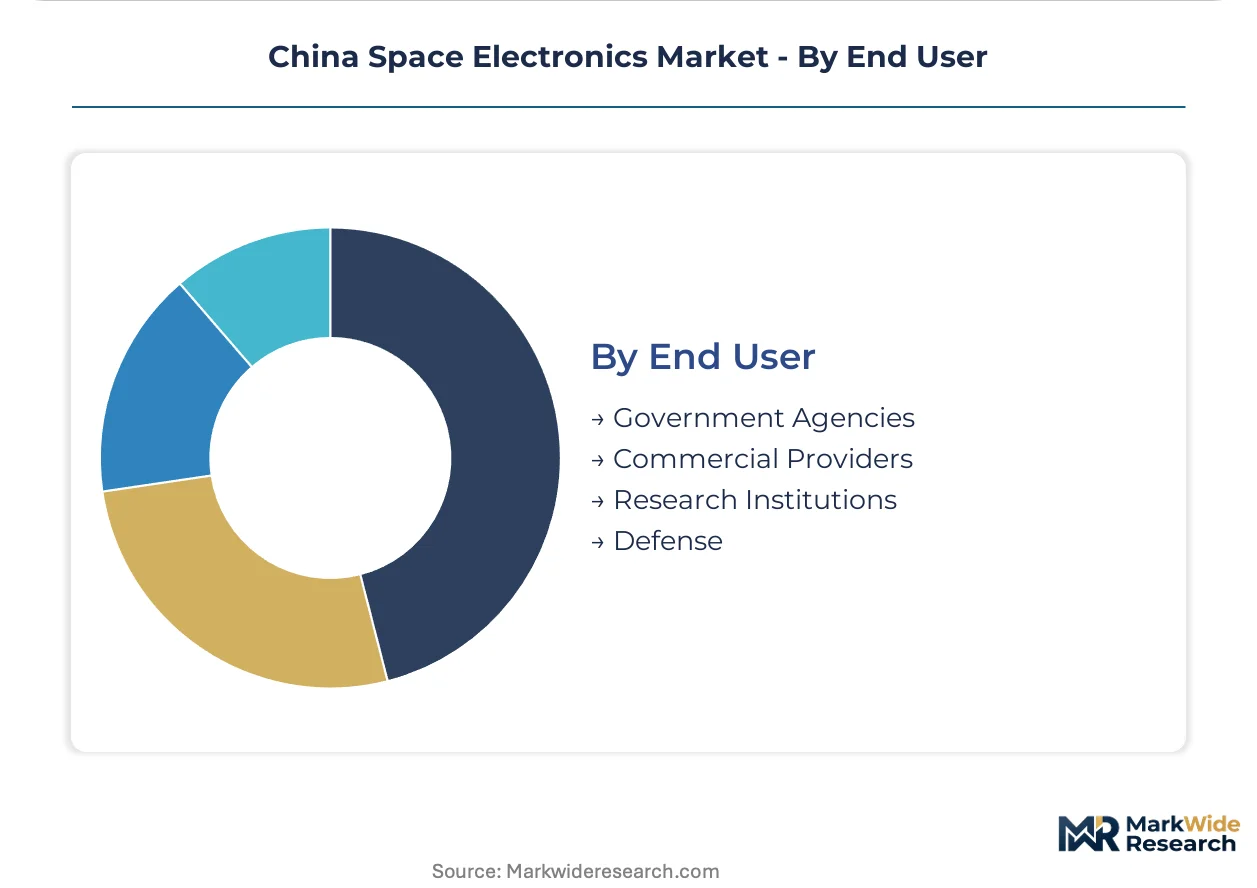
Government Agencies and Defense channels enforce the strictest qualification standards, while Commercial Providers are unbundling subsystem procurement from traditional prime contractor relationships.
- Government Agencies:China Aerospace Science and Technology Corporation and civil space programs procure through centralized defense contractor supply chains with multi-year total ionizing dose testing cycles. SAMR-enforced quality standards consume capital without guaranteed procurement awards, elongating qualification cycles for new entrants.
- Commercial Providers:Constellation operators and emerging launch providers are establishing direct relationships with specialized component vendors. Spacety Aerospace Co. and similar ventures in Zhongguancun are disintermediating traditional channels to enable component-level cost optimization, transferring integration risk to operators.
- Defense:Military satellite and launch programs anchor demand for highest-reliability grades with restricted supplier pools.
- Research Institutions:Universities and technology demonstrators procure experimental payloads with streamlined qualification requirements.
Government Agencies anchor premium procurement. Commercial Providers are restructuring supply relationships fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiation effects engineering talent concentrates in Beijing's Zhongguancun aerospace cluster and Shanghai's integrated circuit manufacturing corridor, anchoring domestic supply chain development. MIIT certification protocols and dual carbon implementation timelines are reshaping regional investment patterns across China's space electronics production base.
Beijing-Tianjin-Hebei
Lunar program contractors and space station module integrators drive demand for power systems with extended temperature-range specifications. MIIT's tightening GB certification protocols for aerospace-grade semiconductors elongate qualification cycles for new entrants seeking national mission procurement access. Zhongguancun hosts China Aerospace Science and Technology Corporation's vertical integration across launch vehicles and satellites.
Yangtze River Delta
Shanghai's integrated circuit manufacturing corridor attracts space-grade cleanroom investment under regional industrial policy incentives. SAMR-enforced quality standards require multi-year total ionizing dose testing cycles that consume capital without guaranteed procurement awards. Constellation operators here scale megaconstellation deployments for low Earth orbit broadband networks.
Sichuan-Chongqing
Defense contractors with captive design capabilities anchor demand for radiation-tolerant microprocessors and signal processing units. Dual carbon goals accelerate cleanroom energy efficiency upgrades, indirectly tightening qualification requirements for semiconductor fabrication facilities. Legacy system integration friction persists as new packaging technologies interface with established satellite bus architectures.
Shandong Peninsula
Specialized semiconductor foundries serving military and civil aerospace demand expand production capacity under state-affiliated structures. Import substitution bottlenecks concentrate domestic FPGA and high-performance integrated circuit production among limited commercial capacity providers. Shandong Aerospace Electronic Technology Institute anchors regional research infrastructure.
China Space Electronics Market Competitive Landscape
Top-tier vendors anchor government-backed deep-space missions, while commercial constellation operators seek streamlined procurement relationships with emerging suppliers. The vendor base splits between state-affiliated defense contractors with captive foundries and independent small-satellite developers adopting tiered qualification frameworks. Two strategic archetypes dominate: vertically integrated prime contractors controlling upstream supply and specialized component vendors serving disintermediated procurement channels. Competitive moves center on capacity expansion at Yangtze River Delta fabrication clusters and strategic partnerships between constellation operators and power electronics specialists.
Among state-affiliated defense contractors, China Aerospace Science and Technology Corporation, China Electronics Technology Group Corporation, and China Aerospace Science & Industry Corporation exemplify the vertically integrated archetype controlling launch vehicle and satellite supply chains. Spacety Aerospace Co. occupies a position within the commercial small-satellite tier, representing the streamlined procurement model that reduces barrier-to-entry for qualified domestic component vendors.
| Leading Market Players |
|---|
| China Aerospace Science and Technology Corporation (CASC) |
| China Electronics Technology Group Corporation (CETC) |
| China Aerospace Science & Industry Corporation (CASIC) |
| Aviation Industry Corporation of China (AVIC) |
| Shandong Aerospace Electronic Technology Institute (SISET) |
| Chang Guang Satellite Technology Co. Ltd |
| China National Electronics Import & Export Corporation (CEIEC) |
| Guodian Gaoke |
| Spacety Aerospace Co. |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride power electronics convergence with silicon control architectures is simultaneously compressing subsystem costs and concentrating procurement authority among constellation operators with in-house qualification capabilities. This technology transition fragments legacy prime contractor pricing power while rewarding direct component vendor relationships.
Pricing Analysis
Unbundled subsystem procurement from turnkey satellite contracts is displacing bundled prime contractor pricing. Three-tier pricing structure across radiation-hardened premium, radiation-tolerant standard, and commercial-off-the-shelf economy levels reflects MIIT GB certification grade and volume scale. Cost compression in the commercial tier intensifies because constellation operators screen COTS components with post-manufacturing hardening. Commercial providers exhibit highest price sensitivity; government space station programs remain least sensitive due to mission-critical reliability requirements.
Supply Chain Analysis
MIIT mandatory certification protocols gate supplier access to national mission procurement pools, concentrating qualified production in China's Yangtze River Delta and Beijing-Tianjin-Hebei clusters. The supply chain draws from domestic state-affiliated foundries for FPGA and high-performance integrated circuits, with gallium nitride substrates and radiation-hardened packaging materials as critical inputs. Single-source vulnerability persists at qualified semiconductor fabrication facilities serving space-grade production. Distribution runs through direct relationships between constellation operators and specialized component vendors, bypassing traditional prime contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where MIIT's tightening GB certification protocols for aerospace-grade semiconductors continuously elevate barriers to national mission access, amplifying demand for qualified domestic suppliers.
For Market Incumbents: Deepen captive foundry capacity in Shanghai's integrated circuit manufacturing corridor to defend against emerging commercial constellation operators adopting tiered qualification frameworks. Invest in parallel GB and IEC certification infrastructure to capture procurement pools restricted under SAMR enforcement, insulating against import substitution acceleration at state-affiliated competitors. For New Entrants and Emerging Players: Launch via streamlined small-satellite procurement relationships with Beijing Zhongguancun constellation developers, bypassing legacy prime contractor channels. Target commercial low Earth orbit broadband ventures with radiation-tolerant component offerings that compress subsystem delivery timelines. Pursue direct power management and attitude control electronics supply contracts that transfer integration risk to operators. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized semiconductor foundries with nascent space-grade cleanroom investment under regional dual carbon policy incentives. Long-term viability centers on qualification timeline compression and certification asset accumulation. Watch for inflection when tiered supplier frameworks expand beyond small-satellite developers to medium-lift launch providers.| Strategic Initiative | Industry Significance |
|---|---|
| GB Certification Infrastructure Investment | MIIT mandatory protocols restrict national mission access to qualified suppliers with parallel testing capability. |
| Gallium Nitride Power Electronics Integration | Convergence with silicon architectures enables subsystem miniaturization for next-generation spacecraft platforms. |
| Direct Constellation Operator Relationships | Disintermediation of prime contractor channels transfers integration risk while enabling component-level cost optimization. |
| Yangtze River Delta Cleanroom Expansion | Regional industrial policy incentives attract space-grade fabrication investment under dual carbon implementation timelines. |
| Post-Manufacturing Radiation Hardening Capability | COTS component screening decentralizes procurement authority toward operators with in-house qualification infrastructure. |
Research Methodology
Multiple input streams — primary interviews with satellite program managers, semiconductor foundry operations directors, and MIIT certification specialists, plus secondary validation against customs trade data, MIIT regulatory filings, and Yangtze River Delta industrial policy disclosures — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored the analytical framework across the projection horizon, modeling segmentation by product type, technology node, application mission profile, and end-user procurement channel. CAGRs were derived from volume trajectory analysis incorporating constellation deployment schedules, lunar program milestone pacing, and cleanroom capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt dual carbon policy acceleration or import substitution bottleneck resolution at state-affiliated foundries. A model refresh is warranted upon material change in MIIT GB certification protocol implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Ground System Market
Space
Private Space Travel Market
Space
Suborbital Space Tourism Market
Space
US Space Electronics Market
Space
Spain Space Electronics Market
Space
Deep Space Robotics Market
Space
Space Frame Market
Space
Space-Based Smart Sensors Market
Space
Space Travel Market
Space
Space Wheel Market
Space
Orbital Spaceflight Market
Space
Germany Space Electronics Market
Space
Japan Space Electronics Market
Space
Space Robots Market
Space
Space Debris Monitoring and Removal Market
Space
Asia-Pacific Space Logistics Market