
 Germany Space Electronics Market | 2026-2036
Germany Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Space Electronics Market Insights
Buyer concentration around European prime contractors and national space agencies is hardening procurement standards for German suppliers. Infineon Technologies leverages its power semiconductor expertise to anchor radiation-hardened component supply chains. RUAG International sustains vertical integration across satellite structures and electronics packaging. Texas Instruments competes through high-reliability analog portfolios qualified for extended orbital missions.
Germany space electronics encompasses radiation-hardened semiconductors, power distribution units, and communication subsystems engineered to withstand thermal cycling, ionizing radiation, and vacuum conditions across orbital and deep-space environments. These systems enable payload operation, telemetry transmission, and spacecraft bus management for satellites, launch vehicles, and ground infrastructure. Communication Systems command the largest revenue share among product types due to persistent bandwidth expansion in Low Earth Orbit constellations. Satellite Technology leads the technology dimension as German manufacturers prioritize on-board processing and optical inter-satellite links. Defense Contractors represent the fastest-growing end-user category as military satellite procurement accelerates under European strategic autonomy frameworks.
KBA and BSI certification requirements intersect with ESA ECSS standards to govern component qualification timelines and traceability protocols for German space electronics manufacturers. The EU Green Deal and national dual-use export regulations further constrain material sourcing and foreign customer access for sensitive technologies. Stakeholders must monitor evolving ITAR-EU equivalency negotiations and domestic foundry capacity investments to secure supply continuity for qualified components.
Market Dynamics
ESA's constellation procurement surge is compressing qualification timelines for Bavarian suppliers while tightening traceability mandates under revised ECSS standards. Prime contractors now demand dual-source redundancy for radiation-hardened components, forcing mid-tier German manufacturers to accelerate certification investments or exit qualified supplier lists.
Growth Catalysts
- IRIS² constellation deployment:The EU's sovereign broadband infrastructure program is generating multi-year procurement contracts for German payload electronics and optical inter-satellite link terminals.
- Defense satellite acceleration:Military end-users under European strategic autonomy frameworks are expanding classified procurement channels for hardened communication subsystems.
- Bavaria aerospace cluster concentration:Munich-Ottobrunn's integrated supply chain of research institutes, primes, and component specialists reduces qualification friction for new entrants.
Market Restraints
- Domestic foundry capacity scarcity:Germany lacks qualified semiconductor fabrication for rad-hard processes, creating dependency on French and US foundry slots with 18-24 month lead times.
- Dual-use export licensing friction:National regulations governing military-civilian technology transfer create documentation burdens that delay foreign customer deliveries.
- Palladium and tantalum input volatility:Space-grade capacitor and connector manufacturers face price instability in conflict-mineral supply chains subject to EU Green Deal sourcing constraints.
Strategic Opportunities
- Optical payload miniaturization:Convergence of photonic integrated circuits with silicon germanium processes is opening new product categories for Earth observation constellation primes.
- North Rhine-Westphalia expansion:Cologne-Bonn's emerging space logistics hub offers underutilized test infrastructure and proximity to DLR facilities for qualification cost reduction.
- CSRD-aligned sustainability reporting:Early adoption of supply chain carbon accounting creates differentiation for German suppliers bidding on EU institutional procurement frameworks.
Industry Challenges
- Radiation effects engineering talent scarcity:German universities produce insufficient specialists in single-event upset modeling and total ionizing dose hardening to meet qualification pipeline demands.
- ECSS-Q-ST-60-02C certification timeline compression:Accelerated constellation deployment schedules conflict with traditional 24-36 month component qualification protocols.
- ITAR-EU equivalency negotiation uncertainty:Transatlantic regulatory misalignment threatens German supplier access to US satellite prime contractor supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Space Electronics Market |
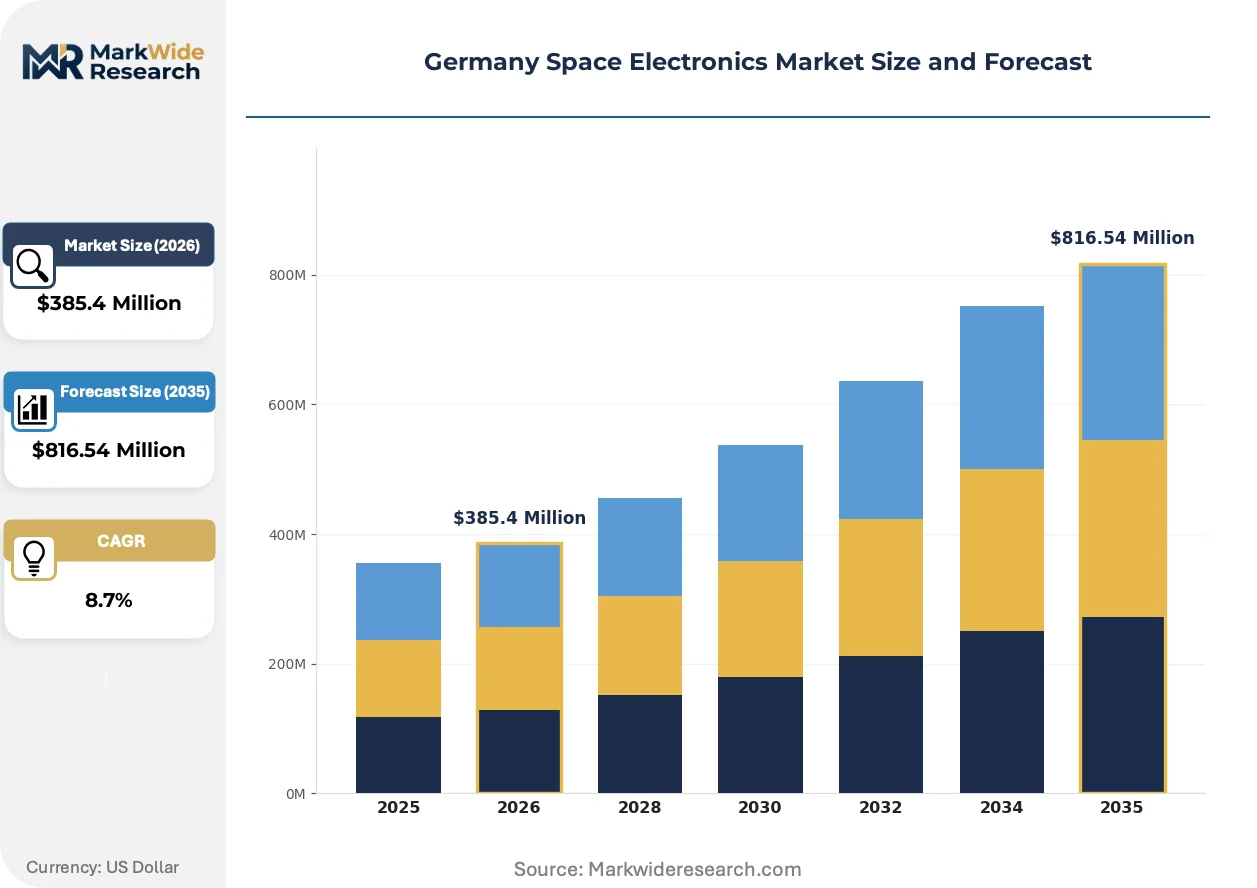
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Systems, Communication Systems, Payloads, Control Systems Technology: Satellite Technology, Launch Vehicle Technology, Ground Support Equipment, Alternate Propulsion Application: Earth Observation, Communication, Scientific Research, Navigation End User: Government Agencies, Commercial Enterprises, Research Institutions, Defense Contractors |
| Companies Covered | Northrop Grumman Corporation, Texas Instruments, Infineon Technologies, RUAG International, Microchip Technology, STMicroelectronics, BAE Systems, Thales Group, Honeywell International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Space Electronics Market Trends and Innovations
Gallium nitride power electronics and software-defined payload architectures are displacing legacy silicon-based systems across German satellite manufacturing. These shifts compress development cycles while introducing new qualification complexities for radiation tolerance.
GaN-on-SiC high-electron-mobility transistors deliver superior power density and thermal efficiency for satellite power distribution units. Airbus Defence and Space and OHB System AG are qualifying these devices for medium-Earth orbit missions with accelerated test protocols. This technology is expanding into deep-space probe applications previously reserved to silicon insulated-gate bipolar transistors.
The EU Green Deal's conflict minerals regulation and extended producer responsibility frameworks are reshaping material sourcing obligations for German space electronics manufacturers. Component suppliers must now document tantalum, tungsten, tin, and gold supply chain provenance to maintain ESA qualified parts list status. Small and mid-tier Bavarian firms face disproportionate compliance costs relative to vertically integrated primes.
Consolidated procurement through European prime contractor framework agreements is displacing direct component purchasing by national space agencies. German suppliers now negotiate multi-year supply commitments with Airbus and Thales Alenia Space rather than discrete contracts with DLR or ESA. This concentration is most visible in Bavaria, where Ottobrunn-based subsystem manufacturers report 70% revenue dependency on two prime contractor accounts.
Germany Space Electronics Market Segmentation
German space electronics procurement patterns diverge sharply across customer mission profiles and technical risk tolerances. Prime contractor consolidation and ESA framework contracting have compressed the vendor landscape, making segment-level positioning decisive for supplier survival.
Product Type:
Cost tier differentiation separates volume constellation suppliers from deep-space qualification specialists serving single-mission budgets.
- Communication Systems:RF transceivers, modems, and optical inter-satellite link terminals engineered for bandwidth-intensive Low Earth Orbit constellations. IRIS² sovereign infrastructure procurement concentrates demand in Bavaria's Ottobrunn cluster, where Airbus Defence and Space qualifies multi-gigabit payload electronics under compressed ECSS timelines.
- Power Systems:Radiation-hardened power distribution units, solar array regulators, and battery management electronics. Gallium nitride high-electron-mobility transistors from Infineon Technologies displace silicon IGBTs in medium-Earth orbit applications, though domestic foundry scarcity forces 18-24 month qualification cycles through French and US fabrication partners.
- Payloads:On-board processors, sensor interfaces, and data handling units for Earth observation and scientific missions.
- Control Systems:Attitude determination electronics, star trackers, and command receivers for spacecraft bus management.
Communication Systems leads volumes today; Power Systems is gaining share fastest through GaN qualification acceleration.
Technology:
Application maturity determines whether German suppliers compete on heritage qualification or emerging technology insertion.
- Satellite Technology:On-board computing, optical communications, and miniaturized payload electronics for orbital platforms. Munich-Ottobrunn's integrated research-to-manufacturing pipeline gives Bavarian firms qualification friction advantages for new photonic integrated circuit products entering Earth observation constellations.
- Ground Support Equipment:Test instrumentation, mission control interfaces, and launch range electronics. Cologne-Bonn's underutilized DLR-adjacent infrastructure offers emerging suppliers cost reduction pathways for environmental test and verification workflows.
- Launch Vehicle Technology:Avionics, telemetry, and stage separation electronics for expendable and reusable boosters.
- Alternate Propulsion:Electric thruster control electronics and power processing units for station-keeping and orbit-raising.
Satellite Technology dominates current procurement; Alternate Propulsion exhibits the steepest expansion trajectory as electric propulsion adoption accelerates.
Application:
Customer procurement channel bifurcates between classified defense frameworks and transparent commercial constellation bidding.
- Earth Observation:Optical and synthetic aperture radar payload electronics for environmental monitoring and intelligence gathering. German manufacturers prioritize on-board processing architectures that reduce downlink bandwidth requirements for Copernicus program satellite series.
- Communication:Broadband and narrowband relay electronics for consumer, enterprise, and government connectivity services. European strategic autonomy frameworks expand classified procurement channels for hardened communication subsystems serving military end-users.
- Scientific Research:Instrument control and data acquisition electronics for deep-space probes and orbital laboratories.
- Navigation:Atomic clock interfaces and signal generation electronics for GNSS augmentation and independent systems.
Communication commands the largest revenue base today; Earth Observation is climbing the fastest as optical constellation deployment intensifies.
End User:
Contracting modality separates institutional framework agreements from discrete commercial negotiations with diverging technical documentation burdens.
- Defense Contractors:Classified satellite procurement for signals intelligence, secure communications, and early warning systems. Military end-users under European strategic autonomy frameworks are expanding procurement volumes for radiation-hardened communication subsystems with ITAR-EU equivalency compliance requirements.
- Government Agencies:ESA, DLR, and EU institutional procurement for scientific and operational satellite programs. Consolidated framework agreements through Airbus and Thales Alenia Space now displace direct component purchasing, concentrating 70% of Bavarian subsystem manufacturer revenue on two prime contractor accounts.
- Commercial Enterprises:Constellation operators and satellite service providers procuring payload and bus electronics.
- Research Institutions:University and institute-led small satellite and technology demonstration missions.
Government Agencies anchor current procurement volumes; Defense Contractors are expanding most quickly under rearmament and strategic autonomy investment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German radiation effects engineering specialists concentrate in Bavaria's Munich-Ottobrunn corridor, anchoring Europe's densest cluster of qualified space electronics suppliers. This talent density shapes procurement patterns across the country's federal structure.
Bavaria
Airbus Defence and Space and OHB System AG drive demand for payload electronics and optical inter-satellite link terminals in Ottobrunn. ESA ECSS qualification protocols govern component traceability for suppliers integrated into IRIS² constellation procurement. The Munich-Ottobrunn research-to-manufacturing pipeline reduces friction for photonic integrated circuit products entering Earth observation programs.
North Rhine-Westphalia
Cologne-Bonn's emerging space logistics hub attracts environmental test providers seeking proximity to DLR facilities. The EU Green Deal's extended producer responsibility frameworks reshape material sourcing obligations for capacitor manufacturers in the region. Underutilized test infrastructure near DLR's Cologne headquarters offers qualification cost reduction pathways for new entrants.
Baden-Württemberg
Stuttgart's precision engineering base supports satellite structure and electronics packaging specialists serving prime contractor frameworks. KBA certification requirements intersect with ESA standards to govern component qualification timelines for regional manufacturers. The state's automotive semiconductor heritage feeds talent pipelines for power electronics specialists targeting satellite power distribution units.
Hesse
Frankfurt's financial and regulatory infrastructure hosts compliance specialists navigating dual-use export licensing for military-civilian technology transfers. National regulations governing sensitive technology transfer create documentation burdens that delay foreign customer deliveries for exporters in the region. The cluster specializes in regulatory navigation rather than manufacturing concentration.
Germany Space Electronics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Germany's space electronics supply base. Prime contractor consolidation has compressed the vendor landscape, concentrating 70% of Bavarian subsystem manufacturer revenue on two accounts. Three archetypes dominate: vertically integrated European primes with captive electronics divisions, German component specialists leveraging radiation-hardening expertise, and US semiconductor majors competing through qualified analog portfolios. Competitive moves center on multi-year framework agreement negotiations and accelerated ECSS certification investments to maintain qualified supplier status.
Among US-based semiconductor suppliers, Texas Instruments and Microchip Technology occupy positions within the high-reliability analog tier. Infineon Technologies anchors the German specialist archetype, representing power semiconductor expertise applied to radiation-hardened component supply chains. RUAG International exemplifies the vertically integrated European model, sustaining in-house production across satellite structures and electronics packaging. These three entities represent distinct strategic positions rather than direct substitutes.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Texas Instruments |
| Infineon Technologies |
| RUAG International |
| Microchip Technology |
| STMicroelectronics |
| BAE Systems |
| Thales Group |
| Honeywell International |
| Others |
Pricing and Supply Chain Analysis
Captive foundry arrangements at Infineon Technologies and RUAG International anchor supply positions while insulating qualified component pricing from spot-market volatility in palladium and tantalum. This backward integration into radiation-hardened packaging creates pricing power for Bavarian primes bidding on IRIS² constellation frameworks, though domestic fabrication scarcity forces mid-tier German suppliers into 18-24 month qualification cycles through French and US partners.
Pricing Analysis
Capacity additions in French and US foundries are reshaping price floors for radiation-hardened semiconductors as German suppliers compete for limited qualification slots. Three-tier pricing structure across heritage-qualified, accelerated-test, and commercial-off-the-shelf levels separates deep-space mission budgets from constellation volume procurement. Cost compression in commercial LEO tiers is intensifying because prime contractors now mandate dual-source redundancy for power distribution units. Commercial constellation operators exhibit highest price sensitivity, while defense contractors under European strategic autonomy frameworks absorb premiums for ITAR-EU equivalency compliance.
Supply Chain Analysis
Dual-sourcing requirements from Airbus Defence and Space and Thales Alenia Space are fragmenting component allocation across French, US, and German qualified suppliers. Geographic supply concentration centers on France for rad-hard foundry services, the United States for analog semiconductor heritage, and Germany for payload integration and testing. Raw material dependencies include palladium for space-grade capacitors, tantalum for high-reliability connectors, and silicon germanium for photonic integrated circuits. Single-source vulnerability in qualified semiconductor fabrication creates procurement risk for Bavarian subsystem manufacturers. Distribution runs through prime contractor framework agreements rather than direct national agency purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's space electronics market functions as a regulatory compounder where ESA ECSS qualification mandates and EU Green Deal conflict-mineral tracing create accelerating barriers to entry. The IRIS² sovereign infrastructure program represents the decisive regulatory milestone driving multi-year procurement commitments through 2035.
For Market Incumbents: Deepen captive packaging capabilities to defend margin position against emerging photonic integrated circuit specialists from North Rhine-Westphalia. Accelerate ECSS-Q-ST-60-02C certification investments to maintain qualified supplier status as prime contractors compress heritage timelines from 36 to 18 months. Threat substitution from GaN-on-SiC power electronics demands immediate R&D allocation to avoid displacement in medium-Earth orbit applications. For New Entrants and Emerging Players: Launch via Cologne-Bonn's underutilized DLR-adjacent test infrastructure to bypass Ottobrunn's saturated qualification pipeline. Target Earth observation payload electronics as the most penetrable segment, where optical miniaturization creates white-space for silicon germanium process entrants. Go-to-market angle: CSRD-aligned supply chain carbon accounting differentiation for EU institutional procurement frameworks. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier Bavarian subsystem specialists because prime contractor revenue concentration above 70% on two accounts creates distressed exit pressure for founder-owned firms. Five-to-ten year viability hinges on securing qualified foundry access before domestic capacity investments mature. Acquisition target archetype: radiation effects engineering boutiques with ECSS heritage and unresolved succession planning. Signal to watch: ITAR-EU equivalency negotiation breakthrough enabling US prime contractor supply chain re-entry.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Partnership | Secures qualified rad-hard fabrication slots through French-US alliances, reducing 18-24 month lead times for Bavarian suppliers. |
| Photonic Integrated Circuit Qualification | Opens Earth observation constellation revenue streams via Munich-Ottobrunn research-to-manufacturing pipeline integration. |
| CSRD Carbon Accounting Adoption | Creates procurement differentiation for German suppliers bidding on EU Green Deal-aligned institutional frameworks. |
| Defense Channel Certification | Expands classified procurement access under European strategic autonomy rearmament investment programs. |
| North Rhine-Westphalia Test Hub Expansion | Reduces qualification cost burden for new entrants via proximity to DLR Cologne facilities and underutilized environmental test infrastructure. |
Research Methodology
Direct dialogue with ESA procurement officers, Bavarian prime contractor supply chain directors, radiation effects engineering specialists, and KBA certification auditors grounded qualitative findings in operational reality. Secondary validation drew from ECSS standard revision documentation, EU Space Programme framework agreements, BSI technical bulletins, and customs records for space-grade palladium and tantalum imports. Bottom-up component demand modeling triangulated against top-down constellation deployment forecasts.
Segmentation outputs across product type, technology, application, and end-user dimensions informed revenue allocation across the projection horizon. CAGRs derived from fitted adoption curves for GaN power electronics and optical inter-satellite link terminals, cross-referenced against prime contractor disclosed procurement pipelines. Industry-specific forecast inputs included IRIS² satellite deployment schedules and DLR research funding allocations for electric propulsion control electronics.
Several conditions sit outside the modeled scope, including ITAR-EU equivalency negotiation outcomes, domestic foundry construction timelines, and conflict-mineral supply chain disruptions from geopolitical events. Forecasts embed assumptions about ECSS certification protocol stability and prime contractor dual-sourcing policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Management Solutions Market
Space
North America Spacesuit Market
Space
LAMEA Space As a Service Market
Space
UK Space Propulsion System Market
Space
Mexico Space Electronics Market
Space
Space Frame Market
Space
Space on Board Computing Platform Market
Space
Japan Space Electronics Market
Space
Space-Based Solar Power Market
Space
Spain Space Electronics Market
Space
Space Wheel Market
Space
Space Debris Monitoring Market
Space
Asia-Pacific Space Electronics Market
Space
Canada Space Electronics Market
Space
Space Transportation Market
Space
Space Blanket Market