
 Orbital Spaceflight Market | 2026-2036
Orbital Spaceflight Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Spaceflight Market Analysis
Defense and intelligence agencies are redrawing procurement patterns in the orbital spaceflight sector, displacing traditional science-driven missions as the dominant buyer archetype. SpaceX leverages reusable rocket architectures to compress launch costs and capture national security contracts. Northrop Grumman sustains its position in cargo resupply through the Cygnus spacecraft and ongoing NASA Commercial Resupply Services agreements. Lockheed Martin anchors government mission assurance with heavy-lift vehicles and deep-space human-rated systems.
Orbital spaceflight encompasses the launch and operation of craft achieving velocities exceeding orbital velocity, typically employing staged rocket propulsion with specific impulse ratings above 300 seconds in vacuum conditions, to deliver payloads into sustained Earth orbit or beyond. Reusable rockets dominate capital deployment and launch cadence, while satellite deployment missions generate the highest volume of contracted flights. Space tourism and research missions remain nascent segments with concentrated margin pools tied to specialized capsule designs.
The Federal Aviation Administration Office of Commercial Space Transportation licenses U.S. launch operations, while NASA sets human-rating standards that gate access to crewed missions. The U.S. Space Force's National Security Space Launch program imposes additional certification requirements that filter viable competitors. Stakeholders must monitor how evolving orbital debris mitigation rules from the FCC and international coordination bodies reshape vehicle design priorities and operational licensing timelines.
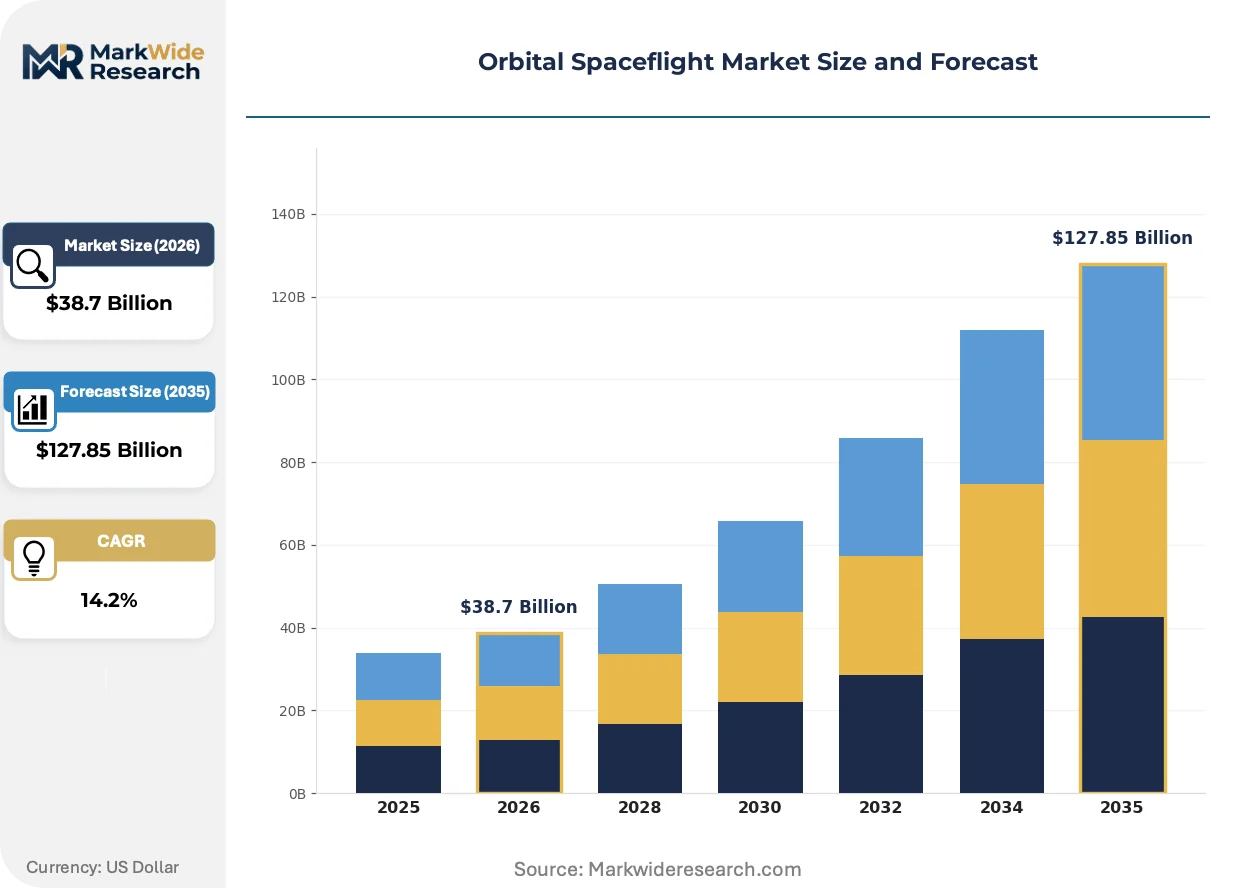
Market Dynamics
Reusable rocket architectures are compressing launch economics and redrawing competitive boundaries across the orbital spaceflight sector, forcing legacy expendable systems into niche heavy-lift missions while national security procurement tilts toward rapid-turnaround providers.
Growth Catalysts
- Streamlined FAA Certification Pathways:The Federal Aviation Administration Office of Commercial Space Transportation has accelerated launch licensing timelines, enabling higher flight cadence for commercial operators and reducing pre-mission regulatory overhead.
- Satellite Constellation Expansion:Commercial broadband and Earth observation operators are contracting record launch volumes to deploy phased orbital arrays, creating sustained demand for medium-lift vehicles with rapid reflight capability.
- Stainless-Steel Propellant Tanks:Switching from aluminum-lithium alloys to cryogenic-grade stainless steel is simplifying manufacturing, improving thermal properties, and enabling faster production scaling for next-generation launch vehicles.
Market Restraints
- Launch Site Concentration:Active orbital launch infrastructure concentrates at Cape Canaveral Space Force Station and Vandenberg Space Force Base, creating geographic chokepoints and range scheduling bottlenecks during high-cadence windows.
- Engine Supply Constraints:Domestic production of full-flow staged-combustion engines remains limited to a single qualified supplier, exposing the market to single-source risk for high-performance propulsion systems.
- Orbital Debris Liability Exposure:FCC rules requiring collision avoidance and post-mission disposal are extending mission insurance costs and complicating operational planning for constellation operators.
Strategic Opportunities
- India's Emerging Launch Capacity:The Indian Space Research Organisation is opening its launch facilities to commercial payloads under revised foreign satellite launch policies, creating alternative access to equatorial and polar orbits.
- In-Space Manufacturing:Microgravity production of fiber-optic cables, pharmaceutical crystals, and advanced alloys represents nascent demand for dedicated orbital platforms with crew-tended laboratory capabilities.
- Space-Based Solar Power Transmission:Japan's METI-funded demonstration missions are validating microwave power beaming from geostationary orbit, potentially opening utility-scale energy markets to orbital infrastructure providers.
Industry Challenges
- Human-Rating Certification Timelines:NASA's crew vehicle qualification requirements demand extensive abort testing and integrated system validation, extending development schedules and capital lockup periods for new entrants.
- Propulsion Engineering Talent Scarcity:The specialized workforce for turbopump design, combustion instability analysis, and regenerative cooling channel machining remains concentrated among legacy aerospace employers, constraining expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orbital Spaceflight Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Space Shuttle, Space Capsule, Spaceplane, Reusable Rocket Launch Provider: Government Agency, Private Company, Space Alliance, International Consortium Mission Type: Satellite Deployment, Research Mission, Space Tourism, Cargo Resupply Technology: Rocket Propulsion, Hybrid Propulsion, Ion Drive, Electromagnetic Launch |
| Companies Covered | Intuitive Machines, Northrop Grumman, SpaceX, L3Harris, RTX, Rocket Lab, Lockheed Martin, Redwire, Planet Labs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Spaceflight Market Emerging Trajectories
Propulsion architecture, orbital traffic management, and payload integration methods are undergoing simultaneous transformation, with each shift altering how vehicles are certified, financed, and operated across mission profiles.
Full-flow staged-combustion cycle engines are decomposing the traditional trade-off between sea-level thrust and vacuum efficiency. SpaceX's Raptor and Blue Origin's BE-4 are replacing gas-generator and staged-combustion heritage designs across new vehicle programs. Defense and commercial operators are accelerating adoption timelines as these engines demonstrate reusability beyond ten flights, compressing the economic viability window for expendable alternatives.
The FCC's updated orbital debris mitigation rules are mandating shorter post-mission disposal timelines and collision avoidance system certification. Satellite operators must now demonstrate passivation and controlled reentry capability prior to license grant. Constellation planners in the United States are redesigning spacecraft for autonomous maneuvering and allocating propellant budgets for deorbit burns, increasing platform mass and complexity.
Integration service contracts are displacing traditional launch service agreements as the dominant commercial arrangement. Payload providers now procure end-to-end mission management encompassing licensing, range coordination, and orbital insertion rather than purchasing raw launch capacity. This shift concentrates margin with vertically integrated operators capable of managing regulatory interfaces, with the transformation most visible among European Earth observation agencies and Asian telecommunications consortia.
Orbital Spaceflight Market Segmentation
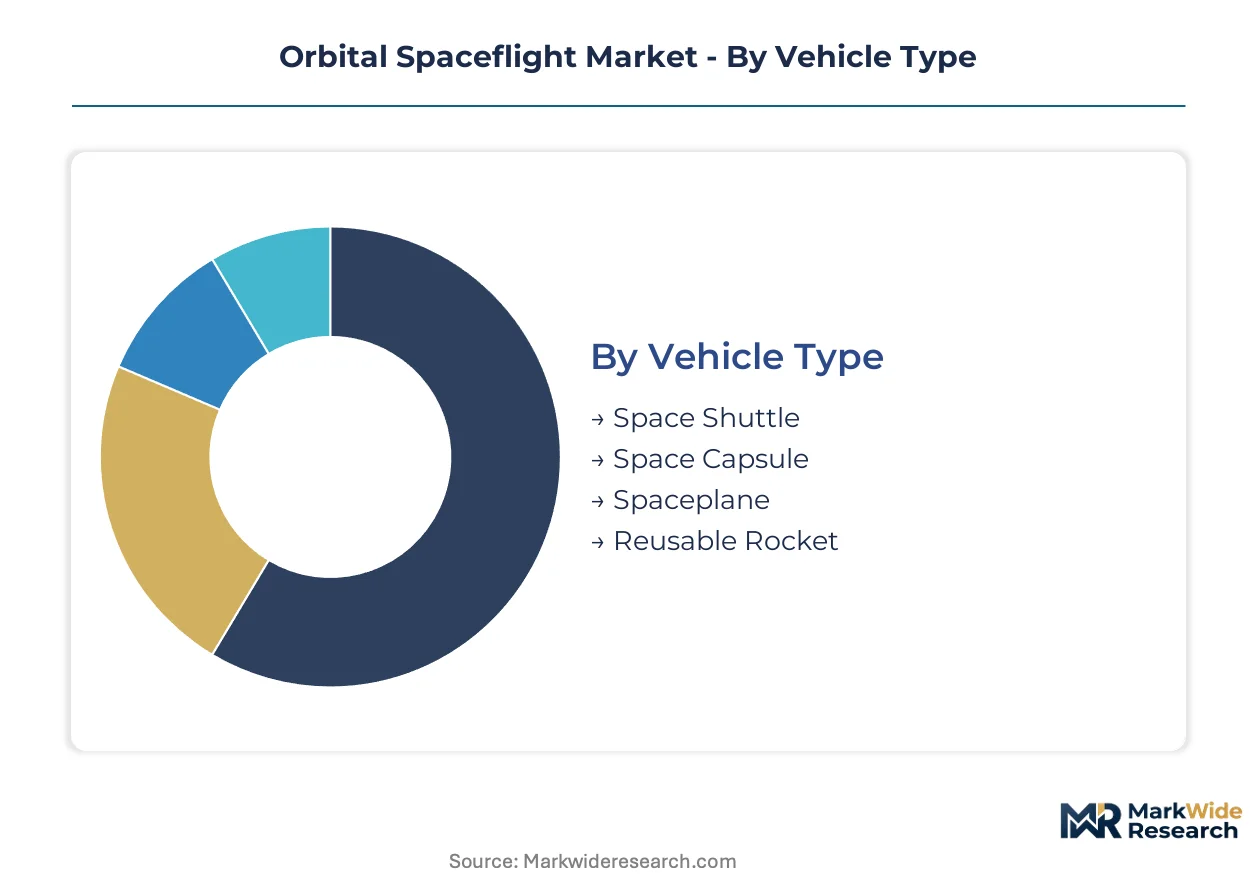
Segmentation in orbital spaceflight reveals how regulatory frameworks, certification requirements, and procurement channels fragment demand across vehicle classes and operational models. Understanding these divisions exposes where capital concentrates and which technology pathways command premium pricing.
Vehicle Type:
FAA Part 450 licensing and NASA human-rating standards create divergent compliance burdens across vehicle architectures, with crewed systems facing multi-year qualification timelines absent from cargo-only platforms.
- Reusable Rocket:Stainless-steel propellant tanks and full-flow staged-combustion engines enable rapid reflight cadence. Commercial constellation operators in the United States contract these systems for satellite deployment missions, though engine supply constraints limit qualified suppliers.
- Space Capsule:Crew-rated pressure vessels with integrated launch abort systems serve NASA Commercial Crew and Commercial Resupply Services contracts. Human-rating certification timelines extend development schedules, concentrating orders with incumbents possessing validated thermal protection and life support systems.
- Space Shuttle:Retired NASA fleet exemplifies winged orbital vehicle architecture with cross-range capability. No operational systems currently occupy this segment; heritage designs inform reusable spaceplane development programs.
- Spaceplane:Horizontal takeoff and runway landing configurations promise airline-style operations. Suborbital tourism vehicles and proposed point-to-point transport concepts populate this emerging category, with FAA experimental permits governing flight testing.
Reusable rockets handle the majority of throughput; spaceplanes are expanding most quickly on share as horizontal landing architectures mature.
Launch Provider:
Cost tier differentiation separates vertically integrated operators with captive manufacturing from consortium arrangements pooling development risk across national boundaries.
- Private Company:SpaceX and Blue Origin internalize engine production, vehicle integration, and launch operations. Rapid turnaround capabilities and price compression have captured national security launch contracts previously awarded to legacy providers.
- Government Agency:NASA, ISRO, and ESA maintain sovereign launch capacity for science and crewed missions. Procurement restrictions and technology transfer policies limit commercial access to these facilities.
- Space Alliance:United Launch Alliance combines Lockheed Martin and Boeing heritage vehicles under unified management. Cost-plus contracting structures and assured access commitments sustain this model despite higher per-launch pricing.
- International Consortium:Multinational partnerships distribute development costs and guarantee launch rights to participant nations. Ariane 6 and Soyuz-5 programs exemplify this structure, with procurement governed by intergovernmental agreements.
Private companies command the steepest expansion trajectory; government agencies retain anchor demand for crewed exploration missions.
Mission Type:
Customer type fragmentation separates high-volume, price-sensitive constellation operators from margin-rich specialized missions requiring dedicated platform configurations.
- Satellite Deployment:Phased orbital array construction for broadband and Earth observation networks generates sustained launch demand. FCC licensing and orbital debris mitigation rules extend mission planning complexity for constellation operators.
- Cargo Resupply:Pressurized and unpressurized logistics to orbital stations require rendezvous, proximity operations, and berthing capabilities. NASA Commercial Resupply Services contracts anchor this segment with multi-year service agreements.
- Research Mission:Microgravity experiments, technology demonstrations, and educational payloads occupy secondary capacity on rideshare missions. Dedicated laboratory platforms remain limited to ISS access and emerging commercial station concepts.
- Space Tourism:Suborbital and orbital crewed experiences command premium pricing from high-net-worth individuals. FAA commercial spaceflight participant regulations and informed consent requirements shape operator liability frameworks.
Satellite deployment generates the highest flight volume; space tourism is gaining share fastest as capsule designs achieve reusability milestones.
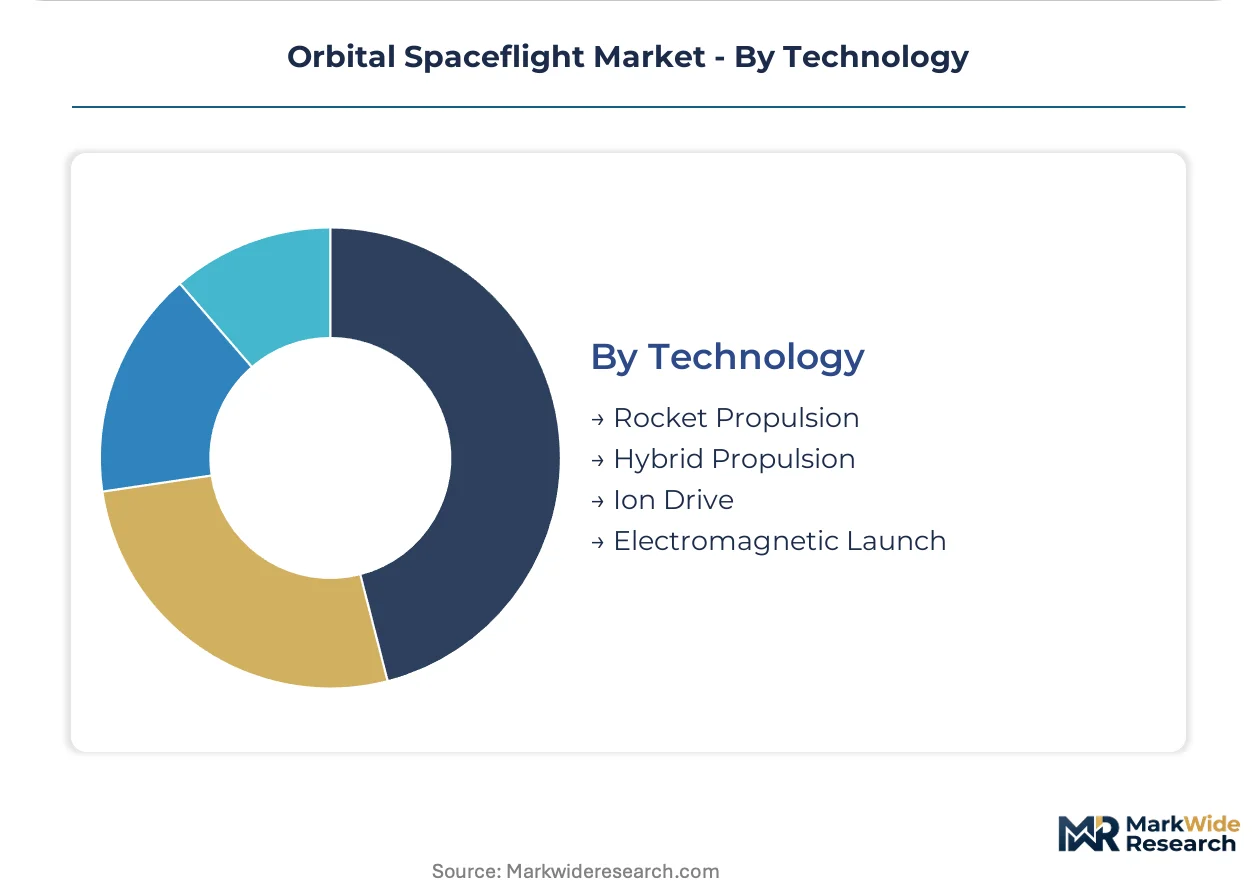
Technology:
Supply concentration in propulsion engineering talent and manufacturing infrastructure constrains which technology pathways achieve commercial scale.
- Rocket Propulsion:Chemical engines with specific impulse ratings above 300 seconds in vacuum dominate orbital insertion. Full-flow staged-combustion cycles are displacing gas-generator designs across new vehicle programs.
- Ion Drive:Solar-electric propulsion systems with high specific impulse enable efficient orbital transfer and station-keeping. Deep-space missions and geostationary satellite repositioning constitute primary applications.
- Hybrid Propulsion:Combined liquid-solid systems offer throttleability and safety advantages for crewed applications. Limited operational heritage restricts adoption to suborbital and small-lift vehicle programs.
- Electromagnetic Launch:Ground-based kinetic energy transfer concepts remain experimental, with hypersonic research applications preceding orbital velocity demonstrations. No commercial launches have employed this architecture.
Rocket propulsion handles the majority of throughput; ion drive is climbing the fastest as satellite operators prioritize fuel efficiency over thrust.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States launch providers export orbital insertion services to European telecommunications operators, Japanese Earth observation agencies, and emerging Asian constellation ventures. This trade corridor concentrates capital deployment in Cape Canaveral and Vandenberg while driving regulatory harmonization pressures across export control regimes.
United States
National Security Space Launch contracts and Commercial Crew program awards anchor domestic demand. The FAA Office of Commercial Space Transportation licenses launch operations from Cape Canaveral Space Force Station, Vandenberg Space Force Base, and the emerging Spaceport America facility. Texas hosts engine test infrastructure and manufacturing campuses where stainless-steel propellant tank production scales for next-generation reusable vehicles.
China
State-directed constellation deployment and sovereign crewed space station operations drive launch cadence. The Ministry of Industry and Information Technology licenses commercial launch providers under evolving national security frameworks. Hainan Province hosts the Wenchang Satellite Launch Center, where equatorial launch advantages support heavy geostationary missions and lunar transfer trajectories.
India
ISRO's commercial arm Antrix and emerging private launch ventures capture rideshare demand from European and Southeast Asian satellite operators. The Department of Space revised foreign satellite launch policies to permit greater commercial access. Satish Dhawan Space Centre in Andhra Pradesh processes record launch volumes as international payload providers seek polar and low-inclination orbits.
Japan
METI-funded space-based solar power demonstration missions and ISS resupply obligations sustain institutional demand. The Cabinet Office Space Development Strategy Headquarters coordinates regulatory frameworks for emerging private launch operators. Tanegashima Space Center and Uchinoura Space Center concentrate launch infrastructure, with Hokkaido hosting suborbital test facilities for reusable vehicle development.
Germany
ESA member state obligations and commercial small satellite manufacturing generate downstream launch demand. The Federal Aviation Office coordinates with EASA on commercial spaceflight regulatory development. Bavaria hosts payload integration facilities and propulsion component suppliers serving Ariane 6 and emerging small-lift vehicle programs.
Orbital Spaceflight Market Vendor Landscape
Player mix skews toward vertically integrated private operators with captive engine production and launch site control. Market structure concentrates around three to four qualified providers for national security missions, with a longer tail of emerging ventures targeting small-lift and specialized orbital services. Strategic archetypes include full-stack integrators with reusable architectures, heritage defense contractors with cost-plus government relationships, and specialist component suppliers. Competitive moves center on rapid reflight capability demonstration and human-rating certification achievement.
Within the full-stack integrator tier, SpaceX and Blue Origin exemplify capital-intensive vertical integration strategies, while Northrop Grumman occupies a position bridging heritage defense contracting with commercial resupply services. Rocket Lab represents the emerging specialist archetype, concentrating on small-lift rapid response and dedicated orbital insertion for constellation operators. Lockheed Martin anchors the mission assurance segment through heavy-lift vehicle heritage and deep-space human-rated system development.
| Leading Market Players |
|---|
| Intuitive Machines |
| Northrop Grumman |
| SpaceX |
| L3Harris |
| RTX |
| Rocket Lab |
| Lockheed Martin |
| Redwire |
| Planet Labs |
| Others |
Supply Flow & Price Mechanics
FAA Part 450 licensing requirements gate both supplier qualification and launch pricing tiers simultaneously, compressing margins for uncertified operators while rewarding rapid-reflight providers with national security contract premiums. This regulatory filter concentrates pricing power with vertically integrated launch operators who have absorbed the capital burden of human-rating and range coordination capabilities.
Pricing Analysis
Full-flow staged-combustion engine pricing sits at a 40-60% premium over gas-generator heritage designs, while stainless-steel tank architectures undercut aluminum-lithium manufacturing costs by simplifying production scaling. Three-tier pricing structure across premium, standard, and economy levels separates NASA crew missions from commercial constellation batch launches and rideshare secondary payloads. Cost compression in the medium-lift tier intensifies because SpaceX's reflight cadence has reset customer expectations for per-kilogram pricing. Commercial constellation operators exhibit the highest price sensitivity, whereas defense agencies prioritize mission assurance over unit economics.
Supply Chain Analysis
Strategic stockpiling of cryogenic propellants and engine turbopump assemblies dominates inventory strategy, as production lead times for full-flow staged-combustion systems extend beyond typical mission booking windows. Manufacturing concentrates in the United States, with stainless-steel tank fabrication centered in Texas and engine assembly anchored in California. Raw material dependencies include nickel-based superalloys for turbopumps, cryogenic-grade stainless steel for propellant tanks, and solid rocket motor propellants for launch abort systems. Single-source vulnerability for qualified full-flow staged-combustion engines exposes the supply chain to disruption. Distribution runs through vertically integrated launch operators who control pad access and range scheduling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reusable rocket architectures are compressing launch economics at a pace unseen since the jet age, with FAA streamlined certification pathways serving as the primary regulatory accelerant. Stakeholders must position against this disruption vector or face margin erosion from rapid-reflight competitors.
For Market Incumbents: Fortify human-rating certification moats by accelerating NASA Commercial Crew validation timelines and securing multi-year national security launch commitments before emerging entrants achieve full-flow staged-combustion engine qualification. Capacity addition in Texas and Florida launch corridors preserves pad scheduling priority against range congestion. Engine supply backward integration insulates against single-source turbopump vulnerability.
For New Entrants and Emerging Players: FAA experimental permit fast-tracks enable suborbital flight testing and iterative vehicle development without full orbital licensing burdens. India's emerging commercial launch capacity offers the most penetrable geography for rideshare payload aggregation, with ISRO's revised foreign satellite policies reducing regulatory friction. Target dedicated small-lift missions for constellation operators who prioritize schedule certainty over heavy-lift economies of scale.
For Investors and Strategic Acquirers: National Security Space Launch Phase 3 contract awards reshape the acquisition landscape by validating which operators can sustain assured access commitments. Long-term viability hinges on demonstrated reflight counts exceeding ten missions per vehicle core. Acquisition target archetype: specialist propulsion component suppliers with full-flow staged-combustion engineering talent. The signal to watch is FAA launch license issuance velocity as inflection indicator for regulatory capacity expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Reflight Capability Demonstration | SpaceX's 15+ mission core reuse validates rapid-turnaround economics for national security contracts. |
| Human-Rating Certification Investment | NASA Commercial Crew validation gates access to premium crewed mission pricing tiers. |
| Engine Production Scale-Up | Blue Origin's BE-4 manufacturing expansion addresses single-source supply risk for heavy-lift vehicles. |
| Launch Site Diversification | Spaceport America and Vandenberg expansion reduces Cape Canaveral range scheduling bottlenecks. |
| In-Space Manufacturing Partnership | Redwire's orbital laboratory platforms capture nascent microgravity production demand from pharmaceutical developers. |
Methodological Framework
The analysis maps reusable rocket architectures, crew-rated capsule systems, satellite deployment missions, and emerging spaceplane concepts, each validated through launch operations directors, propulsion engineering leads, constellation procurement managers, and FAA licensing officers. Primary interviews with vehicle integration specialists and range safety officers combined with secondary validation against FAA launch license databases, NASA contract award announcements, and U.S. Space Force procurement disclosures. Bottom-up launch cadence modeling and top-down market sizing triangulate volume estimates across vehicle classes and mission profiles.
Consistency checks against external benchmarks validated projection outputs against disclosed national security launch contract values and commercial constellation operator procurement patterns. The analytical framework segments by vehicle type, launch provider category, mission profile, and propulsion technology across the projection horizon. CAGRs derive from regression analysis of historical launch volumes against constellation deployment schedules and crewed mission cadence assumptions. Industry-specific forecast inputs include stainless-steel tank production scaling curves and full-flow staged-combustion engine qualification timelines.
The analysis sits within stated boundaries; outcomes outside sustained FAA licensing velocity and national security procurement continuity would require recalibration. Forecasts reflect documented assumptions regarding engine supply expansion and orbital debris mitigation compliance costs. Revision becomes warranted when launch site concentration crosses congestion thresholds or when alternative launch provider qualification disrupts incumbent pricing structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Africa Space Propulsion System Market
Space
Near Space Robotics Market
Space
North America Spacesuit Market
Space
Japan Space Electronics Market
Space
Space Traffic Management Market
Space
China Space Electronics Market
Space
Spacecraft Market
Space
Deep Space Robotics Market
Space
Spain Space Electronics Market
Space
Space on Board Computing Platform Market
Space
Space Mobile Service Market
Space
US Space Launch Services Market
Space
Asia-Pacific Space Electronics Market
Space
Space As a Service Market
Space
France Space Electronics Market
Space
Rocket Launchpad Market