
 Space Designing Market | 2026-2036
Space Designing Market Size, Share, and Industry Trends Forecast 2026-2036
Space Designing Market Insights
Hospitality venues is pivoting toward immersive experiential design as post-pandemic travelers prioritize destination uniqueness over standardized accommodations. SpaceX leverages its engineering heritage to inform speculative habitat concepts that blur aerospace and terrestrial spatial logic. Boeing anchors commercial aviation-derived cabin ergonomics into premium hospitality fit-outs. Lockheed Martin competes on defense-sector security protocols translated into corporate workspace access control aesthetics.
Space designing encompasses the systematic planning of interior, exterior, and landscape environments to optimize human occupancy, circulation, and sensory engagement through scale proportioning, material specification, and lighting choreography. The discipline employs computational fluid dynamics for airflow simulation and photometric analysis for circadian lighting calibration across commercial and residential programs. Experiential design commands premium margin pools as brands commission temporary installations with compressed fabrication timelines. Corporate workspaces retain the largest addressable volume, though cultural installations represent the fastest-growing application as municipalities fund public realm renewal. Residential living maintains mature growth trajectories tied to housing cycle volatility rather than structural demand expansion.
LEED certification from the US Green Building Council shapes material specifications across North American projects, while the EU Green Deal's building renovation targets mandate embodied carbon disclosure for European commissions. ISO 19650 building information modeling standards govern data exchange protocols between architects, contractors, and facility operators in cross-border developments. Stakeholders must monitor regulatory divergence between jurisdictions operating dissimilar carbon accounting frameworks as design firms scale internationally.
Market Dynamics
Smart building technology integration is compressing design-to-occupancy timelines while LEED certification requirements are redefining material procurement criteria across premium commercial projects.
Growth Catalysts
- EU Green Deal building renovation targets:Mandated embodied carbon disclosure is accelerating specification of low-carbon materials in European commissions.
- Hospitality experiential design:Post-pandemic destination uniqueness prioritization is driving accelerated adoption of immersive spatial concepts.
- Computational fluid dynamics:Airflow simulation adoption is expanding from aviation-derived cabin design into corporate workspace wellness programs.
Market Restraints
- Specialized lighting fixture supply concentration:Circadian-calibrated luminaire production clusters in German and Japanese manufacturing bases.
- LEED consultant certification backlog:USGBC-accredited professional scarcity extends project initiation timelines by 4-8 weeks.
- Cross-border BIM data friction:ISO 19650 implementation gaps between North American and European project teams create coordination delays.
Strategic Opportunities
- Public realm cultural installations:Municipal funding for urban renewal is opening fastest-growing application vertical with compressed fabrication timelines.
- Photometric analysis software convergence:Integration with IoT sensor networks enables real-time circadian lighting adjustment in smart buildings.
- India's PLI scheme for construction technology:Domestic manufacturing incentives for prefabricated interior systems reduce import dependency for luxury hospitality fit-outs.
Industry Challenges
- Computational design talent scarcity:Parametric modeling and generative design capabilities concentrate in architecture schools with limited graduate pipeline.
- Legacy facility management system integration:Smart building sensor networks require costly middleware development for 1990s-era HVAC infrastructure.
- Multi-jurisdiction carbon accounting reconciliation:Design firms scaling internationally face divergent embodied carbon measurement protocols between US and EU frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Designing Market |
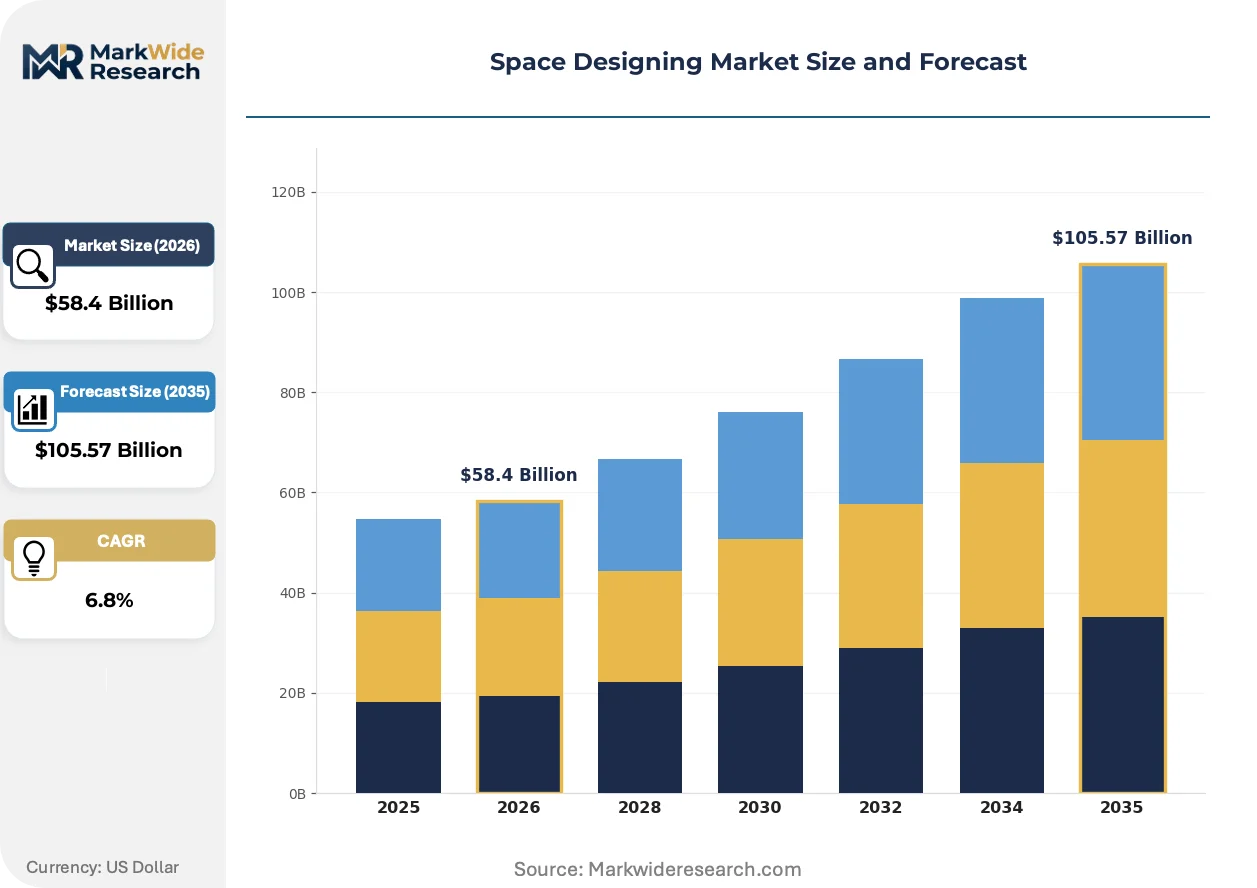
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Design Type: Interior, Exterior, Landscape, Conceptual, Experiential Application: Residential Living, Corporate Workspaces, Hospitality Venues, Cultural Installations, Educational Facilities Client Type: Individual Homeowners, Commercial Developers, Event Organizers, Public Institutions, Creative Agencies Materials Used: Wood, Metal, Glass, Composite Fabrics, Recyclable Polymers |
| Companies Covered | Boeing, Lockheed Martin, Northrop Grumman, Airbus Defence and Space, Thales Alenia Space, SpaceX, Ball Aerospace, L3Harris Technologies, Maxar Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Designing Market Trends and Innovations
Digital twin workflows are collapsing the traditional design-bid-build sequence while material science advances enable structural elements to double as environmental conditioning surfaces.
Generative design algorithms are rewriting spatial planning economics by automating code-compliant layout optimization that previously consumed 30-40% of schematic phase hours. Large hospitality operators are deploying these tools across multi-property renovation programs. The compression is enabling smaller studios to compete on complex commercial programs previously reserved for established firms with deeper bench strength.
REACH substance restrictions on flame retardants are forcing specification pivots toward bio-based intumescent coatings in European commercial interiors. The regulation is eliminating incumbent halogenated chemistries from certified projects. German and French fit-out contractors are accelerating supplier qualification programs to maintain LEED and BREEAM dual-certification eligibility.
Corporate real estate departments are unbundling design services from single-source architecture contracts, instead direct-engaging experiential specialists for amenity zones while retaining traditional firms for core workspace compliance. The model fragments project revenue across more vendors. United States technology sector headquarters expansions exhibit this pattern most visibly, with amenity budgets now representing 25-35% of total interior capital allocation.
Space Designing Market Segmentation
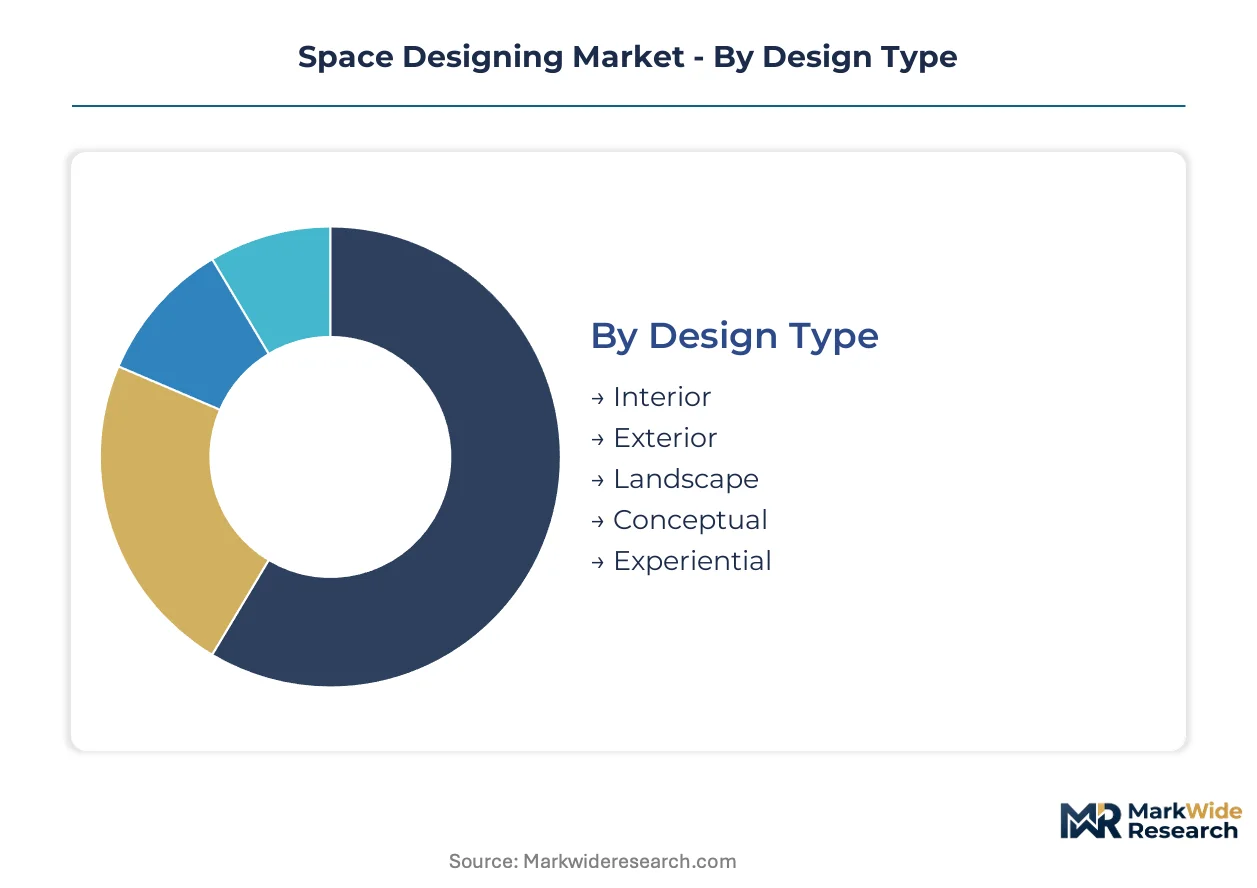
Segmentation in space designing reveals divergent capital deployment patterns across design philosophies, end-use applications, and procurement channels. Understanding these splits enables vendors to align capability investments with where premium fees concentrate versus where volume scales.
Design Type:
Capital intensity escalates sharply from conceptual visualization through to fully realized experiential environments with integrated technology infrastructure.
- Interior:Encompasses enclosed spatial programming with material specification, lighting choreography, and HVAC integration for occupancy optimization. Corporate workspace renovation cycles in the United States sustain the largest addressable volume, though compressed timelines pressure fee structures.
- Experiential:Temporary or permanent immersive installations employing projection mapping, sensor networks, and adaptive acoustics for brand activation. Hospitality venues in destination markets command premium margins as post-pandemic travelers prioritize uniqueness over standardization.
- Exterior:Façade systems and building envelope design balancing thermal performance with aesthetic expression.
- Landscape:Site planning integrating hardscape, vegetation, and drainage for human circulation patterns.
- Conceptual:Preliminary spatial studies and feasibility visualization without construction documentation obligation.
Interior work absorbs the bulk of installed capacity; experiential is expanding most quickly.
Application:
Procurement sophistication varies dramatically between private residential clients with emotional decision drivers and institutional purchasers with compliance mandates.
- Corporate Workspaces:LEED certification requirements and smart building integration reshape procurement criteria across developed markets. United States technology sector headquarters expansions unbundle amenity design from core workspace contracts, fragmenting vendor engagement.
- Hospitality Venues:Immersive spatial concepts with compressed fabrication timelines and destination-specific narratives. EU Green Deal embodied carbon disclosure mandates accelerate specification of low-carbon materials in European commissions.
- Residential Living:Mature growth tied to housing cycle volatility rather than structural demand expansion.
- Cultural Installations:Municipal funding for public realm renewal opens fastest-growing application vertical.
- Educational Facilities:Circadian lighting calibration and airflow simulation adoption from aviation-derived cabin design.
Corporate workspaces generate the deepest project pipelines; cultural installations are climbing the fastest.
Client Type:
Contract structure and payment security diverge between individual clients with limited recourse and institutional purchasers with multi-year framework agreements.
- Commercial Developers:Multi-property programs with standardized design packages and volume pricing expectations.
- Public Institutions:ISO 19650 BIM compliance and cross-border data exchange protocols for international developments.
- Creative Agencies:Temporary installation expertise with rapid fabrication networks and brand narrative integration.
- Individual Homeowners:Luxury residential development sustaining premium design fees in concentrated metropolitan markets.
- Event Organizers:Compressed timeline specialists with modular system inventories for rapid deployment.
Commercial developers anchor volume commitments; creative agencies are gaining share fastest.
Materials Used:
Supply chain geography and regulatory compliance burden vary substantially across material categories, with European REACH restrictions forcing specification pivots.
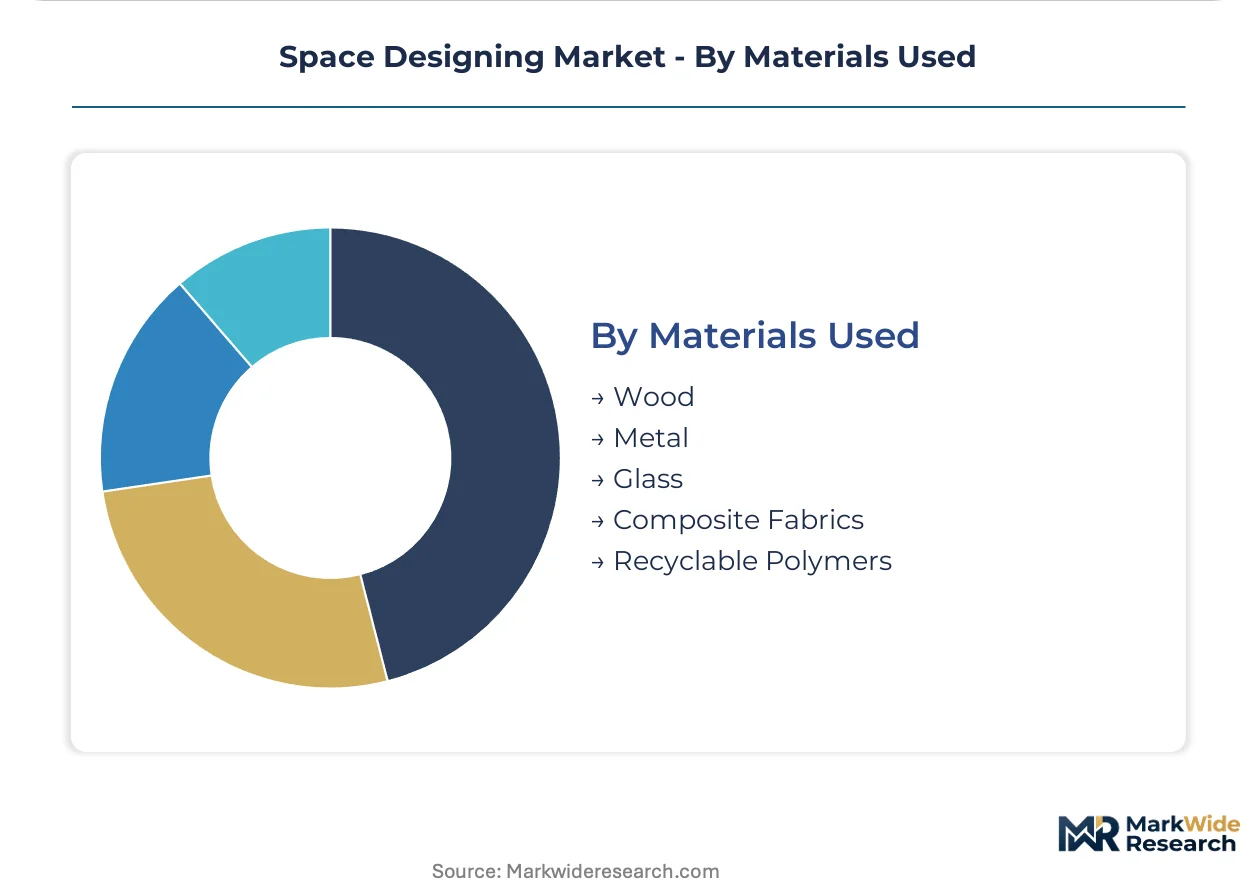
- Wood:Mass timber and engineered lumber with embodied carbon advantages for LEED and BREEAM dual-certification eligibility.
- Recyclable Polymers:Bio-based alternatives to halogenated flame retardants eliminated by ECHA substance restrictions.
- Metal:Structural and finish applications with recycled content verification for green building compliance.
- Glass:Photometric performance specification for circadian lighting calibration in smart building integration.
- Composite Fabrics:Tensile structures and acoustic panels with complex end-of-life disposal protocols.
Wood dominates sustainable specification; recyclable polymers are scaling most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in distressed US census tracts concentrate space designing investment through capital gains tax deferrals, while Dubai's Design District freehold framework attracts experiential studios serving Gulf hospitality developments.
United States
Corporate headquarters renovation cycles in Austin, Seattle, and New York Metro sustain premium design fees. The Inflation Reduction Act's commercial building efficiency tax credits accelerate smart building retrofits. Miami's Design District anchors experiential hospitality fit-out specialization serving Latin American developer clients.
Germany
Engineering-intensive industrial workspace redesigns in Stuttgart and Munich drive demand for computational fluid dynamics integration. ECHA REACH substance restrictions on halogenated flame retardants force specification pivots toward bio-based intumescent coatings. Berlin's Kreuzberg district clusters experiential design studios serving European cultural institution clients.
China
Dual carbon goals mandate embodied carbon disclosure for commercial developments in Shanghai and Shenzhen. MIIT smart building standards accelerate IoT sensor network integration in premium office towers. Beijing's 798 Art District hosts temporary installation specialists serving brand activation briefs with compressed timelines.
India
PLI scheme incentives for construction technology reduce import dependency for luxury hospitality prefabricated systems. BIS building code harmonization accelerates ISO 19650 BIM adoption in cross-border developments. Mumbai's Lower Parel corridor concentrates experiential design capacity serving domestic hotel operator expansion programs.
United Arab Emirates
NEOM giga-project specifications attract experiential design firms with sovereign-backed payment security and compressed fabrication timelines. Dubai's building code modernization mandates smart building infrastructure in new commercial developments. Abu Dhabi's Saadiyat Island cultural district anchors museum and gallery fit-out specialization.
Space Designing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with aerospace heritage firms commanding premium positioning in experiential hospitality while regional studios capture volume interior work through developer framework agreements. The vendor base organizes around three archetypes: engineering-conglomerate design divisions, independent experiential studios, and technology-integrated workspace specialists. Consolidation pressure intensifies as hospitality operators seek single-source accountability for complex immersive installations. Dominant competitive moves include strategic partnerships between lighting technology vendors and design studios, plus selective backward integration into prefabricated interior system manufacturing.
Within the engineering-conglomerate tier, Boeing and Lockheed Martin occupy positions translating aerospace-derived spatial logic into terrestrial applications. SpaceX exemplifies the technology-integrated archetype through speculative habitat concepts that blur aerospace and terrestrial design conventions. These three firms anchor premium-market positioning by leveraging defense-sector security protocols and commercial aviation ergonomics into corporate workspace and hospitality fit-out procurement.
| Leading Market Players |
|---|
| Boeing |
| Lockheed Martin |
| Northrop Grumman |
| Airbus Defence and Space |
| Thales Alenia Space |
| SpaceX |
| Ball Aerospace |
| L3Harris Technologies |
| Maxar Technologies |
| Others |
Pricing and Supply Chain Analysis
Parametric modeling talent concentration in Berlin and Stuttgart amplifies labor-cost differentials that separate premium experiential studios from volume interior contractors across European commissions. USGBC-accredited professional scarcity in North America extends project initiation timelines, compressing fee structures for standardized workplace renovation programs while immersive hospitality fit-outs sustain margin premiums.
Pricing Analysis
Compressed fabrication timelines command premium pricing multiples as hospitality operators prioritize rapid amenity deployment over cost optimization. Three-tier pricing structure across premium experiential, standard interior, and economy conceptual design levels stratifies by certification tier and smart building integration complexity. Pricing pressure stems from generative design algorithm commoditization that collapses schematic phase hours for code-compliant layout optimization. Corporate real estate departments exhibit highest price sensitivity through unbundled procurement models, while sovereign-backed Gulf developments demonstrate lowest sensitivity given payment security guarantees.
Supply Chain Analysis
Direct-to-hospitality-operator channels handle hyperscale experiential installation demand, bypassing traditional architecture firm intermediaries. Circadian-calibrated luminaire production clusters in Germany and Japan, while mass timber engineered lumber sources from Austrian and Canadian forestry operations. REACH substance restrictions on halogenated flame retardants force specification pivots toward bio-based intumescent coatings, creating regulatory-driven supply friction. Distribution runs through qualified contractor networks for LEED and BREEAM dual-certification eligibility, with prefabricated interior system manufacturing scaling under India's PLI scheme incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around single-source accountability demands from hospitality operators, with weaker studios facing elimination from complex immersive installation procurement as aerospace-conglomerate design divisions capture premium positioning.
For Market Incumbents: Lock in experiential hospitality operator relationships through sovereign-backed project pipelines in Gulf developments, while accelerating backward integration into prefabricated interior system manufacturing to defend against algorithm-driven commoditization of schematic design services. Certification investment in USGBC LEED and BREEAM dual-eligibility maintains procurement gatekeeping power as EU Green Deal embodied carbon disclosure mandates intensify. For New Entrants and Emerging Players: Launch via municipal cultural installation funding verticals where compressed fabrication timeline specialization commands premium positioning absent entrenched incumbent relationships. India's PLI scheme-supported domestic manufacturing for luxury hospitality fit-outs offers the most penetrable geography, with direct-engagement models targeting technology sector headquarters amenity zones as the optimal go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with technology-integrated workspace specialists given photometric analysis software convergence with IoT sensor networks as the catalyst for smart building premium capture. Long-term viability favors studios with parametric modeling capabilities and generative design algorithm deployment across multi-property renovation programs. Monitor hospitality operator consolidation into single-source procurement models as the inflection signal for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabricated Systems | Captive supply of modular interior components compresses fabrication timelines for hospitality fit-outs. |
| Photometric Software-IoT Convergence | Real-time circadian lighting adjustment commands premium pricing in smart building integration mandates. |
| Dual Certification Investment | LEED and BREEAM eligibility maintains procurement access as EU Green Deal restrictions intensify. |
| Municipal Cultural Installation Specialization | Public realm renewal funding opens fastest-growing vertical with compressed timeline premium capture. |
| Generative Design Algorithm Deployment | Automated code-compliant layout optimization collapses schematic phase economics for volume competition. |
Research Methodology
SEC 10-K filings from aerospace-conglomerate design divisions, USGBC project certification databases, and EU Green Deal building renovation target disclosures formed the secondary backbone, cross-referenced with primary interviews involving hospitality operator procurement directors, experiential design studio principals, and smart building technology integration specialists. Bottom-up project pipeline aggregation across corporate workspace renovation cycles and hospitality development programs was triangulated against top-down market sizing from construction technology trade flows and interior fit-out capital expenditure tracking.
Bottom-up modeling segmented the market by design type, application vertical, client archetype, and material specification across the projection horizon, with CAGRs derived from housing cycle volatility correlations, LEED certification penetration trajectories, and smart building retrofit acceleration patterns. Computational fluid dynamics adoption curves and photometric analysis software licensing data informed experiential design premium capture assumptions throughout the modeling period.
Regulatory divergence between US and EU carbon accounting frameworks, REACH substance restriction implementation delays, and USGBC consultant certification backlog fluctuations are the dominant revision risks to base case assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Oscillator Market
Space
Space Radar Market
Space
Space Technology (Spacetech) Market
Space
Space Debris Monitoring Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Management Solutions Market
Space
Space on Board Computing Platform Market
Space
China Space Propulsion System Market
Space
Japan Space Electronics Market
Space
Africa Space Propulsion System Market
Space
Space Debris Monitoring and Removal Market
Space
Space Travel Market
Space
France Space Electronics Market
Space
Mexico Space Electronics Market
Space
Rocket Launchpad Market
Space
Space As a Service Market