
 South Africa Hemodialysis and Peritoneal Dialysis Market | 2026-2036
South Africa Hemodialysis and Peritoneal Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Hemodialysis and Peritoneal Dialysis Market Intelligence
The gap between premium dialysis systems and commodity consumables is hardening across South African procurement channels. Fresenius Medical Care AG & Co. KGaA leverages its integrated manufacturing footprint to dominate hemodialysis machine supply to public hospitals. Baxter International Inc anchors the peritoneal dialysis solutions segment through established distribution partnerships with private dialysis chains. Nipro Corporation competes aggressively on dialysis filter pricing, sustaining volume share among cost-conscious state buyers.
Hemodialysis and peritoneal dialysis encompass renal replacement therapies that filter metabolic wastes and excess fluids from blood when native kidney function fails, typically requiring sessions lasting three to five hours with ultrafiltration rates calibrated to patient fluid status. Hemodialysis Machines represent the most capital-intensive product category, with margin pools concentrated among manufacturers offering integrated consumable ecosystems. Automated Peritoneal Dialysis is expanding fastest among Home Care Patients, driven by nursing shortages and patient preference for nocturnal therapy in urban centers like Johannesburg and Durban.
The South African Health Products Regulatory Authority governs device registration and clinical safety standards for dialysis equipment, while the National Department of Health shapes procurement through centralized tender mechanisms and NHI transition planning. BIS certification requirements for imported medical devices add compliance layers that favor established suppliers with local regulatory expertise. Stakeholders must monitor NHI implementation timelines and provincial health budget allocations to anticipate shifts between public tender volumes and private insurance-reimbursed care.
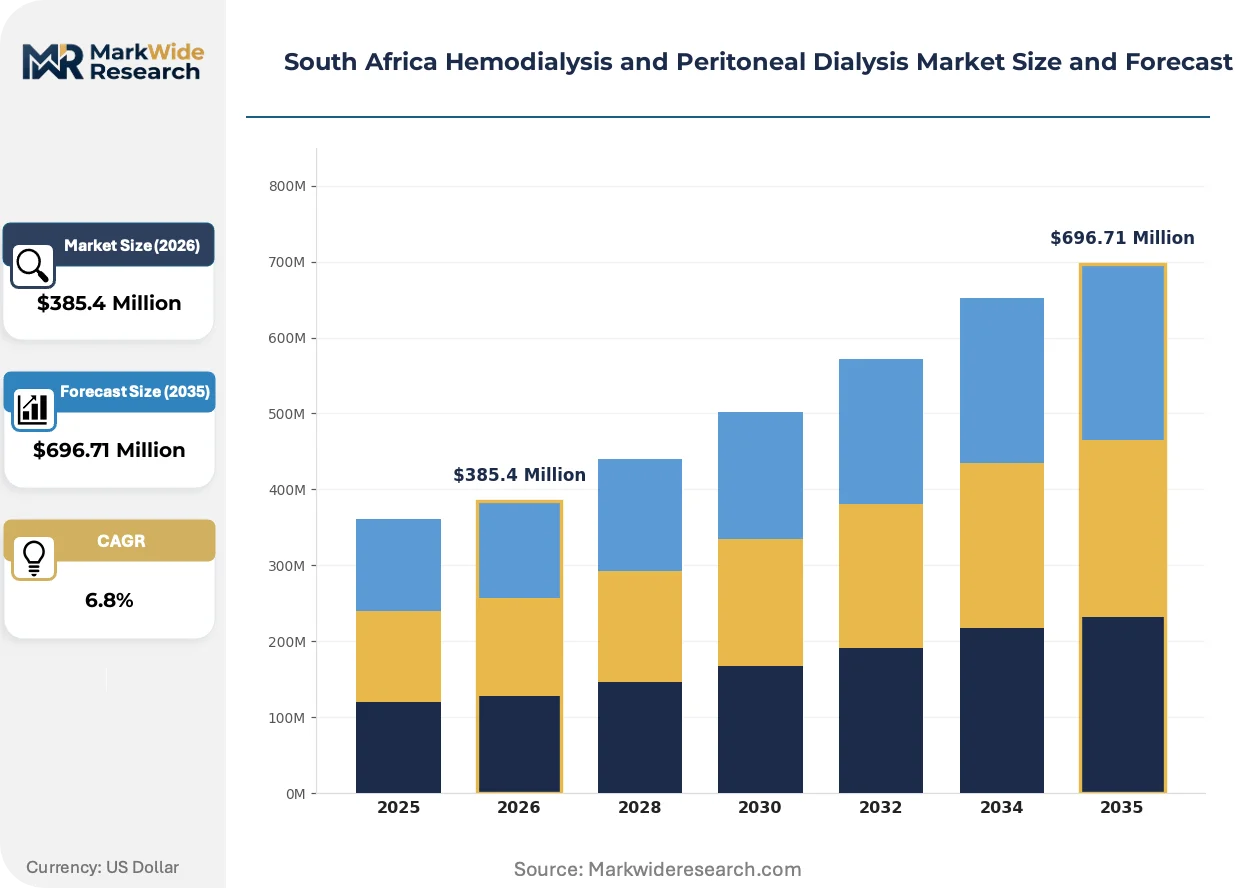
Market Dynamics
The National Health Insurance policy framework is compressing procurement timelines while expanding automated dialysis technology deployment across South African public hospital networks.
Growth Catalysts
- Automated Peritoneal Dialysis technology:Home care patients in Gauteng and KwaZulu-Natal provinces are adopting nocturnal therapy systems that reduce nursing dependency and clinic congestion.
- National Health Insurance transition:The centralized procurement framework is expanding dialysis service coverage to previously underserved provincial health systems.
- Nursing shortage pressures:Hospital administrators are redirecting capital toward self-administered home dialysis modalities to offset critical staffing gaps in renal units.
Market Restraints
- Import dependency for dialysis machines:BIS certification requirements and foreign exchange volatility constrain equipment availability and inflate landed costs for public tenders.
- Concentrated supplier base:Hemodialysis machine supply concentrates among integrated manufacturers with captive consumable ecosystems, limiting price competition.
- Water infrastructure limitations:Rural clinic dialysis expansion faces structural barriers from inconsistent ultrapure water supply systems required for safe hemodialysis delivery.
Strategic Opportunities
- Western Cape home dialysis penetration:Private insurance reimbursement expansion in Cape Town and surrounding municipalities creates white space for remote patient monitoring services.
- Telemedicine-integrated dialysis:Convergence of remote monitoring platforms with automated peritoneal systems enables real-time clinical oversight without physical clinic visits.
- Provincial health budget reallocation:Eastern Cape and Limpopo health departments are redirecting funds toward decentralized dialysis access points outside major urban centers.
Industry Challenges
- Biomedical technician scarcity:Specialized training programs for hemodialysis machine maintenance lag behind equipment deployment rates in expanding provincial facilities.
- SAHPRA registration timelines:Extended device approval cycles for imported dialysis consumables delay market entry and compress supplier margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Hemodialysis and Peritoneal Dialysis Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Machines, Dialysis Chairs, Peritoneal Dialysis Solutions, Dialysis Filters End User: Hospitals, Dialysis Centers, Home Care Patients, Specialty Clinics Technology: Conventional Dialysis, Continuous Ambulatory Peritoneal Dialysis, Automated Peritoneal Dialysis, Online Hemodiafiltration Distribution Channel: Direct Sales, Retail Pharmacies, Online Sales, Medical Supply Distributors |
| Companies Covered | Nipro Corporation, Nikkiso Co., Ltd., Fresenius Medical Care AG & Co. KGaA, Toray Medical, Medtronic plc, Baxter International Inc, DaVita Healthcare Partners, Inc., Life Healthcare Group, B. Braun Avitum AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Hemodialysis and Peritoneal Dialysis Market Strategic Shifts & Innovations
Automation and remote connectivity are displacing conventional clinic-based dialysis models across South African healthcare delivery systems, with regulatory frameworks accelerating technology substitution.
Automated Peritoneal Dialysis systems are automating fluid exchange cycles and treatment parameter adjustments that previously required manual nursing intervention. Home care patients in Johannesburg and Durban metropolitan areas are adopting these systems at accelerating rates. The technology is automating nighttime therapy delivery while compressing daytime clinic capacity constraints.
SAHPRA's evolving medical device registration pathways are streamlining approval processes for software-integrated dialysis equipment while tightening post-market surveillance requirements. Manufacturers are restructuring regulatory submission strategies to accommodate real-world evidence collection mandates. The peritoneal dialysis solutions segment is most affected, with suppliers accelerating local clinical trial investments to secure priority review status.
Hospital procurement officers are consolidating vendor relationships around integrated equipment-consumable contracts that bundle machine placement with multi-year supply commitments. Independent distributors serving smaller private dialysis chains are losing share to direct manufacturer partnerships. This consolidation is most visible in KwaZulu-Natal, where provincial tender awards increasingly favor single-source agreements over fragmented multi-vendor arrangements.
South Africa Hemodialysis and Peritoneal Dialysis Market Segmentation
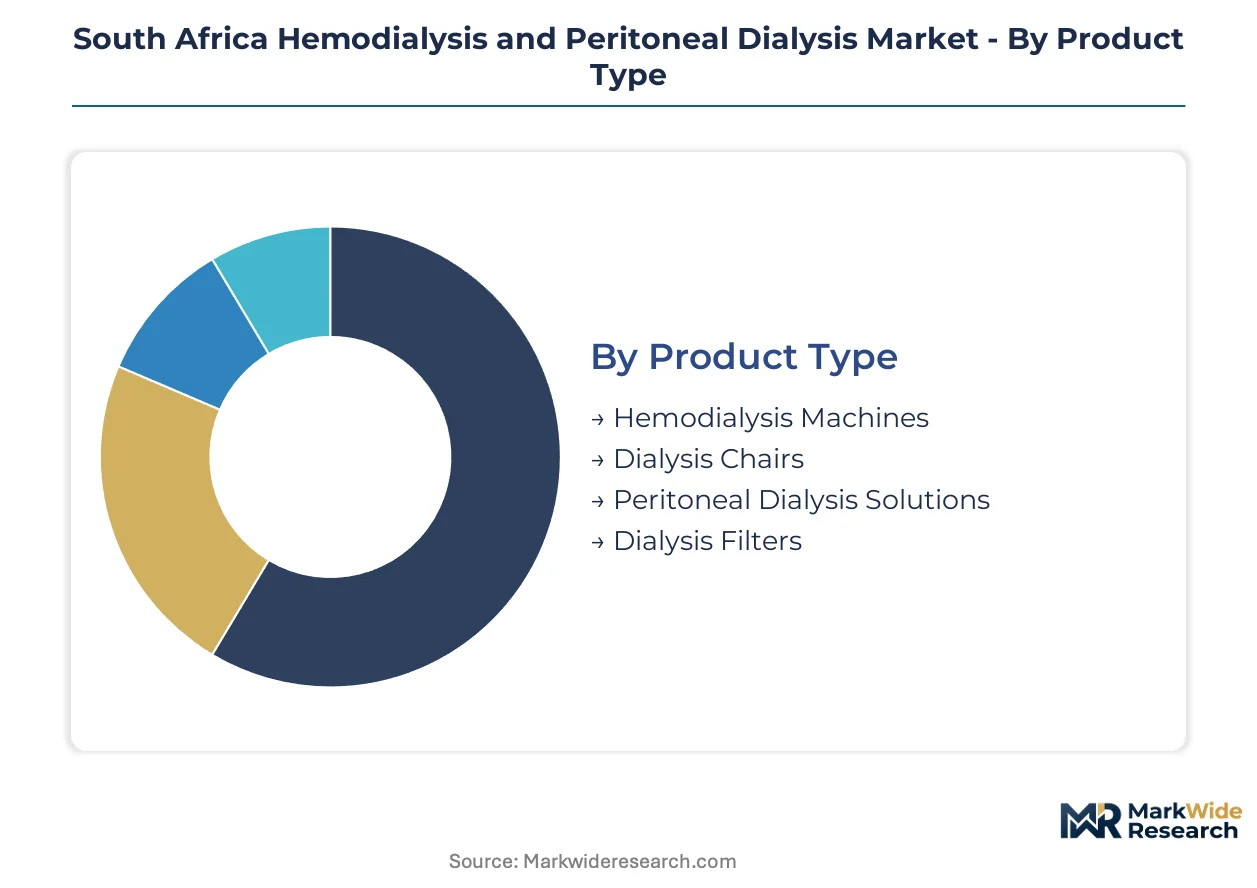
Segmentation reveals how capital deployment, clinical workflow, and procurement authority fragment across South Africa's dialysis delivery infrastructure. Each dimension exposes distinct margin pools and competitive access points for equipment suppliers and consumable manufacturers.
Product Type:
Capital intensity varies dramatically across this category, with electromechanical systems demanding tenfold higher upfront investment than disposable consumables.
- Hemodialysis Machines:These electromechanical systems integrate blood pumps, dialysate delivery modules, and safety monitoring circuits for extracorporeal renal replacement. Public hospital procurement in Gauteng and KwaZulu-Natal concentrates demand here, driven by NHI framework expansion of centralized dialysis services.
- Dialysis Filters:Hollow-fiber membrane cartridges manufactured from polysulfone or polyethersulfone mediate solute clearance and ultrafiltration during treatment sessions. State tender volumes dominate procurement, with cost-conscious buyers prioritizing filter pricing over proprietary machine compatibility.
- Peritoneal Dialysis Solutions:Sterile electrolyte and glucose formulations for intraperitoneal instillation.
- Dialysis Chairs:Reclining patient positioning systems with Trendelenburg capability for vascular access procedures.
Most installed capacity flows through Hemodialysis Machines. Expansion is steepest in Dialysis Filters.
End User:
Reimbursement authority and clinical risk tolerance create four distinct customer archetypes with divergent procurement behaviors.
- Hospitals:Acute care facilities managing inpatient renal failure and complex comorbidities requiring intensive monitoring. Provincial health departments in Eastern Cape and Limpopo are redirecting capital toward hospital-based dialysis expansion outside major urban centers.
- Home Care Patients:Self-administering individuals performing peritoneal dialysis in residential settings with remote clinical oversight. Johannesburg and Durban metropolitan adoption is climbing fastest, supported by nursing shortage pressures and patient preference for nocturnal therapy scheduling.
- Dialysis Centers:Outpatient facilities dedicated to chronic maintenance hemodialysis.
- Specialty Clinics:Nephrology-focused practices with limited procedure capacity.
Procurement volume concentrates in Hospitals. Patient volume is expanding most quickly among Home Care Patients.
Technology:
Automation sophistication and clinical labor substitution define the technology hierarchy, with fully automated systems commanding premium positioning.
- Automated Peritoneal Dialysis:Cycler devices automate fluid exchange cycles, drain timing, and fill volume calculations previously requiring manual nursing intervention. Home care patients in Gauteng and KwaZulu-Natal are adopting these systems at accelerating rates to reduce daytime clinic dependency.
- Online Hemodiafiltration:Advanced hemodialysis modality combining diffusive and convective clearance through high-volume ultrafiltration and sterile substitution fluid infusion. Private dialysis chains in Western Cape are deploying this technology to differentiate service offerings under expanded insurance reimbursement.
- Conventional Dialysis:Standard hemodialysis or manual peritoneal exchange without automation assistance.
- Continuous Ambulatory Peritoneal Dialysis:Manual daytime exchanges performed by patients without mechanical cycler support.
Clinical throughput runs heaviest through Conventional Dialysis. Technology substitution is proceeding fastest in Automated Peritoneal Dialysis.
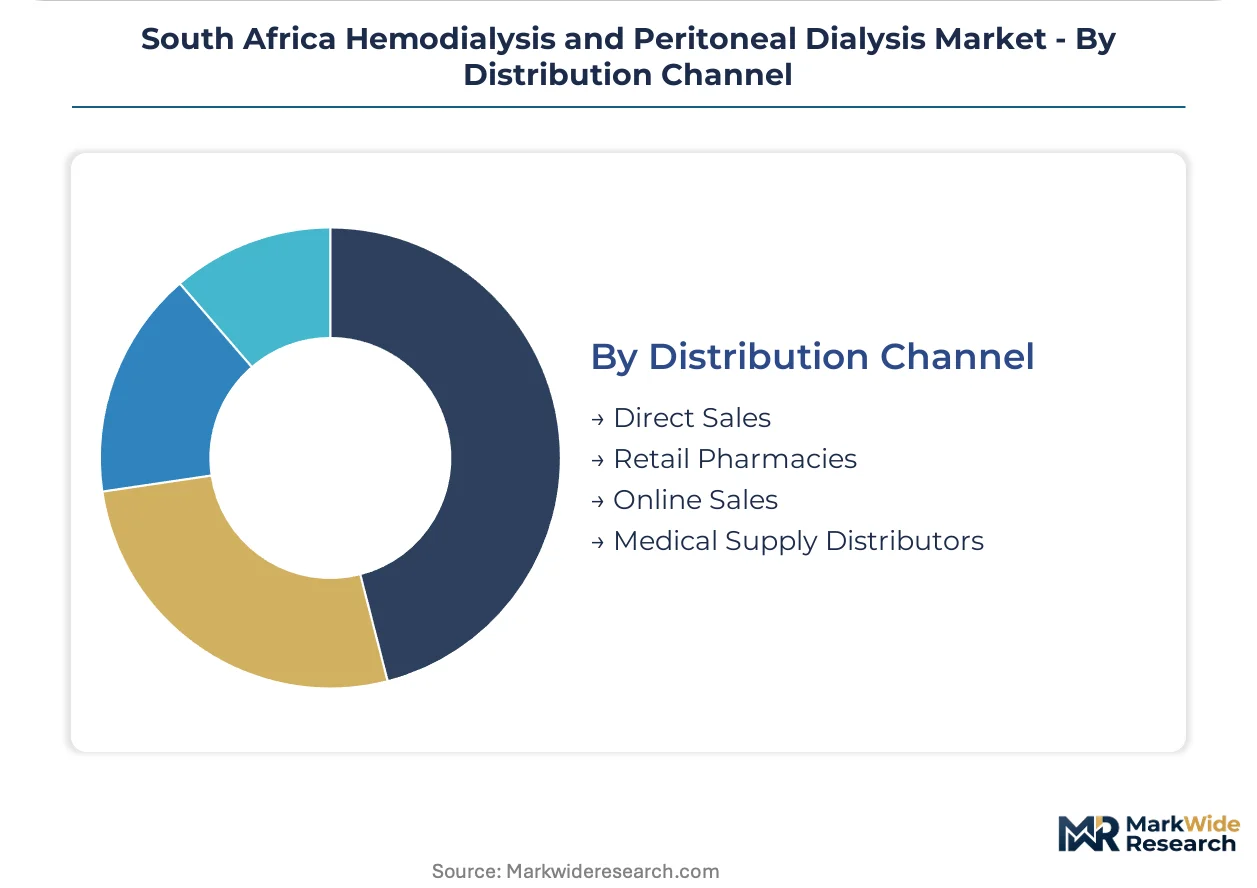
Distribution Channel:
Channel economics reflect equipment complexity, with capital goods favoring direct manufacturer relationships while consumables fragment across intermediaries.
- Direct Sales:Manufacturer-to-institution contracts for hemodialysis machines and multi-year consumable bundles. KwaZulu-Natal provincial tenders increasingly favor these arrangements over fragmented multi-vendor procurement.
- Medical Supply Distributors:Regional wholesalers stocking dialysis filters, solutions, and accessories for hospital and clinic replenishment. Independent distributors serving smaller private chains are losing share to direct partnerships as procurement consolidates.
- Retail Pharmacies:Community dispensaries supplying peritoneal dialysis solutions and patient accessories.
- Online Sales:E-commerce platforms for home dialysis supplies and remote patient monitoring peripherals.
Transaction value concentrates in Direct Sales. Channel development is advancing most rapidly through Medical Supply Distributors consolidating fragmented regional coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's dialysis market diverges sharply from peer African economies, with Gauteng and Western Cape provinces concentrating equipment deployment while Eastern Cape and Limpopo lag in per-capita access despite rising chronic kidney disease prevalence.
Gauteng
Johannesburg and Pretoria metropolitan clusters absorb the bulk of automated peritoneal dialysis deployments, driven by nursing shortages and patient preference for nocturnal home therapy. The National Health Insurance transition is compressing procurement timelines for public hospital hemodialysis expansion. Private dialysis chains in Sandton and Centurion are consolidating vendor relationships around integrated equipment-consumable contracts.
Western Cape
Cape Town anchors the highest private insurance reimbursement rates for dialysis services, creating white space for remote patient monitoring platforms. The provincial health department is redirecting capital toward decentralized access points outside the metropolitan core. Stellenbosch and Paarl medical clusters are piloting telemedicine-integrated peritoneal dialysis programs.
KwaZulu-Natal
Durban and surrounding municipalities are adopting automated peritoneal dialysis systems at accelerating rates to reduce daytime clinic congestion. Provincial tender awards increasingly favor single-source direct manufacturer agreements over fragmented multi-vendor procurement. The eThekwini health district is expanding hospital-based dialysis capacity for complex comorbidity cases.
Eastern Cape
Rural clinic expansion faces structural barriers from inconsistent ultrapure water supply systems required for safe hemodialysis delivery. The provincial health department is reallocating budgets toward decentralized dialysis access points in Mthatha and Gqeberha. Biomedical technician training programs lag behind equipment deployment rates in expanding facilities.
Limpopo
Polokwane and Tzaneen medical centers are redirecting provincial health funds toward hospital-based dialysis expansion outside major urban corridors. Import dependency for dialysis machines constrains equipment availability through BIS certification requirements and foreign exchange volatility. The province exhibits the widest gap between premium dialysis systems and commodity consumables in public procurement channels.
South Africa Hemodialysis and Peritoneal Dialysis Market Key Industry Players
Top-tier vendors anchor integrated equipment-consumable ecosystems, while mid-tier suppliers compete aggressively on filter pricing and regional distribution coverage. The supplier base concentrates among manufacturers with captive manufacturing footprints and established regulatory expertise before SAHPRA. Three archetypes dominate: integrated system providers bundling machines with multi-year supply commitments, consumable specialists competing on state tender pricing, and private dialysis chain operators controlling patient flow. Competitive moves center on procurement consolidation through direct hospital partnerships and regulatory submission acceleration for software-integrated devices.
Among Japan-based manufacturers, Nipro Corporation and Nikkiso Co., Ltd. occupy positions within the consumable and equipment tiers respectively, representing archetypes of cost-competitive filter supply and precision electromechanical system fabrication. Fresenius Medical Care AG & Co. KGaA anchors the integrated ecosystem model, exemplifying the bundled machine-placement and supply-contract strategy that KwaZulu-Natal provincial tenders increasingly favor. Baxter International Inc sits within the peritoneal dialysis solutions segment, representing established distribution partnership structures with private dialysis chains.
| Leading Market Players |
|---|
| Nipro Corporation |
| Nikkiso Co., Ltd. |
| Fresenius Medical Care AG & Co. KGaA |
| Toray Medical |
| Medtronic plc |
| Baxter International Inc |
| DaVita Healthcare Partners, Inc. |
| Life Healthcare Group |
| B. Braun Avitum AG |
| Others |
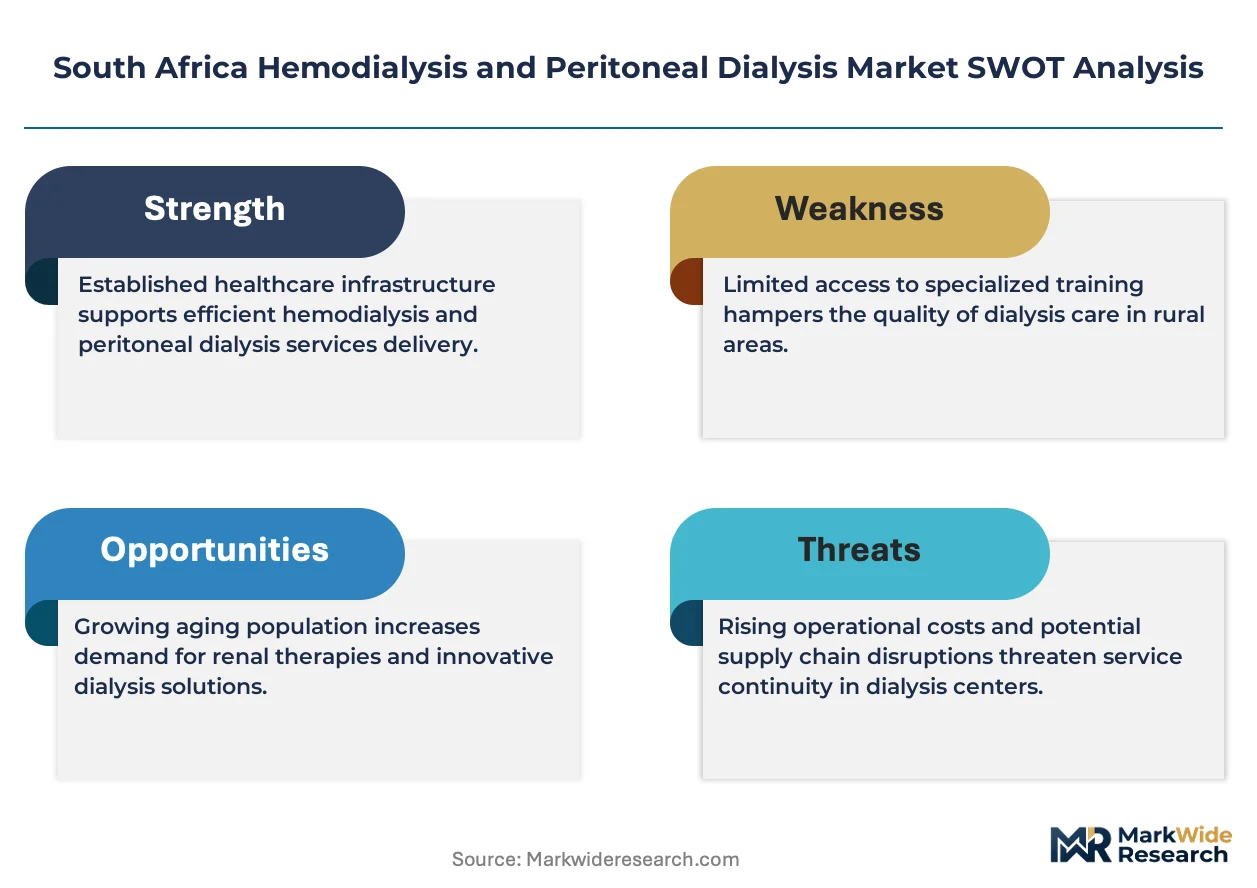
Cost & Logistics Intelligence
Biomedical technician scarcity in Eastern Cape and Limpopo widens labor-cost differentials between urban centers and rural provinces, compressing pricing-tier spreads for hemodialysis machine maintenance contracts while inflating premiums for remote service coverage.
Pricing Analysis
Bundled equipment-consumable contracts dominate KwaZulu-Natal provincial tenders, while unbundled filter procurement persists among cost-conscious state buyers prioritizing Nipro Corporation pricing over Fresenius Medical Care AG & Co. KGaA machine compatibility. Price differentiation rests on SAHPRA registration tier and after-sales service bundling. Cost compression in commodity consumables is intensifying because state tender volumes consolidate around lowest-bidder criteria. Public hospital procurement committees exhibit highest price sensitivity; private dialysis chains in Western Cape demonstrate lowest sensitivity due to insurance reimbursement expansion.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese electromechanical component suppliers for hemodialysis machines. Manufacturing draws from Germany, Japan, and China for precision pumps, dialysate delivery modules, and hollow-fiber membrane polymers. Supply chain risk centers on BIS certification delays for imported devices. Distribution runs through direct manufacturer-to-institution contracts for capital equipment, with medical supply distributors handling consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory compounder, with National Health Insurance transition timelines driving demand acceleration for automated dialysis technology deployment across public hospital networks.
For Market Incumbents: Acquire biomedical technician training capabilities to offset workforce scarcity threatening equipment uptime guarantees in Eastern Cape and Limpopo expansion sites. Deepen backward integration into hollow-fiber membrane production to defend filter pricing against Nipro Corporation cost aggression in state tenders. Prioritize SAHPRA registration acceleration for software-integrated devices before NHI procurement frameworks finalize.
For New Entrants and Emerging Players: Capture Western Cape remote patient monitoring white space created by private insurance reimbursement expansion outside Cape Town metropolitan core. Target telemedicine-integrated peritoneal dialysis programs in Stellenbosch and Paarl medical clusters where established distribution partnerships remain underdeveloped. Pursue direct-to-clinic go-to-market models bypassing consolidated KwaZulu-Natal provincial tender channels.
For Investors and Strategic Acquirers: Integrated dialysis service operators are the most active acquirer in this space, consolidating fragmented private clinic networks ahead of NHI reimbursement harmonization. Five-to-ten year viability hinges on positioning for public-private partnership structures under centralized procurement. Target acquisition archetype: regional distributors with SAHPRA regulatory expertise and established provincial health department relationships. Monitor NHI implementation timeline announcements as primary inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Registration Acceleration | Priority review status for software-integrated devices compresses market entry timelines before NHI procurement finalizes. |
| Biomedical Technician Training Programs | Specialized workforce development in Eastern Cape and Limpopo addresses equipment maintenance gaps threatening rural expansion. |
| Direct Manufacturer Partnerships | Single-source agreements with KwaZulu-Natal provincial health departments displace fragmented multi-vendor procurement structures. |
| Telemedicine Platform Integration | Remote monitoring convergence with automated peritoneal systems enables real-time clinical oversight in Johannesburg and Durban. |
| Backward Integration into Membrane Production | In-house hollow-fiber manufacturing defends filter pricing against commodity competition in state tender volumes. |
Research Approach
Coverage spans Gauteng, Western Cape, KwaZulu-Natal, Eastern Cape, and Limpopo, with primary inputs from each province's health infrastructure. The analysis combines structured interviews with hospital procurement officers, biomedical engineers, nephrology department heads, provincial health department planners, and private dialysis chain operators with secondary validation from SAHPRA device registration databases, National Department of Health tender records, and hospital procurement system disclosures. Bottom-up provincial capacity assessments triangulate against top-down National Health Insurance expenditure projections.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. The analytical framework models segmentation across product type, end user, technology, and distribution channel, with provincial regulatory cluster and NHI implementation phase as additional dimensions. CAGRs derive from installed base growth assumptions, replacement cycle compression, and technology substitution curves for automated peritoneal dialysis. Forecast inputs incorporate nursing shortage severity indices and provincial health budget reallocation patterns.
NHI implementation delays, foreign exchange volatility, and SAHPRA registration timeline extensions are the dominant revision risks. Forecasts reflect assumptions about policy continuity, equipment import certification efficiency, and rural water infrastructure investment pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Blood Dialyzer Market
Nephrology
Global Dialyzer Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Renal Stent Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Dialysis Centers Market
Nephrology
Dialysis Service Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market