
 Hemodialysis and Peritoneal Dialysis Market | 2026-2036
Hemodialysis and Peritoneal Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis and Peritoneal Dialysis Market Intelligence
The expansion of equipment leasing and service-based financing models for dialysis machines is fragmenting the competitive landscape for clinic operators. Fresenius Medical Care AG leverages its extensive network of dialysis centers and integrated product portfolio. Baxter International Inc. specializes in peritoneal dialysis and home-based care solutions. DaVita Inc. operates a large chain of outpatient dialysis centers, primarily in the United States, focusing on service delivery.
Hemodialysis and peritoneal dialysis are medical procedures that remove waste products and excess fluid from the blood of patients with kidney failure. The process relies on diffusion across a semipermeable membrane, either an external dialyzer in hemodialysis or the patient's own peritoneum in peritoneal dialysis, to filter toxins like urea. Treatment for end-stage renal disease represents the most mature application, generating consistent demand for dialysis machines and dialyzers. The home-based delivery mode, while smaller, is the fastest-growing segment, driven by patient preference and technological advancements in portable systems.
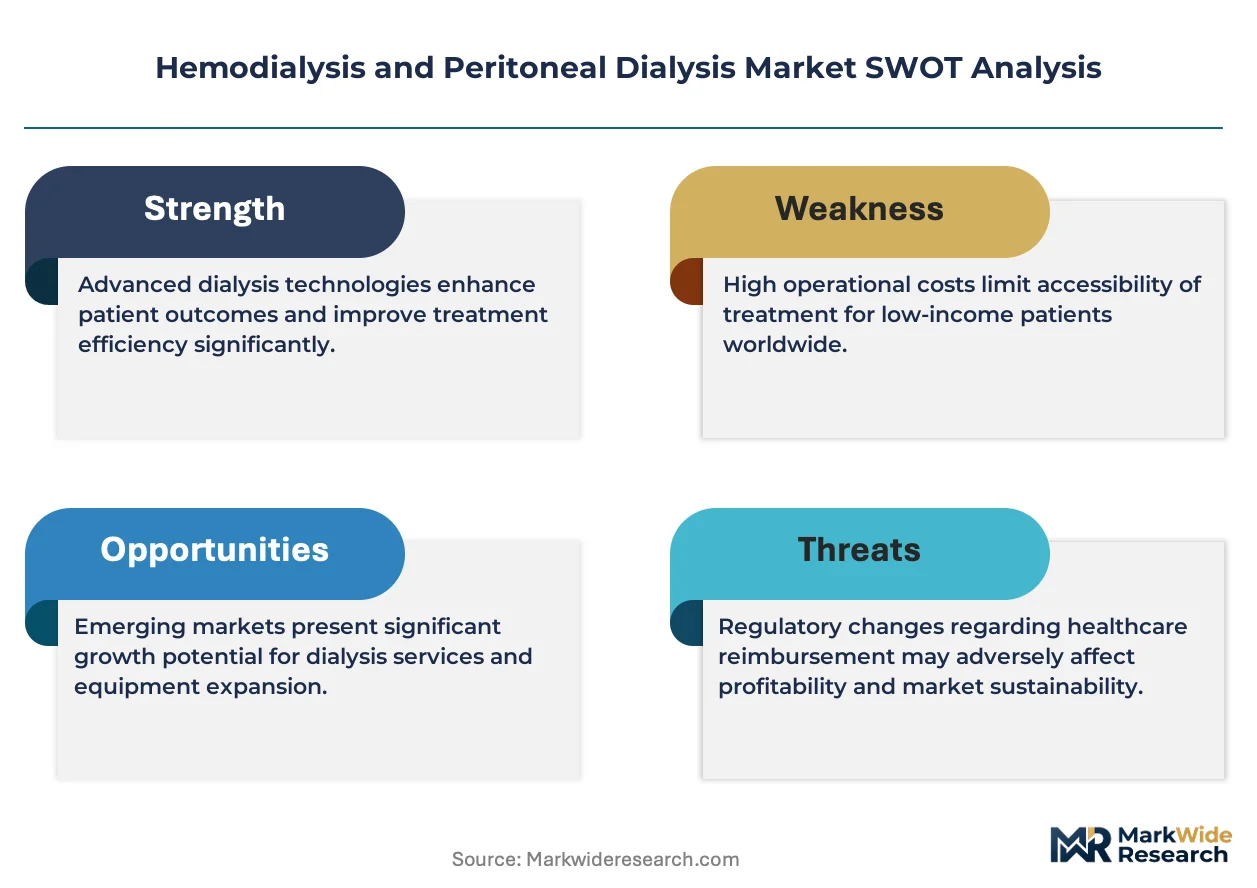
Market access and product safety are governed by stringent regulatory frameworks, including the US Food and Drug Administration (FDA) for device approvals and the European Union's Medical Device Regulation (MDR) for CE marking. In Japan, the Pharmaceuticals and Medical Devices Agency (PMDA) oversees standards for dialysis equipment. Stakeholders must navigate evolving reimbursement policies and the strategic choice between investing in high-volume in-center services versus developing infrastructure for decentralized home care.
Market Dynamics
The central structural force shaping the dialysis market is the deliberate shift in care delivery from centralized, high-volume clinics to decentralized home settings. This transition is driven by patient preference for autonomy and technological advancements in portable systems, compelling a strategic re-evaluation of infrastructure investment and service models.
Growth Catalysts
- Favorable Reimbursement Policies:In the United States, payment models that incentivize home dialysis are accelerating adoption by making it a financially viable option for both patients and providers, directly supporting market expansion.
- Advancements in Dialysis Membranes:The development of more biocompatible and efficient semipermeable membranes, often using novel polymers, improves patient outcomes by reducing inflammation and enhancing toxin clearance during treatment.
- Rising ESRD Prevalence:An aging global population and increasing rates of diabetes and hypertension, particularly in developed nations like Japan and Germany, create a consistent and growing patient base requiring renal replacement therapy.
Market Restraints
- High Cost of Treatment:The significant expense associated with dialysis equipment, consumables, and recurring procedures presents a substantial barrier to access, especially in emerging economies with limited public healthcare funding.
- Stringent Regulatory Pathways:Manufacturers face long and costly approval processes for new devices, with bodies like the US FDA and the EU's MDR imposing rigorous requirements for clinical data and post-market surveillance.
- Inadequate Infrastructure:In many developing regions, the lack of reliable access to clean water and stable electricity severely limits the feasibility of establishing and operating both in-center and home dialysis programs.
Strategic Opportunities
- Telehealth and Remote Monitoring:Integrating connected home dialysis machines with telehealth platforms offers a significant opportunity to improve patient monitoring, enhance adherence, and provide timely clinical support without requiring clinic visits.
- Expansion in Underserved Geographies:There is considerable white space for market entry and expansion in regions like Southeast Asia and Latin America, where the incidence of kidney disease is rising but access to dialysis remains low.
- Development of Wearable Devices:Investment in R&D for a wearable artificial kidney could revolutionize treatment by offering continuous, ambulatory dialysis, representing a paradigm shift from current intermittent therapies.
Industry Challenges
- Shortage of Skilled Professionals:A global deficit of trained nephrologists, dialysis nurses, and biomedical technicians creates operational bottlenecks and limits the capacity to expand services, particularly in rural areas.
- Patient Training and Adherence:The complexity of home dialysis equipment requires extensive patient and caregiver training, and ensuring long-term adherence and proper technique remains a significant operational hurdle for providers.
- Cybersecurity of Connected Devices:As dialysis machines become more connected for remote monitoring, ensuring the security of patient data and protecting devices from cyber threats becomes a critical and complex challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis and Peritoneal Dialysis Market |
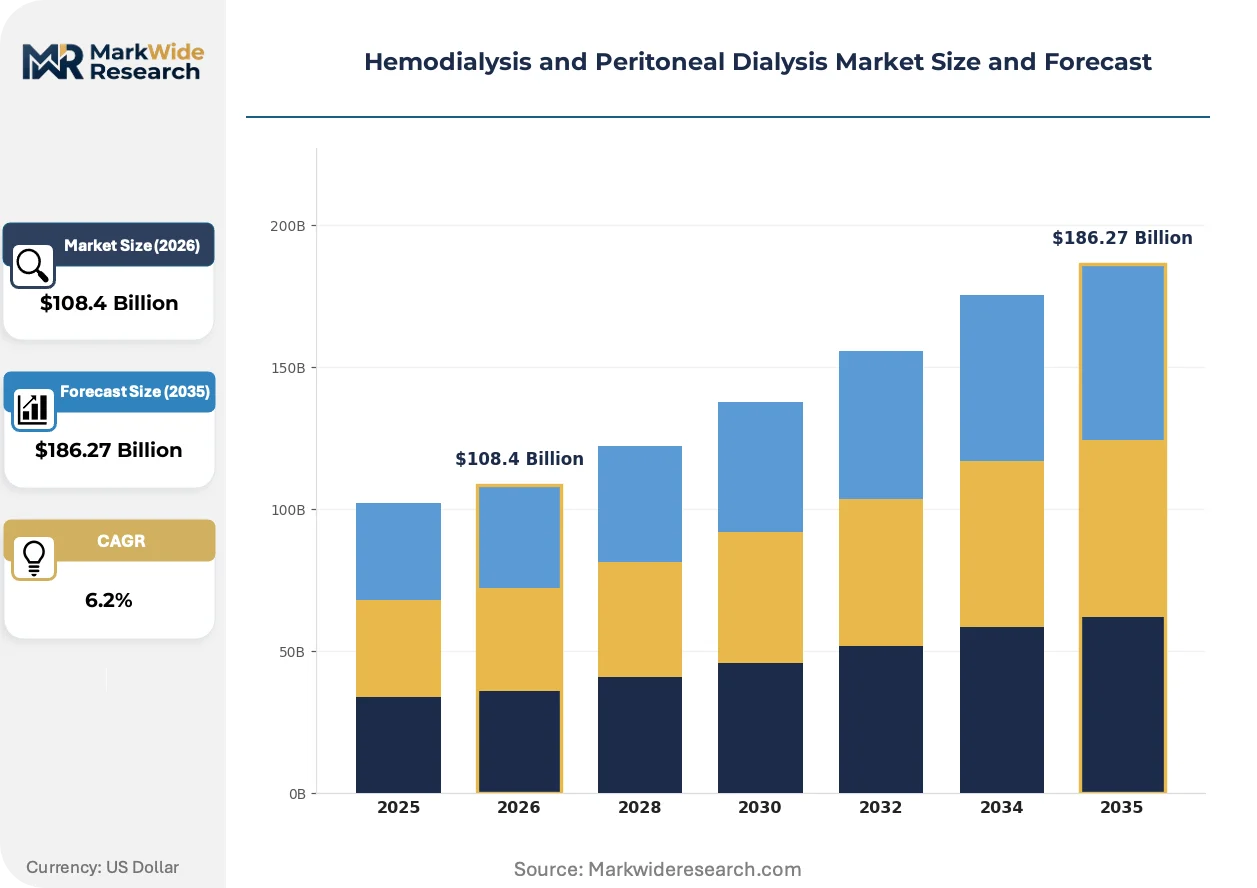
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $186.27 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dialyzers, Dialysis Machines, Catheters, Fluid Management Systems Application: Acute Kidney Injury, Chronic Kidney Disease, End-Stage Renal Disease, Home Dialysis Delivery Mode: In-Center, Home-Based, Hospital-Based, Portable End User: Hospitals, Dialysis Centers, Home Care Providers, Caregivers |
| Companies Covered | Medtronic plc, Nipro Corporation, Fresenius Medical Care AG, Asahi Kasei Corporation, Nikkiso Co., Ltd., Baxter International Inc., B. Braun Melsungen AG, Diaverum AB, DaVita Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis and Peritoneal Dialysis Market Strategic Shifts & Innovations
Decentralization and personalization are the defining themes in the dialysis market. Technological innovation and supportive policy frameworks are enabling a fundamental shift in care delivery, moving treatment away from standardized clinic protocols and toward more individualized therapies managed within the home environment.
Sorbent-based technology is a key innovation in portable dialysis systems. These systems use a cartridge to regenerate a small volume of dialysate, removing the need for a continuous water source and extensive plumbing. Patients seeking greater lifestyle flexibility and mobility are the primary adopters. The treatment paradigm is migrating from large, water-intensive stationary machines in clinics towards compact, resource-efficient systems suitable for home and travel use.
Regulatory initiatives like the Advancing American Kidney Health (AAKH) executive order in the United States are reshaping competitive positioning. This policy creates direct financial incentives for providers to increase home dialysis utilization and preemptive kidney transplants over traditional in-center hemodialysis. Consequently, large outpatient dialysis center operators are compelled to diversify their service portfolios, investing heavily in home therapy training, logistics, and support infrastructure to align with new payment models.
Service-based financing models are altering equipment procurement for clinic operators. Instead of large, upfront capital expenditures for machines, many clinics now prefer leasing agreements or pay-per-use contracts that bundle equipment, consumables, and maintenance. This shift lowers the barrier to entry for smaller or new clinics and is most visible in competitive markets like the United States and parts of Europe, forcing manufacturers to adapt their sales strategies.
Hemodialysis and Peritoneal Dialysis Market Segmentation
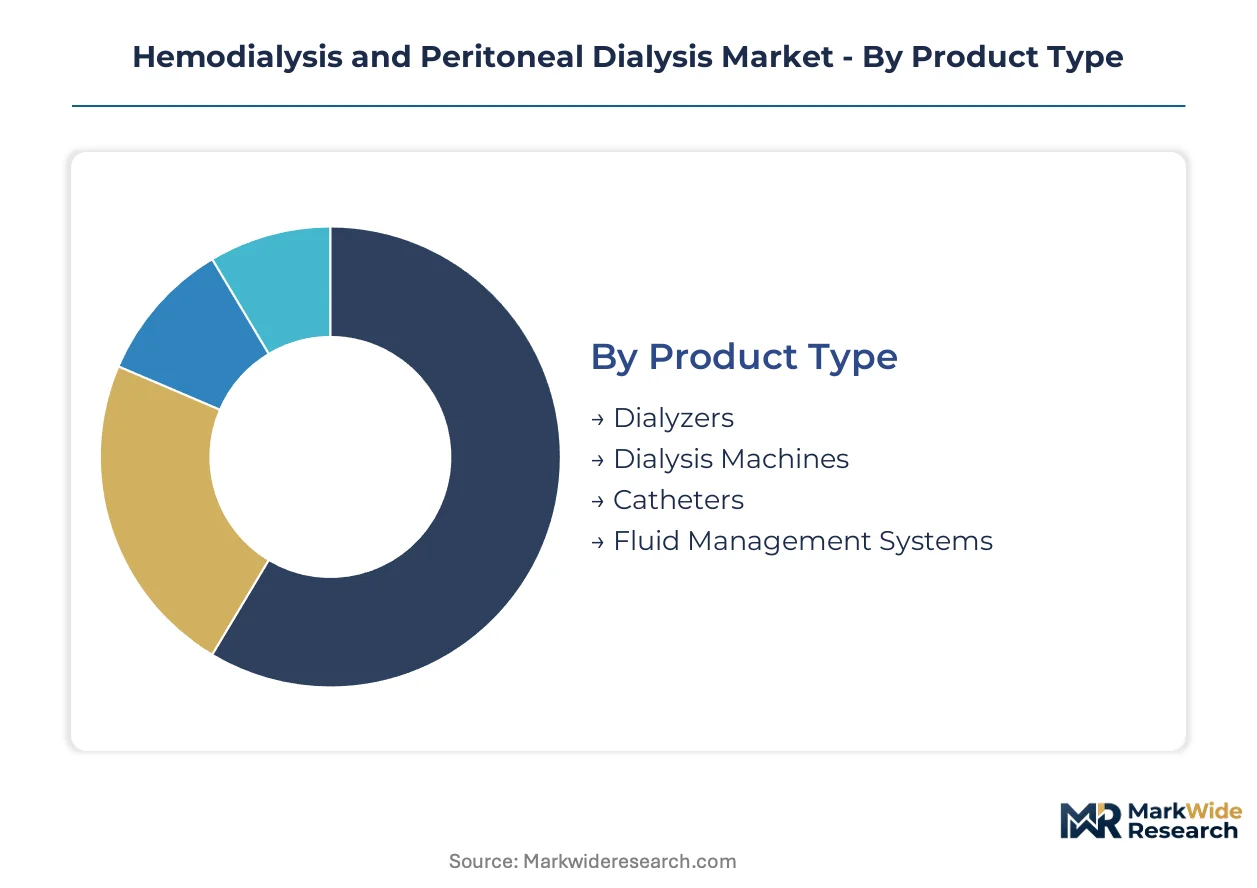
Understanding the distinct segments within the hemodialysis and peritoneal dialysis market is crucial for stakeholders to align product development and service delivery with specific patient needs and operational realities. This granular view helps identify areas of concentrated demand, emerging technological preferences, and varying regulatory compliance requirements across the value chain.
Product Type:
The after-sales service intensity for dialysis products varies significantly, influencing procurement decisions and long-term operational costs across different equipment types.
- Dialyzers:These are disposable artificial kidneys, typically comprising bundles of hollow fibers or parallel plates, essential for filtering waste products and excess fluid from the blood during hemodialysis. Demand for these consumables is consistent and directly proportional to the number of treatment sessions globally.
- Dialysis Machines:Sophisticated medical devices that pump blood through the dialyzer and manage fluid balance, these systems require regular maintenance, calibration, and software updates. Advancements in portable dialysis machines are driving adoption in home settings, particularly in the United States and European markets.
- Catheters:These medical tubes provide vascular access for hemodialysis or peritoneal access for peritoneal dialysis, requiring careful placement and ongoing care to prevent infection.
- Fluid Management Systems:Devices used to prepare, deliver, and monitor dialysate and other fluids during dialysis procedures, ensuring precise control over treatment parameters.
Dialyzers hold the largest share; momentum sits with Dialysis Machines.
Application:
The maturity curve for dialysis applications ranges from established life-sustaining therapies to rapidly evolving home-based care models.
- End-Stage Renal Disease:This application represents the most mature and consistent demand driver, requiring permanent renal replacement therapy for patients with irreversible kidney failure. The increasing prevalence of diabetes and hypertension, particularly in developed nations, sustains this segment.
- Home Dialysis:This application involves patients administering dialysis themselves at home, offering greater flexibility and improved quality of life, supported by technological advancements in portable devices. Patient preference and favorable reimbursement policies in the United States are accelerating this segment's expansion.
- Acute Kidney Injury:This application addresses sudden kidney failure, often temporary, requiring short-term dialysis support in hospital settings.
- Chronic Kidney Disease:This application covers the long-term management of progressive kidney function decline, often preceding end-stage renal disease and requiring proactive care.
Chronic Kidney Disease represents the foundational application, while Home Dialysis exhibits the steepest expansion trajectory.
Delivery Mode:
Volume considerations heavily influence the viability and infrastructure requirements for different dialysis delivery modes.
- In-Center:This traditional delivery mode involves patients receiving dialysis treatments at specialized clinics or hospitals, benefiting from direct medical supervision and established infrastructure. This mode accounts for the majority of treatments, particularly in regions with high patient density.
- Home-Based:This delivery mode allows patients to perform dialysis in their own homes, offering increased patient autonomy and reducing travel burden. Technological advancements in compact, user-friendly equipment are facilitating its growth across Europe and North America.
- Hospital-Based:This mode typically serves critically ill patients or those with acute kidney injury, where continuous medical oversight and access to emergency services are paramount.
- Portable:This mode refers to compact, mobile dialysis systems that offer patients enhanced flexibility and the ability to travel, supporting a more active lifestyle.
In-Center delivery commands the majority of patient volumes, though Home-Based solutions are gaining patient preference.
End User:
The diverse nature of end-users for dialysis services necessitates tailored support and equipment configurations.
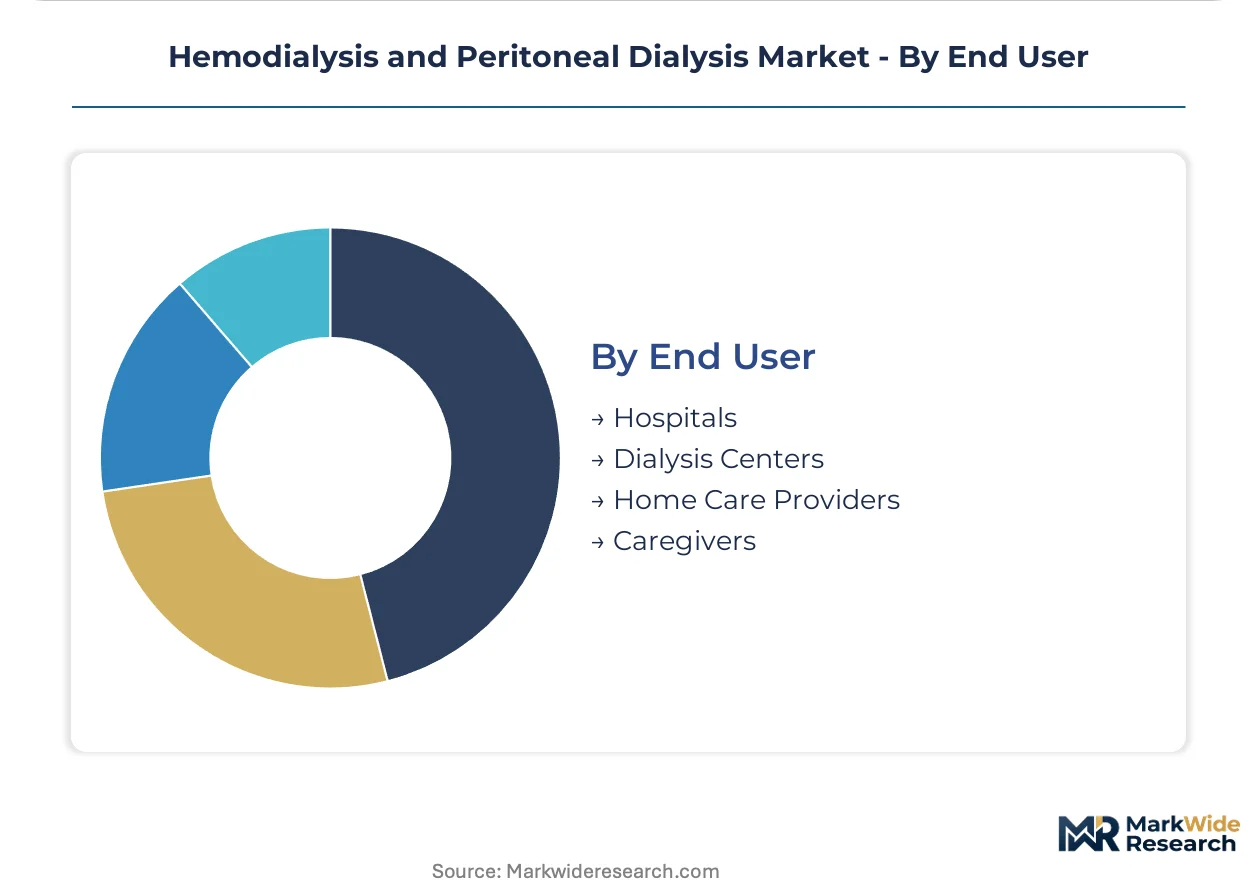
- Dialysis Centers:These specialized outpatient facilities provide regular dialysis treatments for a large patient population, serving as the primary point of care for end-stage renal disease patients. Operators like Fresenius Medical Care AG and DaVita Inc. manage extensive networks of these centers.
- Home Care Providers:These entities facilitate and support home-based dialysis, offering training, equipment delivery, and remote monitoring services to patients and their caregivers. Baxter International Inc. focuses on solutions for this segment.
- Hospitals:Medical institutions that utilize dialysis for both acute and chronic kidney conditions, particularly for inpatients requiring immediate or complex care.
- Caregivers:Individuals, often family members, who assist patients with home dialysis treatments, requiring specific training and ongoing support from healthcare providers.
Dialysis Centers remain the primary point of care, but Home Care Providers are increasingly central to decentralized models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of buyers for dialysis equipment and services is notably high in developed economies, driven by established healthcare infrastructure and a significant patient demographic. This regional demand profile shapes investment priorities and regulatory adaptations across key markets. Providers in these regions navigate complex reimbursement landscapes while expanding access to advanced treatment modalities.
United States
High rates of end-stage renal disease (ESRD) and a preference for home-based care drive demand. Favorable reimbursement policies under the Advancing American Kidney Health (AAKH) executive order incentivize home dialysis adoption. The Boston-Cambridge biotech cluster researches novel filtration technologies and compact dialysis systems.
Germany
An aging population and increasing prevalence of diabetes sustain consistent demand for dialysis. The European Union's Medical Device Regulation (MDR) sets stringent standards for device approvals. Munich and Berlin serve as hubs for medical device manufacturing and clinical research into renal care advancements.
Japan
A high incidence of chronic kidney disease necessitates widespread access to renal replacement therapies. The Pharmaceuticals and Medical Devices Agency (PMDA) strictly oversees quality and safety of dialysis equipment. Kobe's medical industry cluster focuses on developing biocompatible materials and miniature dialyzers.
China
The rising burden of kidney disease, fueled by lifestyle changes, creates substantial demand for dialysis services. National health policies aim to expand access, particularly in rural areas, through infrastructure development. Shanghai's medical technology parks attract investment in localized production of dialysis machines.
India
A large and underserved patient population, coupled with improving healthcare access, fuels demand for affordable dialysis solutions. National health programs are working to establish more dialysis units and reduce treatment costs. Bengaluru's medical device ecosystem is emerging with innovations in cost-effective and portable dialysis technologies.
Hemodialysis and Peritoneal Dialysis Market Key Industry Players
Channel-controlling players compete with product-specialist players across the dialysis market, creating a hybrid competitive structure. This landscape includes large integrated providers alongside focused technology developers. Strategic archetypes range from service-centric operators managing extensive clinic networks to technology innovators specializing in portable systems. Dominant competitive moves include strategic partnerships for market access and continuous portfolio diversification into home care solutions.
Among the established global entities, Fresenius Medical Care AG exemplifies an integrated provider with an extensive network of dialysis centers and a broad product portfolio. Baxter International Inc. occupies a position as a specialist in peritoneal dialysis and home-based care solutions, anchoring advancements in decentralized treatment. DaVita Inc. represents a service-delivery archetype, operating a large chain of outpatient dialysis centers primarily within the United States. These companies navigate evolving care models and adapt to shifts in patient preference.
| Leading Market Players |
|---|
| Medtronic plc |
| Nipro Corporation |
| Fresenius Medical Care AG |
| Asahi Kasei Corporation |
| Nikkiso Co., Ltd. |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Diaverum AB |
| DaVita Inc. |
| Others |
Cost & Logistics Intelligence
The Trans-Pacific shipping lanes' cost fluctuations directly impact the pricing of imported dialysis equipment components, influencing supply concentration and subsequent price differentiation for clinic operators. This dynamic creates pressure points across the value chain, from raw material procurement to final service delivery.
Pricing Analysis
Cost-plus contracts, often indexed to medical inflation rates and raw material prices, define pricing for dialysis consumables. Price differentiation stems from after-sales service bundling and FDA/CE certification levels. Pricing softness reflects increasing competition from home-based solutions, particularly impacting in-center operators. Hospitals and large dialysis centers exhibit lower price sensitivity due to critical patient needs, while smaller clinics are more cost-conscious.
Supply Chain Analysis
Specialized contract manufacturers in Germany and Japan hold significant capacity for advanced dialyzer membranes and portable machine components. The supply chain relies heavily on high-purity polymers and specialized medical-grade plastics as raw materials. Single-source vulnerability for specific biocompatible materials represents a structural risk. Distribution runs through a dual model: direct sales to large hospital networks and third-party distributors for smaller clinics and home care providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hemodialysis and peritoneal dialysis market is undergoing a platform-economics inflection, driven by the emergence of connected home care ecosystems. Interoperability between portable dialysis machines and telehealth platforms is reshaping patient engagement and clinical oversight.
For Market Incumbents: Entrench existing in-center patient bases by investing in advanced patient experience technologies and expanding value-added services. Diversify service portfolios into home care solutions, mitigating the threat from decentralized models and new technology entrants. Deepen vertical integration into specialized dialyzer membrane production to control input costs and quality.
For New Entrants and Emerging Players: Establish a beachhead in underserved geographies like Southeast Asia by offering cost-effective, portable dialysis solutions. Target the home dialysis segment with user-friendly, connected devices that simplify patient training and adherence. A go-to-market angle involves strategic partnerships with local healthcare providers to build trust and market access.
For Investors and Strategic Acquirers: Technology innovators specializing in miniaturized dialysis systems and remote monitoring software represent attractive acquisition targets for long-term viability. The market offers sustained demand over a 5-10 year window due to rising ESRD prevalence and home care shifts. A key signal to watch is the rate of reimbursement policy adoption for novel home dialysis modalities in major developed markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Portable Dialysis R&D | Drives patient autonomy and expands market reach into home-based care settings. |
| Expand Telehealth Integration | Enhances remote patient monitoring and improves adherence for home dialysis users. |
| Diversify into Service-Based Financing | Lowers capital expenditure barriers for new clinics and smaller operators. |
| Pursue Regulatory Approvals in Emerging Markets | Unlocks significant growth potential in underserved regions with rising kidney disease incidence. |
| Develop Biocompatible Membrane Materials | Improves patient outcomes by reducing inflammation and enhancing toxin clearance during treatment. |
Research Approach
Desk research of regulatory filings, medical journals, and industry association reports preceded structured interviews with nephrologists, dialysis center administrators, and medical device engineers. This approach combined primary insights from industry stakeholders with secondary validation of market trends. Bottom-up analysis of product segments was triangulated with top-down market sizing.
Constant macroeconomic conditions and stable regulatory environments were assumed, while technological advancements and reimbursement policy shifts were varied across the analysis window. The analytical framework modeled market dynamics across product type, application, and delivery mode. CAGRs were derived from historical growth patterns and projected adoption rates for home dialysis. Key forecast inputs included ESRD prevalence rates and healthcare expenditure trends.
Stress conditions across global public health crises and major shifts in healthcare funding were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological stability and patient preference evolution. Quarterly review of home dialysis adoption rates and regulatory changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Kidney Transplant Market
Nephrology
Global Dialysis Market
Nephrology
Global Dialyzer Market
Nephrology
US Dialysis Services Market
Nephrology
US Dialysis Centers Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
End Stage Renal Disease Market
Nephrology
Global Hemodialysis Market
Nephrology
Hemodialysis Services Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market