
 Renal Anemia Treatment Market | 2026-2036
Renal Anemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Anemia Treatment Market Analytics
CE marking under the EU Medical Device Regulation is rotating the competitive landscape for renal anemia devices and combination therapies. Amgen Inc. leverages its pioneering recombinant protein platform to sustain dominance in erythropoiesis-stimulating agent supply. Roche Holding AG anchors its position through diagnostic-therapeutic integration in nephrology care pathways. Fresenius Medical Care AG & Co. KGaA competes by controlling vertical channels from dialysis services to in-clinic drug administration.
Renal anemia treatment encompasses pharmacological and transfusion-based interventions that correct hemoglobin deficits in chronic kidney disease patients, primarily through recombinant human erythropoietin analogs with defined international unit potencies and iron repletion protocols. ESAs command the largest revenue pool due to chronic administration requirements, while iron supplements represent the fastest-expanding segment as oral formulations gain traction in predialysis populations. Dialysis centers generate the highest procedure-linked volumes among end users, though homecare delivery models are capturing incremental share through subcutaneous self-administration training programs.
The FDA risk evaluation and mitigation strategy and EMA pharmacovigilance frameworks constrain ESA dosing flexibility while mandating cardiovascular outcome disclosures on product labels. Japan's PMDA maintains distinct hemoglobin target guidelines that shape formulation preferences in that market. Stakeholders must monitor evolving iron deficiency diagnostic thresholds and biosimilar entry timelines to align portfolio investments with shifting reimbursement structures.
Market Dynamics
The FDA's risk evaluation and mitigation strategy for erythropoiesis-stimulating agents has compressed dosing flexibility and forced cardiovascular outcome disclosures onto product labels, fundamentally altering how nephrologists calibrate hemoglobin targets.
Growth Catalysts
- Japan's METI-backed chronic kidney disease management programs:These initiatives sustain consistent ESA utilization through standardized care pathways and reimbursement alignment.
- Subcutaneous self-administration training programs:Dialysis centers and homecare providers are expanding patient education infrastructure to reduce clinic visit burdens.
- Iron deficiency diagnostic threshold revisions:Updated guidelines from nephrology societies are expanding the addressable population for iron repletion therapies.
Market Restraints
- Biosimilar entry timelines:Pending patent expirations for originator ESAs create investment uncertainty among formulation developers.
- EMA pharmacovigilance frameworks:Mandatory cardiovascular outcome monitoring adds post-market surveillance costs and labeling restrictions.
- Injectable iron supply concentration:Manufacturing capacity for intravenous iron formulations clusters among a limited supplier base in Western Europe.
Strategic Opportunities
- Predialysis population oral iron penetration:Non-dialysis chronic kidney disease stages represent underaddressed demand for convenient iron supplementation.
- Diagnostic-therapeutic integration:Combined hemoglobin-ferritin testing platforms enable point-of-care treatment optimization in nephrology clinics.
- Homecare delivery channel expansion:Subcutaneous ESA administration training creates direct-to-patient distribution pathways outside dialysis center capture.
Industry Challenges
- Specialized nephrology nursing shortages:Complex ESA dosing protocols and iron infusion administration require trained personnel that dialysis operators struggle to retain.
- Legacy electronic health record integration:Hemoglobin target tracking systems must interface with diverse hospital IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Anemia Treatment Market |
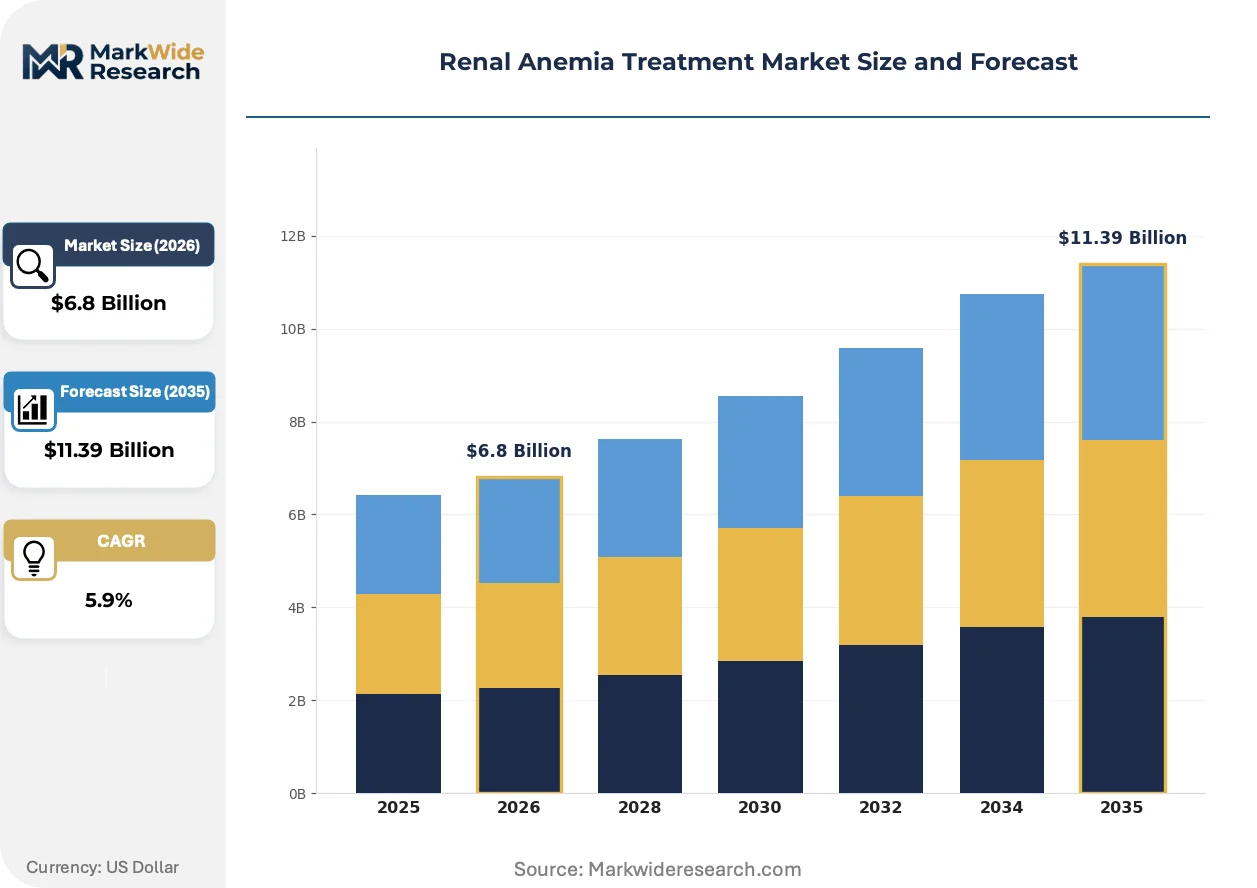
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ESAs, Iron Supplements, Blood Transfusion, Vitamin D Analogs Formulation: Injectable, Oral, Intravenous, Subcutaneous End User: Hospitals, Homecare, Dialysis Centers, Clinics Distribution Channel: Retail Pharmacy, Online Pharmacy, Hospital Pharmacy, Wholesalers |
| Companies Covered | Amgen Inc., Johnson & Johnson, Roche Holding AG, Fresenius Medical Care AG & Co. KGaA, GSK plc., Pfizer Inc., AstraZeneca, Akebia Therapeutics, Inc., CSL Vifor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Anemia Treatment Market Evolving Landscape
Formulation science and administration modalities are converging to reduce treatment burden while regulatory frameworks tighten safety surveillance requirements across major markets.
Hypoxia-inducible factor prolyl hydroxylase inhibitors are displacing traditional erythropoiesis-stimulating agents in select patient cohorts. Nephrology practices in Japan and Western Europe are adopting these oral alternatives for predialysis populations. The shift is compressing revenue per patient for injectable ESA manufacturers while expanding total addressable volume through improved adherence.
CE marking under the EU Medical Device Regulation is rotating competitive positioning for combination therapy devices. The framework mandates clinical evidence standards that favor established diagnostic-therapeutic integrators. Dialysis service operators in Germany and France are prioritizing suppliers with validated MDR technical documentation.
Patient-administered subcutaneous protocols are fragmenting historical site-of-care concentration. Homecare nurses and specialty pharmacies are capturing ESA dispensing volume previously controlled by in-center dialysis staff. This channel rotation is most pronounced in Japanese urban corridors with established chronic disease management infrastructure.
Renal Anemia Treatment Market Segmentation
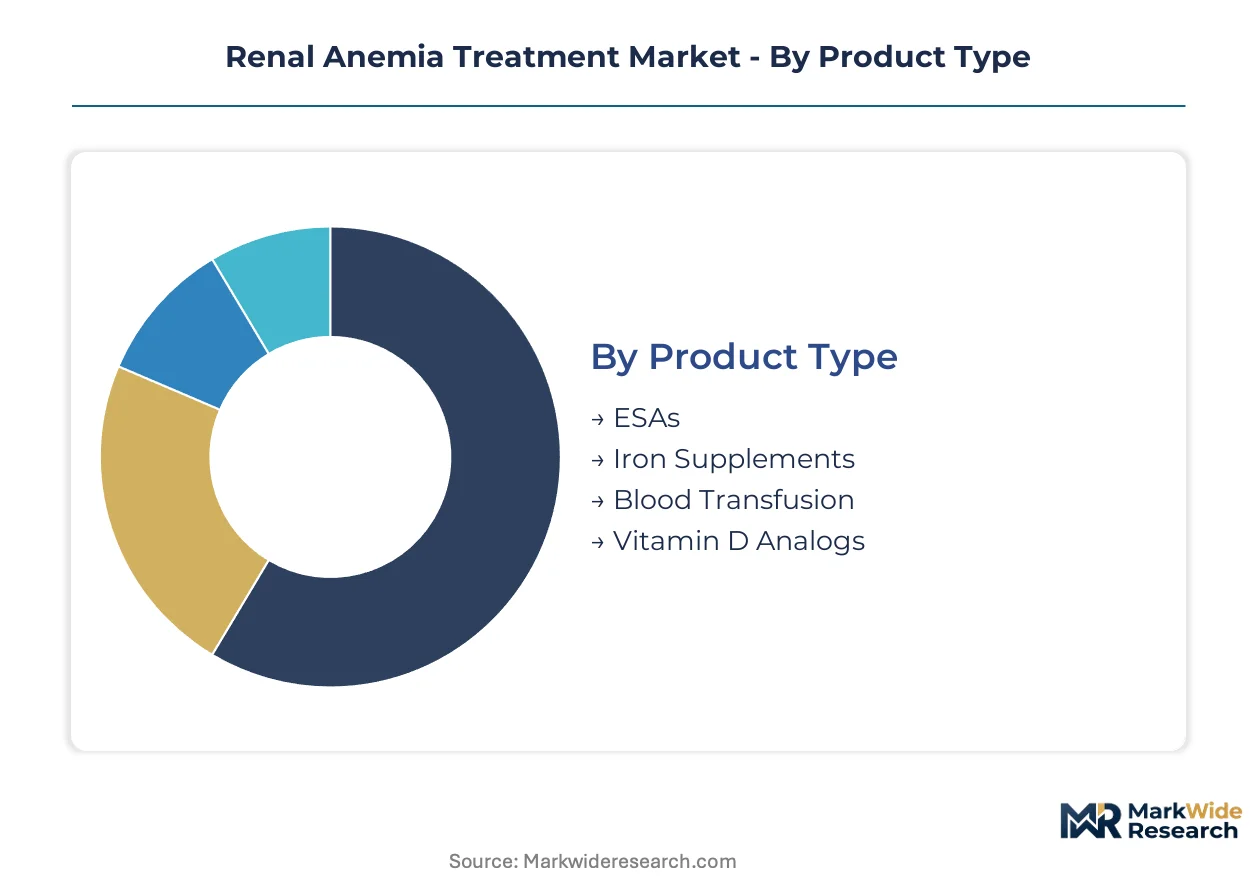
Segmentation in renal anemia treatment reveals how administration modalities and care settings fragment revenue capture across competing channels. Product type and formulation choices determine reimbursement pathways, while end-user concentration shapes procurement leverage.
Product Type:
Substitution pressure from oral hypoxia-inducible factor inhibitors is reshaping which pharmacological categories face the steepest demand erosion.
- ESAs:Recombinant human erythropoietin analogs with defined international unit potencies require chronic administration. Dialysis centers in Japan and the United States generate the highest procedure-linked volumes, though cardiovascular outcome disclosure mandates on FDA labels have compressed dosing flexibility.
- Iron Supplements:Oral formulations targeting predialysis chronic kidney disease populations are expanding the addressable patient base through improved adherence compared to intravenous alternatives. METI-backed chronic kidney disease programs in Japan prioritize iron repletion protocols ahead of dialysis initiation.
- Blood Transfusion:Reserved for acute hemoglobin crises and ESA-refractory cases where rapid correction outweighs infection risk.
- Vitamin D Analogs:Adjunct therapy addressing secondary hyperparathyroidism in advanced chronic kidney disease stages.
ESAs anchor the volume base while iron supplements gain share at the steepest rate.
Formulation:
Cost tier differentiation separates high-touch intravenous administration from patient-directed oral and subcutaneous alternatives.
- Injectable:Intravenous erythropoiesis-stimulating agents dominate in-center dialysis administration where nursing staff manage dosing protocols. EMA pharmacovigilance frameworks mandate cardiovascular outcome monitoring that adds post-market surveillance costs.
- Oral:Hypoxia-inducible factor prolyl hydroxylase inhibitors and iron salts target predialysis populations with reduced clinic visit burdens. Nephrology practices in Western Europe are adopting these alternatives for stage 3-4 chronic kidney disease patients.
- Intravenous:Iron dextran and ferric carboxymaltose formulations concentrate manufacturing capacity among Western European suppliers.
- Subcutaneous:Self-administration training programs enable homecare delivery outside dialysis center capture.
Injectable formulations retain the largest revenue pool while oral alternatives expand most quickly through predialysis penetration.
End User:
Patient volume concentration determines procurement scale, with dialysis operators commanding tiered pricing leverage through vertical channel control.
- Dialysis Centers:Fresenius Medical Care and independent operators generate the highest procedure-linked ESA volumes through in-clinic intravenous administration. Staffing shortages for specialized nephrology nurses constrain expansion capacity.
- Homecare:Subcutaneous ESA self-administration and oral iron protocols fragment historical site-of-care concentration. Japanese urban corridors with established chronic disease management infrastructure lead this channel rotation.
- Hospitals:Acute admissions and transplant evaluation centers manage transfusion-dependent cases and ESA initiation.
- Clinics:Predialysis nephrology practices drive oral iron and vitamin D analog prescribing ahead of dialysis referral.
Dialysis centers capture the dominant volume share while homecare climbs the fastest on patient-administered protocol expansion.
Distribution Channel:
Supply chain configuration separates acute inpatient dispensing from chronic outpatient fulfillment across pharmacy tiers.
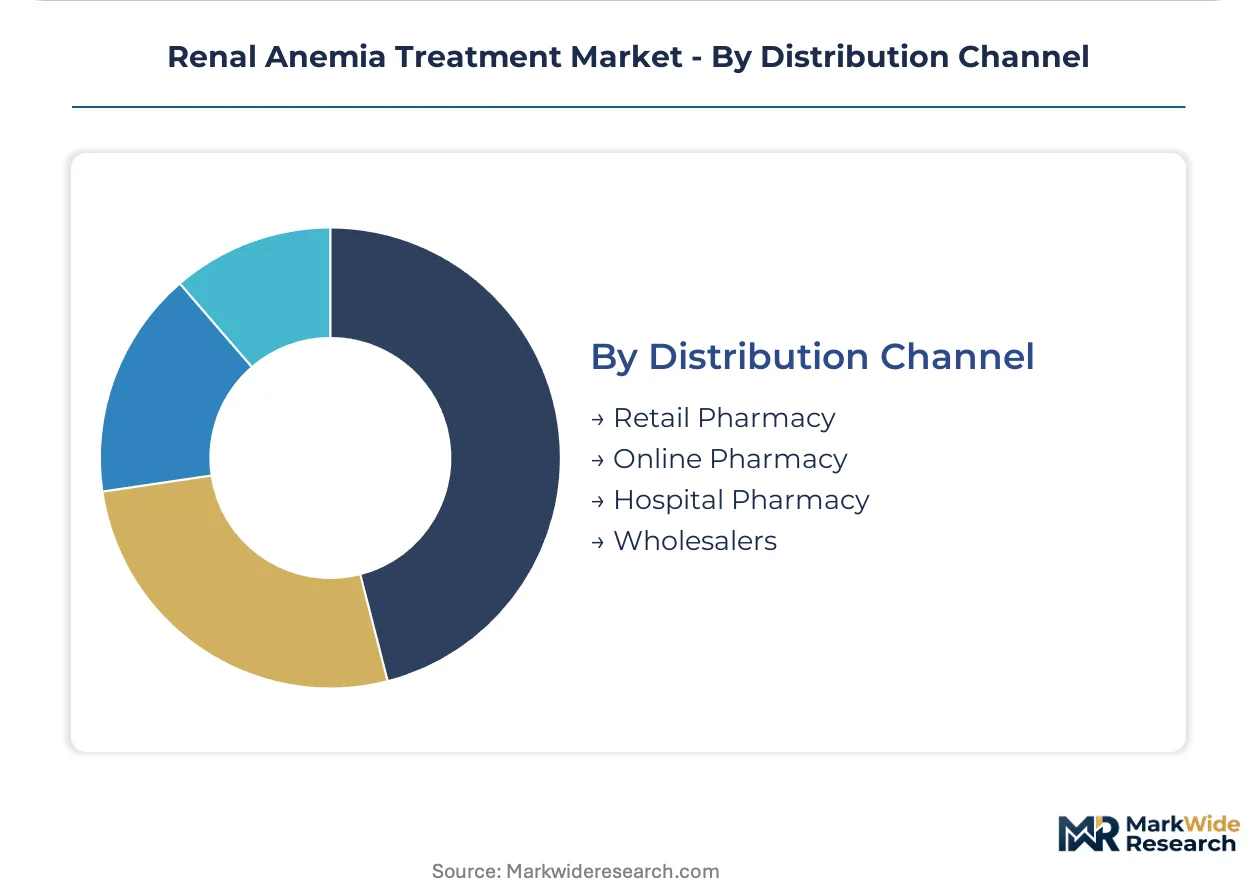
- Hospital Pharmacy:Intravenous ESAs and iron formulations flow through captive dispensing for in-center dialysis and inpatient transfusion cases.
- Retail Pharmacy:Oral iron supplements and vitamin D analogs reach predialysis patients through community pickup.
- Online Pharmacy:Specialty pharmacies capture subcutaneous ESA dispensing for homecare delivery models.
- Wholesalers:Three-tier distribution networks move injectable products from manufacturing clusters to dialysis service operators.
Hospital pharmacy anchors the value concentration while online pharmacy expands fastest on homecare channel growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical distribution infrastructure underwrites Western Europe's role in intravenous iron formulation supply chains. Japan's METI-backed chronic kidney disease management corridors concentrate demand generation in Kanto urban clusters.
United States
Dialysis center networks and Medicare reimbursement alignment drive ESA procurement volumes. FDA risk evaluation and mitigation strategy mandates cardiovascular outcome disclosures on product labels. The Boston-Cambridge biotech corridor hosts diagnostic-therapeutic integrators refining nephrology care pathways.
Japan
Standardized chronic kidney disease care pathways and PMDA hemoglobin target guidelines sustain consistent ESA utilization. METI-backed disease management programs align reimbursement with treatment protocols. Tokyo-Osaka urban corridors lead homecare delivery model adoption for subcutaneous self-administration.
Germany
Dialysis service operators command procurement leverage through vertical channel control from clinic services to drug administration. CE marking under EU Medical Device Regulation mandates clinical evidence standards for combination therapy devices. The Rhine-Ruhr industrial basin concentrates manufacturing capacity for intravenous iron formulations.
France
Nephrology practices adopt oral hypoxia-inducible factor inhibitors for predialysis populations seeking reduced clinic visit burdens. EMA pharmacovigilance frameworks mandate cardiovascular outcome monitoring and labeling restrictions. The Paris-Saclay medical research cluster advances point-of-care hemoglobin-ferritin testing platforms.
United Kingdom
National Health Service procurement frameworks tier pricing leverage across dialysis service networks. MHRA post-market surveillance requirements align with EMA pharmacovigilance standards. The Cambridge-London life sciences corridor develops biosimilar ESA manufacturing capabilities.
Renal Anemia Treatment Market Competitive Landscape
Listed leaders compete with private specialists across recombinant protein platforms and dialysis service integration. Market structure concentrates around three to five integrated players controlling vertical channels from manufacturing to in-clinic administration. Strategic archetypes span recombinant biotechnology developers, diagnostic-therapeutic integrators, and dialysis service operators with captive drug dispensing. Dominant competitive moves include backward integration into biologics manufacturing and geographic expansion through specialty pharmacy partnerships.
Within the recombinant biotechnology tier, Amgen Inc. and Roche Holding AG exemplify platform-based dominance. Among dialysis-integrated service providers, Fresenius Medical Care AG & Co. KGaA occupies a position controlling patient touchpoints from clinic admission to drug administration. These three entities anchor competitive dynamics through divergent channel strategies: biotechnology specialists prioritize formulation science and regulatory navigation, while service-integrated operators leverage procurement scale and site-of-care concentration.
| Leading Market Players |
|---|
| Amgen Inc. |
| Johnson & Johnson |
| Roche Holding AG |
| Fresenius Medical Care AG & Co. KGaA |
| GSK plc. |
| Pfizer Inc. |
| AstraZeneca |
| Akebia Therapeutics, Inc. |
| CSL Vifor |
| Others |
Value Network & Pricing Analysis
CE marking under the EU Medical Device Regulation gates both supply qualification and price differentiation simultaneously, as MDR technical documentation requirements stratify manufacturers into premium-certified and standard-compliant tiers with corresponding reimbursement access.
Pricing Analysis
Certification level creates the primary spread between premium MDR-validated suppliers and standard-compliant alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects formulation complexity and cardiovascular outcome disclosure burdens. Cost compression in injectable ESA segments is intensifying because biosimilar entry timelines compress originator margins. Dialysis centers with vertical channel control exhibit the lowest price sensitivity, while independent nephrology clinics in predialysis settings face acute budget constraints.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for intravenous iron formulations manufactured in the Rhine-Ruhr industrial basin. Manufacturing capacity concentrates in Germany, Switzerland, and Western France for parenteral iron products, while recombinant ESA production anchors in the United States and Japan. Active pharmaceutical ingredient supply draws from Chinese and Indian fermentation specialists, creating single-source vulnerability for certain erythropoietin analog precursors. Distribution runs through three-tier wholesale networks to hospital pharmacies and dialysis service operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Renal anemia treatment sits in early-cycle expansion as hypoxia-inducible factor inhibitors penetrate predialysis populations previously outside ESA addressable markets.
For Market Incumbents: Compound diagnostic-therapeutic integration advantages by embedding hemoglobin-ferritin testing platforms directly into dialysis center workflows. Secure backward integration into biologics manufacturing to defend against biosimilar margin erosion. Prioritize MDR technical documentation investment to maintain premium pricing tier access as CE marking requirements tighten. For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks regulatory pathways for novel oral hypoxia-inducible factor inhibitors targeting stage 3-4 chronic kidney disease. Penetrate Japanese urban corridors with established chronic disease management infrastructure where homecare delivery models fragment historical dialysis center capture. Deploy specialty pharmacy partnerships as the primary go-to-market angle for subcutaneous self-administration protocols. For Investors and Strategic Acquirers: PMDA hemoglobin target guideline revisions reshape the acquisition landscape by favoring formulation portfolios aligned with Japan-specific protocols. Five-to-ten year viability hinges on capturing predialysis oral iron penetration ahead of dialysis referral. Target vertically integrated dialysis service operators with captive drug dispensing capabilities. Monitor iron deficiency diagnostic threshold revisions by nephrology societies as the critical inflection signal for iron repletion therapy expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | CE marking validation secures premium reimbursement tier access across German and French dialysis networks. |
| Predialysis Oral Iron Formulation Launch | Stage 3-4 chronic kidney disease penetration expands addressable volume beyond dialysis-dependent populations. |
| Diagnostic-Therapeutic Platform Integration | Combined hemoglobin-ferritin testing embeds Amgen and Roche systems into nephrology clinic workflows. |
| Subcutaneous Self-Administration Training Program | Patient-directed protocols fragment Fresenius dialysis center capture through homecare channel rotation. |
| Biosimilar ESA Manufacturing Scale-Up | Post-patent originator erosion creates procurement leverage for dialysis operators with vertical integration. |
Research Methodology
The analysis maps erythropoiesis-stimulating agents, iron supplements, hypoxia-inducible factor inhibitors, and transfusion protocols, each validated through nephrologists, dialysis center operations directors, hospital pharmacy procurement managers, and regulatory affairs specialists at biotechnology developers. Primary interview insights triangulate against FDA REMS documentation, EMA pharmacovigilance filings, PMDA approval records, METI chronic kidney disease program reports, and dialysis service operator SEC disclosures. Bottom-up patient volume modeling and top-down reimbursement flow analysis cross-validate market size estimates.
Consistency checks against external benchmarks confirm analytical framework outputs across the projection horizon. Segmentation dimensions span product type, formulation route, end-user setting, and regional regulatory cluster. CAGRs derive from procedure volume trajectories and per-patient revenue compression curves. Forecast inputs incorporate ESA dosing protocol shifts under cardiovascular outcome disclosure mandates and iron deficiency diagnostic threshold revisions by nephrology societies.
Decision-makers should treat outputs as directional under assumptions of stable FDA REMS enforcement and METI program continuity; material deviation in biosimilar entry timelines or PMDA guideline revisions would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Kidney Transplant Market
Nephrology
Hemodialyzer Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Renal Stent Market
Nephrology
Dialysis Centers Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Global Dialyzer Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
US Dialysis Market
Nephrology
Global Acute Kidney Injury Treatment Market