
 Arteriovenous Fistula Treatment Market | 2026-2036
Arteriovenous Fistula Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Arteriovenous Fistula Treatment Market Analysis
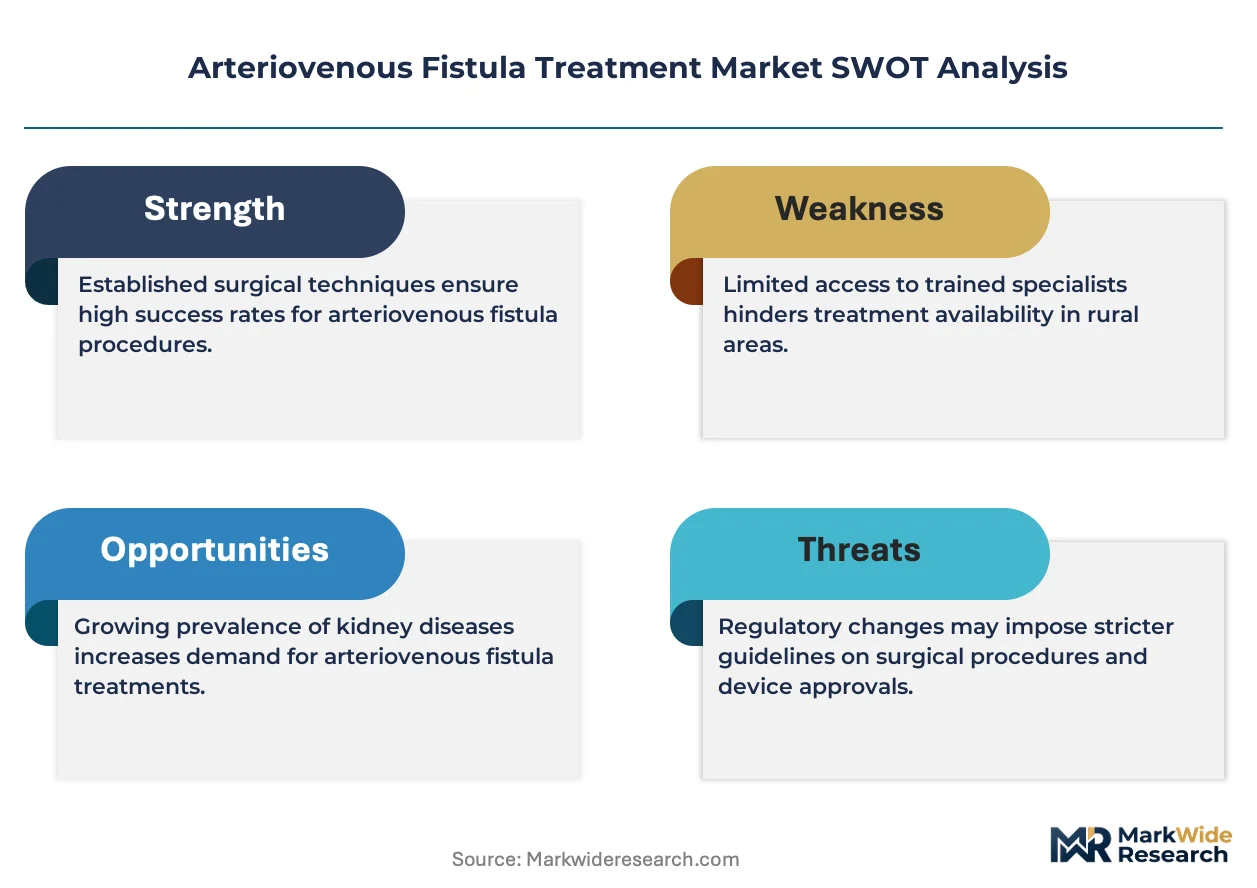
REACH compliance for medical device biocompatibility is pivoting the cost-of-entry calculus for manufacturers seeking European market access. Fresenius Medical Care leverages its vertically integrated dialysis service network to sustain captive demand for vascular access products. B. Braun Melsungen anchors its position through specialized surgical instrumentation for open fistula procedures. Medtronic competes by extending its endovascular portfolio into ultrasound-guided creation systems.
An arteriovenous fistula treatment encompasses the surgical and interventional techniques used to create, maintain, repair, or revise abnormal connections between arteries and veins, typically employing expanded polytetrafluoroethylene grafts or autologous vein segments measuring 6-8 mm in diameter to achieve blood flow rates exceeding 600 mL/min for hemodialysis access. Catheters dominate the product landscape as the entry-level option for emergent dialysis initiation, though grafts capture superior margin pools due to their longer functional patency and higher reimbursement tiers. Endovascular technology is displacing open surgery as the default approach for maintenance and revision procedures, while hybrid techniques occupy a growing niche for complex anatomical revisions.
The FDA's 510(k) clearance framework and the EU Medical Device Regulation jointly shape product development timelines and clinical evidence requirements for vascular access devices. Health Canada's Therapeutic Products Directorate aligns with FDA predicate device standards, creating a harmonized North American regulatory corridor that streamlines market entry for compliant manufacturers. Stakeholders must monitor how reimbursement shifts toward value-based care models will redistribute procurement authority between hospital systems and independent dialysis centers.
Market Dynamics
Endovascular maintenance systems are compressing the addressable market for open surgical revision procedures, redirecting capital expenditure toward ultrasound-guided platforms and catheter-based patency restoration technologies.
Growth Catalysts
- MDR compliance timelines:The EU Medical Device Regulation's stricter clinical evidence requirements are filtering out marginal competitors, concentrating procurement authority among validated manufacturers with robust quality management systems.
- Dialysis center consolidation:Large integrated networks in the United States are standardizing vascular access protocols across their facilities, creating bundled purchasing power for fistula creation and maintenance devices.
- Autologous vein harvesting techniques:Advancements in minimally invasive vein mapping and transposition methods are extending functional patency durations, reducing total lifetime intervention costs for hemodialysis patients.
Market Restraints
- Silicone and fluoropolymer feedstock volatility:Expanded polytetrafluoroethylene graft production depends on petrochemical derivatives subject to energy-price swings, compressing margin stability for device manufacturers.
- Single-source sterilization capacity:Ethylene oxide sterilization services concentrate in limited geographic clusters, exposing supply continuity to localized regulatory enforcement actions or facility closures.
- Biological graft thrombosis rates:Autologous and cryopreserved vein segments exhibit unpredictable neointimal hyperplasia, limiting their reliability in diabetic patients with compromised vascular integrity.
Strategic Opportunities
- Home-based dialysis expansion:Medicare reimbursement adjustments favoring home hemodialysis modalities are creating demand for portable vascular access monitoring devices and patient-administered maintenance protocols.
- Artificial intelligence integration:Machine learning algorithms applied to ultrasound imaging are enabling predictive fistula failure detection, opening subscription revenue streams for software-enabled device platforms.
- Brazil's ANVISA accelerated pathways:Streamlined market authorization for breakthrough vascular access technologies offers first-mover positioning in Latin America's largest dialysis patient population.
Industry Challenges
- Interventional nephrology training pipelines:The specialized skill set for ultrasound-guided fistula creation remains concentrated among fellowship-trained practitioners, constraining procedure volume scalability.
- 510(k) predicate device erosion:FDA's tightening of substantial equivalence standards for vascular access devices is extending premarket notification review timelines and increasing clinical data generation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arteriovenous Fistula Treatment Market |
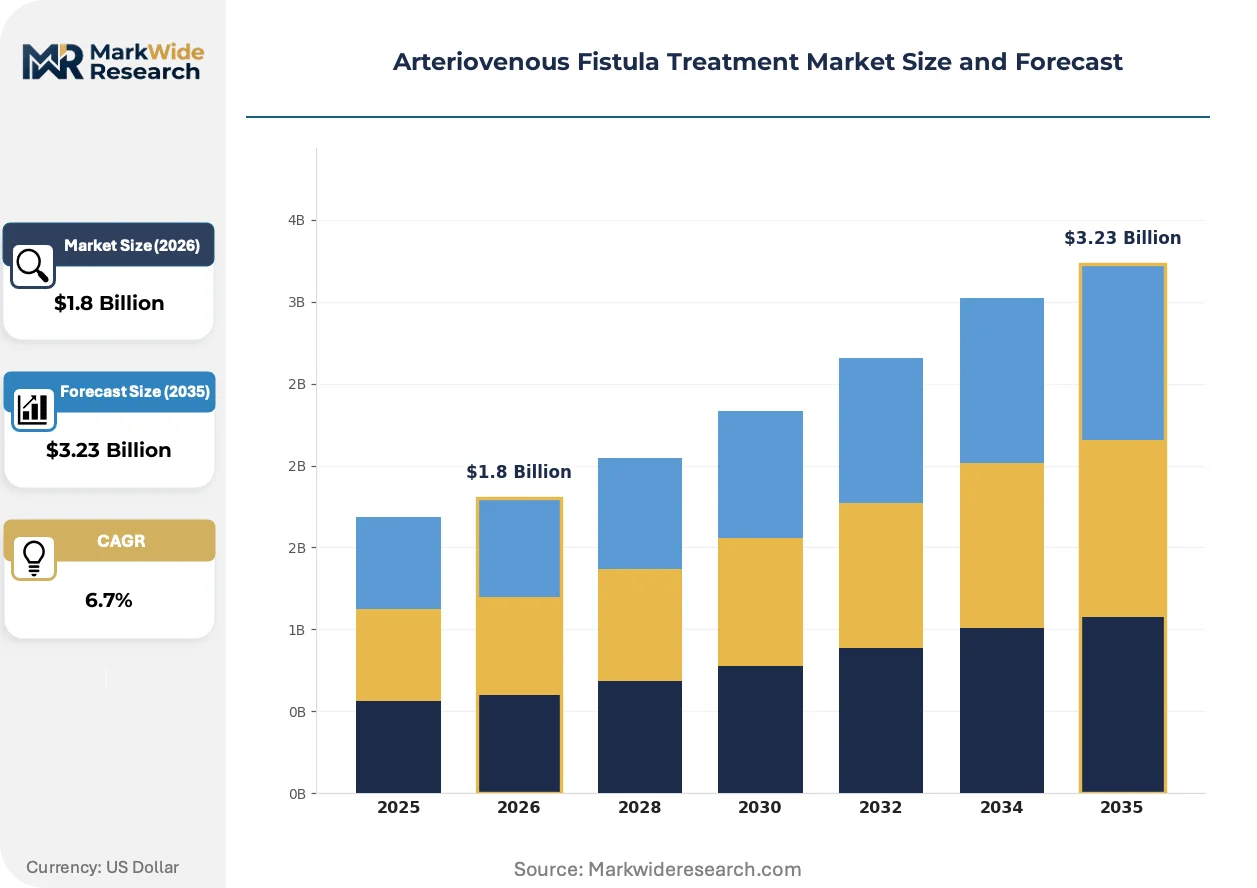
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Grafts, Stents, Sutures End User: Hospitals, Dialysis Centers, Clinics, Home Care Technology: Endovascular, Open Surgery, Hybrid Techniques, Ultrasound-Guided Procedure Type: Creation, Maintenance, Repair, Revision |
| Companies Covered | Medtronic, Becton Dickinson and Company, Fresenius Medical Care, Cook Medical, Teleflex Incorporated, B. Braun Melsungen, NxStage Medical, Poly Medicure, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arteriovenous Fistula Treatment Market Emerging Trajectories
Digital integration and minimally invasive platforms are restructuring how vascular access procedures are performed, monitored, and reimbursed across dialysis care delivery networks.
Ultrasound-guided percutaneous fistula creation is overtaking conventional surgical cutdown techniques in eligible patients. Interventional nephrologists and vascular surgeons in high-volume United States dialysis centers are adopting these systems for outpatient procedures, compressing operating room utilization and shifting site-of-service economics toward ambulatory settings.
REACH compliance for device biocompatibility is elevating material characterization requirements for European market access. Manufacturers must now submit comprehensive chemical safety dossiers covering all constituent substances, extending product development timelines and favoring incumbents with established toxicology testing infrastructure.
Provider purchasing decisions increasingly prioritize total cost-of-ownership metrics over upfront device pricing. Hospital systems and independent dialysis centers in Germany are evaluating fistula maintenance technologies based on patency duration, intervention frequency, and associated labor costs, displacing commodity procurement behaviors with outcome-based vendor selection criteria.
Arteriovenous Fistula Treatment Market Segmentation
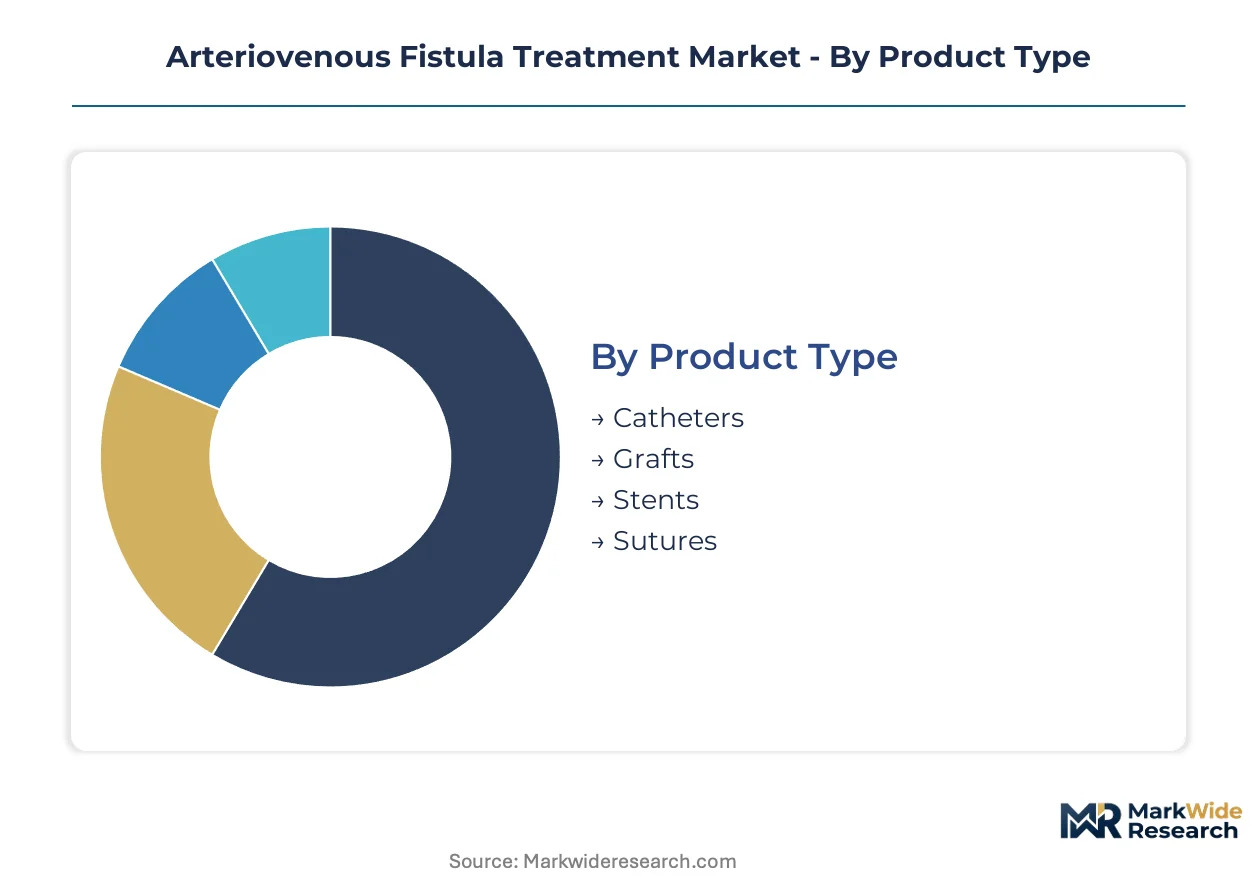
Segmentation in the arteriovenous fistula treatment market reveals how procurement authority distributes across care settings and how technology choices cascade into lifetime cost structures for hemodialysis access. Understanding these divides exposes where margin pools concentrate and where competitive positioning shifts fastest.
Product Type:
Upgrade cycles in vascular access products accelerate where reimbursement tiers reward patency duration over upfront acquisition cost, tilting procurement toward grafts despite catheter dominance in emergency initiation volumes.
- Catheters:Dual-lumen silicone or polyurethane devices provide immediate venous access for emergent dialysis initiation when fistula maturation timelines exceed clinical urgency. Demand concentrates in hospital emergency departments and acute care settings where Medicare's composite rate structure prioritizes rapid therapy commencement over long-term access planning.
- Grafts:Expanded polytetrafluoroethylene conduits measuring 6-8 mm in diameter achieve blood flow rates exceeding 600 mL/min with functional patency extending 2-3 years in compliant patients. Procurement authority in United States dialysis centers increasingly favors grafts for patients with exhausted autologous vein inventory, driven by bundled payment models that internalize downstream intervention costs.
- Stents:Self-expanding nitinol or stainless-steel scaffolds restore luminal patency in venous outflow stenosis, deployed via endovascular access.
- Sutures:Prolene and polytetrafluoroethylene suture lines secure anastomotic integrity in open surgical fistula creation and revision procedures.
Volume placements concentrate in Catheters; the faster expansion belongs to Grafts.
End User:
Site-of-service economics in dialysis access procedures redistribute capital expenditure toward ambulatory settings where facility fees compress and labor productivity rises.
- Hospitals:Academic medical centers and community hospital systems retain complex fistula revision cases requiring hybrid operating room infrastructure and multidisciplinary vascular teams. United States hospital outpatient departments capture higher reimbursement tiers for open surgical procedures under Medicare's hospital outpatient prospective payment system, sustaining investment in surgical suites despite endovascular displacement.
- Dialysis Centers:Freestanding dialysis facilities in integrated networks like Fresenius Medical Care and DaVita standardize ultrasound-guided fistula creation protocols across their footprints. Germany's ambulatory dialysis centers are gaining procedure volume as MDR-compliant device procurement favors validated manufacturers with established European distribution.
- Clinics:Interventional nephrology clinics perform outpatient endovascular maintenance procedures including angioplasty and thrombectomy.
- Home Care:Patient-administered vascular access monitoring and catheter maintenance protocols serve expanding home hemodialysis populations.
Procedure volume concentrates in Dialysis Centers; reimbursement rate compression is steepest in Hospitals.
Technology:
Capital allocation in fistula treatment technology tracks where training pipelines and device ecosystems achieve critical mass fastest.
- Endovascular:Catheter-based angioplasty, stent deployment, and mechanical thrombectomy dominate maintenance and revision procedures, displacing open surgery as the default intervention for failing access. Demand concentrates in high-volume United States dialysis centers where interventional nephrology fellowship programs produce procedure-capable practitioners.
- Open Surgery:Conventional surgical cutdown techniques with autologous vein or prosthetic graft creation retain indication for complex anatomical revisions and primary fistula construction in patients with favorable vascular anatomy. Brazil's surgical training infrastructure supports continued open procedure volume where endovascular device penetration remains incomplete.
- Hybrid Techniques:Combined endovascular and open surgical approaches address complex central venous occlusions and recurrent access failures.
- Ultrasound-Guided:Percutaneous fistula creation systems enable outpatient procedure migration without formal operating room utilization.
Clinical training capacity concentrates in Endovascular; the steepest expansion trajectory belongs to Ultrasound-Guided.
Procedure Type:
Lifetime intervention frequency for hemodialysis access creates recurring revenue pools that redistribute toward maintenance and revision as initial creation volumes plateau.
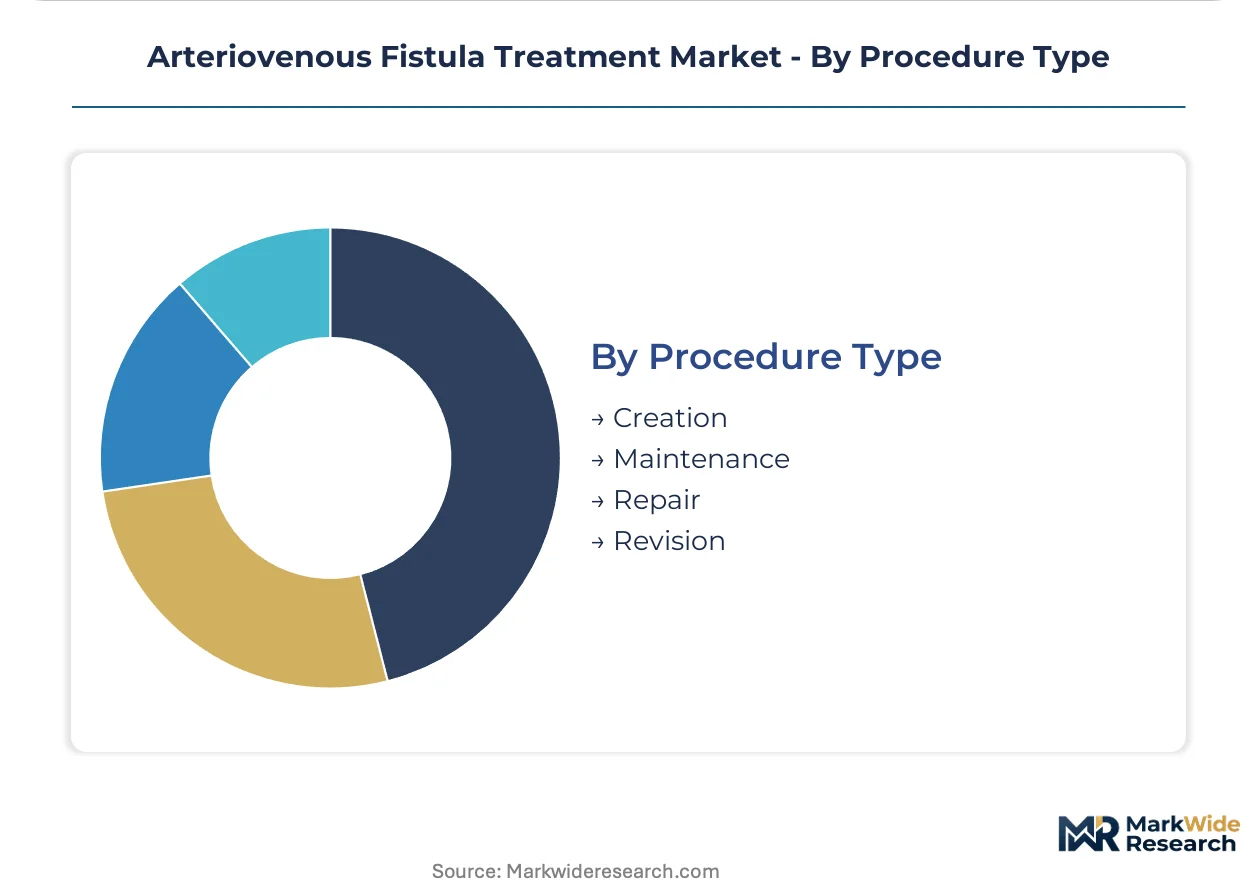
- Creation:Primary surgical or percutaneous establishment of arteriovenous fistula or graft access for hemodialysis, including autologous vein transposition and prosthetic conduit implantation. United States procedure volumes face pressure from preemptive kidney transplantation and conservative care pathways for elderly comorbid patients.
- Maintenance:Surveillance, monitoring, and preventive interventions including routine ultrasound assessment and preemptive angioplasty to preserve access patency. German nephrology practices are adopting value-based maintenance contracts that bundle surveillance with intervention, shifting procurement toward integrated device-service platforms.
- Repair:Targeted intervention for focal access complications including pseudoaneurysm repair and localized thrombectomy.
- Revision:Extensive reconstruction or relocation of failing access to alternative anatomical sites.
Revenue recurrence concentrates in Maintenance; the fastest volume gain belongs to Revision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States dialysis centers concentrate procurement authority for fistula maintenance technologies, while Germany's ambulatory networks and Japan's aging hemodialysis population shape parallel demand corridors across three continents.
United States
Medicare's bundled payment models for end-stage renal disease concentrate purchasing decisions within Fresenius Medical Care and DaVita's integrated networks. The FDA's tightening 510(k) substantial equivalence standards extend premarket notification timelines for vascular access devices. Cleveland Clinic and Mayo Clinic anchor interventional nephrology training pipelines in the Midwest.
Germany
Ambulatory dialysis centers in Bavaria and North Rhine-Westphalia adopt value-based maintenance contracts bundling surveillance with intervention. REACH compliance elevates material characterization requirements for expanded polytetrafluoroethylene graft manufacturers. Fresenius Medical Care's manufacturing presence in Bad Homburg sustains captive supply integration.
Japan
PMDA's alignment with FDA predicate device standards streamlines market authorization for vascular access technologies. Tokyo's aging hemodialysis population exceeds 300,000 patients, compressing fistula maturation timelines. Osaka-based interventional nephrology clinics pioneer ultrasound-guided percutaneous creation techniques.
Brazil
ANVISA's accelerated pathways for breakthrough vascular access devices attract first-mover positioning in Latin America's largest dialysis population. São Paulo's surgical training infrastructure sustains open procedure volume where endovascular penetration remains incomplete. Minas Gerais dialysis centers concentrate public procurement for grafts.
China
NMPA's medical device registration requirements for vascular access products extend clinical evidence generation timelines. Shanghai's dialysis patient population growth drives demand for autologous vein harvesting technologies. Beijing's hospital systems prioritize hybrid operating room infrastructure for complex fistula revisions.
Arteriovenous Fistula Treatment Market Vendor Landscape
United States producers anchor the premium-tier device segment; German and Japanese specialists hold positions in surgical instrumentation and endovascular platforms. The vendor base stratifies across three tiers: vertically integrated dialysis service networks, diversified medical device conglomerates, and regional graft manufacturers. Archetypes include captive-demand holders, endovascular technology extenders, and open-surgery instrument specialists. M&A activity concentrates on ultrasound-guided platform acquisitions; strategic partnerships link device manufacturers with interventional nephrology training programs.
Among diversified medical technology conglomerates, Medtronic and Becton Dickinson occupy positions exemplifying endovascular portfolio extension into vascular access. Fresenius Medical Care represents the captive-demand archetype through its vertically integrated dialysis service network. These three companies anchor distinct competitive vectors: technology licensing, backward integration into device supply, and outcome-based contracting with integrated care networks.
| Leading Market Players |
|---|
| Medtronic |
| Becton Dickinson and Company |
| Fresenius Medical Care |
| Cook Medical |
| Teleflex Incorporated |
| B. Braun Melsungen |
| NxStage Medical |
| Poly Medicure |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
Integrated dialysis service networks in the United States concentrate procurement authority for vascular access devices, anchoring contract-based pricing models that bundle device acquisition with long-term maintenance service obligations. This buyer concentration compresses spot-market premiums while elevating the strategic value of multi-year supply agreements with embedded volume commitments.
Pricing Analysis
Short lead-time premiums for sterilized grafts and emergency catheter shipments command price multiples over scheduled deliveries, reflecting ethylene oxide sterilization capacity constraints and just-in-time inventory policies at dialysis centers. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified European manufacturers from FDA-cleared North American suppliers and emerging Asian producers. Pricing pressure stems from Medicare reimbursement compression for end-stage renal disease services, forcing device vendors to absorb cost increases rather than pass through petrochemical feedstock volatility. Independent dialysis centers exhibit acute price sensitivity compared to vertically integrated networks that internalize lifetime access costs through bundled payment structures.
Supply Chain Analysis
Expanded polytetrafluoroethylene resin supply rests on German and American specialty chemical producers, with silicone catheter components drawing from South Korean and Japanese polymer processors. Raw material dependencies include fluoropolymer feedstocks, medical-grade silicone elastomers, and nitinol shape-memory alloys for stent platforms. Single-source sterilization vulnerability concentrates in regional ethylene oxide facilities, exposing continuity to localized EPA enforcement actions or environmental compliance shutdowns. Distribution runs through manufacturer-direct sales forces serving large integrated networks, supplemented by specialized medical device distributors covering independent dialysis centers and hospital outpatient departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over sterilization capacity and interventional nephrology training pipelines determines competitive durability. Players are pursuing downstream service integration to capture recurring maintenance revenue and lock in device placement.
For Market Incumbents: Lock in sterilization capacity through long-term service agreements or captive facility investments before EPA regulatory tightening constrains ethylene oxide availability further. Deepen interventional nephrology training partnerships with Cleveland Clinic and Mayo Clinic fellowship programs to constrain competitor access to procedure-capable practitioners. Defend against ultrasound-guided platform disruptors by accelerating hybrid operating room deployments in high-volume dialysis centers. For New Entrants and Emerging Players: Ambulatory surgery centers represent an underserved buyer archetype with growing procedure volume but limited vendor attention compared to integrated dialysis networks. Home hemodialysis monitoring devices offer penetrable white space as Medicare reimbursement shifts favor patient-administered care modalities. ANVISA's accelerated pathways in Brazil provide regulatory leverage for first-mover positioning in Latin America's largest dialysis population without confronting entrenched United States procurement relationships. For Investors and Strategic Acquirers: The window for entry favors ultrasound-guided platform developers with FDA 510(k) clearance progress and established European MDR technical documentation. Long-term viability hinges on software-enabled device architectures that generate subscription revenue streams beyond transactional hardware sales. Watch for Medicare reimbursement rulemaking on home dialysis modalities as the inflection signal determining capital allocation toward portable vascular access technologies.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance unlocks German ambulatory dialysis center procurement through REACH-validated material dossiers. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic alliances secure interventional nephrology training pipeline control for device placement. |
| Software Companion Development | Machine learning ultrasound algorithms enable predictive fistula failure detection and recurring subscription revenue. |
| Reimbursement Strategy | Medicare bundled payment alignment captures integrated dialysis network procurement authority in the United States. |
| Backward Integration | In-house ethylene oxide sterilization capacity insulates supply continuity from EPA regulatory enforcement volatility. |
Methodological Framework
Multi-period observation of dialysis center procedure volumes, Medicare reimbursement rate adjustments, and FDA 510(k) clearance timelines anchored the trend analysis, supplemented by interviews with interventional nephrologists, vascular surgeons, biomedical engineers, and GPO contracts managers. Primary fieldwork combined with secondary validation against CMS Medicare claims data, FDA premarket notification databases, hospital procurement records, and EU MDR technical documentation registries. Bottom-up demand modeling triangulated against top-down market sizing from dialysis patient population forecasts and procedure frequency assumptions.
Segment-weighting approaches distributed value across product type, end user, technology, and procedure type dimensions, with regional regulatory clusters capturing differential MDR, FDA, and ANVISA compliance timelines. CAGRs derived from fitted growth curves applied to dialysis patient incidence projections and technology substitution elasticities across the analysis window. Forecast inputs incorporated interventional nephrology fellowship graduation rates, home hemodialysis reimbursement policy trajectories, and ethylene oxide sterilization capacity utilization assumptions.
Revisions become necessary when EPA ethylene oxide regulatory enforcement intensifies, Medicare bundled payment rules shift site-of-service economics, or breakthrough ultrasound-guided platforms achieve substantial equivalence determinations faster than baseline assumptions. A small set of named triggers—sterilization facility closures, reimbursement rulemaking, and predicate device erosion patterns—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Renal Cell Carcinoma Market
Nephrology
Kidney Transplant Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Hemodialysis Services Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Blood Dialyzer Market
Nephrology
US Dialysis Centers Market
Nephrology
Dialysis Centers Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Plasmapheresis Market
Nephrology
Global Diabetic Nephropathy Market