
 Iraq Intensive Care Unit (ICU) Beds and Surfaces Market | 2026-2036
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market Insights
Public hospital procurement is recalibrating Iraq's ICU equipment landscape. Stryker Corporation leverages its critical care bed portfolio to anchor government tender participation. Getinge AB sustains competitive positioning through specialized infection control surfaces. Medline Industries extends distribution reach across Iraq's fragmented hospital supply chain.
Iraq Intensive Care Unit (ICU) Beds and Surfaces encompass height-adjustable platforms with integrated pressure redistribution systems, typically constructed from antimicrobial-coated steel frames with polyurethane foam or air-cell mattress surfaces, designed to support ventilated patients while preventing hospital-acquired pressure injuries. Critical care beds command the dominant revenue share due to mandatory replacement cycles in government facilities, while smart beds with embedded monitoring systems represent the fastest-expanding technology segment as Iraqi hospitals modernize telemetry capabilities. Electric beds capture widening preference over manual alternatives where reliable grid infrastructure exists.
Iraq's Ministry of Health equipment standards, alongside WHO facility guidelines adopted in national hospital accreditation frameworks, shape product specifications and import approval pathways for ICU surfaces. The country's national pharmaceutical regulator enforces medical device registration requirements that filter non-compliant suppliers from public tenders. Stakeholders must monitor procurement budget allocations versus actual disbursement timelines to align inventory commitments with payment certainty.
Market Dynamics
Government hospital procurement programs are recalibrating Iraq's ICU equipment landscape, with Ministry of Health standardization directives forcing rapid platform upgrades across Baghdad, Basra, and Erbil facilities.
Growth Catalysts
- Equipment Modernization Mandates:The Ministry of Health's medical equipment standardization directives are pushing tertiary care hospitals toward electric and smart bed platforms with integrated telemetry capabilities.
- Budget Allocations:Federal and regional health ministry disbursements for ICU capacity expansion in Baghdad's medical district are creating sustained tender volume for critical care surfaces.
- WHO Facility Guidelines:National hospital accreditation frameworks adopted from WHO standards are mandating pressure redistribution systems and antimicrobial coatings in all new ICU installations.
Market Restraints
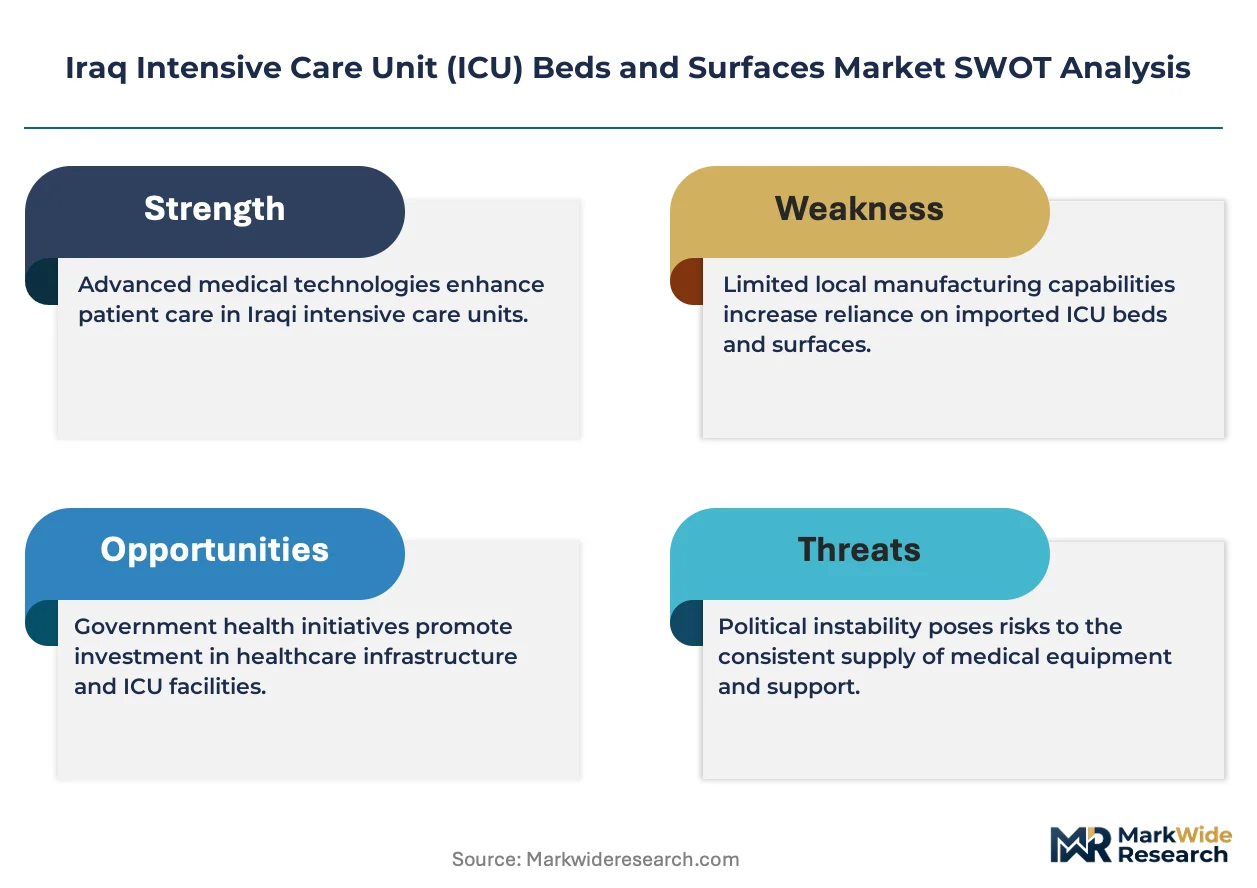
- Import Dependency:Iraq's medical device supply concentrates through a limited corridor of distributors in Amman and Dubai, creating vulnerability to regional logistics disruptions.
- Grid Infrastructure Variability:Electric bed adoption faces structural limits in facilities outside Baghdad, Basra, and Erbil where reliable power supply remains intermittent.
- Payment Timeline Uncertainty:Procurement budget allocations versus actual disbursement timelines from government treasuries create working capital compression for equipment suppliers.
Strategic Opportunities
- Smart Bed Convergence:Integration of embedded monitoring systems with pressure redistribution surfaces offers white space for technology convergence in tertiary hospitals.
- Distribution Network Gaps:Direct service partnerships with hospital groups in southern governorates bypass fragmented traditional supply chains.
- Infection Control Surfaces:Specialized antimicrobial coatings align with Ministry of Health directives on hospital-acquired infection prevention, creating regulatory tailwind for premium surface suppliers.
Industry Challenges
- Biomedical Technician Shortage:Maintenance and calibration of electric and smart bed platforms requires specialized training that remains scarce outside Baghdad's central medical district.
- Legacy Equipment Integration:New telemetry-enabled beds must interface with existing patient monitoring infrastructure that varies widely across Iraq's hospital network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Intensive Care Unit (ICU) Beds and Surfaces Market |
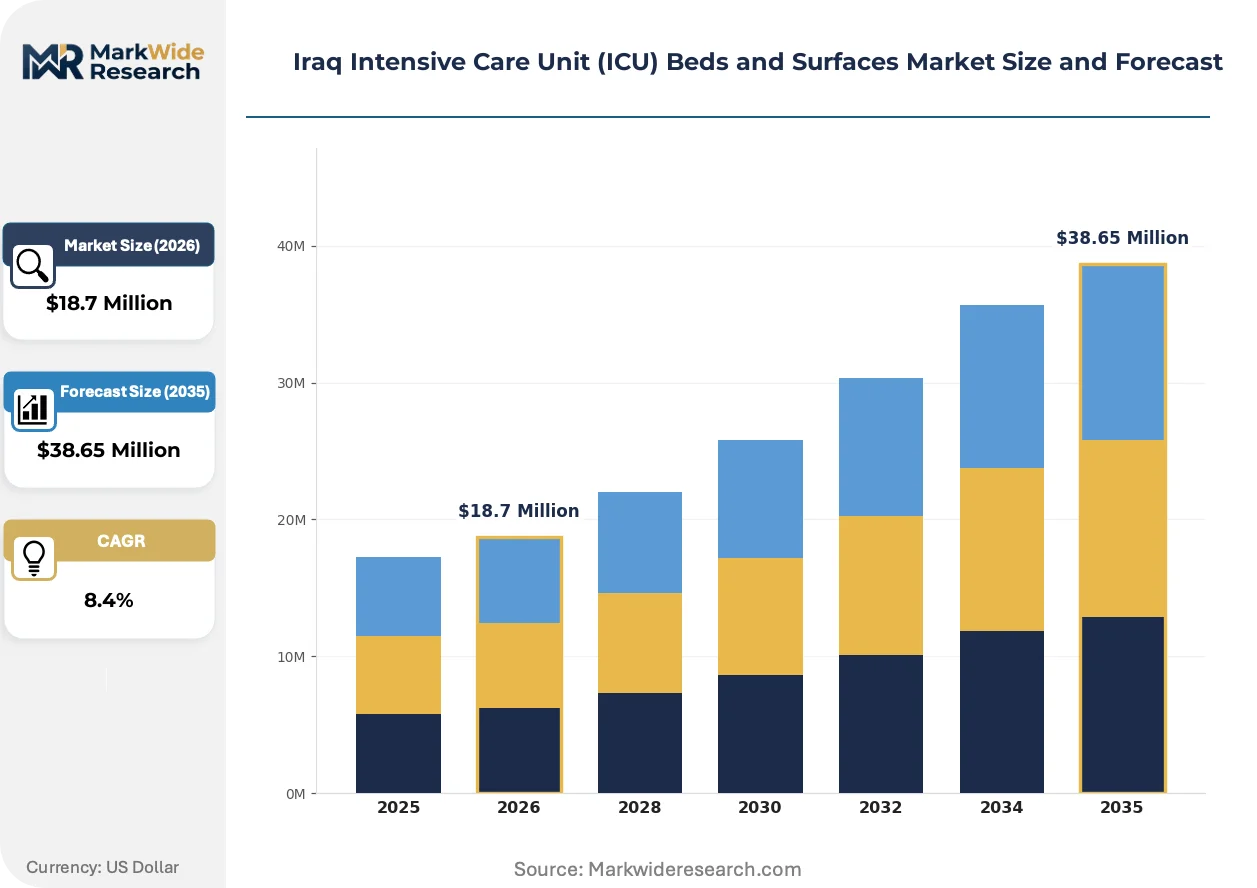
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Critical Care Beds, Pressure Relief Mattresses, Accessories, Over-bed Tables Delivery Mode: Direct Supply, Online Sales, Distributors, Trade Shows End User: Hospitals, Clinics, Emergency Medical Services, Rehabilitation Centers Technology: Manual Beds, Electric Beds, Smart Beds, Monitoring Systems |
| Companies Covered | Stryker Corporation, Baxter, Invacare Corporation, Getinge AB, Linet Group, Medline Industries, Paramount Bed Holdings, MESPA, Nitrocare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market Trends and Innovations
Telemedicine infrastructure deployment is reshaping how Iraqi hospitals specify ICU bed capabilities, with remote monitoring requirements now embedded in procurement criteria.
Air-cell mattress technology with dynamic pressure redistribution is overtaking static foam surfaces in Baghdad's tertiary hospitals. The Ministry of Health's tertiary care procurement specifications now prioritize these systems for ventilated patient populations. This shift is compressing demand for conventional polyurethane foam platforms while expanding service revenue streams for pressure mapping and calibration.
The Ministry of Health's medical equipment registration requirements are filtering non-compliant suppliers from public tenders. These standards mandate antimicrobial coating certifications and electrical safety testing for all imported ICU beds. Iraqi facilities in the central medical district are responding by consolidating purchases around pre-approved vendor lists that satisfy national pharmaceutical regulator documentation.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases. Tertiary care facilities in Basra and Erbil now negotiate separate multi-year maintenance agreements rather than accepting bundled pricing. This behavioral shift is most visible in Baghdad's government hospital network, where biomedical engineering departments demand direct technician training and spare parts inventory commitments from suppliers.
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market Segmentation
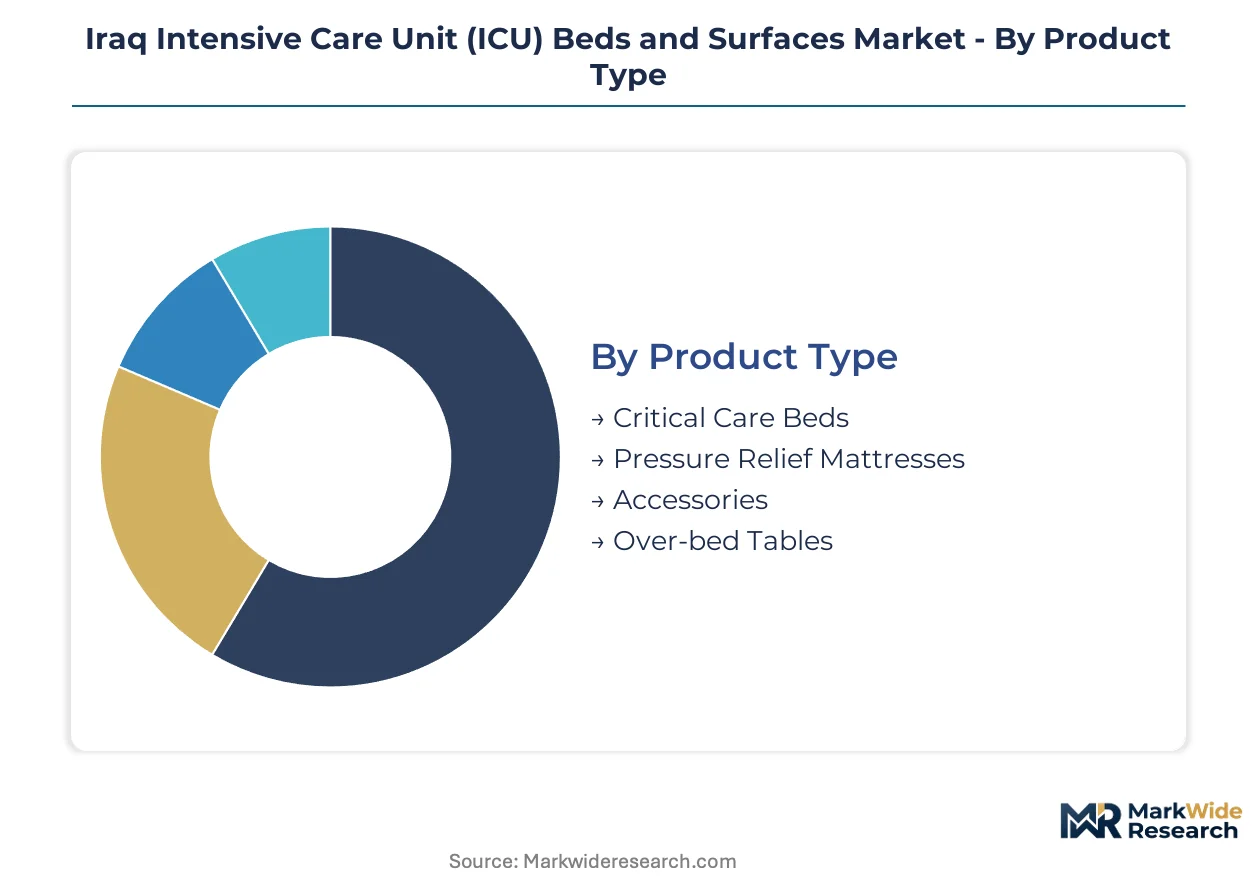
Segmentation in Iraq's ICU beds and surfaces market reveals how procurement standardization, infrastructure constraints, and clinical requirements intersect. Technology specifications dominate tender criteria while distribution channels adapt to fragmented logistics networks across Baghdad, Basra, and Erbil.
Product Type:
Technology specifications and clinical outcomes define product differentiation in Iraqi government tenders.
- Critical Care Beds:Height-adjustable platforms with integrated siderails and Trendelenburg positioning, constructed from antimicrobial-coated steel frames. Baghdad's tertiary hospitals in the medical district drive procurement volume through Ministry of Health replacement mandates for ventilated patient support.
- Pressure Relief Mattresses:Dynamic air-cell systems with alternating pressure cycles or low-air-loss technology, replacing static foam surfaces. WHO facility guidelines adopted into national accreditation frameworks mandate these systems for ICU installations, accelerating displacement of conventional polyurethane foam in government facilities.
- Accessories:Siderails, IV poles, and patient lift attachments compatible with standardized bed platforms.
- Over-bed Tables:Height-adjustable surfaces with antimicrobial finishes for patient feeding and clinical documentation.
Critical care beds lead on scale; pressure relief mattresses lead on momentum.
Delivery Mode:
Channel structure reflects Iraq's import dependency through Amman and Dubai distribution corridors.
- Distributors:Amman- and Dubai-based intermediaries control import logistics, customs clearance, and local warehousing for government tender fulfillment. These channels concentrate supply risk during regional disruptions but remain essential for Ministry of Health procurement compliance.
- Direct Supply:Manufacturer-to-hospital contracts negotiated by Baghdad's central medical district facilities seeking spare parts commitments and technician training. Basra and Erbil hospital groups increasingly pursue direct partnerships to bypass fragmented traditional supply chains.
- Online Sales:Limited to accessories and replacement components for private clinic procurement.
- Trade Shows:Annual medical equipment exhibitions in Baghdad facilitate vendor pre-qualification for tender participation.
Distributors dominate transaction volume; direct supply climbs the fastest as service unbundling accelerates.
End User:
Facility type determines specification complexity and payment timeline exposure.
- Hospitals:Tertiary care facilities in Baghdad's medical district, plus Basra and Erbil government hospitals, command procurement volume through federal and regional health ministry disbursements. These facilities specify electric and smart bed platforms where grid infrastructure permits, with antimicrobial coatings and pressure redistribution systems mandated by national accreditation frameworks.
- Emergency Medical Services:Mobile units requiring manual beds and portable pressure relief surfaces for field deployment.
- Clinics:Secondary facilities with limited ICU capacity and constrained procurement budgets.
- Rehabilitation Centers:Long-term care settings prioritizing bariatric capacity and extended pressure injury prevention.
Hospitals anchor procurement scale; emergency medical services gain share fastest through ministry fleet modernization programs.
Technology:
Power infrastructure reliability creates geographic stratification in technology adoption.
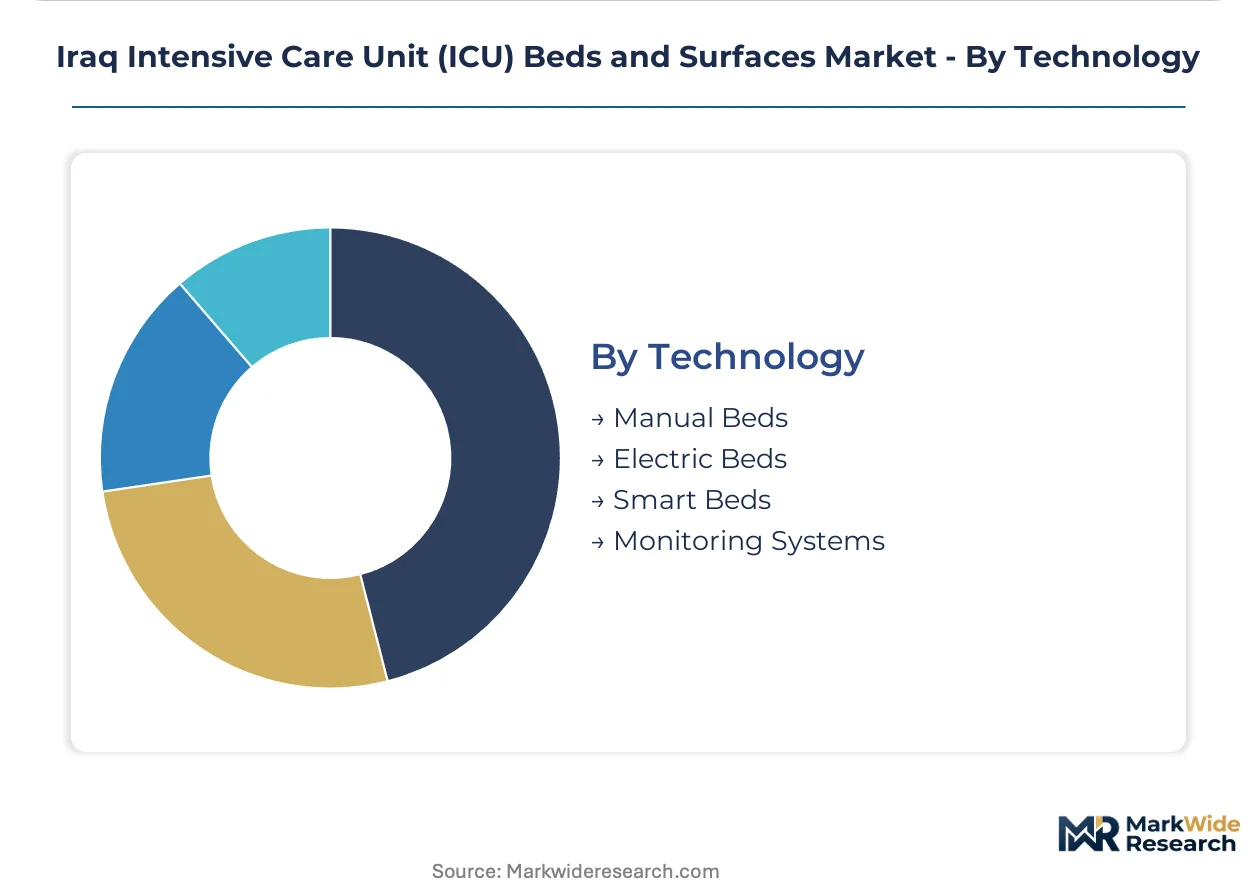
- Electric Beds:Motorized height, head, and foot adjustment with battery backup systems. Baghdad, Basra, and Erbil facilities with reliable grid access specify these platforms under Ministry of Health standardization directives, displacing manual alternatives in tertiary care procurement.
- Smart Beds:Embedded patient monitoring systems with telemetry integration for remote data transmission. Baghdad's central medical district hospitals drive specification as telemedicine infrastructure deployment reshapes procurement criteria, though biomedical technician shortage constrains deployment outside major urban centers.
- Manual Beds:Mechanical crank systems dominating facilities in southern governorates with intermittent power supply.
- Monitoring Systems:Standalone pressure mapping and patient position tracking modules retrofitting existing bed platforms.
Electric beds lead on installed base expansion; smart beds face the steepest expansion trajectory where technician training and legacy infrastructure integration advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where ICU bed manufacturers concentrate production capacity, with compliance-cost gaps between jurisdictions driving facility location decisions and export routing strategies for Middle Eastern markets.
Baghdad Governorate
Baghdad's medical district commands the dominant procurement volume through Ministry of Health replacement mandates for ventilated patient support. The national pharmaceutical regulator enforces medical device registration requirements that filter non-compliant suppliers from public tenders. Tertiary care facilities in the central medical district specify electric and smart bed platforms where grid infrastructure permits.
Basra Governorate
Basra's government hospitals drive sustained tender volume through regional health ministry disbursements for ICU capacity expansion. WHO facility guidelines adopted into national accreditation frameworks mandate pressure redistribution systems and antimicrobial coatings in all new installations. Hospital procurement committees in Basra now negotiate separate multi-year maintenance agreements rather than accepting bundled pricing.
Erbil Governorate
Erbil's facilities specify electric bed platforms under Ministry of Health standardization directives where reliable power supply exists. The country's national pharmaceutical regulator documentation requirements are consolidating purchases around pre-approved vendor lists. Direct service partnerships with hospital groups in Erbil bypass fragmented traditional supply chains.
Southern Governorates
Manual bed systems dominate facilities in southern governorates with intermittent power supply outside major urban centers. Grid infrastructure variability creates structural limits for electric bed adoption in these regions. Biomedical technician shortage constrains deployment of smart bed platforms outside Baghdad's central medical district.
Ninawa and Anbar Governorates
Emergency medical services in Ninawa and Anbar gain procurement share fastest through ministry fleet modernization programs. Mobile units in these regions require manual beds and portable pressure relief surfaces for field deployment. Distribution network gaps in these areas create opportunities for direct manufacturer-to-hospital contracts.
Iraq Intensive Care Unit (ICU) Beds and Surfaces Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers seek to secure spare parts commitments and technician training agreements with Baghdad's central medical district facilities. The vendor base clusters around three tiers: multinational critical care equipment specialists with government tender pre-qualification status, regional distributors controlling Amman- and Dubai-based import logistics, and emerging direct-service providers targeting southern governorate hospital groups. Technology licensing arrangements and geographic expansion through distribution network gaps represent the two dominant competitive moves as manufacturers bypass fragmented traditional supply chains.
Among multinational specialists, Stryker Corporation and Getinge AB exemplify the government-tender tier, anchoring procurement participation through pre-approved vendor status with Iraq's Ministry of Health. Medline Industries occupies a position within the distribution-architecture tier, extending reach across fragmented hospital supply chains. These three entities represent distinct archetypes: equipment standardization leaders, infection control surface specialists, and supply chain consolidation platforms respectively.
| Leading Market Players |
|---|
| Stryker Corporation |
| Baxter |
| Invacare Corporation |
| Getinge AB |
| Linet Group |
| Medline Industries |
| Paramount Bed Holdings |
| MESPA |
| Nitrocare |
| Others |
Pricing and Supply Chain Analysis
Biomedical technician scarcity in Baghdad's central medical district widens labor-cost differentials between electric-smart bed tiers and manual alternatives, compressing margin spreads for suppliers serving government tender markets.
Pricing Analysis
Distributor margins through Amman- and Dubai-based intermediaries add 15-25 percent to landed equipment costs before Ministry of Health procurement committees evaluate bids. Three-tier pricing structure across premium, standard, and economy levels separates smart beds with telemetry integration from electric height-adjustable platforms and manual crank systems. Pricing pressure stems from unbundled after-sales service contracts that force suppliers to compete on stripped hardware pricing. Government hospitals in Baghdad's medical district exhibit lowest price sensitivity due to federal disbursement guarantees, while southern governorate facilities prioritize economy-tier manual beds.
Supply Chain Analysis
Freight costs from European and East Asian manufacturing hubs concentrate through Jordan's Aqaba port and UAE's Jebel Ali corridor before final customs clearance in Iraq. Germany, Sweden, and China anchor production capacity for critical care bed platforms and pressure relief mattress systems. Steel frame assemblies, polyurethane foam cores, and embedded sensor modules constitute primary component dependencies. Single-source vulnerability through the Amman-Dubai distribution corridor exposes tender fulfillment to regional logistics disruptions. Distribution runs through Ministry of Health pre-approved vendor lists that consolidate procurement around compliant intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's ICU bed market functions as a geographic-arbitrage play where European quality certifications command premium positioning against lower-cost Asian alternatives, exploiting regulatory compliance gaps between WHO-adopted national standards and actual facility infrastructure capabilities.
For Market Incumbents: Cement pre-approved vendor status with Iraq's national pharmaceutical regulator through accelerated antimicrobial coating certification investments. Deepen spare parts inventory commitments in Baghdad's central medical district to counter emerging direct-service competitors from southern governorates. Anchor tender participation against price erosion from regional distributors seeking volume share. For New Entrants and Emerging Players: The premium-to-economy price-point gap in electric bed categories offers white-space entry for mid-tier manufacturers with battery-backup systems suited to intermittent grid infrastructure. Target southern governorate hospital groups bypassing fragmented traditional supply chains through direct technician training partnerships. Pursue unbundled maintenance contract specialization rather than competing on bundled equipment pricing. For Investors and Strategic Acquirers: Regional medical device distributors with established Amman-Dubai logistics infrastructure are the most active acquirer in this space, consolidating fragmented supply chain control. Five-to-ten year viability hinges on Ministry of Health standardization directive durability and actual disbursement timeline predictability. Acquisition target archetype: mid-cap distributors with pre-approved vendor status and biomedical technician training capabilities. Monitor federal budget allocation versus actual treasury disbursement spreads as inflection indicator for working capital risk.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Direct service agreements with Basra and Erbil facilities bypass fragmented distributor networks. |
| CE Marking Pathway | European certification satisfies Iraq's national pharmaceutical regulator import requirements for tender eligibility. |
| Biomedical Technician Training Program | Specialized calibration capabilities address scarcity constraints outside Baghdad's central medical district. |
| Software Companion Development | Telemetry integration modules align with telemedicine infrastructure deployment reshaping procurement criteria. |
| Reimbursement Strategy | Pressure redistribution system specifications match WHO facility guidelines adopted into national accreditation frameworks. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down distributor shipment tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee members, biomedical engineering directors, Ministry of Health equipment standardization officials, and Amman-based distributor principals combined with secondary validation from customs import records, GPO contract databases, and national pharmaceutical regulator registration filings. Triangulation across these sources calibrated equipment replacement cycle assumptions and tender volume estimates.
Historical trendline analysis of Ministry of Health budget allocations and actual disbursement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, delivery mode, end-user facility category, and technology tier, with geographic infrastructure reliability serving as an additional cross-cutting variable. CAGRs derived from equipment replacement mandates, ICU capacity expansion targets, and technology upgrade adoption curves. Forecast inputs incorporated grid infrastructure development timelines and biomedical technician training program scaling.
Caveats apply where federal treasury disbursement delays, regional logistics disruptions, or power infrastructure investment shortfalls could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Equipment
Healthcare Personal Protection Equipment Market
Healthcare Equipment
Healthcare Cold Chain Monitoring Market
Healthcare Equipment
Physiotherapy Equipment Market
Healthcare Equipment
Bedpan Washer Disinfectors Market
Healthcare Equipment
US Medical Cold Storage Market
Healthcare Equipment
Skin Cooling Systems Market
Healthcare Equipment
Specialty Medical Chairs Market
Healthcare Equipment
Middle East and Africa Ultrasound Probe Disinfection Market
Healthcare Equipment
Medical Chairs Market
Healthcare Equipment
North America Nurse Call Systems Market
Healthcare Equipment
Cold Plunge Tub Market
Healthcare Equipment
Medical Cold Storage Market
Healthcare Equipment
Patient Infotainment Terminals Market
Healthcare Equipment
Veterinary Furniture Market
Healthcare Equipment
India Healthcare Machine Vision System Market
Healthcare Equipment
Ophthalmic Examination Chairs Market