
 Renal Artery Stenosis Treatment Market | 2026-2036
Renal Artery Stenosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Artery Stenosis Treatment Market Analytics
Aftermarket service revenue for balloon catheter reconditioning and stent retrieval systems is narrowing as OEMs tighten refurbishment protocols and shift toward single-use premium devices. Boston Scientific Corporation leverages its interventional cardiology infrastructure to sustain catheter supply chain density across North American hospital networks. Medtronic PLC anchors its position through integrated hypertension management platforms that pair renal denervation with remote patient monitoring.
Renal artery stenosis treatment encompasses percutaneous transluminal angioplasty with balloon dilation, metallic or drug-eluting stent deployment, surgical revascularization, and pharmacological management of renovascular hypertension, typically performed via femoral or radial access under fluoroscopic guidance with iodinated contrast. The primary purpose is restoration of renal perfusion to preserve glomerular filtration rate and control secondary hypertension. Angioplasty and stenting segments capture the dominant share of interventional procedures due to established reimbursement and operator familiarity, while renal denervation within the surgical intervention category represents the fastest-expanding margin pool as catheter-based sympathetic nerve ablation gains procedural codes. Interventional radiology and vascular surgery therapy areas split procedural volume, with nephrology increasingly influencing referral patterns as biomarker-based screening protocols proliferate.
FDA premarket approval requirements for renal denervation devices and CE marking under the EU MDR govern product standards, clinical evidence thresholds, and market access timelines for manufacturers seeking to commercialize novel therapies. The EPA regulates iodinated contrast agent disposal from catheterization laboratories, influencing operational compliance costs for hospital end users. Stakeholders must monitor evolving NCD and LCD determinations from CMS and parallel European health technology assessment bodies as these will dictate whether renal denervation achieves category I CPT codes and widespread reimbursement adoption.
Market Dynamics
Catheter-based renal denervation is displacing pharmacological hypertension management as first-line therapy for resistant cases, forcing reimbursement frameworks to accelerate procedural code adoption and reshape hospital capital allocation toward hybrid angiography suites.
Growth Catalysts
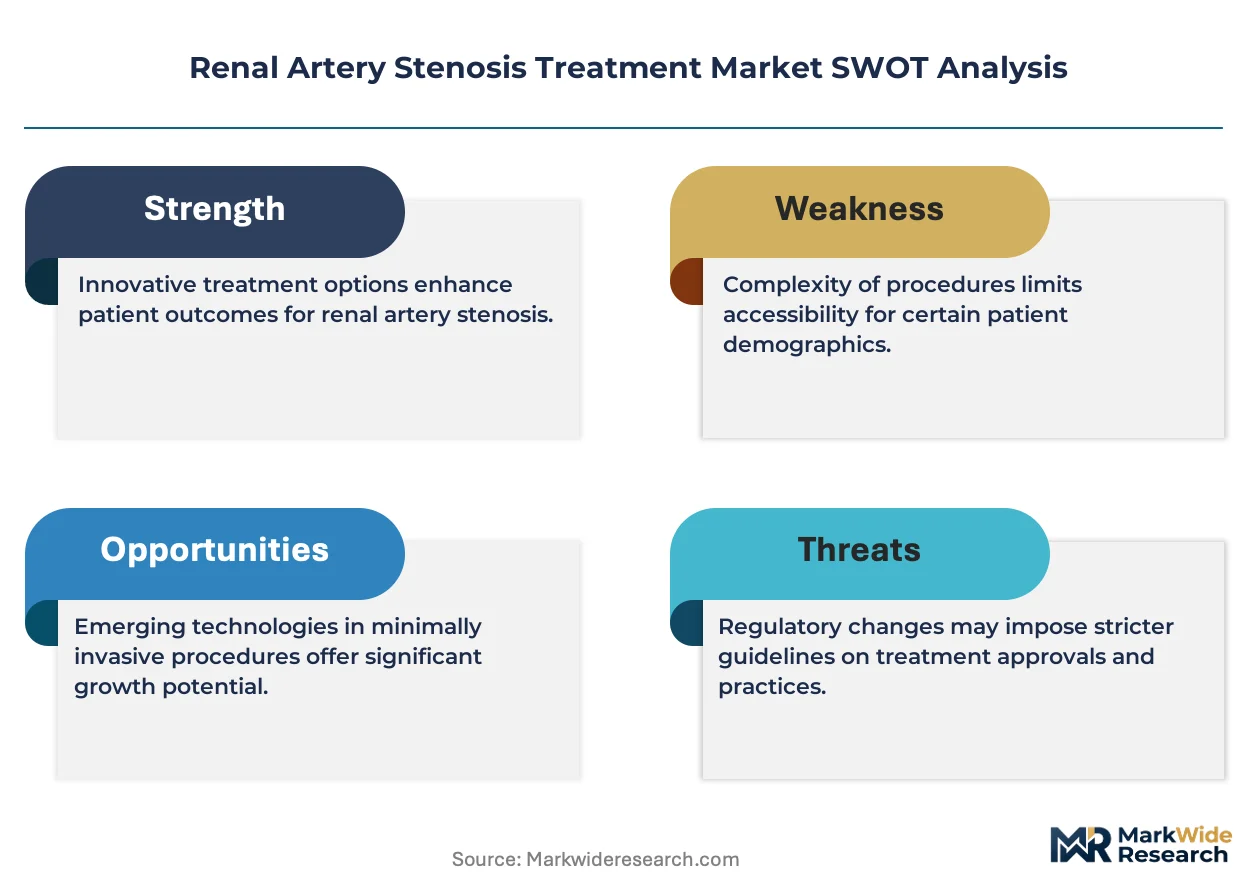
- FDA Breakthrough Device Pathway:Expedited review timelines for sympathetic nerve ablation systems compress commercialization cycles and accelerate hospital formulary inclusion.
- Japan's aging hypertensive population:Screening protocols in Tokyo and Osaka catheterization labs drive procedural volume expansion for renovascular interventions.
- Drug-eluting balloon technology:Localized antiproliferative delivery reduces restenosis rates and extends lesion-specific treatment durability.
Market Restraints
- Iodinated contrast agent costs:Supply concentration among three manufacturers creates input price volatility for catheterization laboratory operations.
- CE marking under EU MDR:Elevated clinical evidence thresholds for renal denervation devices extend European market access timelines by 18-24 months.
- Pharmacological substitution:Mineralocorticoid receptor antagonists and SGLT2 inhibitors capture resistant hypertension cases previously referred for intervention.
Strategic Opportunities
- Radial access adoption:Transradial catheterization protocols reduce access-site complications and enable same-day discharge, expanding ambulatory surgical center eligibility.
- Germany's Diagnosis-Related Group reform:Bundled reimbursement for complex renovascular procedures incentivizes integrated care pathway investments.
- AI-powered stenosis detection:Machine learning analysis of CT angiography automates screening triage and funnels appropriate cases to interventional specialists.
Industry Challenges
- Cross-trained operator scarcity:Dual competency in interventional cardiology and vascular surgery remains concentrated among fellowship-trained specialists at academic medical centers.
- Hybrid suite capex intensity:Fixed-imaging integration and radiation shielding requirements constrain community hospital expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Artery Stenosis Treatment Market |
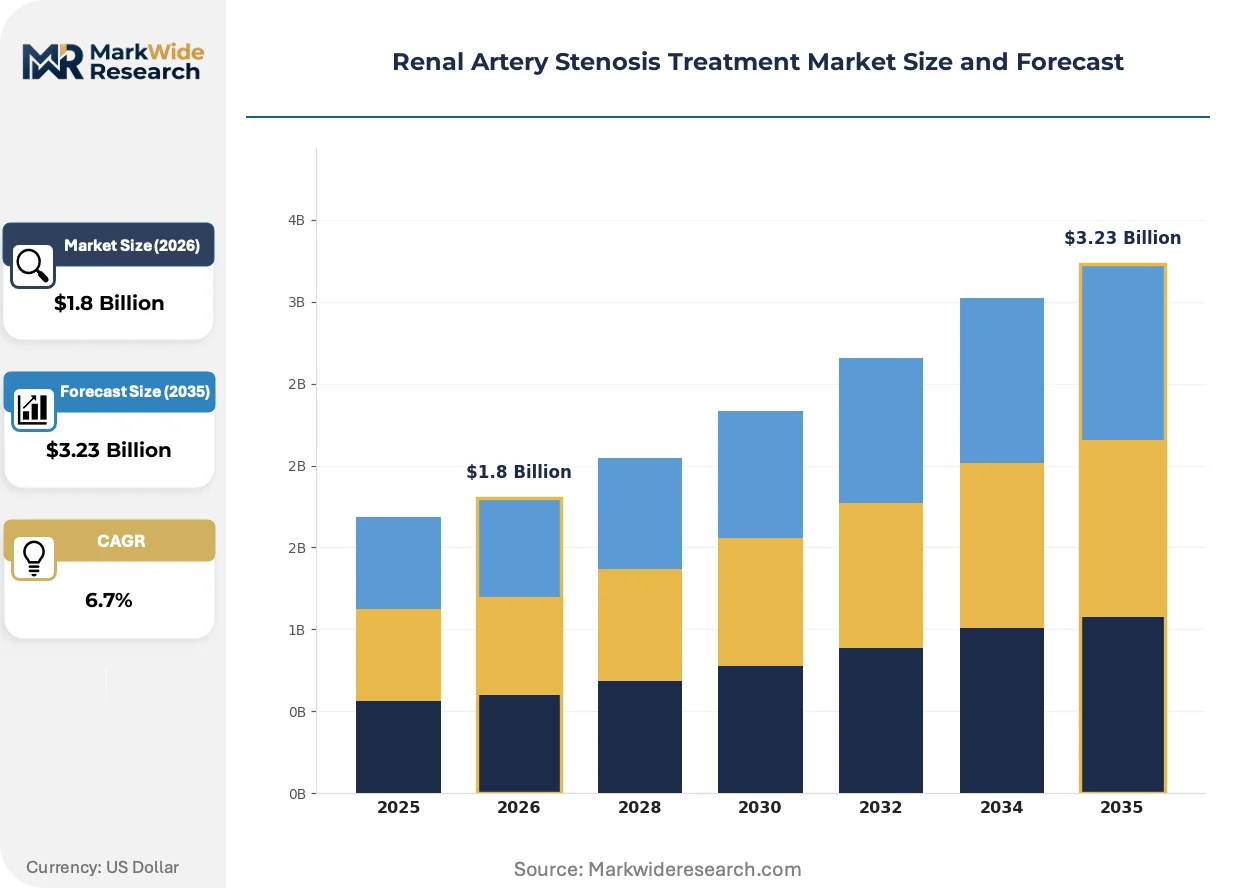
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Angioplasty, Stenting, Surgical Intervention, Medication Therapy Area: Interventional Radiology, Nephrology, Vascular Surgery, Cardiovascular End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Delivery Mode: Invasive Procedures, Non-invasive Procedures, Combination Therapy, Pharmacological |
| Companies Covered | Abbott Laboratories, Boston Scientific Corporation, Medtronic PLC, Terumo Corporation, Cook Medical, ReCor Medical, Ablative Solutions, Inc., Mercator MedSystems, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Artery Stenosis Treatment Market Evolving Landscape
Digital twin modeling and predictive hemodynamic simulation are compressing procedural planning cycles while regulatory harmonization efforts across major markets reshape competitive access patterns for novel device categories.
Radiofrequency balloon catheter systems are virtualizing the renal denervation procedure by enabling precise, multi-electrode sympathetic nerve ablation under real-time impedance monitoring. Interventional cardiologists at high-volume United States centers are adopting these platforms at accelerating pace. The technology is virtualizing traditional surgical sympathectomy and reducing reliance on prolonged antihypertensive polypharmacy.
CE marking under the EU MDR is elevating post-market surveillance requirements for renal denervation devices, mandating extended follow-up registries and annual safety reporting. Manufacturers must now maintain notified body relationships across multiple European jurisdictions. The surgical intervention segment is responding by consolidating clinical evidence generation through multinational investigator-initiated studies.
Hospital procurement committees are unbundling device purchasing from procedural service contracts, forcing manufacturers to compete on unit economics rather than bundled loyalty programs. United States integrated delivery networks are centralizing renovascular case volume to negotiate preferential pricing. This behavioral shift is most visible in the Midwest, where Catholic health systems and academic alliances dominate referral pattern consolidation.
Renal Artery Stenosis Treatment Market Segmentation
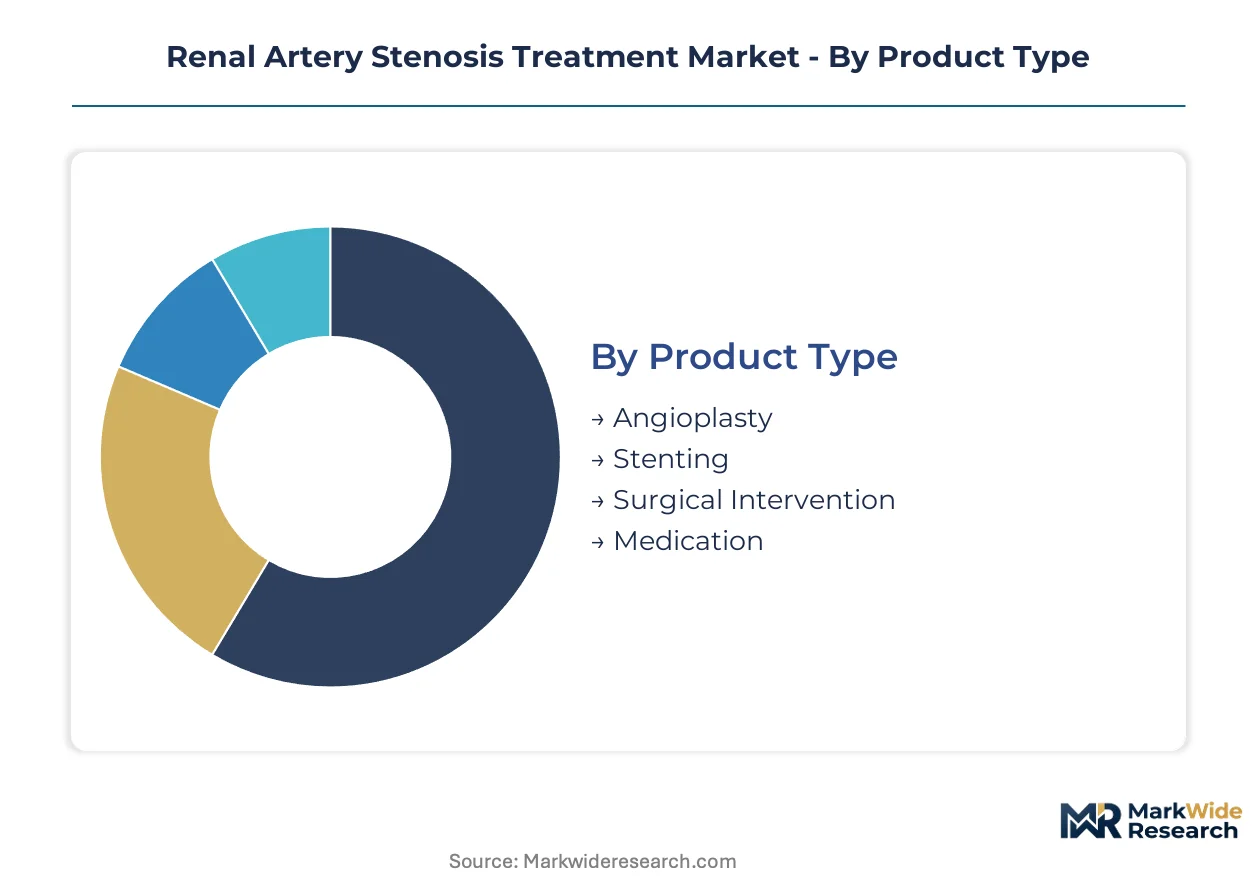
Segmentation in renal artery stenosis treatment reveals how procedural economics, reimbursement pathways, and operator training requirements reshape capital allocation across hospital systems and outpatient settings. Understanding these divides exposes where device manufacturers must tailor clinical evidence packages and service contracts to match purchasing authority structures.
Product Type:
After-sales service intensity varies sharply across this category, with capital equipment platforms demanding multi-year maintenance agreements while disposable catheter systems rotate through high-volume replenishment cycles.
- Angioplasty:Balloon dilation systems with semi-compliant and non-compliant pressure ratings dominate initial revascularization attempts. United States catheterization labs in Cleveland Clinic and Mayo Clinic networks drive procedural standardization through bulk purchasing agreements with defined service response times.
- Stenting:Metallic bare-metal and drug-eluting stent platforms anchor durable lesion management with established CPT reimbursement codes. German university hospitals in Heidelberg and Munich concentrate demand for premium stent systems with extended patency guarantees.
- Surgical Intervention:Open revascularization and renal denervation catheter systems.
- Medication:Antihypertensive pharmacological protocols.
Stenting holds the largest share; momentum sits with surgical intervention.
Therapy Area:
Cost tier stratification separates high-acuity inpatient procedures from outpatient monitoring protocols, with reimbursement differentials dictating where capital investment concentrates.
- Interventional Radiology:Fluoroscopy-guided percutaneous access and image-guided therapeutic delivery. Tokyo and Osaka catheterization labs in Japan generate concentrated procedural volume through integrated screening-to-treatment pathways.
- Vascular Surgery:Open surgical revascularization and hybrid endovascular techniques. Academic medical centers in Boston and Baltimore maintain fellowship-trained operator pipelines that sustain complex case referrals.
- Nephrology:Medical management and biomarker-driven screening protocols.
- Cardiovascular:Cross-specialty hypertension management and comorbidity coordination.
Interventional radiology commands current procedure volume; vascular surgery is gaining share fastest through hybrid suite investments.
End User:
Customer type determines purchasing authority concentration, with integrated delivery networks centralizing renovascular case volume to negotiate preferential device pricing.
- Hospitals:Tertiary and quaternary centers with catheterization laboratory infrastructure. United States Catholic health systems in the Midwest consolidate procurement through shared service organizations that unbundle device purchasing from procedural contracts.
- Ambulatory Surgical Centers:Same-day discharge protocols for stable patients. Transradial access adoption in German outpatient clinics enables procedure migration from inpatient settings.
- Clinics:Diagnostic screening and referral coordination.
- Home Care:Post-procedural monitoring and medication adherence.
Hospitals retain the dominant revenue share; ambulatory surgical centers are expanding most quickly through radial access protocols.
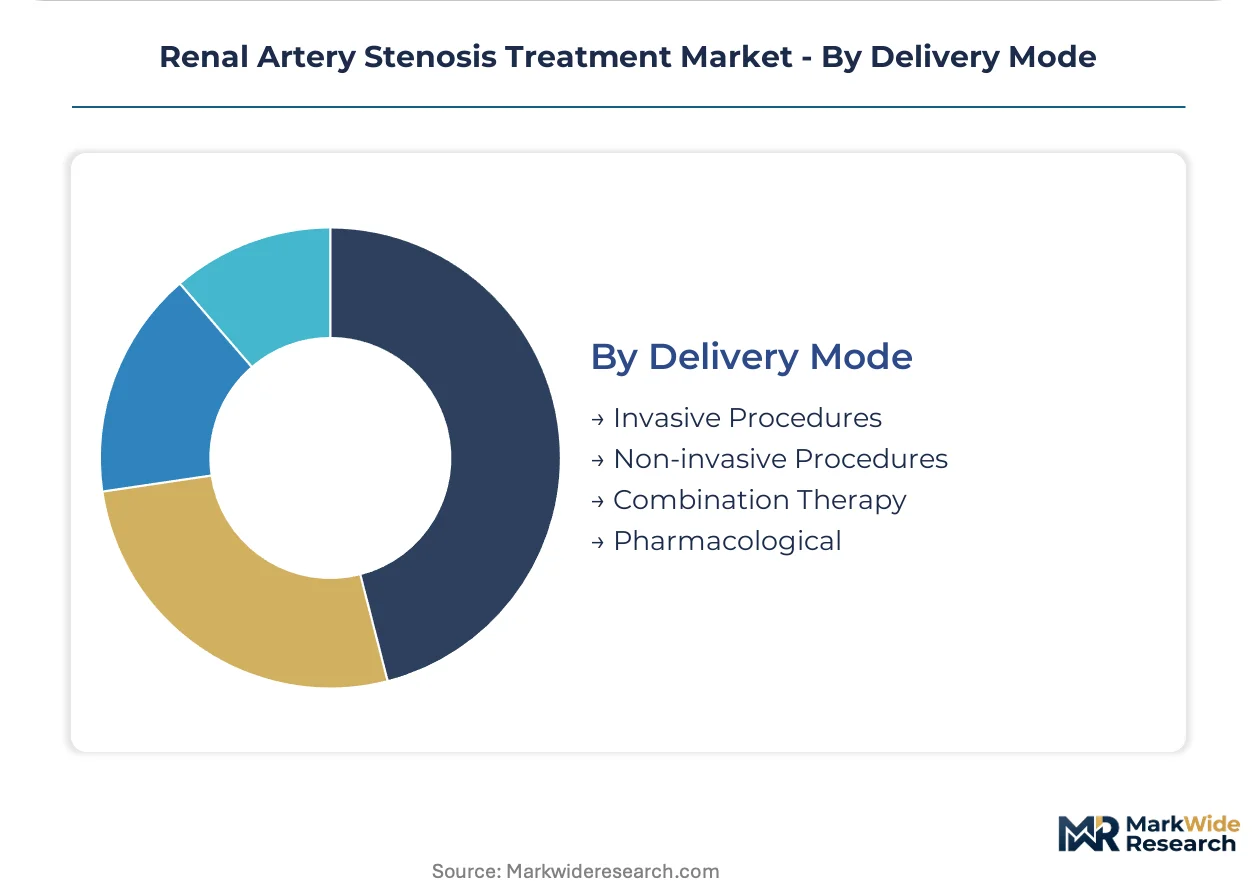
Delivery Mode:
Maturity gradients separate established invasive reimbursement pathways from emerging non-invasive alternatives still seeking procedural codes.
- Invasive Procedures:Femoral and radial access angiography with iodinated contrast. FDA premarket approval requirements govern device standards for United States commercialization, while CE marking under EU MDR extends European timelines.
- Pharmacological:Mineralocorticoid receptor antagonist and SGLT2 inhibitor protocols. Resistant hypertension cases in Japan's aging population increasingly trial medication optimization before interventional referral.
- Non-invasive Procedures:CT angiography screening and AI-powered stenosis detection.
- Combination Therapy:Sequential pharmacological and interventional protocols.
Invasive procedures generate current revenue concentration; pharmacological approaches are climbing the fastest as drug classes capture resistant hypertension cases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Japanese and German hospital systems absorb premium device pricing through comprehensive reimbursement, while Indian and Brazilian facilities face acute budget constraints that favor cost-optimized balloon platforms.
United States
Integrated delivery networks in the Midwest consolidate renovascular case volume through Catholic health system alliances. FDA breakthrough device designations compress commercialization timelines for renal denervation systems. Cleveland Clinic and Mayo Clinic networks drive procedural standardization through bulk purchasing agreements with defined service response times.
Germany
University hospitals in Heidelberg and Munich concentrate demand for premium stent systems with extended patency guarantees. Diagnosis-Related Group reforms bundle reimbursement for complex renovascular procedures. CE marking under the EU MDR elevates post-market surveillance requirements, mandating extended follow-up registries.
Japan
Tokyo and Osaka catheterization labs generate concentrated procedural volume through integrated screening-to-treatment pathways. PMDA regulatory pathways govern market access for sympathetic nerve ablation devices. METI screening protocols for aging hypertensive populations drive referral expansion.
United Kingdom
NHS England technology appraisals determine renal denervation coverage thresholds. NICE guidance shapes hospital formulary inclusion for drug-eluting balloon platforms. London and Manchester academic medical centers maintain fellowship-trained operator pipelines for complex endovascular cases.
India
Price-sensitive private hospital chains in Mumbai and Delhi favor cost-optimized balloon dilation systems over premium stent platforms. CDSCO regulatory pathways govern device import and clinical trial requirements. Government hypertension screening initiatives in tier-2 cities expand diagnostic reach.
Renal Artery Stenosis Treatment Market Competitive Landscape
Capability concentration sits with interventional cardiology specialists; scale advantage sits with diversified medtech conglomerates. The vendor base stratifies across three tiers: diversified device conglomerates with catheterization lab infrastructure, renal denervation pure-plays with sympathetic nerve ablation focus, and regional balloon catheter specialists with cost-optimized manufacturing. Dominant competitive moves include strategic partnerships for integrated hypertension management platforms and geographic expansion through distributor networks in Asia-Pacific markets.
Within the diversified conglomerate tier, Medtronic PLC and Boston Scientific Corporation anchor positions through interventional cardiology infrastructure and integrated care platforms. Abbott Laboratories exemplifies the cardiovascular device specialist archetype with broad catheterization lab portfolio breadth. Among renal denervation pure-plays, ReCor Medical and Ablative Solutions, Inc. occupy positions within the sympathetic nerve ablation segment, representing the technology-focused competitive vector.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Boston Scientific Corporation |
| Medtronic PLC |
| Terumo Corporation |
| Cook Medical |
| ReCor Medical |
| Ablative Solutions, Inc. |
| Mercator MedSystems |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Iodinated contrast agent manufacturing concentrates among three suppliers in Germany and the United States, concentrating margin capture upstream while catheterization laboratories absorb input price volatility through operational budgets. This supply asymmetry forces hospital procurement committees to unbundle device purchasing from service contracts and negotiate on unit economics rather than bundled loyalty programs.
Pricing Analysis
After-sales service revenue from balloon catheter reconditioning and extended maintenance agreements drives lifetime value for capital equipment platforms. Three-tier pricing structure across premium, standard, and economy levels separates drug-eluting stent systems with extended patency guarantees from cost-optimized balloon dilation platforms. Price differentiation rests on FDA breakthrough device designation tier and CE marking under EU MDR certification level. Cost compression in the aftermarket tier is intensifying because OEMs are tightening refurbishment protocols and shifting toward single-use premium devices. Ambulatory surgical centers in Germany exhibit the highest price sensitivity due to thin procedural margins, while United States academic medical centers in the Cleveland Clinic and Mayo Clinic networks absorb premium pricing through bulk purchasing agreements.
Supply Chain Analysis
Contract manufacturing for radiofrequency balloon catheter systems concentrates among specialized EMS providers in Ireland, Costa Rica, and Malaysia with FDA-registered facilities. Raw material dependencies include nitinol hypotube stock from United States specialty metal suppliers, polymeric balloon film from Germany, and multi-electrode impedance monitoring chips from Taiwan. Single-source vulnerability for iodinated contrast agent active pharmaceutical ingredients creates supply chain risk given the limited qualified manufacturing sites. Distribution runs through hospital procurement committees at integrated delivery networks and group purchasing organizations that centralize renovascular case volume for preferential device pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement through United States Catholic health system alliances and German shared service organizations that unbundle device purchasing from procedural contracts.
For Market Incumbents: Pre-empt pharmacological substitution threats from mineralocorticoid receptor antagonists and SGLT2 inhibitors by accelerating renal denervation reimbursement strategy investments and securing category I CPT codes. Vertical integration into remote patient monitoring platforms creates defensive moats against hypertension management pure-plays. Lock in catheter supply chain density across North American hospital networks through multi-year service response time guarantees. For New Entrants and Emerging Players: India's tier-2 cities present the most penetrable geographic white-space given government hypertension screening initiatives and price-sensitive private hospital chains in Mumbai and Delhi. Target ambulatory surgical center eligibility expansion through transradial catheterization protocols that enable same-day discharge. Pursue distributor network partnerships in Asia-Pacific markets rather than direct sales infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid angiography suite infrastructure as fixed-imaging integration and radiation shielding requirements constrain community hospital expansion. Long-term viability favors diversified medtech conglomerates with interventional cardiology infrastructure over renal denervation pure-plays facing extended EU MDR timelines. Acquisition target archetypes include sympathetic nerve ablation technology specialists with FDA breakthrough device designations. Watch for NCD and LCD determinations from CMS as the signal indicating reimbursement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates extended follow-up registries across multiple European jurisdictions. |
| Hospital System Partnership | Cleveland Clinic and Mayo Clinic networks drive procedural standardization through bulk purchasing agreements. |
| Reimbursement Strategy | Category I CPT code acquisition determines whether renal denervation achieves widespread adoption. |
| Software Companion Development | AI-powered stenosis detection automates CT angiography screening triage to interventional specialists. |
| FD Submission | Breakthrough device designation compresses commercialization timelines for sympathetic nerve ablation systems. |
Research Methodology
Desk research of FDA premarket approval filings, CMS NCD and LCD determinations, and EU MDR notified body guidance documents preceded structured interviews with interventional cardiologists, vascular surgeons, hospital procurement managers, and GPO contracts specialists. Primary fieldwork combined with secondary validation from hospital procurement databases, catheterization lab utilization reports, and regulatory submission records. Bottom-up procedure volume estimates triangulated against top-down market size reconstructions across product type, therapy area, and end user segmentation dimensions.
Assumptions regarding FDA breakthrough device designation timelines, CE marking pathway durations under EU MDR, and CMS reimbursement adoption curves were held fixed while procedural volume migration rates and radial access adoption trajectories were varied across sensitivity scenarios. The analytical framework modeled price elasticity by end user type, operator training pipeline constraints, and capital expenditure cycles for hybrid suite infrastructure. CAGRs were derived from procedure volume forecasts applied to blended device pricing trajectories. Forecast inputs included PMDA regulatory pathway timelines in Japan and Diagnosis-Related Group reform impacts in Germany.
Practitioners should monitor FDA renal denervation device approvals, CMS reimbursement determinations, and iodinated contrast agent supply disruptions for early signals of forecast revision. Forecasts reflect assumptions regarding regulatory harmonization progress and hospital capital allocation priorities. Quarterly review of catheterization lab capacity expansion announcements and GPO contract award disclosures is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Proteinuria Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Membranous Nephropathy Treatment Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Kidney Transplant Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
US Dialysis Market
Nephrology
Glomerulonephritis Treatment Market