
 Global Dialyzer Market | 2026-2036
Global Dialyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dialyzer Market Foresight
Home healthcare providers is redrawing procurement patterns across the dialyzer supply chain as patients migrate from facility-based hemodialysis to at-home modalities. Fresenius Medical Care AG & Co. KGaA leverages its vertically integrated dialysis service network to anchor recurring dialyzer demand across multiple continents. Asahi Kasei Corporation dominates hollow fiber membrane manufacturing through proprietary polysulfone spinning technology that sustains premium positioning. Nikkiso Co. Ltd. competes in high-flux dialyzer segments where Japanese precision manufacturing differentiates product consistency.
A dialyzer is a hollow-fiber membrane device that filters blood through semipermeable barriers with pore sizes typically ranging from 1 to 3 nanometers, removing urea, creatinine, and excess electrolytes during extracorporeal renal replacement therapy. Hemodialysis dialyzers command the largest installed base while high-flux variants capture expanding share among patients requiring enhanced middle-molecule clearance. Polysulfone and polyethersulfone materials lead membrane composition due to superior biocompatibility profiles and thermal stability during steam sterilization, though polyacrylonitrile surfaces attract interest for their reduced thrombogenicity in sensitive patients. End-stage renal disease applications generate the steadiest volume pull as dialysis centers maintain fixed replacement schedules for chronic patients.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape dialyzer market access timelines, with notified bodies extending review durations for novel membrane materials. ISO 8638 standards govern blood circuit performance testing, while Japan's PMDA maintains distinct biocompatibility documentation requirements that fragment regulatory submission strategies. Stakeholders must monitor reimbursement rate negotiations between public health systems and dialysis providers, as these directly determine whether high-flux and home-use dialyzers achieve favorable formulary placement against standard alternatives.
Market Dynamics
Home-based hemodialysis migration is compressing traditional clinic procurement cycles while forcing membrane manufacturers to redesign dialyzer durability standards for unsupervised patient use.
Growth Catalysts
- EU MDR biocompatibility mandates:Tighter hollow fiber membrane testing requirements are accelerating replacement demand for certified dialyzer inventories across European dialysis networks.
- Polysulfone membrane thermal stability:Steam sterilization compatibility enables extended shelf logistics and reduces cold-chain dependency for distributors serving remote treatment sites.
- Japan's aging demographic concentration:Chronic kidney disease prevalence in patients over 65 sustains fixed replacement schedules for high-flux dialyzers in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Polymer feedstock volatility:Polysulfone and polyethersulfone resin prices fluctuate with benzene derivative markets, compressing membrane gross margins unpredictably.
- Notified body capacity constraints:EU MDR conformity assessment backlogs extend novel dialyzer approval timelines by 12-18 months, freezing product pipeline commercialization.
- Peritoneal dialysis substitution:Automated peritoneal dialysis systems capture incident ESRD patients who might otherwise initiate hemodialysis, capping dialyzer volume expansion.
Strategic Opportunities
- India's reimbursement expansion:The Pradhan Mantri National Dialysis Program is extending subsidized hemodialysis access to district hospitals, opening procurement channels for cost-optimized dialyzer specifications.
- Portable wearable artificial kidney convergence:Miniaturized sorbent regeneration technology paired with reduced-membrane-area cartridges could enable ambulatory dialysis outside fixed infrastructure.
- Direct-to-patient subscription channels:Home dialysis patients in Germany and the United States are sourcing dialyzers through specialty pharmacy intermediaries, bypassing traditional clinic purchasing consortia.
Industry Challenges
- Biocompatibility toxicology expertise scarcity:ISO 10993-5 cytotoxicity testing and hemocompatibility validation require specialized analytical chemists that dialyzer manufacturers struggle to recruit.
- Legacy clinic inventory integration:Home-use dialyzers with modified packaging and patient-facing instructions must interface with existing bloodline sets and dialysis machine firmware without triggering safety interlocks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dialyzer Market |
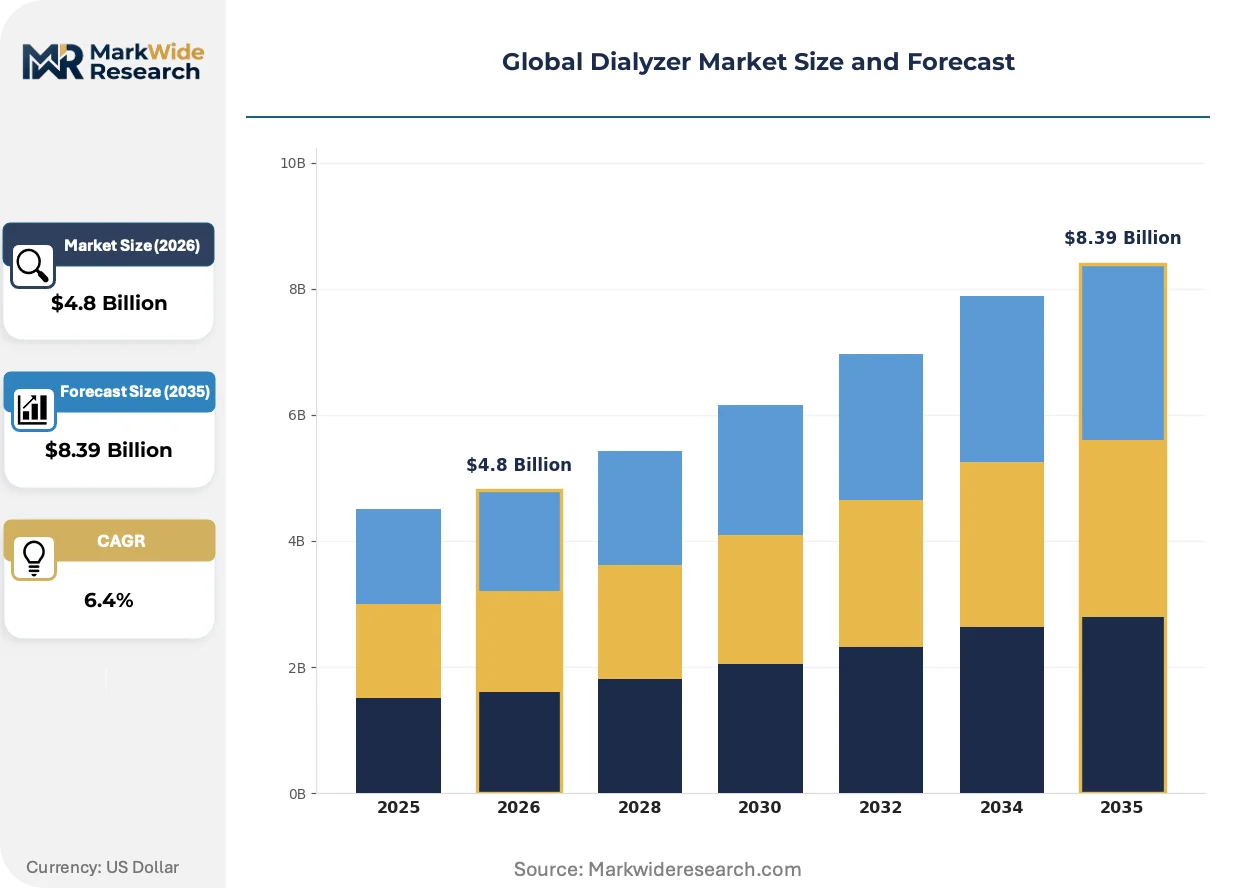
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis Dialyzers, Peritoneal Dialyzers, High-flux Dialyzers, Low-flux Dialyzers, Hollow Fiber Dialyzers Material: Polysulfone, Polyethersulfone, Cellulose Acetate, Polyacrylonitrile, Ethylene Vinyl Alcohol Application: Chronic Kidney Disease, Acute Kidney Injury, End-Stage Renal Disease, Continuous Renal Replacement Therapy End User: Dialysis Centers, Ambulatory Surgical Centers, Home Healthcare, Specialty Clinics |
| Companies Covered | Asahi Kasei Corporation, Nikkiso Co. Ltd., Fresenius Medical Care AG & Co. KGaA, Allmed Medical Care Holdings Limited, Toray Industries Inc., Baxter International Inc., Nipro Corporation, JMS Co. Ltd., B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dialyzer Market Shifts & Advancements
Membrane chemistry refinement and regulatory documentation burdens are simultaneously elevating performance thresholds and compliance costs across dialyzer manufacturing.
High-flux polysulfone membranes with enhanced middle-molecule clearance capability are bifurcating the installed base between standard low-flux dialyzers and premium variants. Japanese and German dialysis centers are prioritizing beta-2 microglobulin removal specifications in procurement tenders. This performance tiering is compressing mid-range product positioning and forcing manufacturers to commit to single-tier specialization.
EU MDR Article 10 technical documentation requirements are extending notified body review timelines for hollow fiber membrane modifications. Manufacturers must now submit comprehensive clinical evaluation reports for even incremental pore size adjustments. German and French dialysis providers are delaying procurement decisions until MDR-certified alternatives achieve formulary placement.
Patient self-administration training protocols are reshaping how dialyzer manufacturers structure technical support obligations. Home healthcare agencies in the United States and Japan now demand 24-hour nurse hotline commitments bundled with dialyzer supply contracts. This service unbundling is visible most acutely in Medicare Advantage plan negotiations where star ratings depend on patient satisfaction scores tied to responsive troubleshooting.
Global Dialyzer Market Segmentation
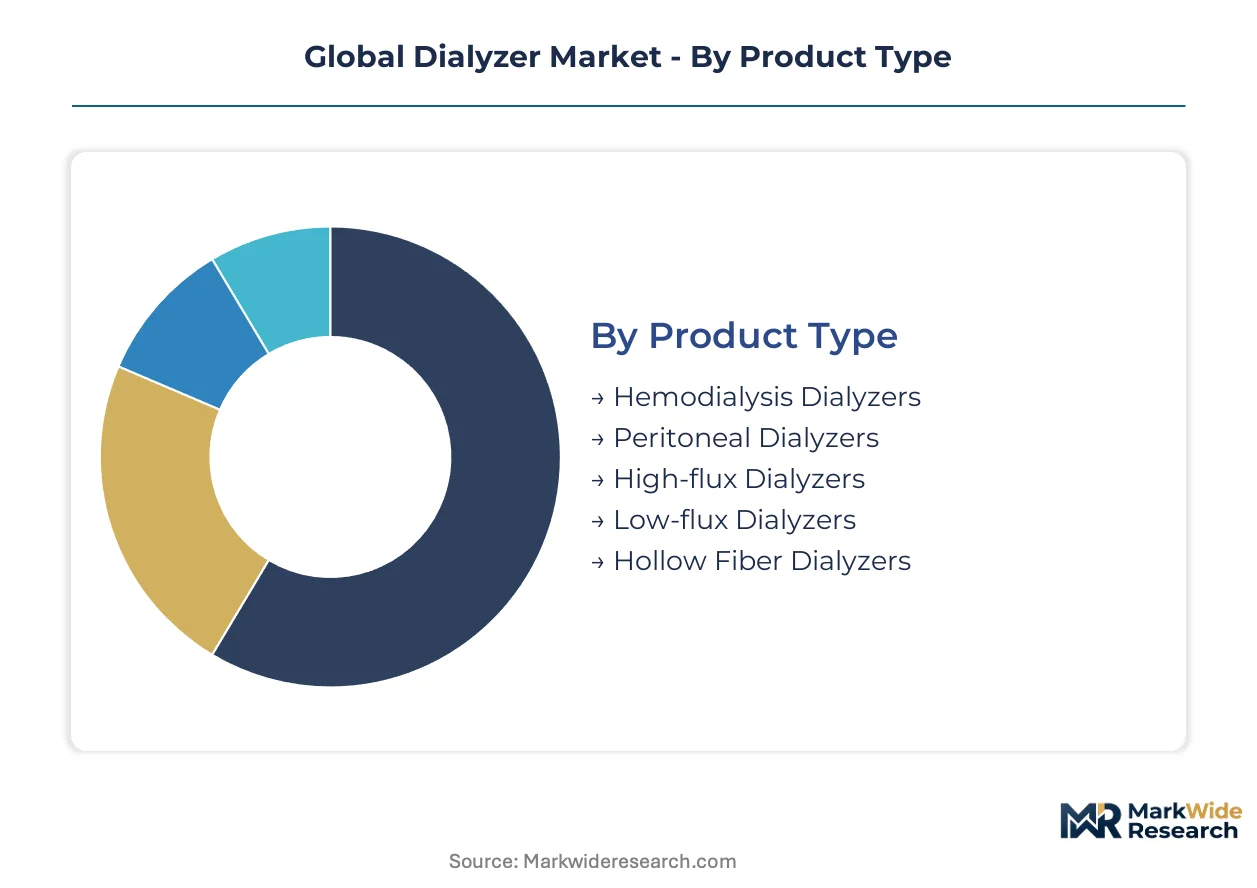
Dialyzer procurement channels fragment sharply across treatment settings, with membrane specifications and sterilization requirements diverging between institutional buyers and direct-to-patient distributors. Manufacturers must maintain parallel product lines to serve clinic volume contracts alongside home-use packaging and compliance documentation.
Product Type:
Channel mix varies dramatically: hemodialysis dialyzers flow through consolidated purchasing consortia serving dialysis center networks, while high-flux variants command premium positioning through specialty distributors targeting academic medical centers and home healthcare agencies.
- Hemodialysis Dialyzers:These hollow-fiber membrane devices filter blood through semipermeable barriers with pore sizes typically ranging from 1 to 3 nanometers, removing urea, creatinine, and excess electrolytes during extracorporeal renal replacement therapy. Demand concentrates in the United States, Germany, and Japan where aging demographics and established reimbursement frameworks sustain chronic kidney disease treatment volumes through fixed replacement schedules.
- High-flux Dialyzers:Enhanced middle-molecule clearance capability distinguishes these premium variants, with Japanese and German dialysis centers prioritizing beta-2 microglobulin removal specifications in procurement tenders. Home healthcare providers are expanding procurement as patients shift toward at-home renal therapy, forcing manufacturers to redesign durability standards for unsupervised patient use.
- Low-flux Dialyzers:Standard clearance specifications serve cost-sensitive procurement in emerging markets and public hospital systems with constrained reimbursement rates.
- Peritoneal Dialyzers:Automated peritoneal dialysis systems capture incident ESRD patients who might otherwise initiate hemodialysis, capping volume expansion for membrane-based alternatives.
- Hollow Fiber Dialyzers:The EU Medical Device Regulation is tightening biocompatibility testing requirements for these membrane configurations, accelerating replacement demand for certified inventories across European dialysis networks.
Hemodialysis Dialyzers dominates installed base. High-flux Dialyzers is where expansion concentrates.
Material:
Cost tiering separates steam-sterilizable synthetic polymers from cellulose-derived alternatives, with polysulfone and polyethersulfone commanding margin premiums while polyacrylonitrile surfaces attract interest for reduced thrombogenicity in sensitive patients.
- Polysulfone:Thermal stability during steam sterilization enables extended shelf logistics and reduces cold-chain dependency for distributors serving remote treatment sites. Fresenius Medical Care leverages vertically integrated dialysis service networks to anchor recurring demand for this material across multiple continents.
- Polyethersulfone:Superior biocompatibility profiles and chemical resistance sustain premium positioning in high-flux membrane manufacturing. Asahi Kasei dominates through proprietary spinning technology that differentiates product consistency in Japanese precision manufacturing clusters.
- Cellulose Acetate:Legacy membrane composition persists in cost-optimized specifications for India's Pradhan Mantri National Dialysis Program district hospital procurement.
- Polyacrylonitrile:Reduced thrombogenicity surfaces attract interest for patients with sensitivity to synthetic polymer interactions.
- Ethylene Vinyl Alcohol:Barrier properties suit specialized diffusion applications in hybrid membrane configurations.
Polysulfone captures the largest volume share. Polyethersulfone is climbing the fastest on premium tier demand.
Application:
Patient acuity determines replacement frequency and membrane performance requirements, with chronic populations generating predictable recurring revenue while acute applications demand rapid-response supply chain configurations.
- End-Stage Renal Disease:Fixed replacement schedules for chronic patients generate the steadiest volume pull as dialysis centers maintain predictable procurement cycles. Nikkiso competes in high-flux segments where Japanese precision manufacturing differentiates product consistency for this population.
- Chronic Kidney Disease:Pre-dialysis monitoring and delayed progression protocols create intermittent membrane demand through hospital-based nephrology departments.
- Acute Kidney Injury:ICU-based continuous renal replacement therapy demands rapid-turn inventory with flexible sizing options for hemodynamically unstable patients.
- Continuous Renal Replacement Therapy:Extended treatment durations in critical care settings require specialized membrane surface modifications for anticoagulation compatibility.
End-Stage Renal Disease anchors procurement volume. Acute Kidney Injury shows the steepest expansion trajectory on ICU protocol adoption.
End User:
Customer type dictates service bundling requirements, with institutional buyers negotiating technical support commitments while home healthcare agencies demand 24-hour nurse hotline provisions bundled with supply contracts.
- Home Healthcare:Patients in Germany and the United States are sourcing dialyzers through specialty pharmacy intermediaries, bypassing traditional clinic purchasing consortia. Self-administration training protocols reshape manufacturer technical support obligations, with Medicare Advantage plan negotiations tying star ratings to responsive troubleshooting.
- Dialysis Centers:Consolidated purchasing consortia leverage volume concentration to negotiate formulary placement for high-flux variants against standard alternatives.
- Ambulatory Surgical Centers:Procedure-based procurement cycles differ from chronic replacement schedules, requiring flexible distributor inventory positioning.
- Specialty Clinics:Boutique nephrology practices prioritize premium membrane specifications with direct manufacturer relationships.
Dialysis Centers retain the largest installed base. Home Healthcare is gaining share fastest on modality migration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's cold-chain logistics infrastructure underwrites Germany's distribution dominance for steam-sterilizable membrane consignments serving Central European dialysis networks.
United States
Medicare Advantage star ratings and bundled payment models drive procurement consolidation among dialysis center networks. FDA 510(k) clearance pathways shape market access timelines for novel membrane materials. The Detroit-Windsor corridor anchors manufacturing clusters for polysulfone resin feedstocks supplying Midwestern medical device fabricators.
Germany
EU MDR conformity assessment backlogs extend approval timelines for hollow fiber membrane modifications, freezing product pipeline commercialization. The country's notified bodies maintain stringent biocompatibility documentation requirements that fragment regulatory submission strategies. The Rhine-Main metropolitan cluster concentrates dialysis provider purchasing consortia negotiating high-flux dialyzer formulary placement.
Japan
PMDA maintains distinct biocompatibility documentation requirements separate from FDA and EU frameworks, complicating multinational submission strategies. METI industrial policy supports precision manufacturing capabilities in hollow fiber membrane spinning. The Osaka-Kobe industrial corridor hosts concentrated dialyzer production facilities serving domestic and export demand.
India
The Pradhan Mantri National Dialysis Program extends subsidized hemodialysis access to district hospitals, opening procurement channels for cost-optimized dialyzer specifications. CDSCO medical device regulations govern import licensing for foreign-manufactured membrane devices. The Hyderabad-Bangalore pharmaceutical corridor attracts contract manufacturing investments targeting price-sensitive emerging market specifications.
China
NMPA medical device registration requirements create extended review periods for imported dialyzer products, favoring domestic membrane manufacturers. The country's dual carbon goals pressure sterilization process energy consumption in manufacturing facilities. The Yangtze River Delta concentrates dialysis service expansion in Shanghai and surrounding prefecture-level cities.
Global Dialyzer Market Competitive Landscape
Concentration sits with vertically integrated dialysis service providers and specialized membrane manufacturers. Three archetypes dominate: integrated therapy networks controlling captive dialyzer demand, precision polymer spinners commanding premium membrane specifications, and diversified medical device conglomerates leveraging distribution scale. Competitive moves center on backward integration into hollow fiber membrane production and geographic expansion through therapy service acquisitions.
Among Japanese precision manufacturers, Asahi Kasei Corporation and Nikkiso Co. Ltd. occupy positions exemplifying proprietary spinning technology specialization. Fresenius Medical Care AG & Co. KGaA represents the integrated therapy network archetype, anchoring recurring demand through vertically controlled dialysis service operations across multiple continents.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Nikkiso Co. Ltd. |
| Fresenius Medical Care AG & Co. KGaA |
| Allmed Medical Care Holdings Limited |
| Toray Industries Inc. |
| Baxter International Inc. |
| Nipro Corporation |
| JMS Co. Ltd. |
| B. Braun Melsungen AG |
| Others |
Supply & Pricing Matrix
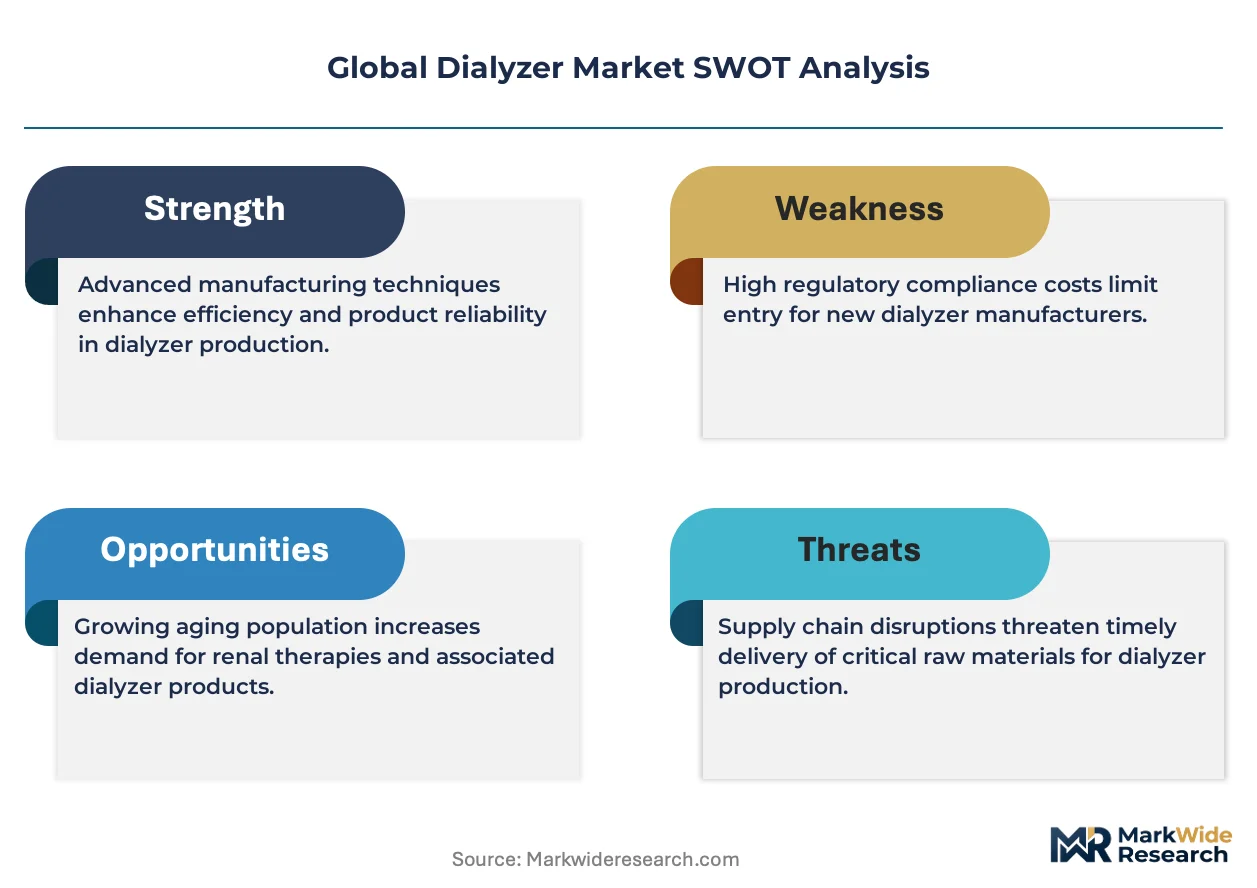
Sixty-to-ninety-day membrane inventory cycles at European dialysis networks concentrate pricing power with polysulfone resin suppliers in Germany and Japan, while steam-sterilization compatibility requirements fragment procurement across cold-chain and ambient-logistics tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates high-flux polysulfone membranes with EU MDR certification from uncertified legacy inventories and cellulose acetate alternatives for cost-sensitive markets. Price differentiation rests on biocompatibility testing documentation and steam-sterilization shelf stability. Cost compression in standard-tier dialyzers is intensifying because India's Pradhan Mantri National Dialysis Program negotiates district-hospital volume contracts. Public hospital systems exhibit highest price sensitivity; academic medical centers in Germany and Japan show lowest.
Supply Chain Analysis
Germany and Japan anchor hollow fiber membrane manufacturing, with the Osaka-Kobe corridor hosting precision spinning facilities and the Rhine-Main cluster concentrating dialysis provider purchasing consortia. Polysulfone and polyethersulfone resin feedstocks draw from benzene derivative markets in the US and EU. Single-source vulnerability concentrates in Japanese precision spinning equipment for high-flux specifications. Distribution runs through consolidated purchasing consortia serving dialysis center networks alongside specialty pharmacy intermediaries for home-use channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized toxicology expertise for ISO 10993-5 cytotoxicity validation represents the critical scarcity constraining new dialyzer commercialization, with analytical chemist recruitment bottlenecks extending EU MDR approval timelines.
For Market Incumbents: Compound backward integration into hollow fiber membrane spinning to capture margin from polysulfone resin volatility. Lock in 24-hour nurse hotline service bundling with Medicare Advantage plans to defend against home healthcare agency channel disintermediation. Prioritize MDR-certified inventory conversion before notified body backlogs extend further. For New Entrants and Emerging Players: Lead with cost-optimized dialyzer specifications targeting India's district hospital procurement under the Pradhan Mantri National Dialysis Program, where reimbursement expansion outpaces domestic manufacturing capacity. Partner with Hyderabad-Bangalore contract manufacturers for price-sensitive emerging market production. Position portable wearable artificial kidney reduced-membrane-area cartridges for ambulatory dialysis white space. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical device conglomerates with underutilized membrane manufacturing assets. Frame long-term viability around 5-10 year home dialysis modality migration sustaining recurring dialyzer demand. Watch FDA 510(k) clearance pathway efficiency versus EU MDR review duration as regulatory arbitrage signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | Notified body approval unlocks formulary placement in German and French dialysis networks. |
| Backward Integration into Membrane Spinning | In-house polysulfone production insulates margins from benzene derivative price swings. |
| Home Healthcare Agency Partnership | Specialty pharmacy intermediaries bypass clinic purchasing consortia in Germany and the US. |
| Portable Wearable Cartridge Development | Miniaturized sorbent regeneration enables ambulatory dialysis outside fixed infrastructure. |
| India Contract Manufacturing Scale-Up | Hyderabad-Bangalore corridor offers cost base for Pradhan Mantri program specifications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across nephrologists, hospital purchasing committees, biomedical engineers, GPO contracts managers, and dialysis service network procurement leads. Secondary validation drew from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up dialyzer volume modeling and top-down market sizing triangulated across membrane material consumption and treatment modality penetration data.
Across the projection horizon, the analytical framework segmented by product type, material composition, application acuity, and end-user channel, with regional regulatory clusters modeled separately. CAGRs derived from treatment volume growth, replacement schedule frequencies, and modality shift assumptions. Forecast inputs included aging demographic trajectories, reimbursement rate negotiations, and biocompatibility testing capacity constraints.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage bundled payment models or accelerated EU MDR approval timelines would require recalibration. Forecasts reflect documented assumptions about home dialysis training protocol adoption and polymer feedstock price stability. Recalibration cycles align with material shifts in notified body capacity, reimbursement framework revisions, or wearable artificial kidney technology maturation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Hemodialyzer Market
Nephrology
US Dialysis Market
Nephrology
Proteinuria Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Dialysis Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Dialysis Service Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
US Dialysis Services Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market