
 Real-World Evidence Analytics Market | 2026-2036
Real-World Evidence Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Real-World Evidence Analytics Market Intelligence
Synthetic data generation is decoupling RWE analytics from traditional patient-consent bottlenecks, collapsing data procurement costs while expanding cohort diversity. IQVIA Inc. leverages its global healthcare data repository to anchor multi-country study designs for pharmaceutical sponsors. Oracle Health sustains deep EHR integration across hospital networks, positioning its platform as a near-real-time pipeline for regulatory-grade evidence. Parexel International Corporation differentiates through therapeutic-area specialization, concentrating biostatistical talent in oncology and rare disease verticals where external comparators face the steepest methodological scrutiny.
Real-world evidence analytics encompasses the systematic collection, integration, and statistical analysis of healthcare data derived from routine clinical practice, insurance claims, patient registries, and wearable devices, typically processed through federated learning architectures that preserve patient privacy while enabling multi-site computation. The primary commercial purpose is generating regulatory-acceptable evidence to support drug approval, label expansion, and reimbursement negotiations without the cost and duration of randomized controlled trials. Services currently command the largest revenue share as sponsors outsource protocol design, bias mitigation, and health authority submission preparation to specialized vendors. Machine learning applications represent the fastest-expanding technology segment, though cloud computing infrastructure absorbs disproportionate capital investment as data volumes scale beyond on-premise capacity.
FDA guidance on RWE standards shapes product development priorities for US-facing vendors, while EMA's DARWIN EU initiative creates parallel compliance obligations for European submissions. HIPAA constraints on identifiable health information directly determine architectural choices around data de-identification and tokenization in domestic deployments. Stakeholders must monitor evolving health authority positions on synthetic control arm acceptability, as regulatory divergence between FDA and EMA pathways would fragment platform investment and talent deployment strategies.
Market Dynamics
Synthetic data generation is collapsing the traditional patient-consent bottleneck that has constrained real-world evidence expansion for decades, enabling pharmaceutical sponsors to construct diverse cohorts without longitudinal recruitment delays or privacy exposure risks.
Growth Catalysts
- FDA 21st Century Cures Act:The framework accelerates regulatory acceptance of external control arms and patient-generated data sources, compressing trial timelines for oncology and rare disease submissions.
- Federated learning architectures:These privacy-preserving computation networks enable multi-site analysis without centralizing identifiable health information, unlocking previously inaccessible hospital system partnerships.
- Integrated payer-provider networks:United States healthcare consolidation generates longitudinal datasets with unmatched scale and granularity, anchoring commercial evidence generation for label expansion negotiations.
Market Restraints
- HIPAA de-identification complexity:Safe Harbor and Expert Determination standards impose substantial compliance costs on domestic deployments, particularly for genomic and rare disease datasets where re-identification risks concentrate.
- EMA-FDA methodological divergence:Differing health authority positions on synthetic control arm acceptability fragment platform investment strategies and force redundant study designs for dual submissions.
- Biostatistical talent scarcity:Therapeutic-area specialization in oncology and rare diseases faces acute shortages of methodologists capable of defending external comparator validity under regulatory scrutiny.
Strategic Opportunities
- Japan's PMDA real-world data pathway:The regulator's expanding acceptance of registry-based evidence creates first-mover positioning for vendors with Asian hospital network integration.
- Wearable device convergence:Continuous glucose monitors, cardiac implants, and activity trackers generate regulatory-grade endpoints that traditional claims data cannot capture, opening new therapeutic monitoring applications.
- Cloud-native evidence platforms:Subscription-based delivery models displace capital-intensive on-premise installations, lowering barriers for mid-cap biotech sponsors without internal data science infrastructure.
Industry Challenges
- Health authority submission preparation:Protocol design and bias mitigation for regulatory-grade evidence demands specialized expertise that sponsors struggle to retain in-house, creating dependency on vendor relationships.
- Legacy EHR integration friction:Hospital network data extraction requires navigating fragmented technical standards and institutional review board negotiations that extend deployment timelines unpredictably.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-World Evidence Analytics Market |
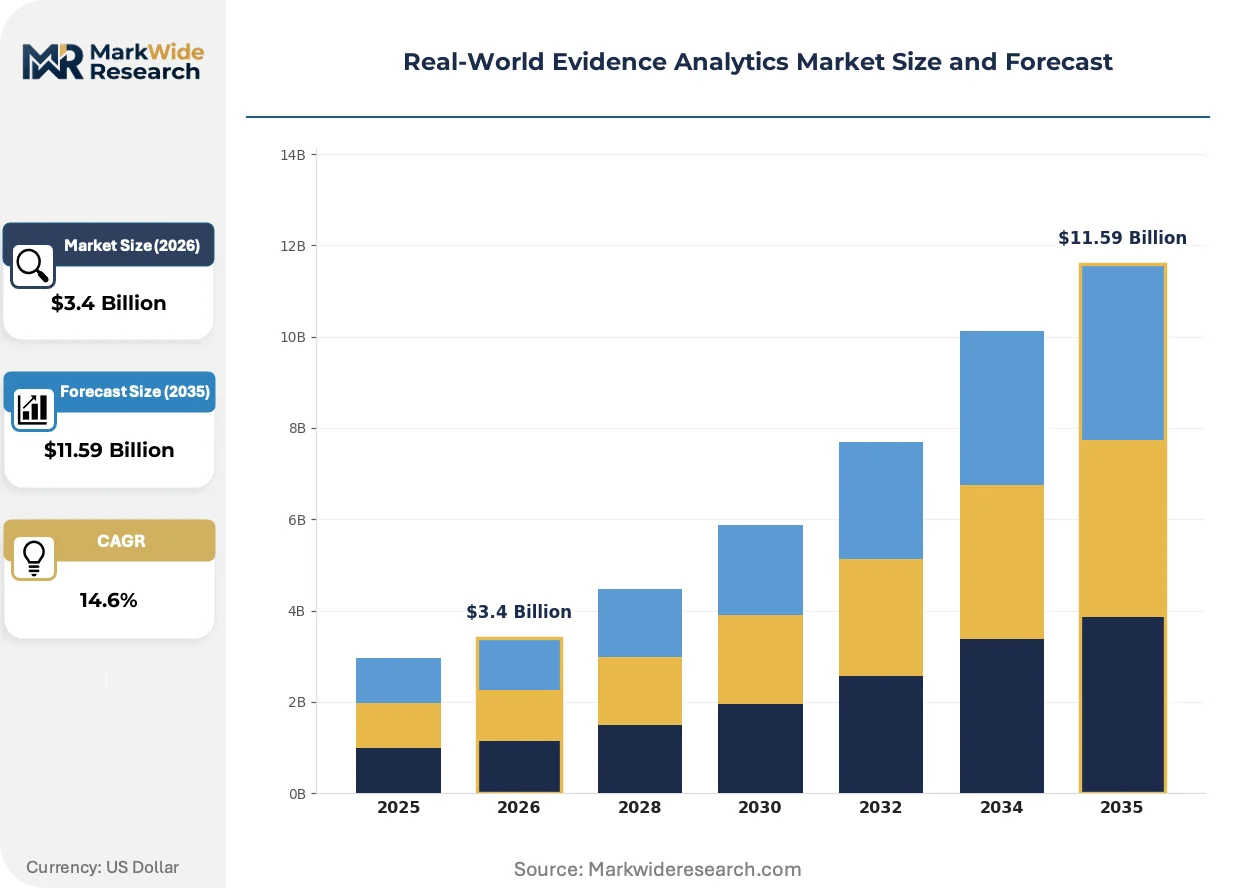
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $11.59 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Services, Platform, Solutions Application: Clinical Development, Market Access, Drug Safety, Real-Time Monitoring End User: Pharmaceutical Companies, Biotech Firms, Research Organizations, Healthcare Providers Technology: Data Analytics, Machine Learning, Artificial Intelligence, Cloud Computing |
| Companies Covered | IQVIA Inc., Optum Inc., Oracle Health, ICON plc, IBM, Syneos Health, Merative, Cognizant, Parexel International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-World Evidence Analytics Market Strategic Shifts & Innovations
Generative adversarial networks and diffusion models are actively displacing traditional data procurement methods, while regulatory frameworks on both sides of the Atlantic scramble to keep pace with methodological innovation.
Generative AI for synthetic patient records is rewriting the economics of cohort construction. Pharmaceutical sponsors now deploy these tools to simulate control arms with matched demographic and disease progression characteristics. The technology is compressing study startup from months to weeks while eliminating the geographic constraints that previously limited trial diversity.
EMA's DARWIN EU initiative mandates standardized real-world data access across member states, forcing vendors to re-architect platforms for cross-border federated compliance. The regulation creates parallel obligations to FDA frameworks, with data quality and interoperability standards now determining platform viability for European submissions. Oncology and immunology sponsors face the steepest adaptation costs given existing study pipelines.
Outcome-based contracting between payers and manufacturers is reshaping evidence requirements for reimbursement negotiations. Pharmaceutical sponsors now commission continuous monitoring studies rather than discrete trials, with payment contingent on demonstrated effectiveness in routine practice. Germany's G-BA and England's NICE anchor this shift in Europe, while Medicare Advantage plans accelerate comparable arrangements domestically.
Real-World Evidence Analytics Market Segmentation
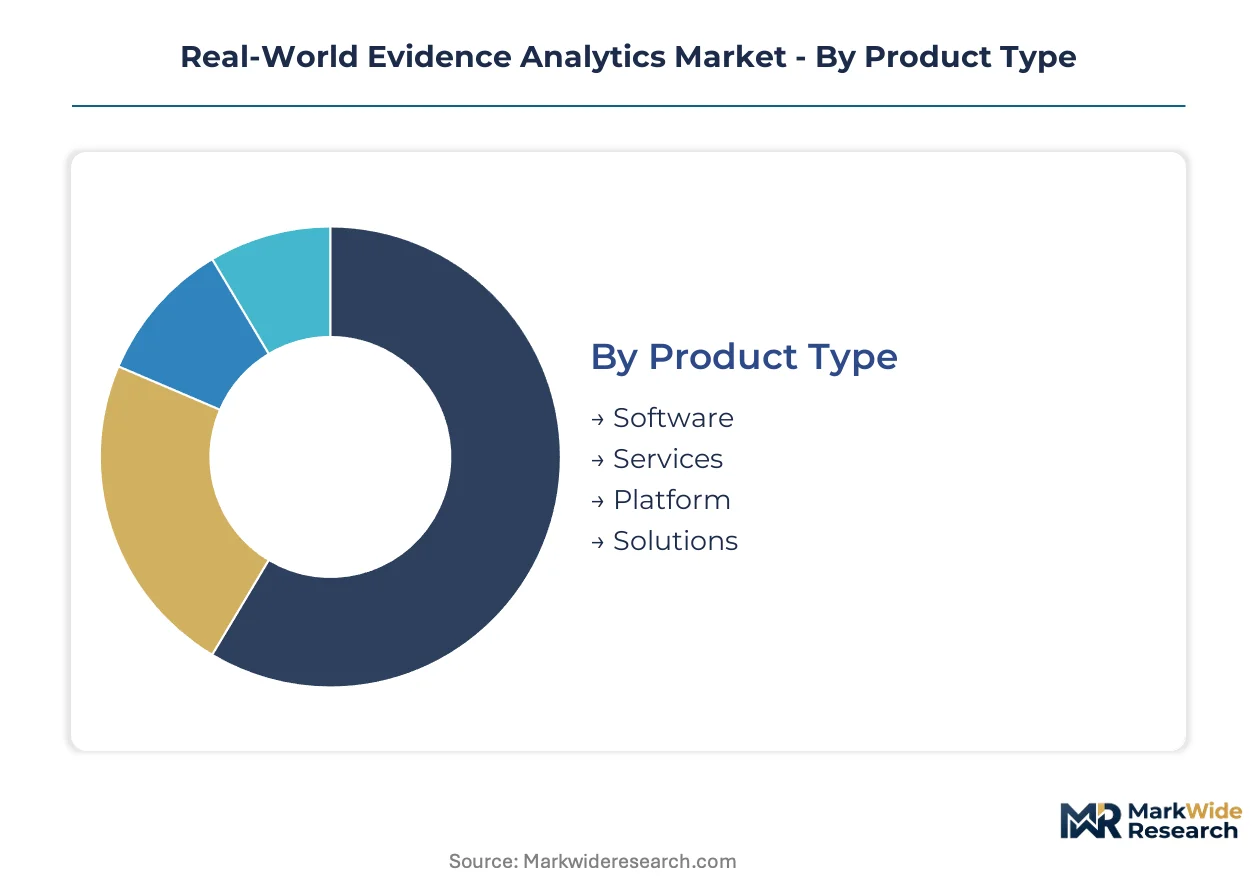
Segmentation in real-world evidence analytics determines procurement strategies and vendor selection criteria. Pharmaceutical sponsors weight segments differently based on therapeutic area maturity, regulatory pathway complexity, and internal data science capabilities.
Product Type:
Capital intensity varies sharply across product categories, with platform infrastructure demanding sustained engineering investment while services require talent-heavy operational scaling.
- Software:Modular applications for data integration, statistical analysis, and regulatory submission formatting deploy across sponsor IT environments. Pharmaceutical companies in the United States prioritize FDA 21st Century Cures Act compliance modules to accelerate external control arm submissions.
- Services:Outsourced protocol design, biostatistical analysis, and health authority engagement dominate current revenue as sponsors lack in-house methodological expertise. Demand concentrates among mid-cap biotech firms without dedicated real-world evidence departments.
- Platform:Integrated environments combining data ingestion, analytics engines, and visualization layers.
- Solutions:Pre-configured packages targeting specific regulatory or commercial use cases.
Services absorbs the bulk of installed capacity; platform is expanding most quickly as sponsors seek to reduce recurring vendor dependency.
Application:
Application segmentation tracks the drug development lifecycle, with each phase imposing distinct evidentiary standards and timeline pressures.
- Clinical Development:External control arm construction, synthetic cohort generation, and comparative effectiveness studies compress randomized controlled trial timelines. Oncology sponsors in the United States leverage these applications under FDA guidance to accelerate rare disease approvals.
- Market Access:Reimbursement dossiers, health technology assessments, and payer negotiation support demonstrate real-world value. Germany's G-BA and England's NICE drive European demand for continuous monitoring studies tied to outcome-based contracts.
- Drug Safety:Post-market surveillance, signal detection, and pharmacovigilance reporting.
- Real-Time Monitoring:Continuous endpoint capture through wearable devices and EHR feeds.
Clinical development commands the largest sponsor budgets; real-time monitoring is climbing the fastest as wearable-generated endpoints achieve regulatory acceptance.
End User:
End user segmentation reveals divergent procurement authority and technical sophistication across the healthcare research ecosystem.
- Pharmaceutical Companies:Large sponsors with global portfolios invest in multi-country federated learning architectures to satisfy simultaneous FDA and EMA submission requirements. Internal real-world evidence teams increasingly demand cloud-native platforms over service-heavy engagements.
- Biotech Firms:Resource-constrained developers outsource entire evidence generation workflows to specialized vendors. United States-based mid-cap sponsors prioritize subscription pricing models that preserve capital for clinical trial execution.
- Research Organizations:Academic medical centers and contract research organizations.
- Healthcare Providers:Integrated delivery networks and hospital systems.
Pharmaceutical companies anchor platform development roadmaps; biotech firms are gaining share fastest as vendor pricing models adapt to smaller sponsor capital structures.
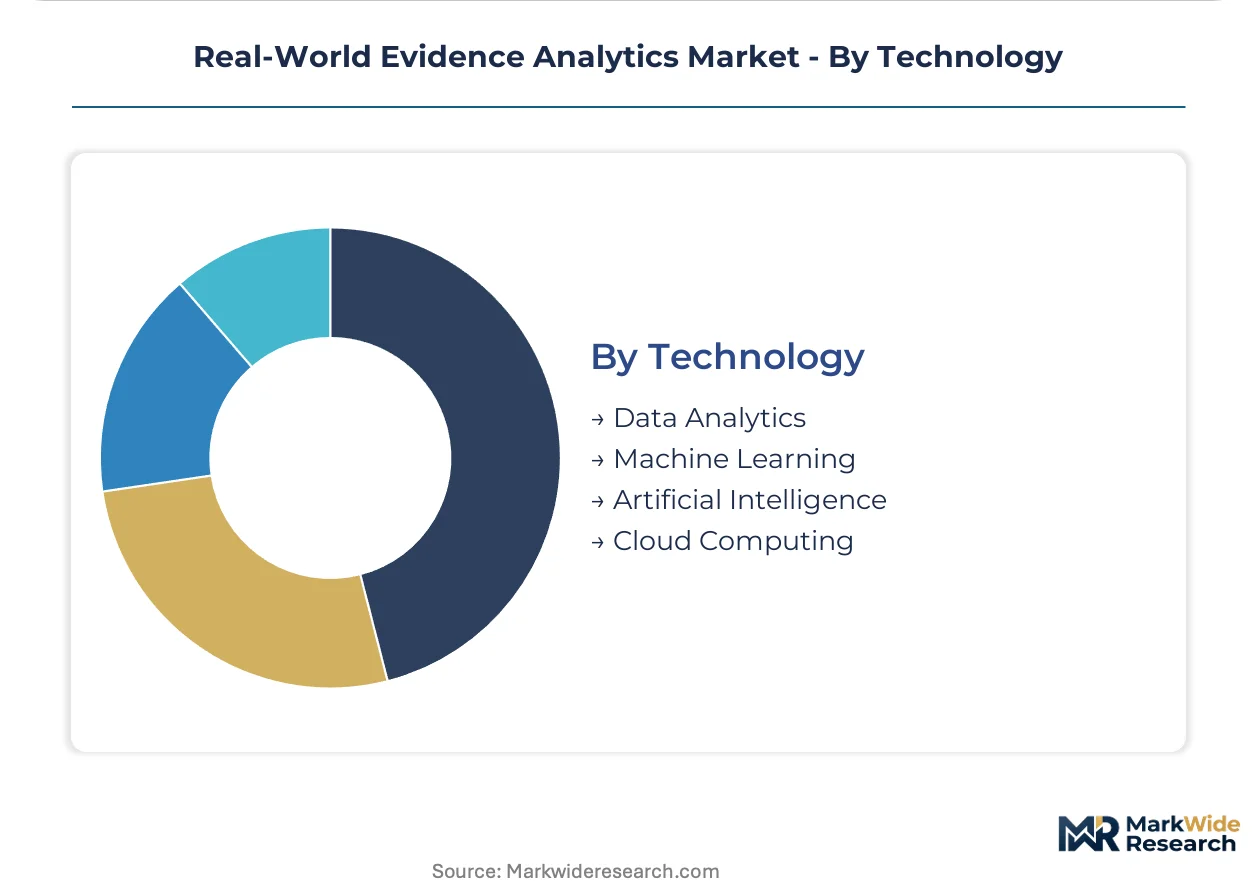
Technology:
Technology segmentation captures the architectural shift from descriptive statistics toward predictive and generative methodologies.
- Machine Learning:Supervised and unsupervised algorithms for patient stratification, treatment response prediction, and bias detection in observational data. Oncology applications face the steepest methodological scrutiny under FDA and EMA divergence on synthetic comparator validity.
- Artificial Intelligence:Generative adversarial networks and diffusion models synthesize patient records with matched demographic and disease progression characteristics. These tools collapse cohort construction timelines from months to weeks while eliminating geographic diversity constraints.
- Data Analytics:Traditional statistical methods and visualization tools.
- Cloud Computing:Scalable infrastructure for multi-site federated computation.
Machine learning absorbs the majority of vendor R&D investment; artificial intelligence is expanding most quickly as generative methods rewrite cohort construction economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors concentrate evidence generation spending in markets with integrated payer data and regulatory clarity. The United States dominates procurement volumes, while European and Asian regulators accelerate parallel framework development.
United States
FDA's 21st Century Cures Act framework anchors external control arm submissions for oncology and rare disease trials. HIPAA Safe Harbor and Expert Determination standards shape domestic platform architecture around de-identification protocols. The Boston-Cambridge corridor hosts dense clusters of biostatistical talent serving mid-cap biotech sponsors.
Germany
G-BA outcome-based contracting mandates continuous real-world monitoring for reimbursement negotiations. The country's national pharmaceutical regulator aligns with EMA DARWIN EU interoperability standards for cross-border federated analysis. Munich and Berlin anchor vendor operations supporting pharmaceutical label expansion dossiers.
United Kingdom
NICE health technology assessments drive demand for comparative effectiveness studies using NHS longitudinal records. GDPR compliance requirements force architectural choices around patient consent and data tokenization. London's health data research hubs concentrate academic-medical partnerships for synthetic cohort validation.
Japan
PMDA's expanding registry-based evidence pathway creates first-mover opportunities for vendors with hospital network integration. METI digital health initiatives accelerate wearable-generated endpoint acceptance for regulatory submissions. Tokyo-Osaka pharmaceutical corridors concentrate sponsor evidence generation budgets.
India
CDSCO's evolving reliance on real-world data for post-market surveillance expands contract research demand. The country's national pharmaceutical regulator grapples with data localization requirements against cross-border federated study needs. Hyderabad and Bangalore clusters host biostatistical service centers for global pharmaceutical sponsors.
Real-World Evidence Analytics Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing premium pricing against modular service providers. The vendor base organizes around three archetypes: global data repository operators, therapeutic-area specialists, and cloud-native analytics platforms. Consolidation pressures favor vendors with multi-country federated compliance capabilities. Dominant competitive moves include strategic partnerships with hospital networks and portfolio diversification into synthetic data generation tools.
Among global data repository operators, IQVIA Inc. and Oracle Health occupy positions anchoring multi-country study designs for pharmaceutical sponsors. Parexel International Corporation exemplifies the therapeutic-area specialist archetype, with concentration in oncology and rare disease verticals where external comparator validity faces steepest methodological scrutiny. These three entities represent the primary competitive anchors shaping platform development roadmaps and service pricing benchmarks.
| Leading Market Players |
|---|
| IQVIA Inc. |
| Optum Inc. |
| Oracle Health |
| ICON plc |
| IBM |
| Syneos Health |
| Merative |
| Cognizant |
| Parexel International Corporation |
| Others |
Cost & Logistics Intelligence
GDPR-compliant data residency mandates gate qualified supply access and premium-tier pricing for European pharmaceutical sponsors, forcing vendors to architect federated infrastructure that satisfies cross-border computation rules before contract eligibility. HIPAA Safe Harbor certification in the United States creates parallel qualification barriers, segmenting vendors into premium-priced regulatory-grade tiers versus standard service-only offerings that lack direct submission pathways.
Pricing Analysis
Volume concentrates in subscription-based SaaS tiers while margins accrue to bespoke protocol design engagements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated platform modules from service-only analytics and basic visualization tools. Cost compression in standard-tier biostatistical services intensifies as automation displaces manual cohort construction. Mid-cap biotech sponsors exhibit acute price sensitivity, whereas large pharmaceutical companies prioritize regulatory-grade validation over unit economics.
Supply Chain Analysis
India's data localization requirements are reshaping sourcing strategies for global contract research organizations, compelling local server deployments that fragment previously centralized architectures. Talent supply concentrates in the United States, India, and Germany, with biostatistical methodologists and clinical data scientists forming the critical workforce layer. Raw material dependencies span de-identified EHR feeds, claims databases, and wearable-generated endpoints. Single-source vulnerability concentrates in United States-based integrated payer-provider networks that anchor longitudinal dataset quality. Distribution runs through direct enterprise sales to pharmaceutical sponsors and channel partnerships with hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative adversarial networks for synthetic patient records are displacing traditional longitudinal recruitment, compressing study startup timelines from months to weeks while eliminating geographic diversity constraints.
For Market Incumbents: Acquire federated learning infrastructure assets to defend against cloud-native entrants threatening multi-site computation dominance. IQVIA Inc. and Oracle Health should deepen hospital network exclusivity agreements that lock in EHR feed access. Biostatistical talent scarcity in oncology and rare diseases represents the priority defensive investment zone, as methodologist retention directly determines synthetic comparator validity under regulatory scrutiny. For New Entrants and Emerging Players: Cloud-native platform delivery offers the most penetrable route into mid-cap biotech sponsors lacking internal data science infrastructure. Japan's PMDA registry-based evidence pathway presents first-mover positioning for vendors with Asian hospital network integration. Wearable-generated endpoint capture for continuous monitoring studies offers a second white-space target underserved by legacy service-heavy incumbents. Subscription pricing models that preserve sponsor capital for clinical trial execution anchor effective go-to-market positioning. For Investors and Strategic Acquirers: EMA-FDA methodological divergence on synthetic control arm acceptability is the leading indicator that platform vendors with dual-compliance architectures will command acquisition premiums. Long-term viability frames around five-to-ten year regulatory convergence timelines, with consolidation favoring multi-country federated compliance capabilities. Acquisition target archetypes include therapeutic-area specialists in oncology and rare diseases with defended biostatistical talent pools. Watch for health authority submission rejections citing external comparator validity as the inflection signal for methodological standardization investments.| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Infrastructure Deployment | Privacy-preserving computation unlocks hospital system partnerships under HIPAA and GDPR constraints. |
| Synthetic Data Generation Capability Buildout | Generative AI for patient records collapses cohort construction economics and timeline risk. |
| Therapeutic-Area Specialist Acquisition | Oncology and rare disease biostatistical talent defends external comparator validity under FDA scrutiny. |
| Outcome-Based Contracting Platform Development | Continuous monitoring studies align with Germany's G-BA and Medicare Advantage reimbursement models. |
| Cross-Border Regulatory Compliance Certification | Dual FDA-EMA validation architectures capture premium pricing for global pharmaceutical sponsors. |
Research Approach
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads, and payer access specialists, combined with secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases, underwrites the qualitative findings in this study. Bottom-up segmentation modeling triangulates against top-down market sizing approaches to bound estimation error.
Comparable-period anchoring to historical regulatory submission volumes and pharmaceutical R&D expenditure patterns structures the forecast framework across the projection horizon. Segmentation dimensions span product type, application, end user, and technology, with therapeutic-area concentration and regional regulatory cluster as industry-specific modifiers. CAGRs derive from trend extrapolation adjusted for policy inflection points, with synthetic data adoption curves and federated learning deployment rates as key forecast inputs.
The model holds under stable health authority guidance on external control arm acceptability; deviation in FDA-EMA methodological divergence or HIPAA enforcement intensity would shift platform investment and talent deployment trajectories. Forecasts reflect documented assumptions regarding regulatory convergence timelines and synthetic data validation standards. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Research
Global Clinical Trial Management Systems Market
Clinical Research
Clinical Trial Logistics and Direct-to-Patient Delivery Platforms Market
Clinical Research
Clinical Trial Patient Recruitment Services Market
Clinical Research
Early Phase Clinical Trial Outsourcing Market
Clinical Research
HIV Clinical Trials Market
Clinical Research
AI-Assisted Clinical Trial Protocol Design Market
Clinical Research
Global Healthcare Contract Research Outsourcing Market
Clinical Research
Healthcare Contract Research Organization Market
Clinical Research
Edema Clinical Trials Market
Clinical Research
Global in Silico Clinical Trials Market
Clinical Research
US Clinical Trials Market
Clinical Research
Global in Vivo Toxicology Market
Clinical Research
US Virtual Clinical Trials Market
Clinical Research
Europe Clinical Trials Market
Clinical Research
AI-Based Clinical Trials Solution Provider Market
Clinical Research
Clinical Trial Biorepository and Archiving Solutions Market