
 Plasmapheresis Market | 2026-2036
Plasmapheresis Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmapheresis Market Intelligence
CE marking under the EU Medical Device Regulation is redrawing competitive boundaries for automated plasmapheresis equipment sold into European health systems. Fresenius SE & Co. KGaA leverages its integrated dialysis-plasma platform to dominate hospital procurement cycles in Western Europe. Haemonetics Corporation anchors the North American donor center segment through captive software and disposable ecosystems. Asahi Kasei Medical specializes in membrane filtration technology that differentiates its devices in therapeutic plasma exchange protocols.
Plasmapheresis is an extracorporeal blood purification procedure that separates plasma from whole blood through centrifugation or membrane filtration, returning cellular components to the patient with replacement fluid or selective therapeutic modification. The process typically processes 2-4 liters of plasma per session and operates at blood flow rates of 50-150 mL/min depending on vascular access and device configuration. Automated equipment commands the largest installed base across blood centers and dialysis facilities due to throughput efficiency and operator standardization requirements. Membrane separation technology is gaining share in specialty clinic settings where lower capital footprint and modular scaling offset the processing speed advantages of centrifugation systems.
FDA 510(k) clearance pathways and the EU MDR conformity assessment process shape device commercialization timelines and clinical evidence requirements for plasmapheresis manufacturers seeking multi-regional market access. The EPA and OSHA frameworks govern waste handling and operator exposure limits in high-volume plasma collection facilities, directly influencing disposable kit design and facility layout specifications. Stakeholders must monitor evolving reimbursement coding for therapeutic plasma exchange procedures across Medicare and national health service frameworks to anticipate volume shifts between hospital-based and outpatient delivery settings.
Market Dynamics
Centrifugation-based systems face mounting pressure from membrane filtration alternatives as hospital networks prioritize lower capital footprints and modular scaling capabilities over raw throughput efficiency.
Growth Catalysts
- Autoimmune Protocol Expansion:Rising therapeutic plasma exchange volumes for conditions such as myasthenia gravis and Guillain-Barré syndrome are pulling additional plasma collection capacity into hospital networks.
- FDA 510(k) Streamlining:Expedited clearance pathways for predicate device submissions are compressing commercialization timelines for next-generation apheresis equipment in the United States.
- Membrane Technology Maturation:Advances in hollow-fiber filtration are enabling single-session plasma volumes that rival centrifugation without the centrifuge capital burden.
Market Restraints
- Specialized Operator Dependency:Therapeutic plasma exchange requires trained perfusionists or nephrologists, creating staffing bottlenecks that constrain session throughput in community hospital settings.
- Single-Use Kit Cost Concentration:Disposable tubing sets and membrane cartridges represent 60-70% of per-procedure economics, leaving operators exposed to polymer resin price volatility.
- Reimbursement Compression:Medicare coding revisions for outpatient plasma exchange are narrowing margin structures and discouraging capital investment in freestanding clinic formats.
Strategic Opportunities
- Home-Based Therapeutic Delivery:Portable membrane systems with simplified vascular access protocols could unlock ambulatory patient segments currently tethered to dialysis chairs.
- CE Marking Under EU MDR:Stricter conformity assessment timelines are advantaging manufacturers with established quality management systems over smaller competitors seeking European market entry.
- Plasma-Derived Biologics Pipeline:Expanding immunoglobulin and albumin demand from fractionators is pulling investment into higher-frequency donor collection infrastructure.
Industry Challenges
- Cross-Training Shortfalls:The perfusionist-to-nephrologist skill gap limits workforce mobility between cardiac surgery and apheresis service lines.
- Legacy Device Interoperability:Proprietary disposable ecosystems from incumbent manufacturers complicate mixed-fleet deployments and lock hospitals into single-vendor maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmapheresis Market |
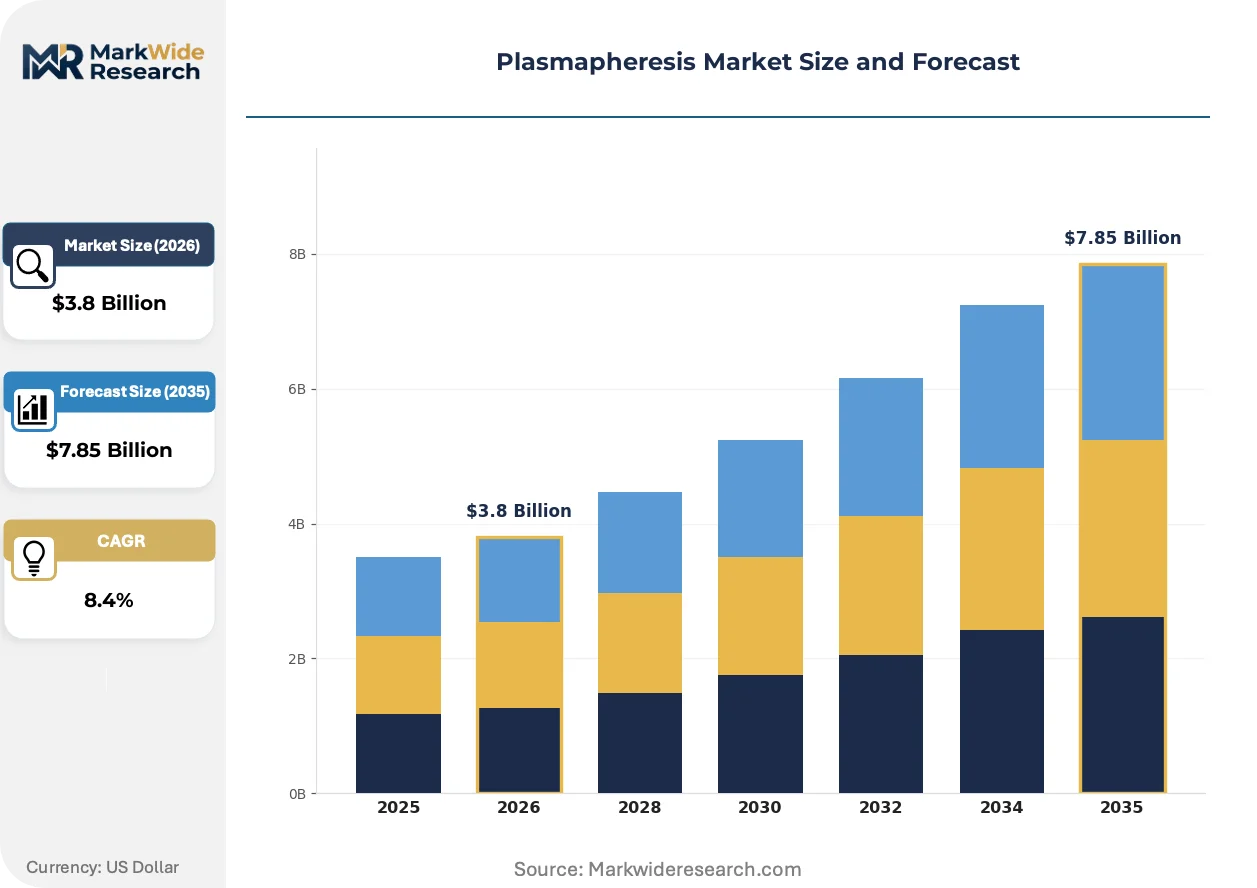
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Equipment, Manual Devices, Single-Use Kits, Plasma Filters, Blood Bags Application: Autoimmune Disorders, Neurological Disorders, Hematologic Conditions, Refractory Diseases, Therapeutic Plasma Exchange End User: Dialysis Centers, Blood Centers, Specialty Clinics, Research Institutions, Homecare Providers Technology: Continuous Flow, Intermittent Flow, Centrifugation, Membrane Separation, Adsorption Techniques |
| Companies Covered | Terumo BCT, Fresenius SE & Co. KGaA, Haemonetics Corporation, Baxter International, Asahi Kasei Medical, B. Braun Melsungen, Grifols, Octapharma, Kedrion Biopharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmapheresis Market Strategic Shifts & Innovations
Membrane filtration architectures are gaining technical credibility against centrifugation dominance as clinical evidence accumulates and capital-constrained buyers seek operational flexibility.
Continuous-flow membrane separation is displacing batch centrifugation in specialty clinic deployments where space constraints and lower session volumes favor compact, modular device footprints. Outpatient therapeutic centers in Germany and Japan are adopting these systems for chronic autoimmune maintenance protocols. The shift is compressing the installed base advantage of legacy centrifuge manufacturers and opening procurement cycles to membrane-specialist vendors.
The EU Medical Device Regulation's tightened clinical evidence requirements for Class IIb active therapeutic devices are extending conformity assessment timelines by 12-18 months for manufacturers lacking predicate device equivalence. European notified bodies are demanding expanded biocompatibility testing for blood-contacting surfaces in disposable apheresis kits. Manufacturers with MDR transition experience are capturing market share from competitors still navigating technical documentation gaps.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases and negotiating direct maintenance agreements with third-party clinical engineering firms. This behavior is most pronounced in United States health systems operating 50+ apheresis chairs across multiple sites. Equipment vendors are responding with tiered service offerings that separate software updates from hardware maintenance to retain contract attach rates.
Plasmapheresis Market Segmentation
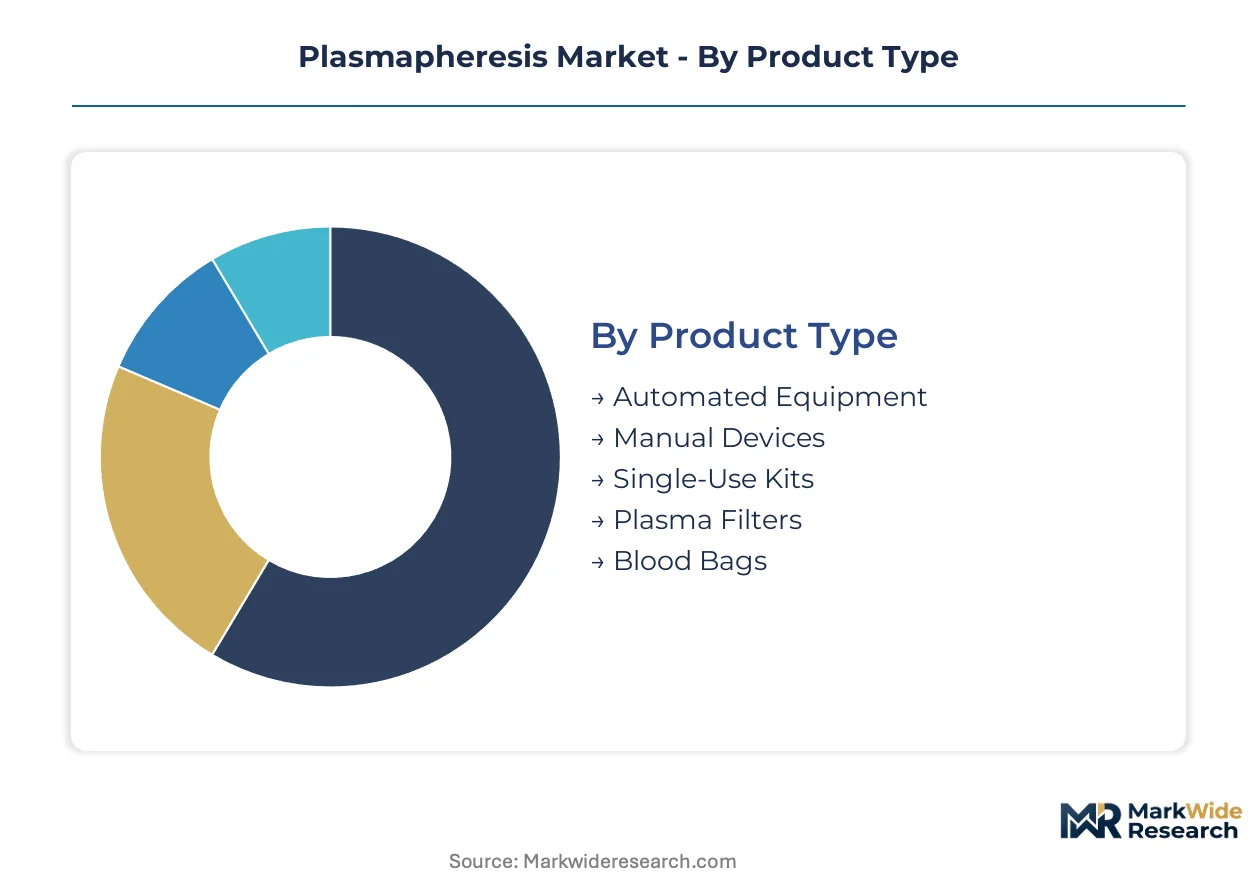
Segmentation in plasmapheresis reveals how technology substitution and care setting migration reshape procurement priorities across hospital networks and donor facilities. Understanding these divides exposes where capital budgets concentrate versus where operational flexibility commands premium positioning.
Product Type:
Substitution pressure from membrane filtration and single-use disposables is fragmenting the equipment hierarchy as buyers trade centrifuge throughput for modular deployment options.
- Automated Equipment:Centrifugation-based systems process 2-4 liters of plasma per session at blood flow rates of 50-150 mL/min. Hospital networks in the United States anchor demand here, driven by throughput requirements in high-volume donor centers and the need for operator standardization across multi-site deployments.
- Single-Use Kits:Disposable tubing sets and membrane cartridges constitute 60-70% of per-procedure economics. Blood centers concentrate procurement of these kits, though polymer resin price volatility creates margin exposure that shapes long-term supply agreements.
- Manual Devices:Basic separation units for resource-constrained settings lacking automated infrastructure.
- Plasma Filters:Hollow-fiber membrane cartridges enabling therapeutic plasma exchange without centrifuge capital burden.
- Blood Bags:Collection and storage vessels for source plasma prior to fractionation processing.
Automated equipment anchors the volume base while single-use kits gain share at the steepest rate.
Application:
Cost tier stratification separates acute inpatient protocols from chronic outpatient maintenance, with reimbursement coding determining where margin structures hold.
- Therapeutic Plasma Exchange:Extracorporeal procedure removing pathogenic antibodies and immune complexes from patient plasma. Neurological and autoimmune indications in German and Japanese outpatient centers are pulling membrane-based system adoption for chronic maintenance protocols.
- Autoimmune Disorders:Myasthenia gravis and Guillain-Barré syndrome protocols are expanding hospital-based collection capacity. Medicare coding revisions for outpatient procedures are narrowing margin structures and discouraging freestanding clinic investment in the United States.
- Neurological Disorders:Chronic inflammatory demyelinating polyneuropathy and other conditions requiring repeated plasma exchange sessions.
- Hematologic Conditions:Thrombotic thrombocytopenic purpura and related disorders demanding urgent plasma intervention.
- Refractory Diseases:Treatment-resistant cases where plasmapheresis serves as salvage therapy after pharmaceutical failure.
Therapeutic plasma exchange commands the revenue concentration while autoimmune disorder protocols expand most quickly across hospital service lines.
End User:
Customer type fragmentation reflects divergent capital cycles, with dialysis networks integrating plasma exchange into existing chair infrastructure while blood centers optimize for donor throughput.
- Blood Centers:High-volume plasma collection facilities supplying fractionators with source material for immunoglobulin and albumin production. The United States donor base density and fractionation infrastructure exceed other national markets, concentrating procurement authority in multi-site operators.
- Dialysis Centers:Facilities leveraging existing vascular access infrastructure and clinical staffing for therapeutic plasma exchange. EPA and OSHA waste handling frameworks govern disposable kit design and facility layout specifications in high-volume settings.
- Specialty Clinics:Focused autoimmune and neurology practices adopting compact membrane systems.
- Research Institutions:Academic medical centers developing novel apheresis protocols and device validation studies.
- Homecare Providers:Emerging delivery channel for portable membrane systems with simplified vascular access.
Blood centers anchor the volume base while specialty clinics gain share at the steepest rate.
Technology:
Maturity gradients separate established centrifugation dominance from membrane filtration's accelerating technical credibility as clinical evidence accumulates.
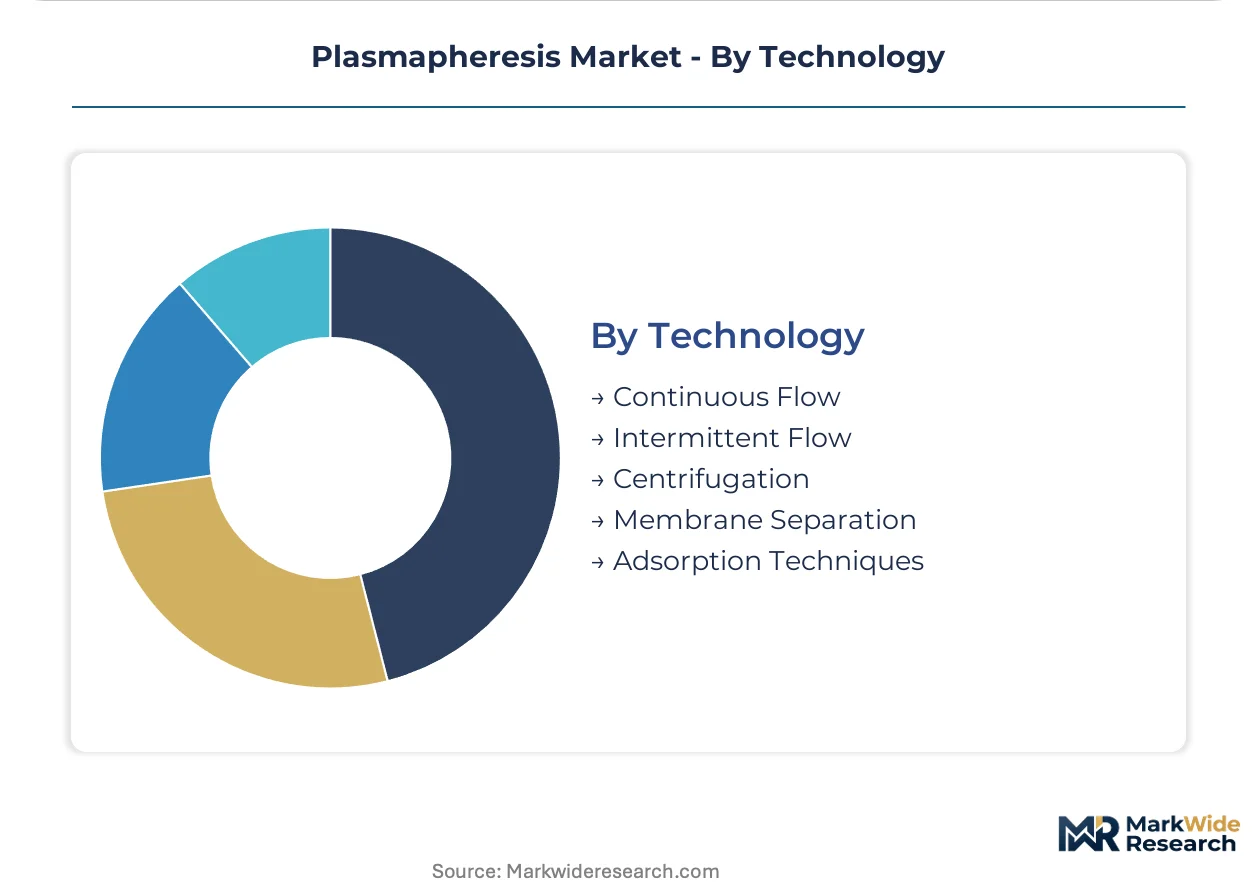
- Centrifugation:Density-gradient separation technology commanding the largest installed base across blood centers and dialysis facilities. Fresenius SE leverages integrated dialysis-plasma platforms to dominate hospital procurement cycles in Western Europe.
- Membrane Separation:Hollow-fiber filtration enabling single-session plasma volumes rivaling centrifugation without capital burden. Asahi Kasei Medical specializes in this technology for therapeutic plasma exchange protocols in specialty clinic deployments.
- Continuous Flow:Real-time plasma separation and return systems maximizing processing efficiency.
- Intermittent Flow:Batch processing architecture with lower complexity and capital requirements.
- Adsorption Techniques:Selective pathogen removal through column-based immunoadsorption.
Centrifugation anchors the volume base while membrane separation gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees and blood center operators concentrate purchasing authority in markets with established plasma fractionation infrastructure and dense donor networks. Regulatory pathways for apheresis devices vary substantially across jurisdictions, shaping where manufacturers prioritize market entry sequencing.
United States
FDA 510(k) clearance pathways for predicate device submissions compress commercialization timelines for next-generation apheresis equipment. The EPA and OSHA frameworks govern waste handling specifications in high-volume collection facilities. Plasma fractionation infrastructure concentrates in North Carolina and California, where multi-site blood center operators anchor procurement volumes for immunoglobulin and albumin production.
Germany
Outpatient therapeutic centers adopt membrane-based systems for chronic autoimmune maintenance protocols, pulling demand from traditional centrifugation deployments. CE marking under the EU MDR extends conformity assessment timelines by 12-18 months for manufacturers lacking predicate equivalence. The Baden-Württemberg medical device cluster houses engineering competencies for hollow-fiber filtration technology development.
Japan
PMDA marketing authorization requirements emphasize clinical evidence standards for therapeutic plasma exchange indications. METI industrial policy supports domestic production of blood purification devices through targeted procurement preferences. The Kansai region around Osaka hosts specialized clinics deploying compact membrane systems for neurological disorder protocols.
China
NMPA regulatory reforms accelerate review timelines for innovative apheresis devices with demonstrated clinical equivalence. The country's national health commission expands reimbursement coverage for autoimmune disorder treatments in tertiary hospitals. Yangtze River Delta medical device manufacturing clusters scale production of disposable tubing sets for regional blood center networks.
India
CDSCO medical device rules classify automated plasmapheresis equipment under higher-risk categories requiring expanded technical documentation. The PLI scheme for pharmaceuticals and medical devices incentivizes domestic manufacturing of blood collection consumables. Maharashtra's Mumbai-Pune corridor concentrates hospital-based therapeutic plasma exchange capacity for neurological and hematologic indications.
Plasmapheresis Market Key Industry Players
Player mix skews toward integrated dialysis-plasma platform specialists and membrane filtration technology developers. Market structure concentrates around three to five equipment vendors with established disposable ecosystems, while blood bag and filtration component suppliers populate a fragmented lower tier. Strategic archetypes include integrated platform providers, membrane technology specialists, and plasma-derived biologics fractionators with captive collection infrastructure. Dominant competitive moves encompass M&A for disposable kit manufacturing capacity and strategic partnerships with blood center networks for long-term supply agreements.
Among Germany-based integrated platform providers, Fresenius SE & Co. KGaA and B. Braun Melsungen occupy positions anchoring hospital procurement cycles through combined dialysis-apheresis service offerings. Japanese membrane technology specialists Asahi Kasei Medical exemplify the hollow-fiber filtration archetype gaining share in specialty clinic deployments. United States-based Haemonetics Corporation represents the donor center segment focus with software-integrated disposable ecosystems.
| Leading Market Players |
|---|
| Terumo BCT |
| Fresenius SE & Co. KGaA |
| Haemonetics Corporation |
| Baxter International |
| Asahi Kasei Medical |
| B. Braun Melsungen |
| Grifols |
| Octapharma |
| Kedrion Biopharma |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety day resin procurement lead times for polymer tubing components tether disposable kit economics to petrochemical feedstock volatility, concentrating pricing power with integrated manufacturers possessing captive resin supply agreements. Blood center operators and hospital procurement committees negotiate multi-year contracts indexed to medical-grade polymer spot markets, yet membrane cartridge suppliers retain margin leverage through hollow-fiber filtration patents.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate single-use kit procurement between blood center networks and disposable manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared kits with enhanced biocompatibility testing from basic CE-marked alternatives. Cost compression in standard-tier membrane cartridges is intensifying because Chinese manufacturers are scaling hollow-fiber production capacity. Blood center networks exhibit highest price sensitivity due to 60-70% per-procedure disposable concentration, while specialty clinics absorbing membrane system premiums show lowest sensitivity.
Supply Chain Analysis
Inventory buffers for membrane filtration cartridges typically hold 45-60 days of safety stock given single-source dependencies on Japanese hollow-fiber extrusion equipment. Manufacturing concentrates in Germany for integrated centrifugation platforms, Japan for precision membrane components, and the United States for software-integrated donor center systems. Raw material flows draw from Saudi petrochemical feedstocks for medical-grade polymers, German precision pumps for blood flow control, and Taiwanese semiconductor components for device automation. Single-source vulnerability in hollow-fiber membrane supply creates chokepoint exposure. Distribution runs through GPO contracts for hospital networks and direct manufacturer agreements for independent blood centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunities proliferate as membrane technology maturation splinters procurement authority between legacy centrifugation incumbents and compact system specialists serving outpatient autoimmune protocols.
For Market Incumbents: Compound installed base advantage through backward integration into membrane cartridge manufacturing, neutralizing the hollow-fiber supply chokepoint threatening centrifugation dominance. Lock hospital networks into 10-year service contracts bundling software updates with preventive maintenance, raising switching costs against membrane entrants. Prioritize CE marking transition completion before EU MDR enforcement tightens further. For New Entrants and Emerging Players: Anchor in German outpatient therapeutic centers where chronic autoimmune maintenance protocols favor compact membrane deployments over centrifuge throughput. Target the specialty clinic segment with simplified vascular access protocols that untether patients from dialysis chair infrastructure. Pursue direct-to-clinic sales bypassing GPO procurement committees through clinical outcome guarantees. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because disposable kit manufacturing scale determines margin capture in a market where per-procedure economics concentrate 60-70% in consumables. Target membrane filtration specialists with FDA 510(k) predicate pathways and established Japanese OEM relationships. Watch Medicare reimbursement coding revisions for outpatient plasma exchange as the inflection signal determining capital allocation between hospital-based and freestanding clinic formats.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Completion | EU MDR transition experience captures share from documentation-lagged competitors across European hospital networks. |
| Backward Integration into Membrane Manufacturing | In-house hollow-fiber production neutralizes single-source supply risk and secures margin control in cartridge economics. |
| Hospital System Partnership | Multi-site service contracts bundling software and hardware raise switching costs against membrane technology substitution. |
| Software Companion Development | Integrated donor management platforms differentiate disposable ecosystems in blood center procurement cycles. |
| Reimbursement Strategy | Medicare coding optimization for outpatient therapeutic plasma exchange determines clinic format investment viability. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR technical documentation filings, and hospital procurement contract disclosures preceded structured interviews with biomedical engineering directors, blood center operations managers, nephrologists, and GPO contracts specialists. Primary fieldwork validated secondary findings from CMS Medicare reimbursement data, SEC equipment manufacturer filings, and Japanese PMDA marketing authorization records. Bottom-up modeling of installed base and session volumes triangulated against top-down plasma fractionation demand forecasts.
Variance decomposition across technology substitution rates, reimbursement coding revisions, and polymer resin price indices shaped projection sensitivity. Segmentation dimensions encompassed product type, application indication, end-user facility category, and regional regulatory cluster. CAGRs derived from logistic diffusion curves for membrane technology penetration and linear extrapolation of autoimmune protocol expansion across the analysis window. Industry-specific inputs included plasma collection session frequency per donor, disposable kit utilization rates, and fractionator offtake contracts.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement and continued EU MDR enforcement without predicate device grandfathering; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Lupus Nephritis Treatment Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
US Dialysis Centers Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Dialysis Centers Market
Nephrology
Hemodialysis Services Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Global Diabetic Nephropathy Market