
 Dialysis Service Market | 2026-2036
Dialysis Service Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Service Market Insights
Asset-light clinic franchising is rewriting competitive entry dynamics in dialysis services, enabling regional operators to scale without capital-intensive facility builds. Fresenius Medical Care AG & Co. KGaA leverages its captive manufacturing of dialyzers and machines to sustain margin control across its clinic network. DaVita Inc. anchors its position through joint venture structures with nephrology practices, while Baxter International Inc. differentiates via peritoneal dialysis home therapy programs that reduce facility dependency.
Dialysis service encompasses the clinical delivery of extracorporeal blood purification and peritoneal fluid exchange for patients with end-stage renal disease, typically requiring three weekly sessions of four hours each using semipermeable membranes with ultrafiltration rates calibrated to patient volume status. The service exists to sustain metabolic homeostasis and fluid balance when native kidney function falls below fifteen percent of normal capacity. Hemodialysis delivered in dedicated dialysis centers commands the largest revenue pool due to reimbursement stability and nursing intensity, while home dialysis services represent the fastest-expanding category as portable cycler technology matures and payors push site-of-care migration. Chronic kidney disease application segments dominate patient volume, though acute kidney injury services generate premium pricing in hospital settings where continuous renal replacement therapy requires specialized ICU staffing.
The US FDA regulates dialyzer and machine safety through 510(k) premarket notification and quality system requirements, while the EMA's Medical Device Regulation imposes stricter clinical evidence standards for European market access, elevating compliance costs for smaller service operators. India's CDSCO alignment with international standards under its Medical Device Rules is opening import pathways for multinational dialysis equipment, directly shaping which technology platforms domestic clinics can adopt. Stakeholders must monitor reimbursement rate negotiations between Medicare Advantage plans and dialysis providers, as these contracts increasingly dictate whether home-based or in-center models achieve operational viability.
Market Dynamics
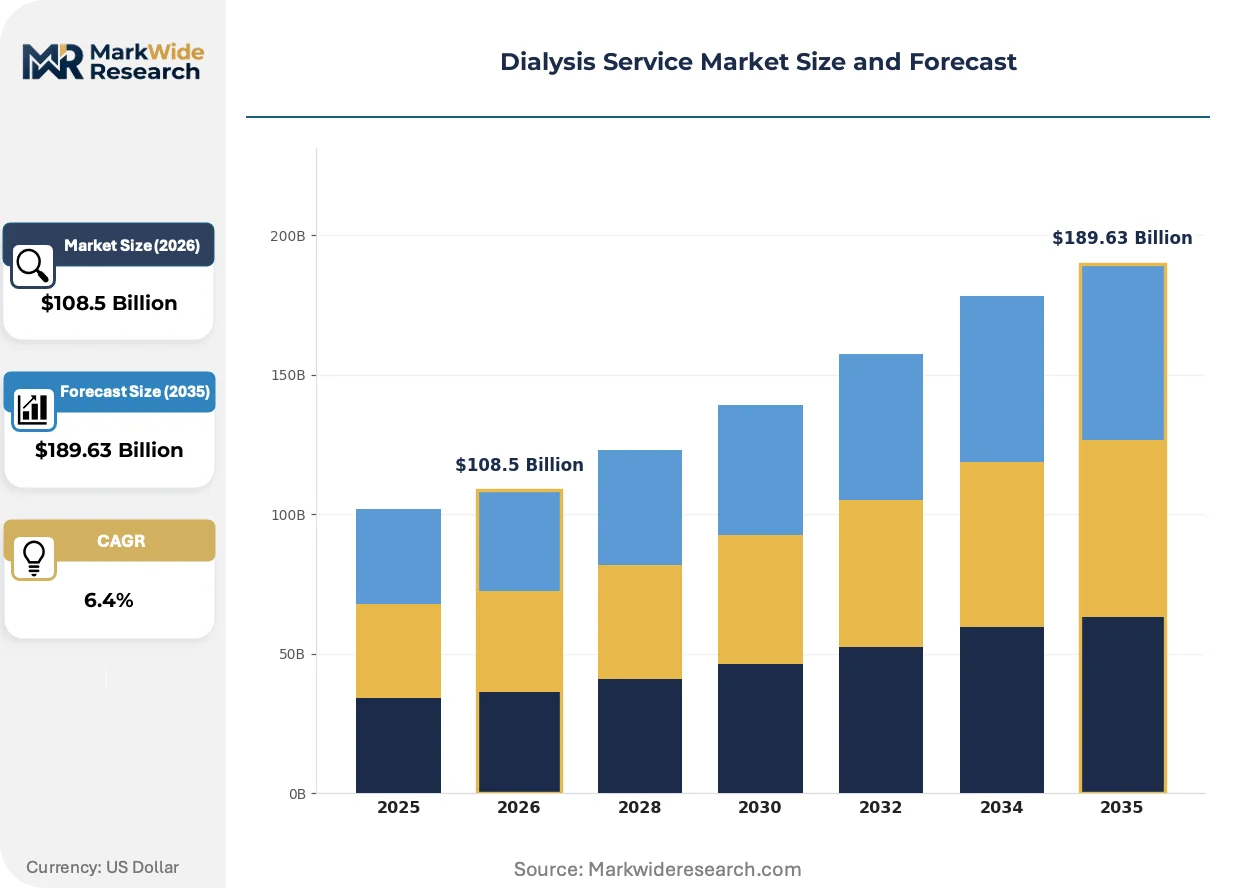
The dialysis service market is restructuring around site-of-care migration pressures, with payor reimbursement differentials between in-center and home-based delivery models forcing capital reallocation across clinic networks and equipment portfolios.
Growth Catalysts
- Medicare Advantage expansion:Private plan enrollment growth in the US is creating reimbursement premiums for home dialysis modalities that accelerate patient migration away from facility-based care.
- Portable cycler maturation:Next-generation peritoneal dialysis systems with automated fluid exchange and remote monitoring capabilities are reducing nursing dependency and enabling independent patient management.
- Brazilian public-private partnerships:Metropolitan hospital systems in São Paulo and Rio de Janeiro are leveraging concession models to extend clinic access into underserved districts without full public capital burden.
Market Restraints
- Concentrated dialyzer supply:Three manufacturers control over eighty percent of global hollow-fiber membrane production, creating vulnerability to polymer raw material disruptions.
- Water purification infrastructure:Hemodialysis requires pharmaceutical-grade water treatment systems that impose fixed costs exceeding two hundred thousand dollars per clinic station.
- EMA MDR compliance burden:Europe's Medical Device Regulation demands clinical evidence portfolios for dialysis machine recertification that smaller service operators cannot finance.
Strategic Opportunities
- Indian tier-two city penetration:CDSCO alignment with ISO standards is accelerating import clearance for multinational equipment, opening clinic deployment in Nagpur, Indore, and Coimbatore.
- Acute kidney injury service lines:Hospital networks are integrating continuous renal replacement therapy into ICU staffing models, capturing premium pricing from critical care episodes.
- Remote patient monitoring convergence:Integration of wearable volume status sensors with cloud-based clinical decision support is virtualizing care coordination between home patients and nephrology practices.
Industry Challenges
- Dialysis technician certification bottlenecks:State-level licensure requirements in the US create eighteen-month training pipelines that constrain clinic expansion velocity.
- Legacy EMR integration friction:Home dialysis platforms face interoperability failures with established hospital information systems, delaying remote prescription workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Service Market |
| Market Size in 2026 | $108.5 Billion |
| Market Size in 2035 | $189.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hemodialysis, Peritoneal Dialysis, Home Dialysis, Continuous Renal Replacement Therapy End User: Hospitals, Clinics, Home Care Settings, Dialysis Centers Technology: Conventional Dialysis Machines, Portable Dialysis Devices, Dialysis Monitors, Artificial Kidneys Application: Chronic Kidney Disease, Acute Kidney Injury, Diabetes Management, Hypertension Treatment |
| Companies Covered | DaVita Inc., Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., B. Braun Melsungen AG, Dialysis Clinic, Inc., Satellite Healthcare Inc., Medtronic plc, NIPRO Corporation, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Service Market Trends and Innovations
Telemedicine infrastructure and wearable biosensors are collapsing the distance between home-based patients and clinical oversight, redefining where dialysis care is delivered and who controls the patient relationship.
Artificial intelligence-enabled ultrafiltration control is virtualizing volume management in hemodialysis sessions. Nephrology practices in integrated delivery networks are piloting these systems to reduce intradialytic hypotension episodes. The technology is compressing nursing intervention requirements while extending treatment tolerance for hemodynamically unstable patients.
The US FDA's streamlined 510(k) pathway for substantially equivalent dialysis devices is accelerating technology turnover timelines. Manufacturers now face compressed product lifecycle pressures as predicate device clearances enable faster competitive entry. Home therapy equipment categories are experiencing the most rapid clearance velocity, reshaping R&D allocation across the device sector.
Payor steerage toward site-neutral reimbursement is fragmenting patient volume across delivery settings. Medicare Advantage plans in Florida and Texas are deploying care coordinators to redirect incident ESRD patients toward home modalities before facility habits form. This behavioral intervention is most visible in markets with high managed care penetration and established nephrology practice networks.
Dialysis Service Market Segmentation
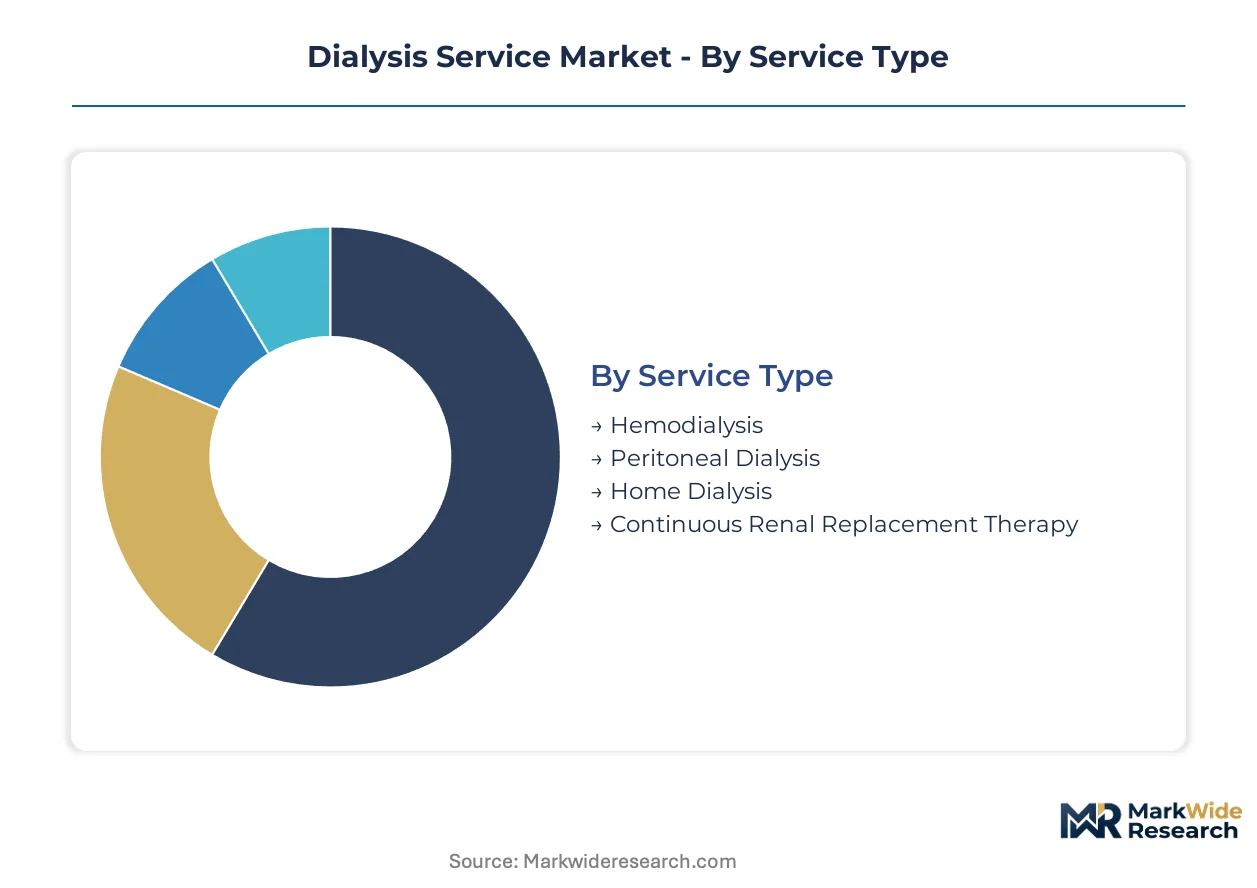
Segmentation in dialysis services determines capital deployment intensity and reimbursement capture. Service type dictates equipment amortization schedules, while end-user setting shapes staffing ratios and regulatory exposure.
Service Type:
After-sales service intensity varies sharply across modalities, with hemodialysis requiring continuous water system maintenance and peritoneal dialysis demanding patient training protocols.
- Hemodialysis:Blood purification through extracorporeal circuits with semipermeable membranes and ultrafiltration control. Demand concentrates in dedicated dialysis centers across São Paulo and Rio de Janeiro, where Brazilian public-private partnerships expand clinic access. Reimbursement stability supports nursing-intensive delivery models.
- Peritoneal Dialysis:Intraperitoneal fluid exchange using automated cycler systems for home-based management. Growth is accelerating in US Medicare Advantage networks, where care coordinators steer incident patients toward home modalities before facility habits form. Portable technology reduces facility dependency.
- Home Dialysis:Patient-managed therapy with remote clinical oversight and wearable volume monitoring. Adoption is climbing fastest where payor steerage toward site-neutral reimbursement fragments patient volume across settings.
- Continuous Renal Replacement Therapy:ICU-based slow continuous filtration for hemodynamically unstable patients. Hospital networks integrate this service line to capture premium pricing from critical care episodes.
By volume, hemodialysis leads. By growth pace, home dialysis is gaining share fastest.
End User:
Customer type determines procurement authority and contract duration, with hospital networks negotiating enterprise agreements while home care settings rely on individual patient enrollment.
- Hospitals:Integrated delivery networks with ICU-based acute services and nephrology department alignment. These facilities face EMA MDR compliance burdens for dialysis machine recertification that strain smaller operators.
- Clinics:Asset-light franchising models enabling regional operators to scale without capital-intensive facility builds. Metropolitan hospital systems in Brazil leverage concession models to extend access into underserved districts.
- Home Care Settings:Patient-managed environments with telemedicine infrastructure and cloud-based clinical decision support. Remote patient monitoring convergence virtualizes care coordination between patients and nephrology practices.
- Dialysis Centers:Dedicated facilities with pharmaceutical-grade water treatment systems exceeding two hundred thousand dollars per station. US state-level technician certification bottlenecks constrain expansion velocity.
Hospitals dominate revenue concentration. Home care settings show the steepest expansion trajectory.
Technology:
Equipment maturity shapes replacement cycles and predicate device pathways, with conventional platforms facing compressed lifecycles as FDA 510(k) clearances accelerate.
- Conventional Dialysis Machines:Stationary hemodialysis systems with fixed ultrafiltration rates and nursing-supervised operation. These platforms anchor in-center revenue pools due to reimbursement stability.
- Portable Dialysis Devices:Compact cycler systems enabling patient mobility and independent management. Next-generation units with automated fluid exchange are reducing nursing dependency.
- Dialysis Monitors:Real-time parameter tracking with AI-enabled ultrafiltration control. Nephrology practices pilot these systems to reduce intradialytic hypotension episodes.
- Artificial Kidneys:Experimental implantable or wearable renal replacement technologies. Development concentrates in research hospital networks with specialized bioengineering capabilities.
Conventional machines retain installed base dominance. Portable devices are climbing the fastest.
Application:
Clinical indication drives session frequency and pricing power, with chronic conditions generating recurring volume and acute episodes commanding premium reimbursement.
- Chronic Kidney Disease:Long-term management of end-stage renal failure requiring sustained metabolic homeostasis. Patient volume concentrates in established dialysis networks with nephrology practice joint ventures.
- Acute Kidney Injury:Sudden renal function loss requiring immediate intervention. Hospital ICU staffing models capture premium pricing from critical care episodes.
- Diabetes Management:Integrated care protocols addressing diabetic nephropathy progression. Multidisciplinary coordination shapes service line profitability.
- Hypertension Treatment:Volume status control through ultrafiltration in dialysis sessions. Blood pressure management protocols influence treatment tolerance.
Chronic kidney disease leads by patient volume. Acute kidney injury shows the strongest pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Advantage expansion in the United States is accelerating site-of-care migration toward home dialysis modalities, while Brazil's public-private partnership frameworks are reshaping metropolitan clinic access. Regulatory alignment in India and Europe's stricter device certification requirements are creating divergent compliance burdens across major markets.
United States
Medicare Advantage enrollment growth is creating reimbursement premiums for home dialysis that redirect patient volume away from facility-based care. The FDA's streamlined 510(k) pathway accelerates technology turnover for predicate dialysis devices. Care coordinators in Florida and Texas markets actively steer incident ESRD patients toward home modalities before facility habits form.
Brazil
Metropolitan hospital systems in São Paulo and Rio de Janeiro are leveraging concession models to extend clinic access into underserved districts without full public capital burden. ANVISA regulates dialyzer and machine safety through premarket notification pathways aligned with international standards. Public-private partnerships concentrate deployment in southeastern state networks where chronic kidney disease prevalence exceeds national averages.
Germany
The EMA's Medical Device Regulation imposes stricter clinical evidence standards for European market access, elevating compliance costs for smaller service operators. KBA and federal health ministry frameworks govern reimbursement negotiations between statutory insurers and dialysis providers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host integrated nephrology networks with captive manufacturing linkages.
India
CDSCO alignment with ISO standards under Medical Device Rules is accelerating import clearance for multinational dialysis equipment, opening clinic deployment in Nagpur, Indore, and Coimbatore. Tier-two city penetration is expanding as equipment import pathways simplify for regional operators. Metropolitan hospital networks in Maharashtra and Karnataka are anchoring joint venture structures with nephrology practices.
Japan
PMDA quality system requirements and METI industrial policy shape dialysis device approval timelines and reimbursement calibration. Aging demographics sustain patient volume growth in chronic kidney disease management. Kanto and Kansai regional networks concentrate hemodialysis center density with established nephrology practice affiliations.
Dialysis Service Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure consolidating around captive manufacturing and joint venture architectures. Three manufacturers control over eighty percent of global hollow-fiber membrane production, creating supply-side concentration that shapes competitive positioning. Strategic archetypes include vertically integrated device-and-service conglomerates, nephrology practice-aligned clinic operators, and home therapy equipment specialists. Dominant competitive moves encompass joint venture structures with nephrology practices and asset-light clinic franchising models that enable regional scale without capital-intensive facility builds.
Among Germany-based healthcare conglomerates, Fresenius Medical Care AG & Co. KGaA exemplifies the vertically integrated archetype through captive dialyzer and machine manufacturing that sustains margin control across clinic networks. DaVita Inc. anchors the United States market through nephrology practice joint ventures, while Baxter International Inc. occupies a position exemplifying home therapy specialization through peritoneal dialysis programs that reduce facility dependency. These three entities represent the dominant strategic configurations shaping competitive dynamics.
| Leading Market Players |
|---|
| DaVita Inc. |
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Dialysis Clinic, Inc. |
| Satellite Healthcare Inc. |
| Medtronic plc |
| NIPRO Corporation |
| Asahi Kasei Corporation |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's hollow-fiber membrane manufacturing clusters anchor global dialyzer supply, with production capacity utilization directly translating to downstream pricing leverage for clinic operators and equipment purchasers.
Pricing Analysis
Certification level (FDA 510(k)-cleared versus CE-marked under MDR versus ISO-standard imports) creates the primary spread across equipment procurement tiers. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service bundling and remote monitoring capability integration. Pricing pressure stems from Medicare Advantage reimbursement compression favoring site-neutral home modalities. Hospital networks show least price sensitivity due to captive patient volume, while independent clinic operators in tier-two Indian cities exhibit highest sensitivity to equipment cost.
Supply Chain Analysis
Tariff exposure between Germany and Brazil dominates supply chain risk calculations for South American clinic deployment. Hollow-fiber membrane production concentrates in Germany, Japan, and the United States, while automated cycler assembly draws from Mexico and Malaysia. Polymer raw material disruptions and concentrated dialyzer supply among three manufacturers create single-source vulnerability. Distribution runs through regional equipment distributors with nephrology practice joint venture linkages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is underway as telemedicine infrastructure and wearable biosensors collapse distance between home patients and clinical oversight, redefining patient relationship control.
For Market Incumbents: Entrench position through backward integration into dialyzer manufacturing and captive water purification system production. Fresenius Medical Care's margin control model demonstrates how in-house production of membranes insulates against polymer cost volatility. Expand certification investment under EMA MDR to forestall smaller operator recertification failures that would consolidate market share.
For New Entrants and Emerging Players: Nagpur, Indore, and Coimbatore represent underpenetrated tier-two Indian cities where CDSCO import simplification enables rapid clinic deployment. Asset-light franchising models bypass capital-intensive facility builds while leveraging public-private partnership structures. Target nephrology practice joint ventures as the most penetrable entry channel.
For Investors and Strategic Acquirers: Carve-out targets emerge from hospital network divestitures of non-core dialysis service lines as integrated delivery networks refocus on acute care. Long-term viability hinges on home therapy platform adoption curves and site-neutral reimbursement durability. Watch Medicare Advantage care coordinator deployment rates in Florida and Texas as the signal for modality shift velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Home Therapy Platform Integration | Portable cycler maturation with remote monitoring collapses nursing dependency and enables independent patient management. |
| EMA MDR Certification Pathway | Clinical evidence portfolios for dialysis machine recertification elevate compliance costs and filter smaller operators. |
| Hospital System Partnership | Joint venture structures with nephrology practices anchor patient volume and secure reimbursement stability. |
| Reimbursement Strategy | Medicare Advantage contract negotiation determines whether home-based or in-center models achieve operational viability. |
| Software Companion Development | AI-enabled ultrafiltration control systems reduce intradialytic hypotension and compress nursing intervention requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement data, and ANVISA regulatory notices. Interviews with dialysis clinic operations directors, nephrology practice administrators, biomedical equipment procurement managers, and GPO contracts specialists inform demand-side validation. Bottom-up patient volume modeling triangulates against top-down healthcare expenditure analysis.
Forecast inputs include service type segmentation across hemodialysis, peritoneal dialysis, and home modalities; end-user settings spanning hospitals, clinics, and home care; and technology tiers from conventional machines to portable devices. CAGRs derive from regression analysis of historical reimbursement rate changes, equipment replacement cycles, and site-of-care migration patterns. Modeling incorporates portable cycler adoption curves and public-private partnership expansion timelines.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by equipment manufacturers or disruptive home therapy entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Renal Anemia Treatment Market
Nephrology
US Dialysis Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Kidney Stone Extraction Balloon Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Renal Stent Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
US Dialysis Centers Market
Nephrology
Plasmapheresis Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Nephrosclerosis Treatment Market