
 Hemodialysis Services Market | 2026-2036
Hemodialysis Services Market Size, Share, and Industry Trends Forecast 2026-2036
Hemodialysis Services Market Intelligence
Home care patients is redrawing utilization patterns across the hemodialysis services landscape as ambulatory clinics and specialty care units cede procedure volume to residential settings. Fresenius Medical Care AG & Co. KGaA leverages its integrated device-to-clinic model to control treatment workflows end-to-end. DaVita Healthcare Partners, Inc. anchors its position through dense outpatient networks in metropolitan corridors. Baxter International, Inc. specializes in home dialysis technology platforms that reduce facility dependency.
Hemodialysis services encompass the clinical delivery, equipment provision, and patient management of extracorporeal blood purification using semipermeable membranes with typical ultrafiltration rates of 200-800 mL/hour and dialysate flow of 500-800 mL/minute, primarily serving end-stage renal disease patients requiring thrice-weekly solute and fluid removal. In-center hemodialysis still occupies the dominant share of procedure volume and reimbursement dollars, though home hemodialysis segments are expanding fastest as vascular access durability and remote monitoring improve. Telehealth integration within the delivery model dimension is reshaping labor economics by reducing in-person nursing ratios for stable patients.
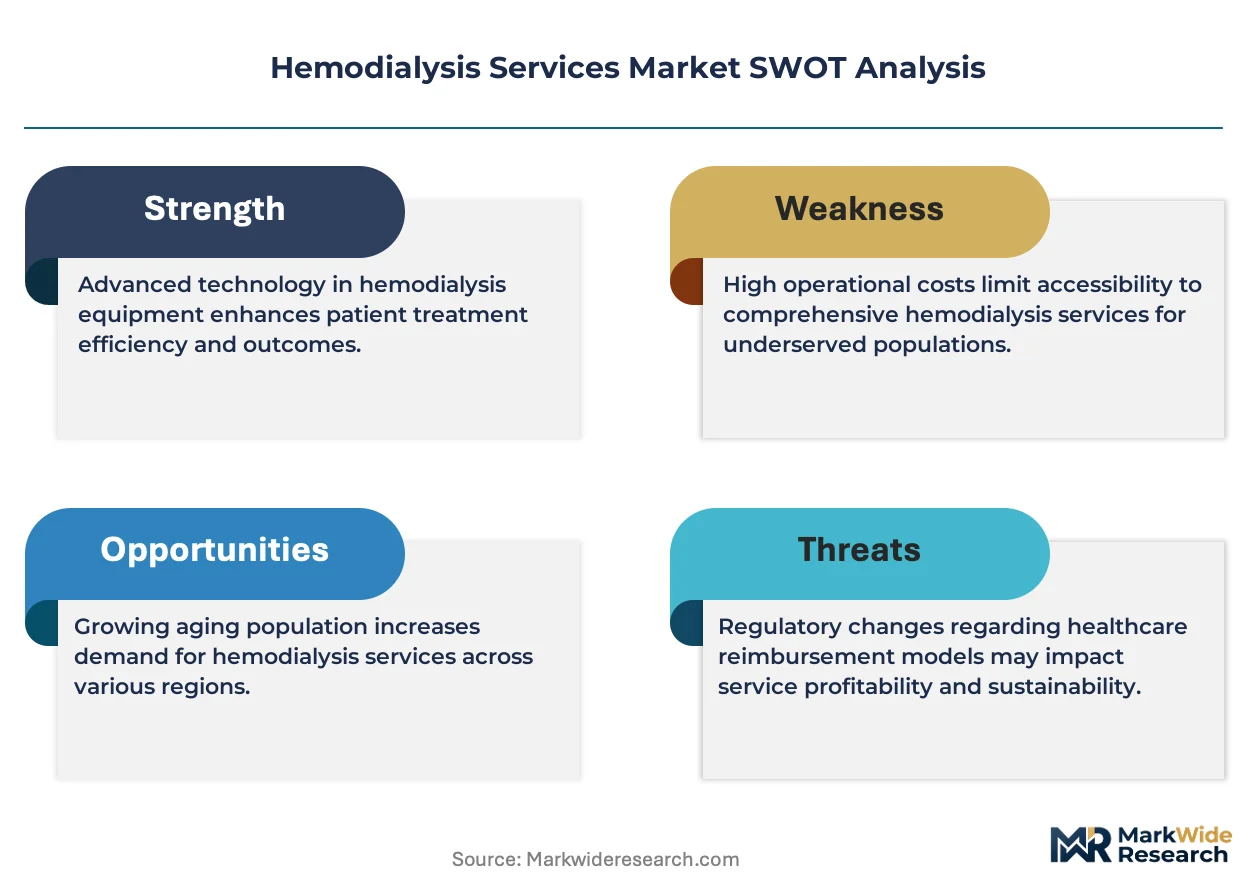
FDA oversight of dialyzer and dialysis machine safety standards, alongside CMS reimbursement rulemaking for the ESRD Prospective Payment System, structures market access and capital deployment timelines for service operators. Japan's PMDA and Germany's national reimbursement authority enforce device quality and tariff benchmarks that filter market entrants. Stakeholders must weigh home therapy infrastructure investments against regulatory uncertainty in bundled payment recalibration.
Market Dynamics
Medicare's ESRD bundled payment system is compressing reimbursement rates while simultaneously tightening clinical quality thresholds, forcing service operators to recalibrate capital deployment toward lower-cost delivery modalities without sacrificing outcome metrics.
Growth Catalysts
- Telehealth Integration:Remote patient monitoring platforms reduce in-person nursing ratios for stable home hemodialysis patients. CMS reimbursement codes now cover virtual check-ins between thrice-weekly treatments.
- Vascular Access Durability:Bioengineered arteriovenous fistula maturation protocols extend functional access lifespan from 3-4 years toward 5-7 years. This technical advance reduces hospitalization frequency for access-related complications.
- Japan's PMDA Fast-Track:Accelerated approval pathways for home dialysis devices compress regulatory timelines from 24 months toward 14 months. Japanese nephrology networks expand home therapy infrastructure in response.
Market Restraints
- Concentrated Dialyzer Supply:Three manufacturers control over 80% of global hollow-fiber membrane production. Any disruption at German or Japanese polymer synthesis facilities propagates immediately through service operator supply chains.
- Water Purification Infrastructure:Home hemodialysis requires residential reverse osmosis systems producing 3-5 liters of ultrapure water per treatment. Municipal water quality variability in rural United States counties limits expansion feasibility.
- Technical Workforce Scarcity:Certified dialysis technicians command wage premiums of 15-20% above comparable allied health roles. Training program throughput has not kept pace with center expansion in metropolitan corridors.
Strategic Opportunities
- Underpenetrated Rural United States:Travel distances exceeding 50 miles to nearest dialysis center affect approximately 12% of ESRD patients in non-metropolitan counties. Mobile dialysis units and telehealth-supported home therapy address this geographic gap.
- Peritoneal Dialysis Convergence:Automated peritoneal dialysis cycler technology now achieves solute clearance rates approaching conventional hemodialysis. Integrated service providers can offer modality-neutral patient choice without facility switching.
- EU Green Deal Alignment:Dialysis center energy consumption averages 400-600 kWh per patient per week. Carbon footprint reduction mandates create competitive differentiation for operators deploying heat-recovery dialysate systems and renewable power purchase agreements.
Industry Challenges
- Biomedical Engineering Talent Pipeline:Dialysis machine maintenance requires hybrid competencies in fluid dynamics, electronics, and regulatory documentation. Vocational programs produce fewer than 400 certified technicians annually against replacement demand.
- Legacy EHR Integration:Proprietary data formats from incumbent device manufacturers impede seamless flow of treatment parameters into hospital enterprise systems. Interface development consumes 8-14 months per institutional deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemodialysis Services Market |
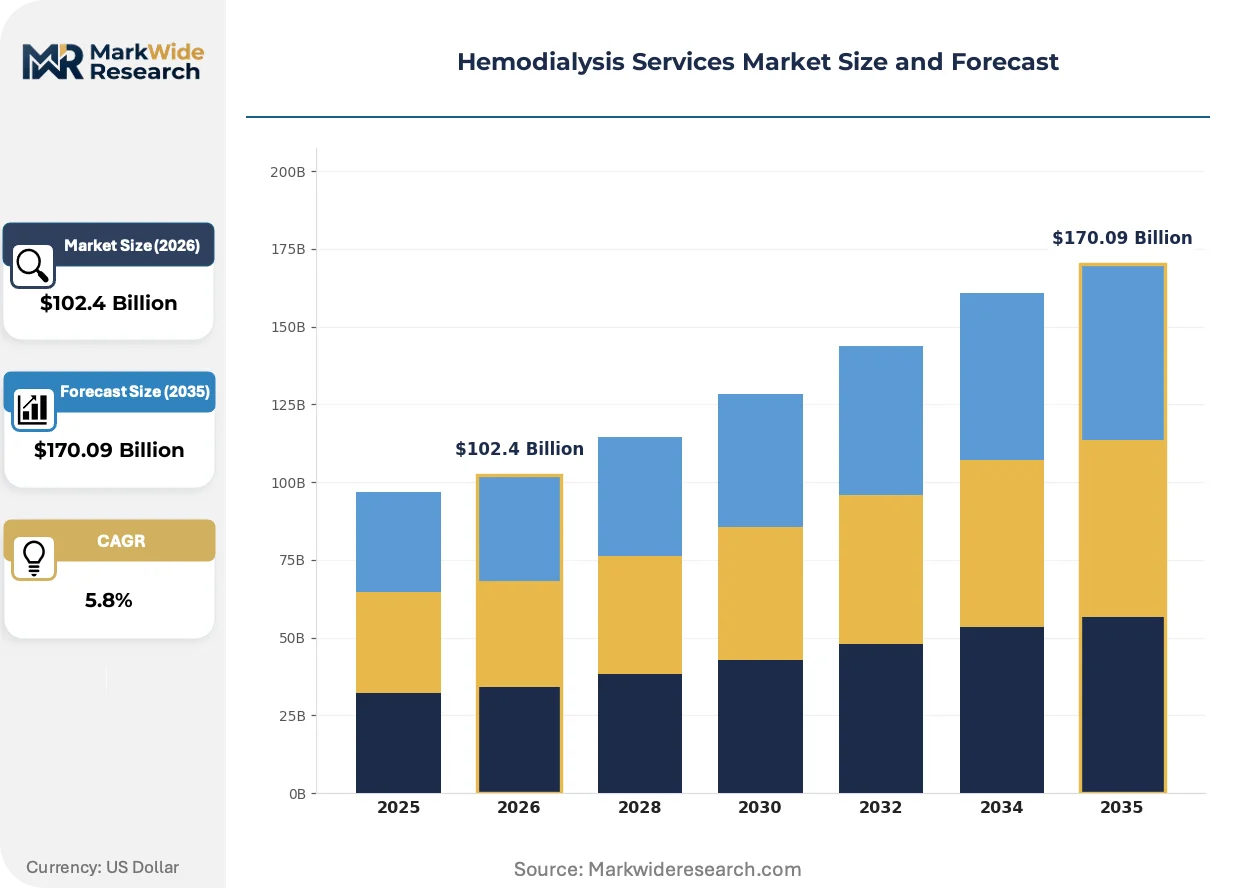
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $170.09 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: In-center Hemodialysis, Home Hemodialysis, Nocturnal Hemodialysis, Short Daily Hemodialysis, Online Hemodiafiltration End User: Dialysis Centers, Ambulatory Clinics, Home Care Patients, Specialty Care Units, Rehabilitation Centers Delivery Model: Outpatient Services, Mobile Dialysis Units, Telehealth Integration, Assisted Dialysis, Community Health Programs Payment Method: Private Insurance, Government Reimbursement, Out-of-pocket, Managed Care Plans, Charitable Funding |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, DaVita Healthcare Partners, Inc., Dialysis Clinic, Inc., US Renal Care, Inc., Satellite Healthcare, Inc., Baxter International, Inc., B. Braun Melsungen AG, Diaverum, Nikkiso Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemodialysis Services Market Strategic Shifts & Innovations
Digital health infrastructure and portable device miniaturization are collapsing the traditional boundary between clinical and residential treatment settings. Service operators now compete on patient convenience metrics rather than facility amenities alone.
Portable hemodialysis systems incorporating sorbent-based dialysate regeneration are bifurcating the market between conventional center-based operators and technology-enabled home therapy platforms. These devices reduce dialysate consumption from 120 liters per treatment toward 6 liters, enabling true mobility. Early adopters in the United States and Germany include employed patients aged 35-55 seeking work-schedule flexibility. The technology is bifurcating reimbursement negotiations, with payers now separating acute dialysis rates from chronic home therapy tariffs.
FDA's evolving guidance on artificial intelligence-enabled dialysis prescription algorithms is reshaping clinical decision support liability frameworks. Machine learning models predicting intradialytic hypotension episodes must now demonstrate prospective validation across diverse patient populations. Home hemodialysis segments face heightened scrutiny as algorithmic dosing recommendations replace traditional physician oversight. Operators are responding by establishing dedicated AI governance committees and external validation partnerships with academic medical centers.
Patient self-management education programs now precede modality selection rather than following it. Traditional referral patterns from nephrologist to in-center facility are yielding to shared decision-making protocols where patients evaluate home versus center options using standardized risk-benefit tools. This behavioral shift is most visible in integrated health systems like Kaiser Permanente and the Veterans Health Administration, where bundled payment accountability aligns provider incentives with patient preference fulfillment.
Hemodialysis Services Market Segmentation
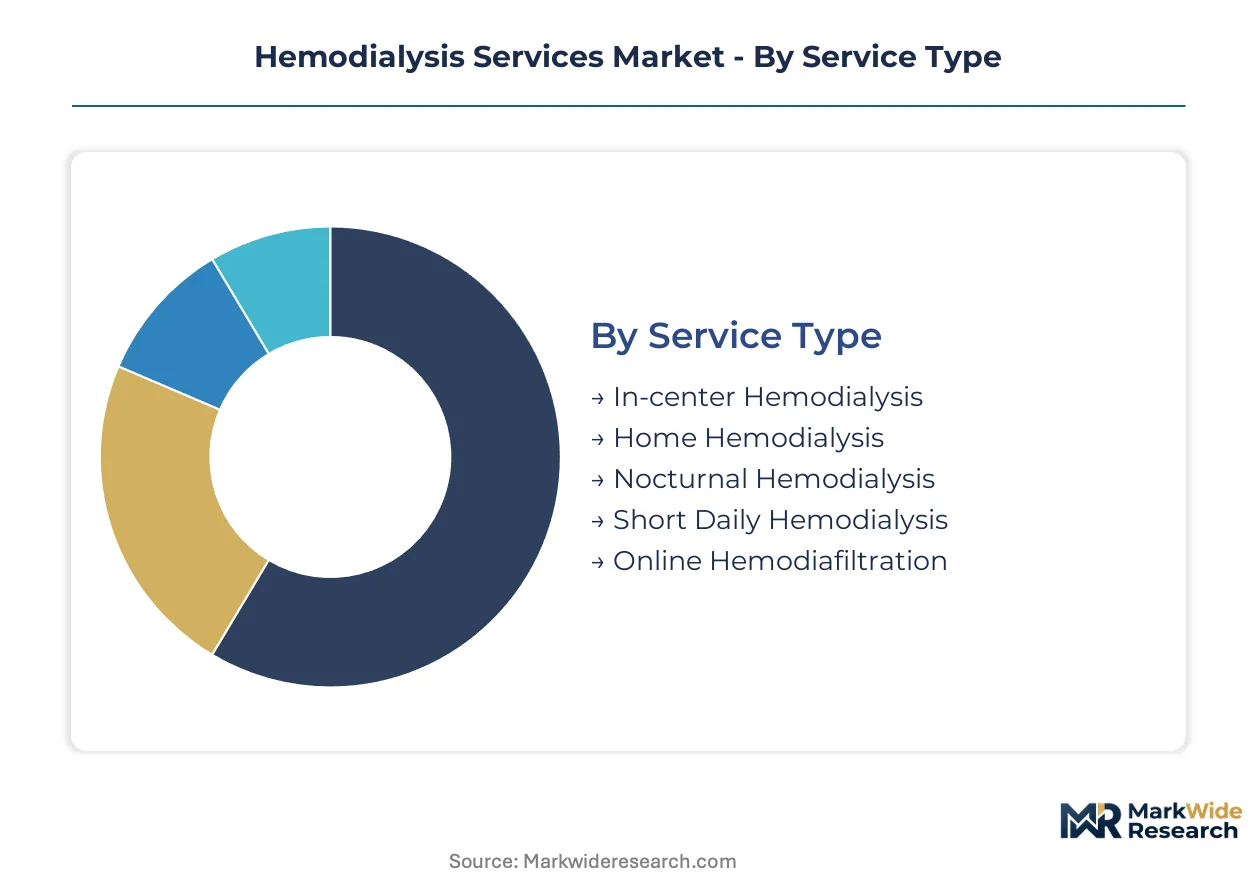
Service modality selection determines capital intensity, labor ratios, and reimbursement exposure for operators across the hemodialysis value chain. Segment boundaries are blurring as portable technology and remote monitoring enable care migration from facility-based to residential settings.
Service Type:
Home-based modalities face accelerating substitution pressure from peritoneal dialysis and emerging wearable artificial kidney platforms, forcing incumbents to defend procedure volume through convenience differentiation.
- In-center Hemodialysis:Conventional thrice-weekly sessions lasting 3-4 hours utilize fixed-station machines with dialysate flow rates of 500-800 mL/minute. United States metropolitan corridors concentrate demand where Fresenius and DaVita operate dense clinic networks under Medicare's bundled ESRD payment system.
- Home Hemodialysis:Patients self-administer treatments using compact systems with remote clinician oversight via cellular-connected monitoring platforms. Germany and Japan lead adoption as PMDA fast-track approvals and statutory reimbursement parity reduce facility dependency.
- Nocturnal Hemodialysis:Extended 6-8 hour sessions during sleep achieve gentler ultrafiltration and improved phosphate clearance. Sleep-disordered breathing comorbidities in obese ESRD populations constrain candidate eligibility.
- Short Daily Hemodialysis:Brief 2-hour sessions performed 5-6 times weekly improve cardiovascular stability but multiply vascular access puncture frequency. Access site preservation protocols limit commercial penetration.
- Online Hemodiafiltration:Convective clearance enhancement requires ultrapure dialysate generation and specialized disposable sets. European nephrology societies promote adoption through outcome-based quality metrics.
In-center hemodialysis anchors the volume base while home hemodialysis gains share at the steepest rate.
End User:
Cost tier stratification separates high-acuity institutional settings from lower-touch residential and ambulatory environments, with reimbursement spreads of 40-60% between inpatient and home-based tariffs.
- Dialysis Centers:Dedicated facilities operate 12-24 stations with on-site water treatment, biomedical engineering support, and centralized supply chains. United States freestanding centers capture the majority of Medicare ESRD spending through consolidated operator networks.
- Home Care Patients:Residential therapy eliminates travel burden and enables schedule flexibility for employed patients. Vascular access durability improvements and telehealth reimbursement codes accelerate migration from facility-based care.
- Ambulatory Clinics:Hospital outpatient departments integrate dialysis with transplant evaluation and vascular surgery services. Academic medical centers use these settings for training and clinical trial recruitment.
- Specialty Care Units:Intensive care and cardiac surgery units provide acute dialysis for hemodynamically unstable patients. Continuous renal replacement therapy equipment overlaps with chronic service supply chains.
- Rehabilitation Centers:Skilled nursing facilities manage post-acute ESRD patients transitioning between hospital and community settings. Medicare's 3-day prior hospitalization rule constrains admission eligibility.
Dialysis centers dominate revenue concentration while home care patients expand most quickly as modality-neutral payment models mature.
Delivery Model:
Volume distribution reflects geographic access gaps, with mobile and telehealth platforms capturing demand from patients residing beyond 50 miles of fixed facilities.
- Outpatient Services:Scheduled clinic visits follow standardized protocols with nursing ratios of 1:12-15 patients. United States bundled payment incentives reward throughput optimization and complication reduction.
- Mobile Dialysis Units:Self-contained vehicles with onboard water treatment serve rural counties and disaster response scenarios. Regulatory licensing complexity limits fleet expansion to large integrated operators.
- Telehealth Integration:Remote monitoring of vital signs, access site surveillance, and prescription adjustments reduces in-person visit frequency. CMS reimbursement codes now cover virtual check-ins between treatments.
- Assisted Dialysis:Caregiver-supported home therapy enables elderly and cognitively impaired patients to avoid facility transfer. Training burden and liability exposure constrain program scale.
- Community Health Programs:Federally qualified health centers and VA facilities provide culturally tailored services for underserved populations. Grant funding supplements reimbursement shortfalls.
Outpatient services maintain volume dominance while telehealth integration climbs the fastest as labor cost pressures intensify.
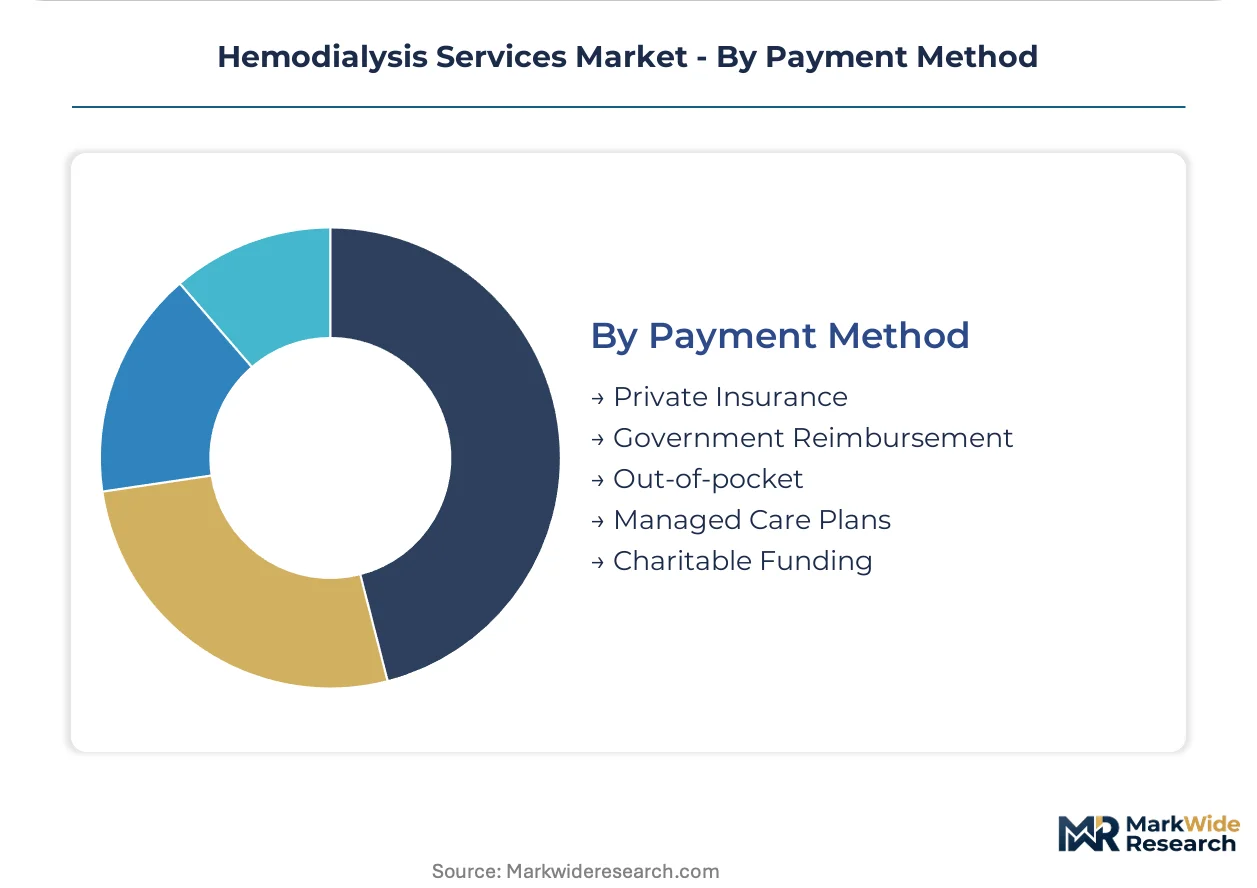
Payment Method:
Margin structure varies sharply across payer mix, with government reimbursement compressing yields while private insurance and supplemental coverage subsidize cross-subsidization strategies.
- Government Reimbursement:Medicare's ESRD Prospective Payment System bundles dialysis, drugs, and laboratory services into a single case-mix-adjusted rate. Annual rulemaking updates create pricing uncertainty for multi-year capital commitments.
- Private Insurance:Employer-sponsored plans and individual market coverage pay 200-400% of Medicare rates during the 30-month coordination period. United States commercial membership concentration in metropolitan markets shapes site selection.
- Managed Care Plans:Medicare Advantage and integrated delivery systems assume full financial risk for ESRD patients. Kaiser Permanente and similar organizations promote home modality selection to reduce total cost of care.
- Out-of-pocket:Uninsured and underinsured patients face treatment costs exceeding $50,000 annually without charitable support. Safety-net programs and manufacturer patient assistance fill coverage gaps.
- Charitable Funding:Nonprofit organizations and dialysis industry foundations subsidize care for undocumented immigrants and impoverished populations. Donor dependency creates operational volatility.
Government reimbursement anchors the volume base while managed care plans gain share at the steepest rate as risk-bearing enrollment expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply of dialyzer membranes and dialysis machines clusters in Germany and Japan, with polymer synthesis facilities in these countries feeding service operators worldwide. This geographic concentration shapes regulatory timelines and reimbursement negotiations across major demand markets.
United States
Medicare's ESRD Prospective Payment System bundles dialysis, drugs, and laboratory services into case-mix-adjusted rates that structure operator economics. The FDA oversees dialyzer safety standards and dialysis machine clearances, with 510(k) pathways dominating device approvals. DaVita Healthcare Partners and Fresenius Medical Care operate dense clinic networks in metropolitan corridors, consolidating capacity to capture chronic kidney disease demand.
Germany
Statutory reimbursement parity for home hemodialysis reduces facility dependency and accelerates residential therapy adoption. The national reimbursement authority enforces tariff benchmarks and device quality standards that filter market entrants. Bavaria and North Rhine-Westphalia host concentrated dialysis center networks where operators deploy heat-recovery dialysate systems to align with EU Green Deal carbon reduction mandates.
Japan
PMDA fast-track approval pathways for home dialysis devices compress regulatory timelines from 24 months toward 14 months. METI promotes medical device innovation through targeted funding programs. The Kanto region around Tokyo anchors nephrology network expansion, with academic medical centers validating remote monitoring platforms for stable home patients.
United Kingdom
NHS England's bundled payment models for renal services incentivize home modality selection to reduce total cost of care. The MHRA regulates dialyzer safety under post-Brexit frameworks that maintain alignment with EU MDR standards. London and the Southeast concentrate private dialysis capacity, while Midlands networks trial telehealth-supported home therapy for rural access gaps.
China
NMPA medical device registration requirements structure market access timelines for dialysis equipment imports. Provincial reimbursement catalogs in Jiangsu and Guangdong increasingly cover home hemodialysis consumables. The Yangtze River Delta hosts manufacturing clusters for dialyzer components, with domestic suppliers expanding hollow-fiber membrane production capacity.
Hemodialysis Services Market Key Industry Players
Concentration sits with integrated device-to-service operators and specialized dialysis clinic chains that control treatment workflows end-to-end. The market exhibits tiered structure with global equipment manufacturers, regional service consolidators, and technology-focused home therapy platforms occupying distinct competitive positions. Two strategic archetypes dominate: vertically integrated suppliers capturing margin across device and service segments, and pure-play operators optimizing facility throughput under bundled payment constraints. M&A activity concentrates clinic networks in metropolitan corridors, while technology licensing agreements accelerate home dialysis platform deployment.
Within the integrated supplier tier, Fresenius Medical Care AG & Co. KGaA and Baxter International, Inc. exemplify device-to-clinic control models. Among specialized service operators, DaVita Healthcare Partners, Inc. and US Renal Care, Inc. represent dense outpatient network strategies. These three named entities anchor distinct competitive positions without exhaustive market coverage claims.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| DaVita Healthcare Partners, Inc. |
| Dialysis Clinic, Inc. |
| US Renal Care, Inc. |
| Satellite Healthcare, Inc. |
| Baxter International, Inc. |
| B. Braun Melsungen AG |
| Diaverum |
| Nikkiso Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Scale economies in hollow-fiber membrane production concentrate dialyzer manufacturing among three German and Japanese suppliers, compressing price floors for service operators while amplifying procurement leverage for vertically integrated clinic chains. This supply-side density shapes Medicare ESRD bundled payment negotiations, as Fresenius and DaVita exploit captive sourcing to defend margins against independent dialysis centers.
Pricing Analysis
Volume-discount tiering structures dominate dialyzer and dialysis machine procurement, with pricing stratifying across premium FDA-cleared devices, standard CE-marked equipment, and economy-grade consumables for emerging markets. Price differentiation rests on certification tier and after-sales service bundling, with German and Japanese manufacturers commanding brand premiums. Cost compression in the standard tier is intensifying because Medicare's annual ESRD Prospective Payment System recalibration squeezes operator budgets. Independent dialysis centers exhibit the highest price sensitivity, while integrated device-to-service operators leverage backward integration to neutralize procurement volatility.
Supply Chain Analysis
Polymer synthesis chokepoints in Baden-Württemberg and Osaka prefectures tether global dialyzer supply to specialized polyurethane and polysulfone resin production. Hollow-fiber membrane manufacturing draws from German precision extrusion and Japanese medical-grade polymer expertise, with dialysate concentrate formulation anchored in North American and European chemical processing. Single-source vulnerability concentrates in Japanese PMDA-regulated component facilities, where any disruption propagates through Fresenius and Baxter assembly lines. Distribution runs through consolidated operator procurement consortia and GPO contracts rather than open-market spot purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity sits with modality-neutral service platforms, as patient self-management education and telehealth reimbursement codes splinter referral patterns away from nephrologist-directed in-center default.
For Market Incumbents: Secure vascular access durability IP and remote monitoring platform certifications to defend against portable hemodialysis device entrants. Consolidate independent clinic networks in United States metropolitan corridors to capture Medicare Advantage risk-bearing enrollment. Prioritize heat-recovery dialysate system deployment to meet EU Green Deal carbon benchmarks in German operations. For New Entrants and Emerging Players: Differentiate on sorbent-based dialysate regeneration technology to collapse water infrastructure requirements for rural United States expansion. Target telehealth-integrated home hemodialysis in Japanese Kanto region, where PMDA fast-track approvals compress regulatory timelines. Pursue hospital system partnership models that bundle device placement with clinician training and remote oversight subscriptions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated device-to-service operators with FDA-cleared AI-enabled prescription algorithms and established CMS reimbursement codes. Long-term viability over the projection horizon rests on backward integration into hollow-fiber membrane production or exclusive licensing with German and Japanese polymer suppliers. Watch for inflection in Medicare Advantage ESRD risk-bearing penetration rates as signal for home modality substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI-Enabled Dialysis Prescription | Machine learning algorithms predicting intradialytic hypotension must demonstrate prospective validation across diverse patient populations. |
| CE Marking Pathway for Portable Hemodialysis Systems | Sorbent-based dialysate regeneration technology enables EU market entry with reduced water infrastructure requirements. |
| Hospital System Partnership | Academic medical centers validate remote monitoring platforms while training next-generation nephrology workforce. |
| Software Companion Development | Cellular-connected patient apps reduce in-person nursing ratios and capture CMS virtual check-in reimbursement codes. |
| Reimbursement Strategy Alignment | Medicare Advantage risk-bearing contracts reward home modality selection with total cost of care savings. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare cost reports, and PMDA approval databases to validate market sizing assumptions. Interviews with dialysis center operations directors, biomedical engineering managers, nephrology practice administrators, and GPO contracts specialists informed demand-side dynamics. Secondary validation drew from hospital procurement databases, ESRD facility survey data, and SEC 10-K disclosures from listed operators. Bottom-up patient volume estimates triangulated against top-down reimbursement expenditure analysis.
Segmentation dimensions modeled span service modality, end-user setting, delivery model, and payment method, with geographic regulatory clusters capturing United States, German, Japanese, and United Kingdom tariff frameworks. CAGRs were derived from procedure volume trajectories and case-mix-adjusted reimbursement rate evolution across the analysis window. Forecast inputs incorporated vascular access durability improvements, telehealth code expansion, and portable device regulatory clearance timelines.
The analysis sits within stated boundaries; outcomes outside Medicare ESRD bundled payment stability, PMDA fast-track continuity, or hollow-fiber membrane supply concentration would require recalibration. Practitioners should keep alternative scenarios live as CMS annual rulemaking, EU MDR enforcement, and AI-enabled device liability frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
US Dialysis Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Kidney Transplant Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Renal Artery Embolization Market
Nephrology
Blood Dialyzer Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Dialysis Centers Market