
 Renal Stent Market | 2026-2036
Renal Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Stent Market Insights
Hospital procurement consolidation is pivoting vendor selection criteria toward total cost-of-ownership metrics rather than unit pricing alone. Boston Scientific Corporation leverages its integrated interventional urology portfolio to secure multi-year supply agreements with large health systems. B. Braun Melsungen AG anchors its position through dedicated renal access product lines and direct hospital service infrastructure. Cook Medical competes by sustaining manufacturing flexibility across stainless steel and nitinol stent platforms for customized clinician preferences.
A renal stent is a tubular metallic or polymeric implant, typically manufactured from nitinol or cobalt-chromium alloys with laser-cut mesh geometries, designed to maintain patency in the ureter or renal pelvis and restore urine flow past obstructions caused by stones, strictures, or extrinsic compression. Drug-eluting stent variants incorporate paclitaxel or sirolimus coatings to inhibit tissue hyperplasia and extend functional dwell time before replacement. Balloon-expandable stents dominate acute deployment precision in interventional radiology suites, while self-expanding configurations lead in outpatient settings where minimally invasive percutaneous delivery reduces procedural complexity. Covered stents command premium positioning for malignant obstruction cases where tumor ingrowth risks compromise bare-metal alternatives.
The FDA's Class II device classification and 510(k) clearance pathway govern US market entry, while the EU Medical Device Regulation's enhanced clinical evidence requirements are reshaping conformity assessment burdens for European submissions. ISO 25539-2 standards for vascular stent durability testing provide foundational mechanical performance benchmarks that renal stent manufacturers adapt for ureteral biomechanical conditions. Stakeholders must monitor evolving reimbursement coding for outpatient percutaneous nephrostomy conversions, as ambulatory surgical center payment structures will determine site-of-care migration and corresponding product form factor requirements.
Market Dynamics
Hospital procurement consolidation across multi-site health systems is compressing vendor margins and pivoting selection criteria toward total cost-of-ownership frameworks rather than unit pricing alone.
Growth Catalysts
- Integrated Delivery Network Expansion:Large health systems in the United States are consolidating purchasing authority, creating volume commitments that favor suppliers with broad interventional portfolios.
- EU Medical Device Regulation Phase-In:MDR's enhanced clinical evidence requirements are raising barriers for marginal competitors and clearing shelf space for established manufacturers with robust quality systems.
- Drug-Eluting Coating Maturation:Paclitaxel and sirolimus formulations are extending functional dwell times and reducing replacement frequency in malignant obstruction cases.
Market Restraints
- Nitinol Price Volatility:Nickel-titanium alloy supply concentrates among a limited supplier base, exposing manufacturers to raw material cost swings.
- FDA 510(k) Timeline Extension:Strengthened premarket notification requirements for Class II devices are extending product development cycles and deferring revenue recognition.
- Balloon Catheter Substitution:Temporary drainage procedures using percutaneous nephrostomy tubes compete for cases where permanent stenting remains clinically discretionary.
Strategic Opportunities
- Ambulatory Surgical Center Migration:Outpatient percutaneous nephrostomy conversions are shifting site-of-care economics and creating demand for simplified delivery systems.
- Covered Stent Premium Positioning:Malignant obstruction applications command pricing power where tumor ingrowth risks compromise bare-metal alternatives.
- ISO 25539-2 Adaptation:Vascular stent durability testing standards provide mechanical benchmarks that renal stent manufacturers can leverage for differentiated regulatory submissions.
Industry Challenges
- Interventional Radiology Training Pipeline:Specialized skills for percutaneous renal access procedures face supply constraints as fellowship programs scale slowly.
- Reimbursement Coding Lag:Ambulatory surgical center payment structures for outpatient conversions remain inconsistently defined across Medicare administrative contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Stent Market |
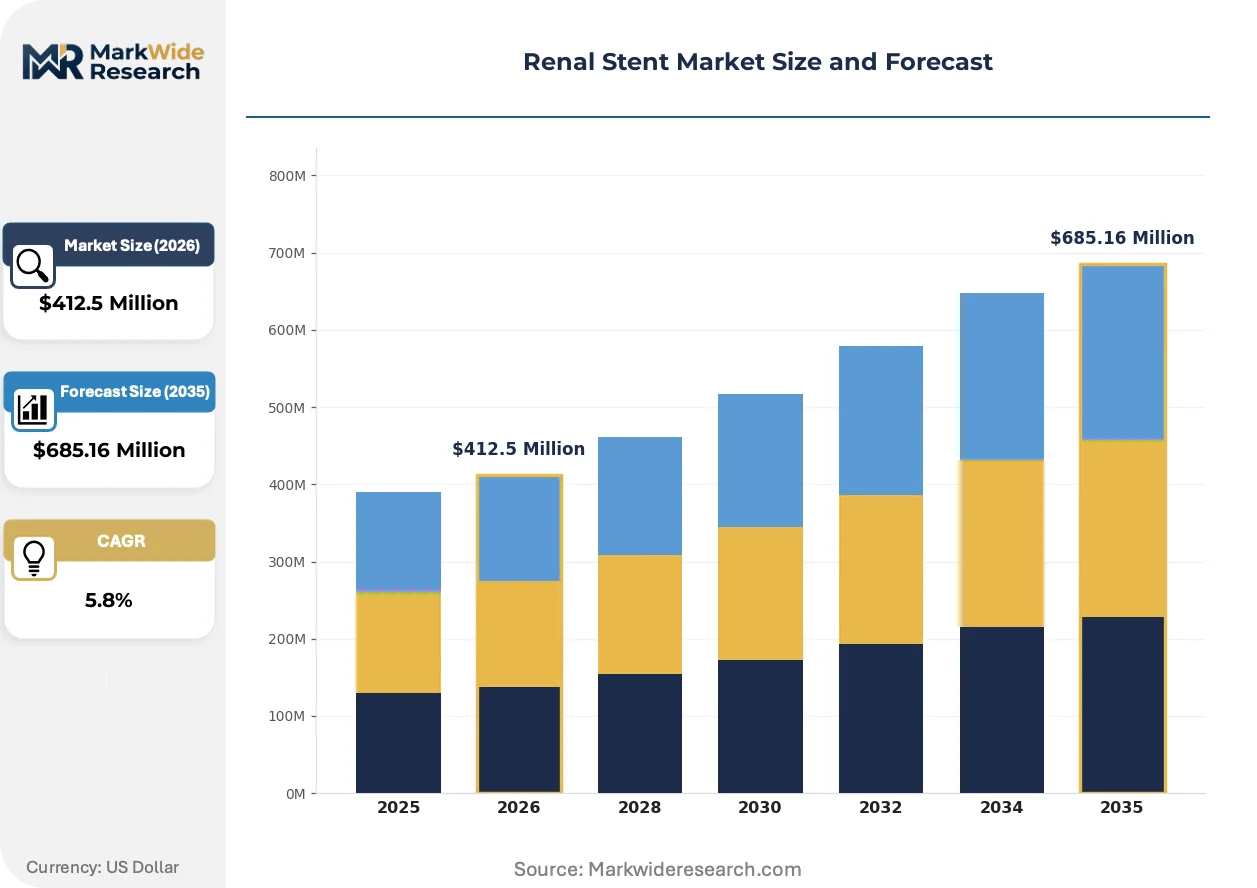
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Expanding Stents, Balloon-Expandable Stents, Covered Stents, Drug-Eluting Stents Delivery Mode: Endoscopic, Percutaneous, Laparoscopic, Open Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Ureteral Obstruction, Renal Calculi, Renal Transplant, Nephrolithiasis |
| Companies Covered | Boston Scientific Corporation, B. Braun Melsungen AG, Cook Medical, Opti-Med, Blue Neem Medical Devices Pvt Ltd, Bio-enterprise, Palex Medical, BD, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Stent Market Trends and Innovations
Three interconnected shifts are restructuring competitive positioning: automation of manufacturing precision, regulatory evidence burdens favoring scaled players, and procurement consolidation demanding integrated service capabilities.
Laser-cut mesh geometries manufactured from cobalt-chromium alloys are automating stent production consistency and reducing lot-to-lot variability that previously required manual inspection. Interventional radiology suites at academic medical centers are adopting these platforms fastest, driven by procedural volume and quality metric transparency. The technology is automating yield improvements that compress per-unit manufacturing costs and defend margin structures against procurement pressure.
The FDA's strengthened 510(k) clearance pathway for Class II devices is extending premarket timelines and raising documentation burdens for renal stent submissions. Manufacturers with captive clinical affairs capabilities and established predicate device libraries capture disproportionate clearance velocity. Smaller competitors without historical 510(k) predicates face exclusion from the United States market or forced partnership structures.
Hospital supply chain departments are unbundling after-sales service from device pricing and evaluating vendors on technical training, inventory management, and case coverage responsiveness. Integrated delivery networks in the United States are consolidating these requirements into multi-year agreements with penalty clauses for service failures. This behavior shift concentrates purchasing leverage among vendors with dedicated field service infrastructure and direct hospital relationships.
Renal Stent Market Segmentation
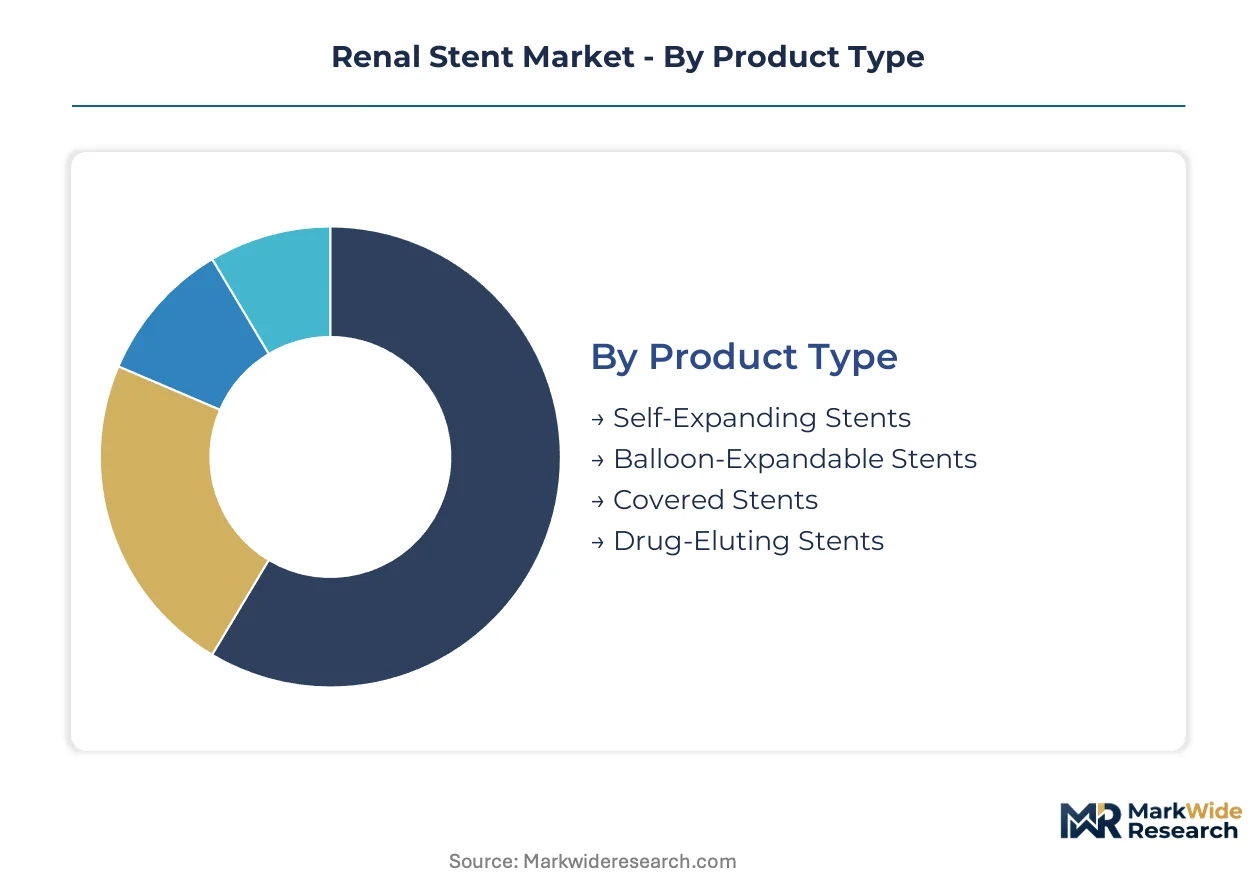
Renal stent purchasing decisions cascade through multiple technical and clinical filters. Procurement teams evaluate product form factor against procedural site-of-care economics, while clinicians prioritize patency duration and deployment precision for specific obstruction etiologies.
Product Type:
Clinicians select stent architecture based on obstruction chronicity, tissue ingrowth risk, and anticipated dwell time.
- Self-Expanding Stents:Nitinol-based designs deploy via constrained delivery sheaths and accommodate ureteral peristalsis without external fixation. Demand concentrates in outpatient settings across the United States where percutaneous access reduces anesthesia requirements and same-day discharge protocols dominate.
- Balloon-Expandable Stents:Cobalt-chromium platforms deliver acute diameter precision for calcified strictures in interventional radiology suites. Academic medical centers in Germany favor these configurations for procedural volume and quality metric transparency.
- Covered Stents:Polymer membranes block tumor ingrowth in malignant obstruction cases.
- Drug-Eluting Stents:Paclitaxel or sirolimus coatings inhibit hyperplasia and extend replacement intervals.
Self-expanding configurations lead on scale; drug-eluting variants lead on momentum.
Delivery Mode:
Site-of-care migration is restructuring access technique preferences across health system networks.
- Percutaneous:Image-guided needle access enables stent placement without endoscopic equipment. Ambulatory surgical centers in the United States are standardizing these workflows to capture outpatient reimbursement differentials.
- Endoscopic:Cystoscopic retrograde deployment retains dominance for distal ureteral lesions. Hospital networks in France maintain dedicated endourology suites for complex stone disease cases.
- Laparoscopic:Minimally invasive surgical access supports concurrent reconstructive procedures.
- Open Surgery:Direct visualization approaches persist for transplant anastomotic strictures.
Percutaneous delivery commands volume share; endoscopic methods defend position in stone-dense patient populations.
End User:
Capital equipment requirements and reimbursement structures fragment purchasing authority across care settings.
- Hospitals:Integrated delivery networks consolidate renal stent procurement through centralized supply chain functions. Multi-year agreements with technical training and inventory management clauses favor vendors with dedicated field service infrastructure.
- Ambulatory Surgical Centers:Simplified delivery systems and reduced sterile processing overhead align with outpatient economics. Medicare administrative contractor payment determinations for percutaneous nephrostomy conversions remain inconsistently defined.
- Specialty Clinics:Urology-focused practices concentrate high-volume stent exchange procedures.
- Research Institutions:Academic medical centers generate predicate device data for FDA 510(k) submissions.
Hospitals anchor procurement volume; ambulatory surgical centers climb the fastest on site-of-care migration.
Application:
Obstruction etiology dictates stent material selection, coating requirements, and anticipated functional lifespan.
- Ureteral Obstruction:Extrinsic compression from gynecologic or colorectal malignancies demands covered stent platforms. Palliative care pathways in the United Kingdom prioritize durable patency over replacement frequency.
- Renal Calculi:Stone passage and fragment migration create dynamic obstruction patterns. Lithotripsy centers in South Korea combine temporary stenting with extracorporeal shock wave protocols.
- Renal Transplant:Ureterovesical anastomotic strictures require biocompatible materials with low encrustation potential.
- Nephrolithiasis:Recurrent stone formers need frequent stent exchanges and infection-resistant designs.
Ureteral obstruction applications command premium positioning; renal calculi segments expand most quickly on procedural volume growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Interventional radiologists and urologists cluster in academic medical centers across Germany, the United States, and South Korea, anchoring procedural volume and technology adoption for renal stent deployment.
United States
Integrated delivery networks in Texas and California consolidate purchasing authority through multi-year supply agreements. The FDA's strengthened 510(k) premarket notification requirements extend clearance timelines for Class II devices. Boston Scientific Corporation leverages its interventional urology portfolio to secure contracts with large health systems in the Northeast corridor.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia favor balloon-expandable stent configurations for calcified stricture cases. The EU Medical Device Regulation's enhanced clinical evidence requirements reshape conformity assessment burdens for manufacturers. B. Braun Melsungen AG anchors its market position through dedicated renal access product lines and direct hospital service infrastructure in Baden-Württemberg.
South Korea
Lithotripsy centers in Seoul and Gyeonggi Province combine temporary stenting with extracorporeal shock wave protocols for renal calculi. The Ministry of Food and Drug Safety maintains alignment with international standards for nitinol-based implantable devices. Domestic manufacturers concentrate production capabilities in the Seoul Capital Area for regional export.
United Kingdom
Palliative care pathways in London and Manchester prioritize durable patency over replacement frequency for malignant ureteral obstruction cases. The Medicines and Healthcare products Regulatory Agency enforces post-market surveillance for drug-eluting stent coatings. Cook Medical competes by sustaining manufacturing flexibility across stainless steel and nitinol platforms for customized clinician preferences.
India
Urology-focused practices in Maharashtra and Karnataka concentrate high-volume stent exchange procedures for recurrent stone formers. The Central Drugs Standard Control Organization governs import licensing and quality certification for metallic implants. Blue Neem Medical Devices Pvt Ltd occupies a position among domestic fabricators serving price-sensitive hospital procurement departments.
Renal Stent Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers. The vendor base structures around three archetypes: diversified medical technology conglomerates with broad interventional portfolios, dedicated urology and nephrology device specialists, and regional fabricators serving price-sensitive markets. Consolidation pressures favor scaled players with captive clinical affairs capabilities and established predicate device libraries. Strategic moves concentrate on securing multi-year supply agreements with integrated delivery networks and adapting manufacturing flexibility across material platforms.
Within the diversified conglomerate tier, Boston Scientific Corporation and B. Braun Melsungen AG exemplify competitors leveraging broad interventional portfolios to anchor hospital procurement relationships. Cook Medical occupies a position among dedicated specialists competing through manufacturing flexibility and direct service infrastructure. Among regional fabricators, Blue Neem Medical Devices Pvt Ltd represents domestic players serving emerging market procurement departments with cost-optimized offerings.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| B. Braun Melsungen AG |
| Cook Medical |
| Opti-Med |
| Blue Neem Medical Devices Pvt Ltd |
| Bio-enterprise |
| Palex Medical |
| BD |
| Medline Industries |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery networks in the United States anchor procurement volume and unbundle after-sales service from device pricing, shifting vendor evaluation toward total cost-of-ownership frameworks that compress unit margins while elevating service premiums.
Pricing Analysis
Bundled technical training and inventory management clauses now separate premium vendor tiers from commodity competitors in multi-year supply agreements. Price differentiation hinges on FDA 510(k) predicate device libraries and dedicated field service infrastructure. Cost compression in standard bare-metal stents is intensifying because procurement consolidation favors scaled manufacturers with captive clinical affairs capabilities. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with quality metric transparency show lowest.
Supply Chain Analysis
ISO 25539-2 adaptation and FDA Class II device classification gate supplier qualification, concentrating nitinol and cobalt-chromium alloy sourcing among manufacturers with established quality systems. Raw material feeds from nickel-titanium suppliers in the United States, Germany, and China rest on limited supplier bases. Single-source vulnerability in nitinol ingot supply exposes production schedules to commodity price swings. Distribution runs through direct hospital service infrastructure and group purchasing organization contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in renal stent manufacturing derives from laser-cut mesh automation reducing lot-to-lot variability and drug-eluting coatings commanding premium positioning in malignant obstruction cases.
For Market Incumbents: Cement multi-year supply agreements with penalty clauses for service failures to lock out emerging competitors lacking dedicated field infrastructure. Deepen backward integration into nitinol alloy processing to defend against raw material cost swings and predicate device library gaps that FDA 510(k) timeline extensions now exploit as competitive barriers.
For New Entrants and Emerging Players: Ambulatory surgical centers in the United States represent the most penetrable buyer archetype as site-of-care migration outpaces established vendor service adaptation. Target simplified percutaneous delivery systems for outpatient economics where reimbursement coding inconsistencies create temporary pricing flexibility. Pursue CE marking pathway under EU MDR to access shelf space cleared by clinical evidence burdens marginalizing smaller European competitors.
For Investors and Strategic Acquirers: Diversified medical technology conglomerates are the most active acquirer in this space, seeking interventional urology portfolio breadth to secure integrated delivery network contracts. Manufacturing flexibility across stainless steel and nitinol platforms defines target acquisition profiles with durable competitive positioning. Watch ambulatory surgical center Medicare reimbursement determinations for percutaneous nephrostomy conversions as inflection signals for site-of-care acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Captures clearance velocity advantages from established predicate device libraries against MDR-pressured European competitors. |
| CE Marking Pathway Investment | Secures conformity assessment capacity before MDR clinical evidence requirements fully reshape European market access. |
| Hospital System Partnership | Locks multi-year supply agreements with technical training clauses that procurement consolidation now demands as baseline. |
| Software Companion Development | Enables image-guided delivery system integration for percutaneous access workflows standardizing in outpatient settings. |
| Reimbursement Strategy | Aligns product form factors with ambulatory surgical center payment structures as site-of-care migration accelerates. |
Research Methodology
Direct dialogue with interventional radiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers grounded qualitative insights in procurement workflow realities. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contract repositories, and EU MDR conformity assessment documentation. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against procedural volume estimates from academic medical centers.
Bottom-up modeling segmented volume and value outputs across product type, delivery mode, end user, and application dimensions throughout the forecast period. CAGRs were derived from slope analysis of annualized procedural growth adjusted for site-of-care migration patterns and regulatory timeline impacts. Forecast inputs incorporated nitinol price volatility indices and integrated delivery network consolidation trajectories specific to interventional urology device procurement.
Inputs from FDA premarket notification databases and EU notified body conformity assessments were available through the study window; gaps in real-time ambulatory surgical center reimbursement determinations introduce uncertainty bands around outpatient conversion projections. Forecasts reflect assumptions regarding MDR implementation pace and procurement consolidation velocity. A model refresh is warranted upon material change in Medicare administrative contractor payment structures for percutaneous nephrostomy procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
US Dialysis Services Market
Nephrology
Kidney Transplant Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Hemodialyzer Market
Nephrology
Global Continuous Renal Replacement Therapy (CRRT) Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Renal Denervation Market
Nephrology
Kidney Dialysis Equipment Market
Nephrology
Glomerulonephritis Treatment Market