
 Global Continuous Renal Replacement Therapy (CRRT) Market | 2026-2036
Global Continuous Renal Replacement Therapy (CRRT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Continuous Renal Replacement Therapy (CRRT) Market Foresight
Hospital intensive care units is unwinding from academic medical centers toward community hospital systems as sepsis protocols standardize. Fresenius Medical Care AG & Co. KGaA leverages its integrated dialysate manufacturing footprint across Germany and the United States. Baxter International anchors its position through deep relationships with critical care group purchasing organizations. B. Braun Melsungen AG competes on pump modularity, allowing bedside conversion between hemofiltration and hemodialysis modes.
Continuous Renal Replacement Therapy delivers slow, continuous blood purification for hemodynamically unstable patients, typically operating at ultrafiltration rates of 20-35 mL/kg/hour to maintain stable fluid removal without precipitating hypotension. Hemofiltration devices dominate installed base economics because disposable sets generate recurring revenue streams that exceed capital equipment margins. Acute Kidney Injury represents the fastest-growing therapy area segment as SOFA score-based screening protocols expand detection in emergency departments. Continuous Venovenous Hemofiltration leads delivery mode preference among intensivists for its superior middle-molecule clearance compared to slower continuous hemodialysis alternatives.
FDA 510(k) pathways and EU MDR Class IIa certification requirements shape product development cycles and geographic launch sequencing for device manufacturers. Japan's PMDA and China's NMPA impose additional clinical testing obligations that delay market entry for Western manufacturers. Stakeholders must monitor evolving ICU staffing ratios and reimbursement benchmarks for prolonged CRRT sessions as these operational variables determine whether community hospitals can sustain program economics outside tertiary referral networks.
Market Dynamics
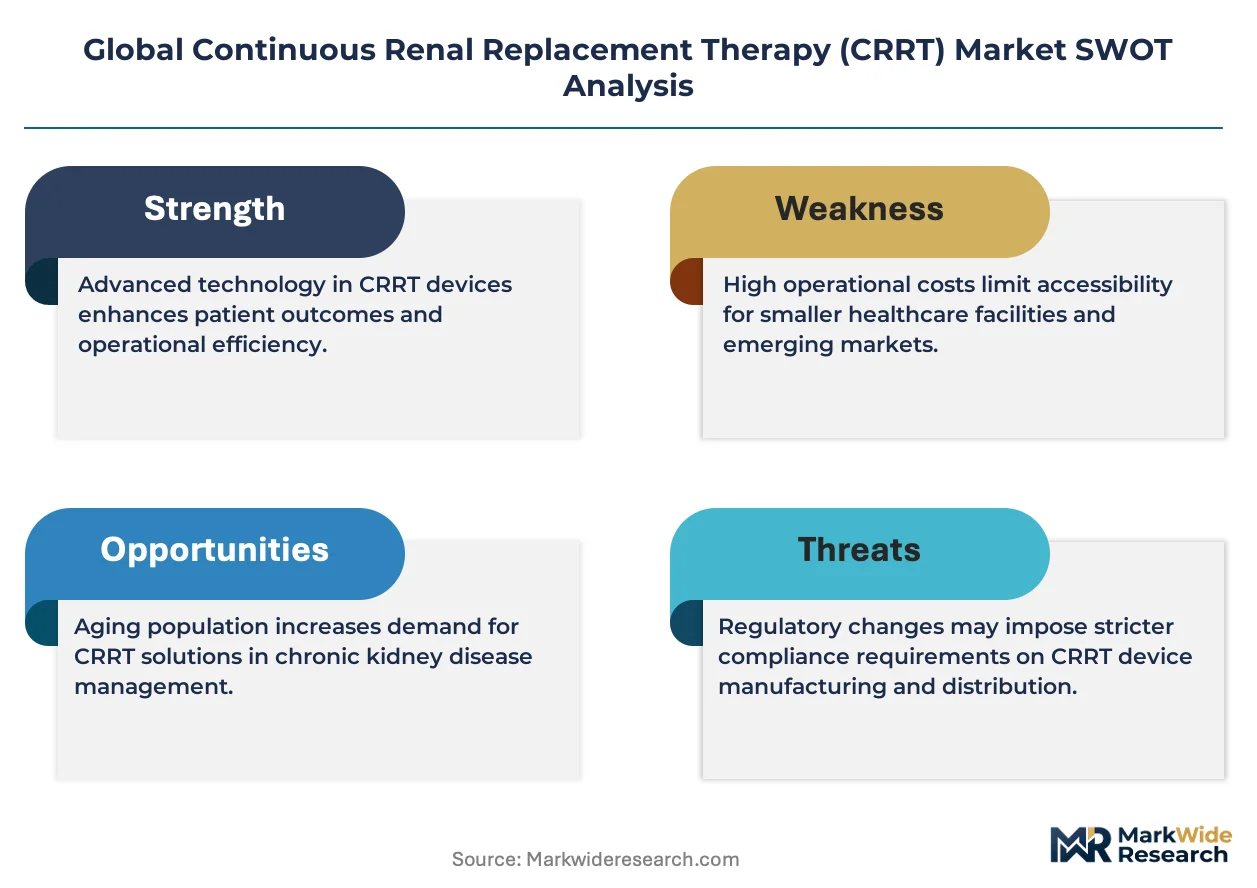
CRRT device economics pivot on disposable set pull-through revenue, creating structural pressure for manufacturers to lock in installed base loyalty through proprietary cartridge interfaces rather than open-platform compatibility.
Growth Catalysts
- EU MDR Class IIa certification harmonization:Streamlined conformity assessment pathways accelerate cross-border commercialization for device manufacturers targeting German and French hospital systems.
- Sepsis bundle protocols:Emergency department SOFA score implementation drives earlier AKI detection and CRRT initiation within 6-hour treatment windows.
- Silicon membrane oxygenators:Improved biocompatibility profiles extend circuit life beyond 72 hours, reducing nursing workload and supply consumption per patient.
Market Restraints
- Polymer supply concentration:Medical-grade polycarbonate for pump housings sources predominantly from German and Japanese chemical suppliers, exposing device makers to input cost volatility.
- Substitution by prolonged intermittent dialysis:Extended daily dialysis protocols in hemodynamically stable patients compress addressable volume for continuous modalities.
- PMDA clinical testing requirements:Japan's pharmaceutical and medical device agency mandates domestic bridging studies that extend registration timelines 18-24 months beyond FDA 510(k) clearance.
Strategic Opportunities
- Community hospital ICU expansion:United States rural health networks lack dedicated nephrology coverage, creating white space for remote monitoring-enabled CRRT programs.
- Hybrid renal-liver support systems:Convergence of albumin dialysis with hemofiltration circuits addresses multi-organ failure in acute-on-chronic liver disease.
- China NMPA innovation fast-track:Priority review pathways for breakthrough-designated devices compress approval timelines for novel anticoagulation management technologies.
Industry Challenges
- Critical care nurse specialization gaps:CRRT circuit troubleshooting and anticoagulation titration require competencies absent from standard ICU training curricula.
- ISO 10993 biocompatibility testing costs:Updated biological evaluation requirements for blood-contacting devices impose six-figure validation expenses on mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Continuous Renal Replacement Therapy (CRRT) Market |
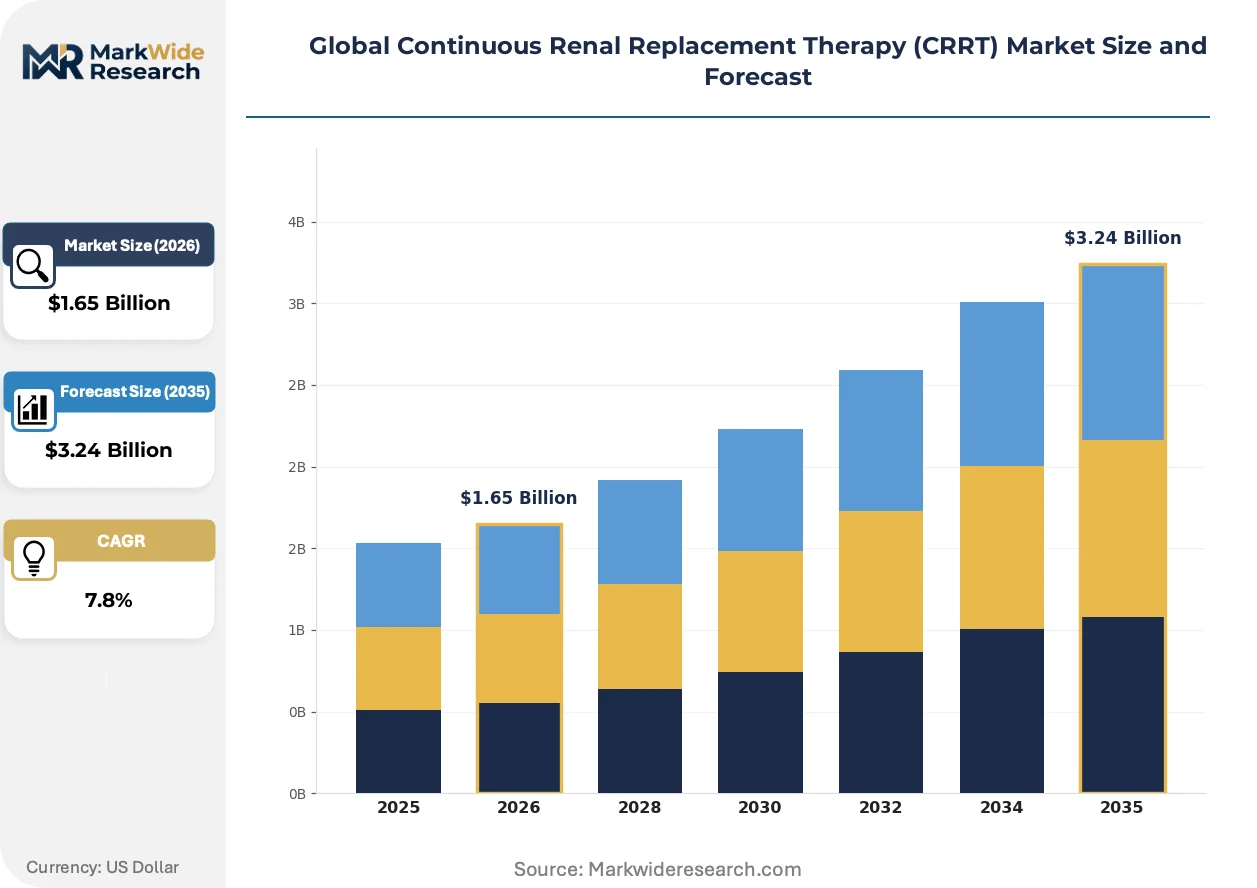
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.24 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemofiltration Devices, Hemodialysis Machines, Dialysate Fluids, Blood Pumps Therapy Area: Acute Kidney Injury, Sepsis, Multiple Organ Dysfunction, Fluid Overload End User: Intensive Care Units, Critical Care Centers, Specialty Clinics, Medical Research Institutes Delivery Mode: Continuous Venovenous Hemofiltration, Continuous Venovenous Hemodialysis, Continuous Venovenous Replacement, Slow Continuous Ultrafiltration |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International, B. Braun Melsungen AG, Medtronic, Asahi Kasei Corporation, Nikkiso Co., Ltd., NxStage Medical, Inc., NIPRO Corporation, Toray Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Continuous Renal Replacement Therapy (CRRT) Market Shifts & Advancements
Device architecture is fragmenting between high-acuity integrated platforms and modular point-of-care systems, with software-defined anticoagulation management emerging as the primary differentiation vector.
Regional citrate anticoagulation is bifurcating CRRT practice patterns between academic centers with in-house pharmacy compounding capabilities and community hospitals dependent on pre-mixed commercial solutions. Tertiary referral networks in the United States and Germany have adopted nurse-driven citrate protocols that reduce heparin exposure and bleeding complications. This technology is compressing the addressable market for heparin-based disposable sets while expanding serviceable ICU populations previously excluded from CRRT due to coagulopathy.
EU MDR technical documentation requirements are reshaping product lifecycle management for legacy devices originally cleared under the Medical Devices Directive. Manufacturers must retrospectively compile clinical evidence and post-market surveillance data for devices with decades of commercial history. Hemofiltration circuits with predicate claims dating to the 1990s face particular scrutiny, forcing portfolio rationalization decisions ahead of 2027 certificate expiration deadlines.
Hospital purchasing consortia are consolidating device selection authority from individual intensivists to centralized value analysis committees. Group purchasing organizations negotiate exclusive multi-year agreements that bundle capital equipment placement with disposable volume commitments. This concentration is most visible in United States health systems exceeding 50 hospitals, where standardization across facilities overrides site-specific physician preferences for pump interface design or alarm logic.
Global Continuous Renal Replacement Therapy (CRRT) Market Segmentation
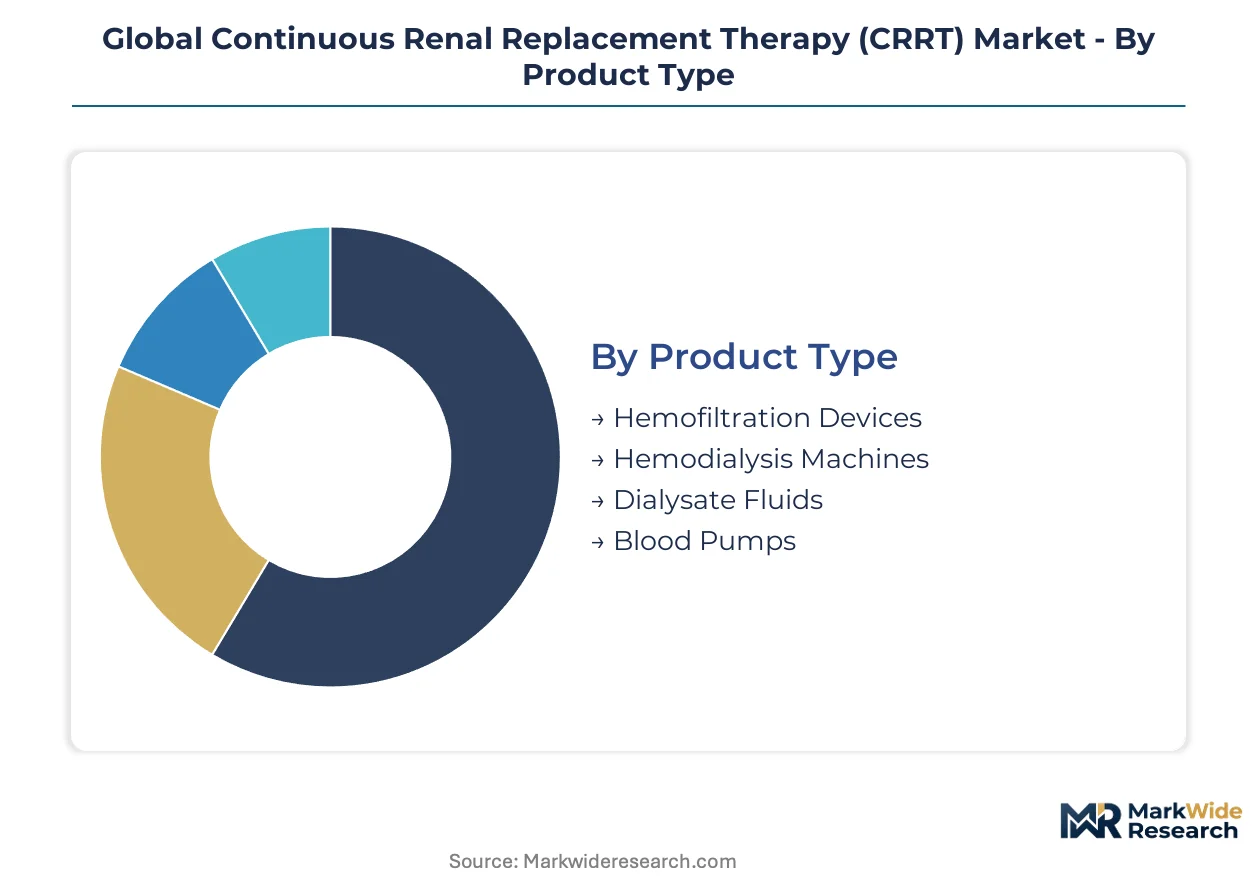
CRRT market segmentation reveals how revenue pools fragment across capital equipment, consumables, and service layers. Understanding these divisions exposes where manufacturers defend margin through proprietary interfaces versus where price competition dominates.
Product Type:
Disposable pull-through economics concentrate margin in recurring cartridge revenue rather than upfront capital sales.
- Hemofiltration Devices:These systems integrate blood pumps, filtration circuits, and fluid balancing mechanisms into bedside platforms. Demand clusters in United States academic medical centers where 72-hour circuit life reduces nursing workload. Silicon membrane oxygenators with improved biocompatility profiles extend operational duration and reduce replacement frequency.
- Hemodialysis Machines:Slower solute clearance rates suit hemodynamically stable patients requiring prolonged intermittent protocols. German hospital systems favor these configurations for cost containment in community ICU settings where continuous modality staffing costs prove unsustainable.
- Dialysate Fluids:Pre-mixed citrate solutions command premium positioning over pharmacy-compounded alternatives.
- Blood Pumps:Peristaltic and roller pump mechanisms vary by alarm sophistication and flow precision.
The dominant share belongs to Hemofiltration Devices, while Dialysate Fluids is closing the gap fastest.
Therapy Area:
Clinical indication expansion reshapes addressable patient populations beyond traditional nephrology boundaries.
- Acute Kidney Injury:SOFA score-based screening protocols in emergency departments compress time-to-treatment initiation. Japanese tertiary centers report expanded detection rates following sepsis bundle standardization, though PMDA testing requirements delay technology adoption versus Western markets.
- Sepsis:Inflammatory mediator clearance drives hemofiltration preference over dialysis modalities. United States critical care networks embed CRRT initiation within 6-hour sepsis bundles, creating protocol-driven demand independent of individual physician discretion.
- Multiple Organ Dysfunction:Hybrid renal-liver support configurations address complex multi-system failure.
- Fluid Overload:Congestive heart failure and post-surgical populations represent emerging off-label utilization.
Acute Kidney Injury maintains the largest patient volume base, yet Sepsis demonstrates the steepest expansion trajectory as bundle protocols proliferate.
End User:
Site-of-care migration from tertiary centers to community hospitals reconfigures purchasing authority and technical support requirements.
- Intensive Care Units:Level I trauma centers in Germany and Japan anchor installed base concentration. These facilities maintain dedicated CRRT nursing specialists and pharmacy compounding capabilities that support complex anticoagulation protocols unavailable in peripheral settings.
- Critical Care Centers:Standalone emergency-ICU hybrid facilities in United States rural health networks lack nephrology coverage. Remote monitoring partnerships with academic medical centers enable program sustainability despite staffing gaps.
- Specialty Clinics:Outpatient dialysis providers occasionally deploy portable CRRT for transitional care.
- Medical Research Institutes:Investigational device exemptions and clinical trial infrastructure support next-generation anticoagulation management development.
Intensive Care Units retain the dominant procurement volume, though Critical Care Centers are gaining share fastest as community hospital networks expand sepsis protocol coverage.
Delivery Mode:
Clearance kinetics and anticoagulation requirements differentiate modality selection among intensivist practice patterns.
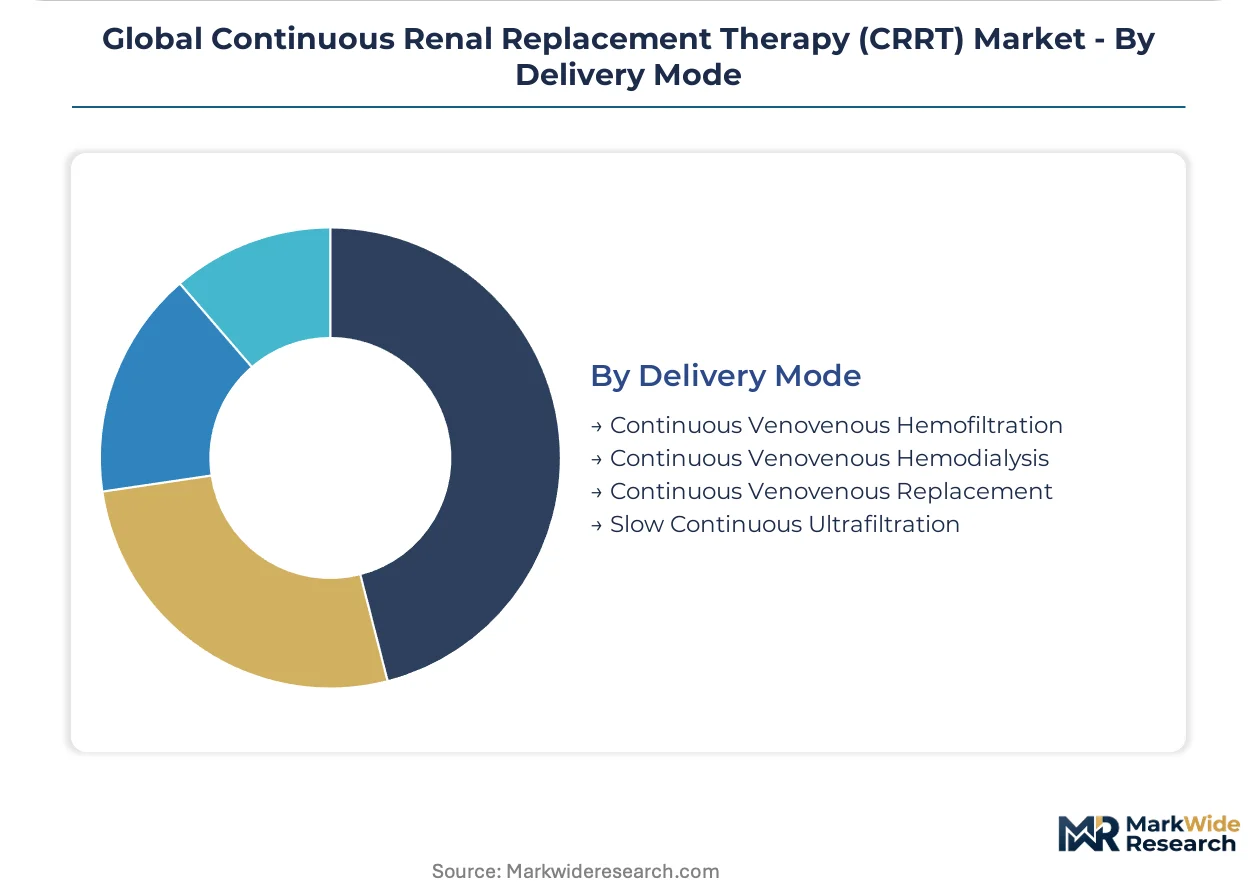
- Continuous Venovenous Hemofiltration:Convective transport achieves superior middle-molecule clearance compared to diffusive alternatives. Academic centers in the United States and Germany favor this modality for septic patients requiring inflammatory cytokine removal.
- Continuous Venovenous Hemodialysis:Slower solute clearance suits stable patients with predominant electrolyte disturbances rather than volume overload. Lower operational complexity reduces training burden for community hospital staff without dedicated CRRT specialization.
- Continuous Venovenous Replacement:Combined convective-diffusive mechanisms balance clearance efficiency.
- Slow Continuous Ultrafiltration:Isolated fluid removal without significant solute clearance addresses refractory edema.
Continuous Venovenous Hemofiltration holds the leading utilization share, while Continuous Venovenous Hemodialysis is expanding most quickly as community hospital adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dialysate manufacturers export pre-mixed citrate solutions to United States hospital systems seeking standardized anticoagulation protocols. This transatlantic trade corridor shapes inventory planning across North American intensive care networks.
United States
Sepsis bundle protocols and aging ICU infrastructure drive CRRT utilization in tertiary referral centers. FDA 510(k) pathways govern device clearance timelines for manufacturers entering the market. Academic medical centers in Boston and Baltimore anchor clinical trial activity for next-generation anticoagulation management systems.
Germany
Integrated dialysate manufacturing and proximity to polymer suppliers concentrate device production economics. EU MDR Class IIa certification requirements reshape technical documentation obligations for legacy hemofiltration circuits. The Baden-Württemberg medical technology cluster hosts specialized pump housing fabricators serving mid-tier equipment makers.
Japan
PMDA bridging study mandates extend registration timelines for Western manufacturers by 18-24 months beyond FDA clearance. Aging demographics and standardized sepsis screening in Tokyo tertiary centers expand addressable patient populations. The Osaka-Kobe medical device corridor concentrates domestic assembly operations for silicon membrane oxygenators.
China
NMPA priority review pathways for breakthrough-designated devices compress approval timelines for novel anticoagulation technologies. Provincial health procurement reforms in Jiangsu and Zhejiang provinces drive price competition among domestic and imported equipment suppliers. The Yangtze River Delta hosts contract manufacturers producing blood pump components for multinational assembly networks.
Global Continuous Renal Replacement Therapy (CRRT) Market Competitive Landscape
Listed leaders compete with private specialists across disposable set manufacturing and regional anticoagulation solution compounding. The vendor base fragments between integrated dialysis conglomerates, modular pump specialists, and membrane technology providers. Three archetypes dominate: vertically integrated dialysate-to-device operators, point-of-care platform innovators, and component-specialist contract manufacturers. Competitive moves concentrate on proprietary cartridge interface lock-in and remote monitoring service bundling.
Among Germany-based integrated operators, Fresenius Medical Care AG & Co. KGaA and B. Braun Melsungen AG occupy positions spanning dialysate production through bedside platform deployment. Baxter International exemplifies the United States-listed critical care conglomerate archetype with deep group purchasing organization relationships. Asahi Kasei Corporation represents the Japanese membrane technology specialist tier supplying silicon oxygenator components to downstream device assemblers.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International |
| B. Braun Melsungen AG |
| Medtronic |
| Asahi Kasei Corporation |
| Nikkiso Co., Ltd. |
| NxStage Medical, Inc. |
| NIPRO Corporation |
| Toray Medical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Installed base scale economies in hemofiltration device manufacturing concentrate margin protection among German and United States producers with captive dialysate operations, compressing price floors for mid-tier competitors dependent on outsourced polymer supply.
Pricing Analysis
Next-generation silicon membrane oxygenators command 40-60% premiums over legacy polycarbonate configurations, while prior-generation peristaltic pump systems face accelerating price erosion in United States group purchasing organization negotiations. Three-tier pricing structure across premium anticoagulation-integrated platforms, standard modular systems, and economy fixed-configuration devices reflects FDA 510(k) clearance tier and remote monitoring capability bundling. Cost compression in economy tiers is intensifying because Chinese contract manufacturers are expanding blood pump component output. Community hospital systems exhibit highest price sensitivity due to uncompensated prolonged CRRT session costs, while academic medical centers prioritize circuit longevity over acquisition price.
Supply Chain Analysis
BASF and Covestro polymer supply corridors through Rotterdam-Antwerp port infrastructure expose device makers to medical-grade polycarbonate concentration risk from German and Japanese chemical suppliers. Blood pump housings draw from Baden-Württemberg precision molding clusters, silicon membrane substrates source from Osaka-Kobe oxygenator specialists, and pre-mixed citrate solutions compound at Fresenius integrated facilities across Germany and the United States. Single-source vulnerability concentrates in pharmaceutical-grade citrate supply for regional anticoagulation protocols. Distribution runs through hospital group purchasing organization warehouses with consignment inventory arrangements for disposable cartridge replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation of United States health systems exceeding 50 hospitals has shifted purchasing authority from individual intensivists to centralized value analysis committees, amplifying buyer leverage in multi-year exclusive agreements.
For Market Incumbents: Fortify installed base loyalty through proprietary cartridge interface lock-in rather than open-platform compatibility, as Baxter International and Fresenius Medical Care have demonstrated with deep group purchasing organization relationships. Expand backward integration into silicon membrane substrate production to insulate margin from Japanese supply concentration. Prioritize FDA 510(k) pathway investments for next-generation anticoagulation management software to defend against modular point-of-care system entrants. For New Entrants and Emerging Players: China NMPA breakthrough-designated device fast-track offers compressed approval timelines for novel anticoagulation technologies, creating regulatory arbitrage opportunities versus PMDA bridging study requirements. Target United States rural critical care centers lacking dedicated nephrology coverage through remote monitoring-enabled service bundling rather than capital equipment sales. Penetrate community hospital ICU expansion white space via nurse-driven citrate protocol simplification and pharmacy compounding partnerships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors membrane technology specialists with silicon oxygenator component supply relationships over capital equipment assemblers facing disposable margin compression. Five-to-ten year viability hinges on hybrid renal-liver support system convergence for multi-organ failure indications. Monitor EU MDR Class IIa certificate expiration deadlines for legacy hemofiltration circuits as portfolio rationalization catalysts forcing target availability.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Software-Defined Anticoagulation | Accelerates clearance timelines for algorithm-driven citrate dosing versus predicate device pathways. |
| Hospital System Partnership with Remote Monitoring Integration | Enables community hospital CRRT program sustainability despite nursing specialization gaps. |
| CE Marking Pathway Under EU MDR Class IIa Harmonization | Streamlines cross-border commercialization for German and French hospital system entry. |
| Backward Integration into Silicon Membrane Substrate Production | Reduces dependency on Asahi Kasei and Toray Medical component supply concentration. |
| Reimbursement Strategy for Prolonged CRRT Session Coverage | Addresses CMS benchmark gaps that threaten community hospital program economics. |
Research Methodology
Two parallel data streams informed the analysis: primary intelligence collection and secondary source validation. Intensive care unit directors, biomedical engineering managers, group purchasing organization contracts specialists, and dialysis device regulatory affairs leads contributed operational perspective through structured interviews. Secondary sources encompassed FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and CMS reimbursement benchmark publications. Bottom-up installed base modeling and top-down therapy area demand estimation were cross-validated to reconcile volume projections.
Across the projection horizon, the analytical framework segmented demand by product type, therapy area, end user site-of-care, and delivery mode, with anticoagulation protocol adoption curves modeled as a cross-cutting dimension. CAGRs were derived from logistic diffusion curves fitted to historical ICU bed expansion and sepsis bundle protocol penetration rates. Forecast inputs incorporated PMDA registration timeline differentials, EU MDR certificate expiration schedules, and Chinese provincial health procurement reform implementation trajectories.
Decision-makers should treat outputs as directional under assumptions of stable ICU staffing ratio regulations and sustained sepsis bundle protocol adherence; material deviation in anticoagulation reimbursement policy or polymer supply disruption would warrant model refresh. Practitioners should keep alternative scenarios live as NMPA innovation fast-track eligibility criteria and United States rural health network consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Renal Stent Market
Nephrology
Global Hemodialysis Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Hemodialysis Services Market
Nephrology
Kidney Transplant Market
Nephrology
Global Dialyzer Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Renal Artery Embolization Market
Nephrology
Chronic Kidney Disease Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
Hemodialyzer Market