
 Americas Healthcare Human Resources (HR) Software Market | 2026-2036
Americas Healthcare Human Resources (HR) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Healthcare Human Resources (HR) Software Market Outlook
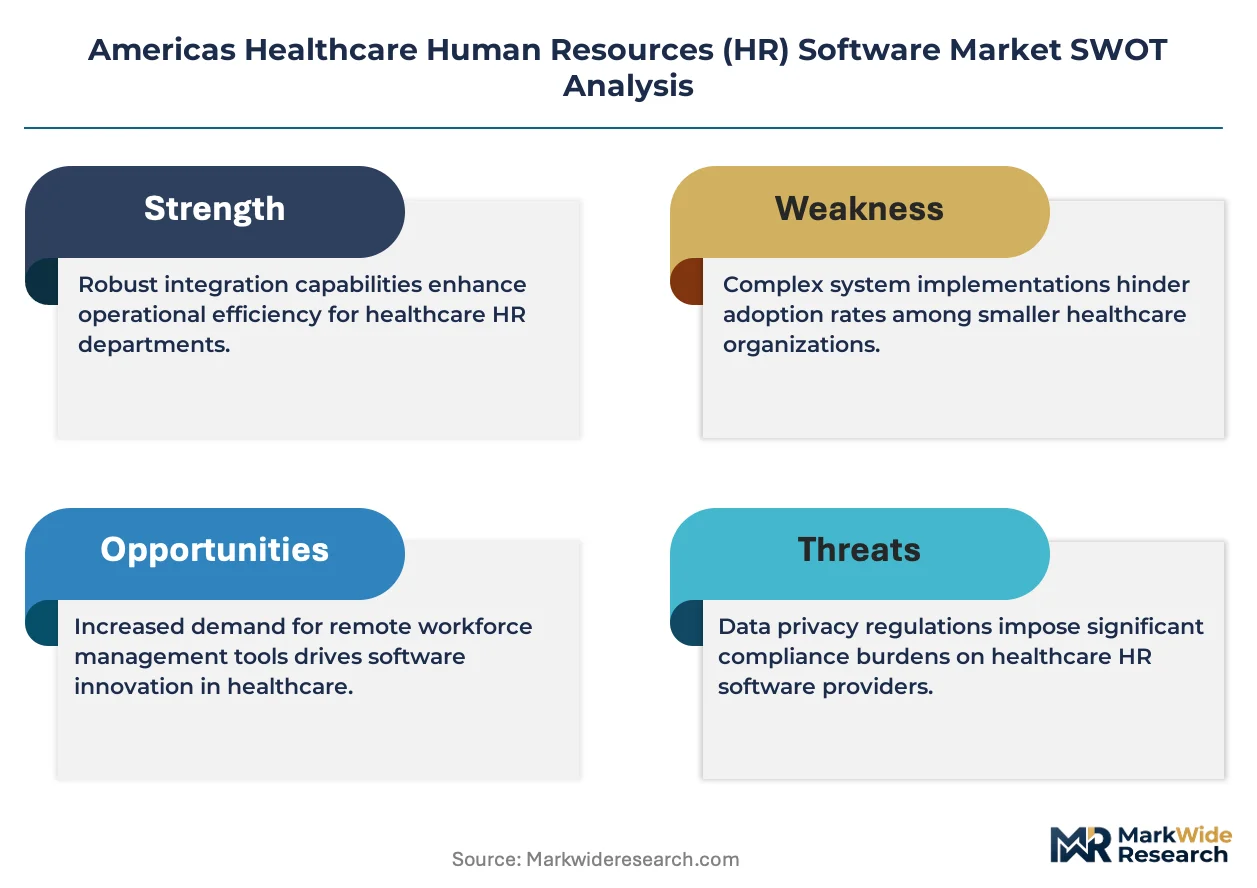
Subscription-based workforce analytics is pivoting how healthcare HR software gets monetized, shifting buyers from perpetual licenses toward recurring revenue models with embedded compliance dashboards. Oracle Corporation leverages its cloud infrastructure dominance to anchor large hospital network deployments across North America. Workday, Inc. competes through native AI-driven scheduling tools that reduce nurse overtime expenditures. SAP SE specializes in payroll management modules that integrate with existing ERP ecosystems prevalent in multi-facility health systems.
Americas Healthcare Human Resources Software encompasses cloud-deployed and on-premise platforms that automate credential verification, shift allocation, benefits administration, and regulatory reporting for medical employers, typically operating through HL7- or FHIR-compatible interfaces to synchronize workforce data with clinical systems. The primary commercial purpose is reducing administrative labor costs while ensuring Joint Commission-ready documentation trails for staff qualifications. Cloud-Based and SaaS deployment modes are capturing the fastest growth as Brazilian and Mexican hospital groups bypass legacy server investments. Recruitment Software and Performance Management represent concentrated margin pools where specialized vendors command premium pricing for predictive turnover analytics and competency-tracking engines.
FDA oversight of clinical decision-support functions embedded in scheduling algorithms, alongside HIPAA mandates for workforce data encryption, creates compliance barriers that favor established vendors with dedicated healthcare practices. OSHA workplace safety reporting requirements and state-level nurse staffing ratio laws in California and Massachusetts further shape product feature roadmaps. Stakeholders must monitor how CMS reimbursement rule changes around value-based care staffing metrics will reshape HR software procurement criteria in hospital systems.
Market Dynamics
Hospital systems across the Americas are consolidating vendor relationships around cloud-native platforms that unify credentialing, scheduling, and compliance reporting under single administrative umbrellas. This consolidation is compressing procurement cycles and raising barriers for point-solution vendors lacking healthcare-specific regulatory expertise.
Growth Catalysts
- HIPAA Security Rule enforcement:Federal audits of workforce data protection are compelling hospital networks to replace legacy on-premise systems with encrypted cloud architectures that automate breach notification protocols.
- Clinician shortage pressures:Health systems in Texas and Florida are deploying predictive scheduling algorithms to optimize labor pools across multi-site networks, reducing reliance on expensive agency staffing.
- Cloud infrastructure maturation:Brazilian public hospitals are leapfrogging server-based deployments through SaaS procurement frameworks that accelerate implementation timelines from years to months.
Market Restraints
- FDA algorithmic oversight:Scheduling tools incorporating clinical decision-support functions face extended validation timelines, delaying product launches and inflating development costs for vendors.
- Interoperability fragmentation:Inconsistent HL7 and FHIR implementation across EHR vendors forces HR software providers to maintain multiple integration codebases, raising maintenance overhead.
- Data localization mandates:Provincial privacy regulations in Quebec and British Columbia require Canadian health authorities to host workforce data within national borders, restricting vendor options.
Strategic Opportunities
- Mexican hospital digitization:Private hospital chains in Guadalajara and Monterrey are initiating first-generation HR automation projects, creating entry points for cloud-native vendors without legacy displacement costs.
- OSHA safety reporting integration:Modules that auto-populate workplace injury documentation from shift scheduling data are capturing premium pricing from hospital systems seeking audit-ready compliance trails.
- AI-driven turnover prediction:Machine learning models analyzing credential expiration patterns and scheduling fatigue metrics are opening new revenue streams in workforce retention consulting.
Industry Challenges
- FHIR interface expertise scarcity:Vendors struggle to recruit developers proficient in healthcare data exchange standards, slowing product roadmaps and inflating salary costs for specialized talent.
- Joint Commission documentation rigor:Staff qualification tracking systems must maintain immutable audit trails spanning multiple employment periods, complicating database architecture and query performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Healthcare Human Resources (HR) Software Market |
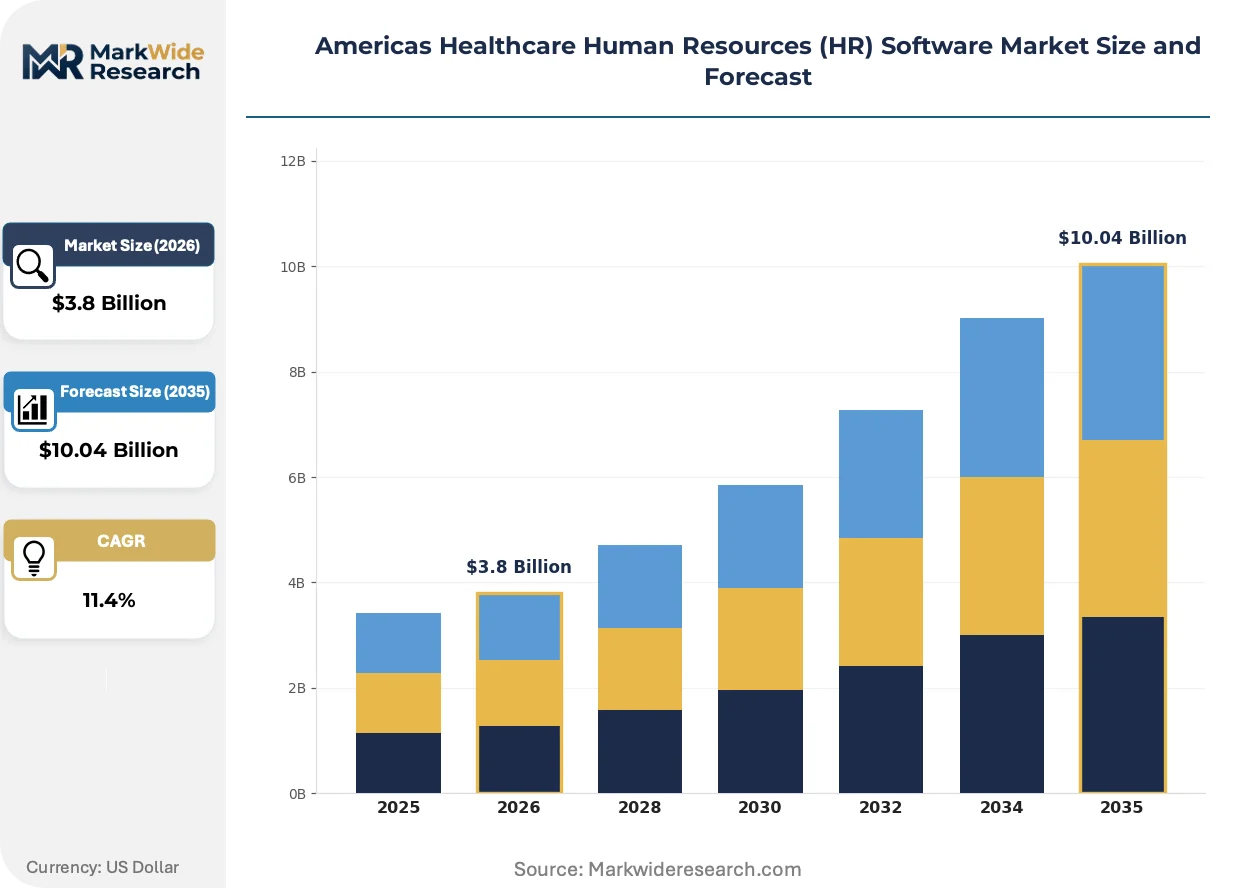
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recruitment Software, Payroll Management, Time & Attendance, Performance Management Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Hospitals, Clinics, Long-Term Care Facilities, Health Insurance Providers Service Type: Support Services, Consulting, Customization, Training |
| Companies Covered | SAP SE, BambooHR, Workday, Inc., Infor, Inc., IBM Corporation, Oracle Corporation, UKG, Paycom Software, Inc., ADP, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Healthcare Human Resources (HR) Software Market Strategic Shifts
Workforce management platforms are absorbing adjacent functionalities—credential verification, benefits administration, and regulatory reporting—into unified cloud architectures that reduce hospital IT integration burdens.
Embedded predictive analytics is rewriting how health systems allocate clinical labor. These engines forecast patient census fluctuations and match them against staff availability matrices. Large hospital networks in California and New York are deploying these tools at enterprise scale, compressing overtime expenditures and reducing last-minute scheduling disruptions. The technology is rewriting competitive positioning by elevating vendors with proprietary healthcare labor datasets above generic workforce management providers.
State-level nurse staffing ratio laws in California and Massachusetts are mandating granular shift-level reporting that legacy systems cannot accommodate. This regulatory pressure is forcing hospital procurement committees to prioritize platforms with native compliance dashboards over cost-focused alternatives. Vendors are responding by embedding real-time staffing alerts and automated ratio calculators into core scheduling modules, particularly for acute care facilities where penalties for non-compliance escalate rapidly.
Subscription-based monetization is displacing perpetual license sales across the Americas. Hospital CFOs prefer operational expenditure treatment for software investments, aligning vendor incentives with ongoing platform utilization rather than upfront deployment. This shift is most visible among mid-sized health systems in the US Southeast and Brazilian public hospital consortia, where capital constraints favor predictable monthly fees over large initial outlays.
Americas Healthcare Human Resources (HR) Software Market Segmentation
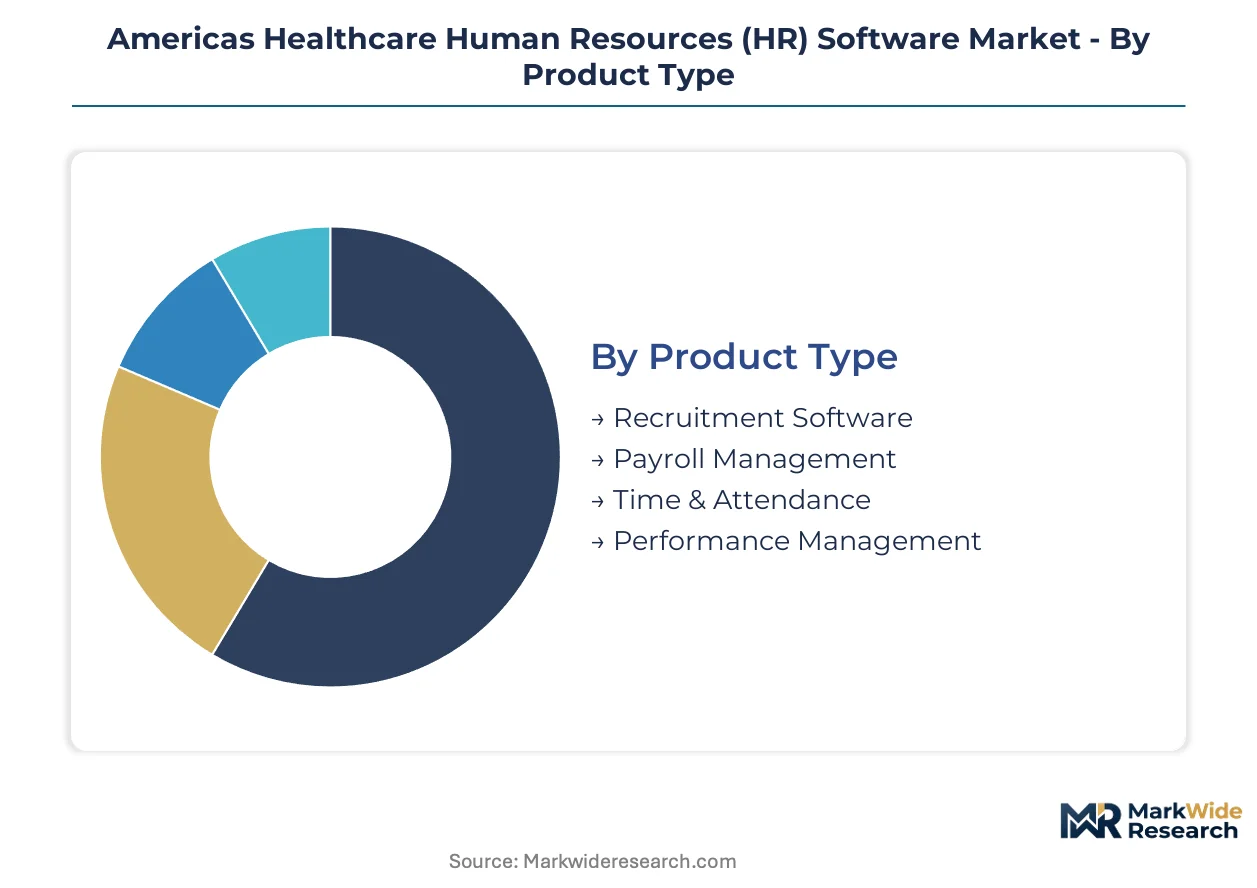
Segmentation reveals how regulatory complexity and infrastructure maturity split demand across the Americas healthcare HR software landscape. Certification burdens vary sharply by product architecture and deployment mode, directing procurement budgets toward segments with embedded compliance automation.
Product Type:
HIPAA Security Rule enforcement and Joint Commission documentation standards impose distinct certification loads across functional modules, with predictive analytics engines facing heightened FDA scrutiny when embedded in workforce algorithms.
- Recruitment Software:Credential verification engines automate primary source verification and license expiration tracking through direct integrations with state medical boards. Texas and Florida hospital systems concentrate procurement here, driven by clinician shortage pressures and agency staffing cost containment mandates.
- Performance Management:Competency-tracking platforms maintain immutable audit trails for continuing education and privileging decisions, requiring HL7-FHIR compatibility for EHR synchronization. California and Massachusetts health systems prioritize these tools to satisfy state nurse staffing ratio documentation laws.
- Payroll Management:Multi-jurisdictional tax calculation engines integrate with existing ERP ecosystems prevalent in multi-facility health systems.
- Time & Attendance:Shift allocation modules with biometric authentication and fatigue-metric tracking.
Leading the category by volume: Recruitment Software. Expanding most quickly: Performance Management.
Deployment:
Cost tier stratification separates capital-constrained buyers from organizations prioritizing operational expenditure treatment and rapid implementation timelines.
- Cloud-Based:Encrypted architectures hosted on third-party infrastructure automate breach notification protocols and disaster recovery. Brazilian public hospital digitization programs and Mexican private chains in Guadalajara concentrate demand, bypassing legacy server investments entirely.
- SaaS:Subscription frameworks with embedded compliance dashboards shift vendor incentives toward ongoing platform utilization. US Southeast mid-sized health systems favor this model for predictable monthly fees over large initial outlays.
- Hybrid:Mixed architectures retaining sensitive workforce data on-premise while leveraging cloud analytics layers.
- On-Premise:Server-based deployments requiring dedicated IT maintenance and capital depreciation schedules.
Cloud-Based deployments capture the steepest expansion trajectory as Latin American markets leapfrog infrastructure generations. SaaS maintains the largest installed base among US hospital networks.
End User:
Application intensity varies by regulatory exposure and workforce scale, with acute care facilities facing the most stringent documentation requirements.
- Hospitals:Enterprise-scale platforms unifying credentialing, scheduling, and compliance reporting under single administrative umbrellas. Large network consolidations across the United States compress procurement cycles and elevate barriers for point-solution vendors.
- Long-Term Care Facilities:Specialized modules addressing high turnover environments and state-specific staffing minimums for skilled nursing facilities.
- Clinics:Lightweight deployments emphasizing provider enrollment and payer credentialing synchronization.
- Health Insurance Providers:Provider network management tools with directory accuracy and sanctions monitoring capabilities.
Hospitals dominate absolute spending. Long-Term Care Facilities are gaining share fastest as workforce retention crises intensify in post-acute settings.
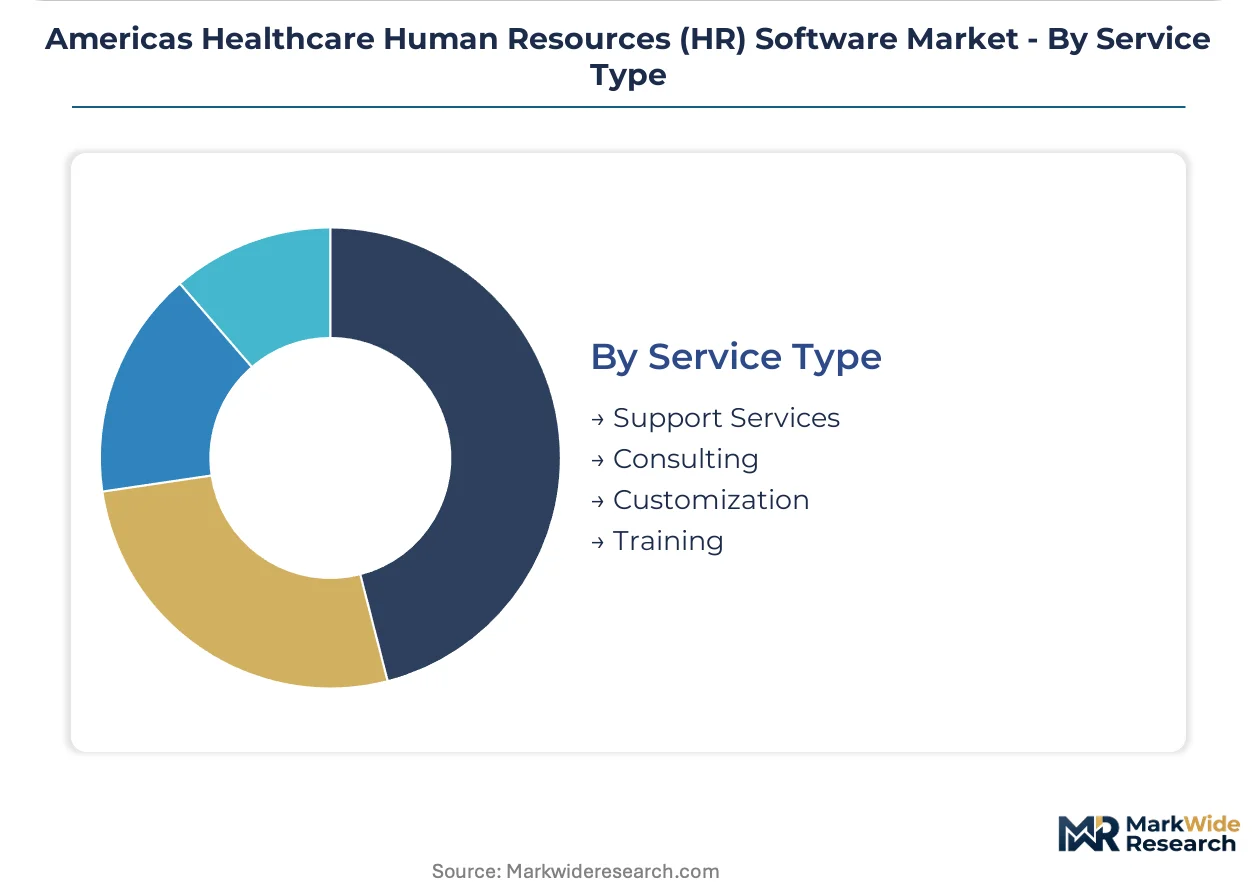
Service Type:
Margin concentration follows implementation complexity and ongoing regulatory change velocity, with customization commanding premium pricing in fragmented EHR integration environments.
- Consulting:Workforce optimization advisory services leveraging proprietary healthcare labor datasets to forecast patient census fluctuations and match staff availability matrices. California and New York hospital networks deploy these engagements at enterprise scale.
- Customization:FHIR interface development and EHR-specific integration builds addressing interoperability fragmentation across vendor ecosystems.
- Training:Change management and user adoption programs for clinical staff transitioning from paper-based or legacy digital workflows.
- Support Services:Tiered help desk and technical maintenance contracts with healthcare-specific response time guarantees.
Consulting services generate the highest margins per engagement. Customization revenues are climbing fastest as interoperability mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems across the United States dominate procurement volumes, with Texas Medical Center in Houston and Massachusetts General Hospital network driving enterprise-scale deployments of integrated talent platforms.
United States
Hospital networks in California and New York deploy predictive scheduling algorithms to optimize labor pools across multi-site operations. HIPAA Security Rule enforcement compels replacement of legacy on-premise systems with encrypted cloud architectures. Texas Medical Center anchors demand concentration, with health systems reducing agency staffing expenditures through AI-driven workforce analytics.
Brazil
Public hospital digitization programs accelerate cloud-based HR system procurement as federal investments bypass legacy server infrastructure. ANVISA guidelines for healthcare data management shape vendor selection criteria for workforce platforms. São Paulo metropolitan hospitals concentrate implementation activity, with state health consortia favoring SaaS frameworks for predictable operational expenditure treatment.
Canada
Provincial health authorities in Ontario and Alberta prioritize platforms with native compliance dashboards for workforce documentation. Provincial privacy regulations in Quebec and British Columbia mandate data localization within national borders, restricting vendor options. Toronto and Vancouver hospital clusters drive procurement for encrypted architectures with automated breach notification protocols.
Mexico
Private hospital chains in Guadalajara and Monterrey initiate first-generation HR automation projects without legacy displacement costs. Federal labor law digitization mandates accelerate procurement timelines for credential verification engines. Jalisco state health system consolidations create entry points for cloud-native vendors seeking mid-market expansion.
Americas Healthcare Human Resources (HR) Software Market Competitive Environment
Capital-heavy enterprise software conglomerates compete with asset-light SaaS specialists across the Americas healthcare HR software landscape. Market structure concentrates around three tiers: cloud infrastructure majors anchoring large hospital networks, mid-market specialists capturing regional health systems, and point-solution vendors serving niche compliance requirements. Strategic archetypes include integrated platform providers unifying credentialing and scheduling, payroll-centric vendors leveraging ERP ecosystem relationships, and predictive analytics specialists commanding premium pricing for turnover forecasting. Dominant competitive moves encompass vertical integration into adjacent workforce management functions and geographic expansion through localized compliance module development.
Within the integrated platform tier, Oracle Corporation and Workday, Inc. occupy anchor positions representing divergent strategic approaches to hospital network penetration. Oracle leverages cloud infrastructure dominance for large-scale North American deployments, while Workday competes through native AI-driven scheduling tools. SAP SE exemplifies the payroll-centric archetype, specializing in modules that integrate with existing ERP ecosystems prevalent in multi-facility health systems.
| Leading Market Players |
|---|
| SAP SE |
| BambooHR |
| Workday, Inc. |
| Infor, Inc. |
| IBM Corporation |
| Oracle Corporation |
| UKG |
| Paycom Software, Inc. |
| ADP, Inc. |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure pricing indices from hyperscale providers cascade through SaaS vendor cost structures, compressing mid-tier pricing as Brazilian and Mexican hospital buyers demand operational expenditure models over capital-intensive deployments.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects hyperscaler compute cost pass-throughs and intensifying competition from ERP-integrated payroll specialists. Pricing stratifies across enterprise-grade compliance bundles, mid-market subscription tiers, and lightweight per-employee-per-month offerings. Cost-down pressure on standalone recruitment modules accelerates because hospital networks consolidate vendor relationships around unified platforms. Public hospital consortia in Brazil exhibit highest price sensitivity; large US health systems with GPO contracts demonstrate lowest.
Supply Chain Analysis
Developer talent scarcity in São Paulo and Bangalore constrains FHIR interface engineering capacity, forcing vendors to distribute R&D across multiple labor pools. Software development centers on the United States, India, and Brazil. Cloud infrastructure draws from AWS, Azure, and Google Cloud data center networks. Regulatory compliance consulting feeds from specialized healthcare law practices in Washington DC and São Paulo. Single-source vulnerability concentrates in FHIR expertise pipelines. Distribution runs through direct enterprise sales teams and regional value-added resellers serving mid-sized health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital vendor consolidation around unified platforms is compressing procurement cycles and eliminating point-solution providers lacking healthcare-specific regulatory expertise.
For Market Incumbents: Anticipate margin compression from ERP-integrated payroll specialists by embedding predictive analytics modules that reduce client agency staffing expenditures. Prioritize certification investments for HIPAA Security Rule automation and Joint Commission audit trail immutability. Channel control through exclusive GPO relationships defends position against cloud-native challengers. For New Entrants and Emerging Players: Begin with Mexican private hospital chains in Guadalajara and Monterrey, where first-generation automation projects proceed without legacy displacement costs. Target mid-sized US Southeast health systems seeking subscription-based operational expenditure treatment. A compliance-first go-to-market angle—embedding native staffing ratio calculators—differentiates against generic workforce management providers. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized predictive analytics vendors with proprietary healthcare labor datasets in California and New York hospital network footprints. Long-term viability hinges on FHIR interface expertise depth and regulatory automation moats. Watch for CMS reimbursement rule changes around value-based care staffing metrics as inflection signal for procurement priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR Interface Development Investment | Addresses interoperability fragmentation forcing multiple integration codebases across EHR vendor ecosystems. |
| HIPAA Compliance Automation Module Launch | Captures federal audit-driven replacement demand for encrypted cloud architectures with breach notification protocols. |
| Strategic Partnership with GPO Networks | Secures channel access to hospital procurement committees consolidating vendor relationships under single umbrellas. |
| Acquisition of Predictive Analytics Specialist | Integrates proprietary healthcare labor datasets elevating vendors above generic workforce management providers. |
| Geographic Expansion into Brazilian Public Hospital Consortia | Exploits federal digitization investments bypassing legacy server infrastructure through SaaS procurement frameworks. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving hospital CIOs, HR technology procurement leads, GPO contracts managers, and FHIR integration specialists. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level estimates. Hospital procurement databases, CMS Medicare reimbursement filings, ANVISA healthcare data management guidelines, and hyperscaler capex disclosures supplied quantitative anchors.
Data-stream reconciliation across deployment mode, organization size, vertical integration complexity, and regional regulatory cluster dimensions produced volume and value estimates throughout the forecast period. CAGRs derived from regression analysis against historical procurement cycle data and cloud adoption velocity metrics. Industry-specific inputs incorporated clinician shortage indices and state-level nurse staffing ratio law implementation timelines.
Underlying measurement precision varies by segment; cloud-based and SaaS deployment modes carry tighter precision than hybrid architectures given clearer procurement visibility. Forecasts reflect documented assumptions regarding HIPAA enforcement intensity and Brazilian federal health IT investment continuity. Material deviation in CMS value-based care staffing metrics or ANVISA data localization mandates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Europe Dental Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Healthcare Mobility Solutions Market
Healthcare IT
Asia-Pacific Revenue Cycle Management Market
Healthcare IT
Europe Hospital Capacity Management Solutions Market
Healthcare IT
Healthcare IT Market
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
Neurosurgery Software Market
Healthcare IT
Senior Care Technologies Market
Healthcare IT
Pharmaceutical Quality Management Systems Market
Healthcare IT
Operating Room Management Software Market
Healthcare IT
Ambulatory Surgical Centers IT Services Market
Healthcare IT
North American Dental Software Market
Healthcare IT
Anatomic Pathology Track and Trace Solutions Market
Healthcare IT
US Urgent Care Center Software Market
Healthcare IT
Global Personal Health Records Software Market