
 Renal Cell Carcinoma Market | 2026-2036
Renal Cell Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Renal Cell Carcinoma Market Outlook
First-line metastatic treatment standards is collapsing toward dual checkpoint inhibition as the benchmark of care. Bristol Myers Squibb Company sustains competitive intensity through its established PD-1 franchise depth. Merck & Co., Inc. leverages pembrolizumab combinations across multiple label expansions. Pfizer Inc. anchors its position through targeted therapy portfolios aligned with VEGF pathway biology.
Renal cell carcinoma constitutes a heterogeneous group of kidney malignancies arising from proximal tubular epithelial cells, with clear cell histology representing the dominant subtype characterized by von Hippel-Lindau gene mutations and associated angiogenic signaling dysregulation. The primary therapeutic objective centers on disrupting angiogenic and immunosuppressive tumor microenvironments to extend progression-free survival in localized and metastatic disease settings. Immunotherapy segments command the fastest expansion trajectory as PD-1/PD-L1 and CTLA-4 combinations displace single-agent targeted therapy in frontline metastatic protocols. Targeted therapy retains substantial volume in second-line and subsequent treatment stages where VEGF tyrosine kinase inhibitors maintain established efficacy profiles. Oral delivery mode dominates patient preference metrics and healthcare resource utilization models across outpatient oncology settings.
FDA accelerated approval designations and EMA conditional marketing authorizations compress commercialization timelines for novel renal cell carcinoma agents while demanding rigorous confirmatory trial execution. NMPA oncology review reforms in China and PMDA sakigake priority review status in Japan create parallel access pathways that reshape multinational launch sequencing strategies. Stakeholders must monitor biomarker-defined patient stratification advances and companion diagnostic co-development requirements that increasingly determine reimbursement positioning and prescribing algorithm integration across major markets.
Market Dynamics
The renal cell carcinoma therapeutic landscape is undergoing a fundamental protocol shift as dual checkpoint inhibition displaces single-agent VEGF inhibition in first-line metastatic settings, compressing the commercial runway for established tyrosine kinase inhibitors and forcing portfolio reconfiguration across oncology divisions.
Growth Catalysts
- PD-1/CTLA-4 combination protocols:Dual immunotherapy regimens are expanding addressable patient populations beyond prior VEGF-inhibitor boundaries, creating new prescription volume in previously underserved clear cell subtypes.
- FDA accelerated approval pathways:Compressed development timelines enable earlier commercial access for novel agents, reducing capital-at-risk duration for investigational programs targeting rare renal cell carcinoma mutations.
- Biomarker stratification advances:Companion diagnostic co-development with next-generation sequencing platforms is sharpening patient selection criteria and improving reimbursement positioning for premium therapies.
Market Restraints
- Confirmatory trial execution requirements:Accelerated approvals mandate rigorous post-marketing studies that strain clinical infrastructure and extend R&D cost recovery timelines.
- Reimbursement concentration in three markets:Premium therapy demand clusters in the United States, Germany, and Japan, leaving substantial geographic segments with constrained access to combination immunotherapy.
- VEGF inhibitor commoditization:Patent expirations and biosimilar entry are eroding pricing power for second-line targeted therapy portfolios.
Strategic Opportunities
- Adjuvant therapy expansion:Immunotherapy migration into earlier disease stages offers substantial volume growth beyond metastatic settings.
- NMPA oncology review reforms:China's streamlined approval processes enable earlier launch sequencing and market-building ahead of reimbursement negotiations.
- Real-world evidence integration:Electronic health record data platforms are enabling post-approval label expansion and differentiated value demonstration to payers.
Industry Challenges
- Immuno-oncology manufacturing complexity:Biologics production scale-up for combination therapies strains CMO capacity and requires specialized cold-chain infrastructure.
- Trial enrollment competition:Patient recruitment for renal cell carcinoma studies faces intensifying competition across multiple simultaneous checkpoint inhibitor programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renal Cell Carcinoma Market |
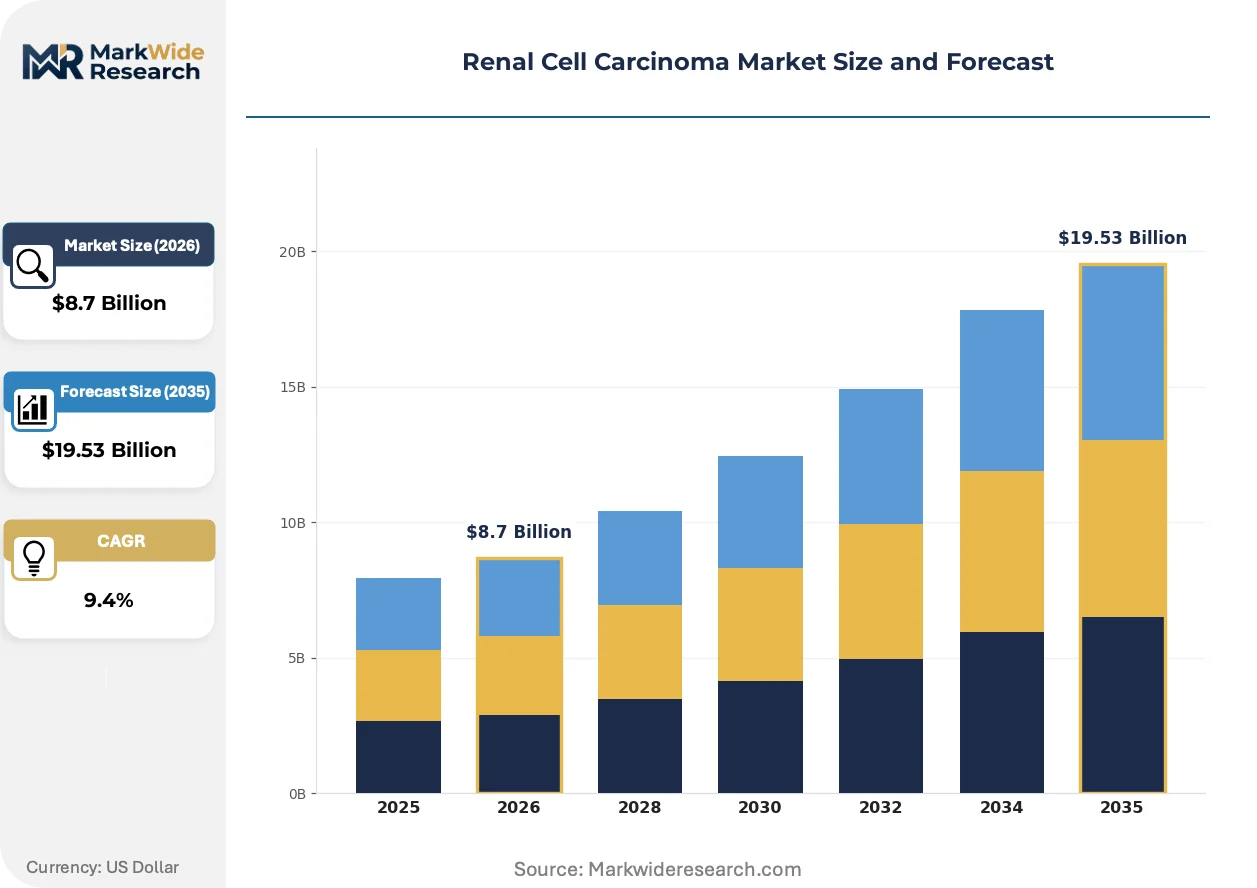
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Targeted Therapy, Immunotherapy, Chemotherapy, Radiation Therapy Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular End User: Oncology Clinics, Hospitals, Ambulatory Surgical Centers, Home Care Treatment Stage: Adjuvant, Neoadjuvant, Metastatic, Recurrence |
| Companies Covered | F. Hoffmann-La Roche Ltd., Pfizer Inc., Novartis AG, Bristol Myers Squibb Company, Exelixis, Inc., Merck & Co., Inc., AstraZeneca, Sanofi, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renal Cell Carcinoma Market Strategic Shifts
Renal cell carcinoma treatment paradigms are fragmenting across histology-specific pathways and combination architectures, with innovation concentrating in three distinct vectors that reshape competitive positioning and development priorities.
Triplet therapy regimens incorporating PD-1, CTLA-4, and VEGF pathway inhibition are advancing through late-stage development as investigators pursue deeper response rates. Academic medical centers in the United States and Germany are enrolling aggressively into these protocols. The clinical development landscape is bifurcating between dual-immunotherapy purists and VEGF-combination advocates, forcing sponsors to place parallel bets.
EMA conditional marketing authorizations are demanding more rigorous interim data packages than FDA accelerated approvals, creating divergent regulatory investment requirements. European sponsors are front-loading confirmatory trial infrastructure to meet post-authorization obligations. This friction most affects mid-cap developers with single-asset portfolios targeting niche renal cell carcinoma subpopulations.
Oncology clinics are consolidating purchasing decisions through integrated delivery networks and specialty pharmacy arrangements. Independent community practices are losing formulary influence to hospital outpatient departments with centralized pharmacy committees. This concentration is most pronounced in United States metropolitan markets where vertically integrated health systems control referral patterns.
Renal Cell Carcinoma Market Segmentation
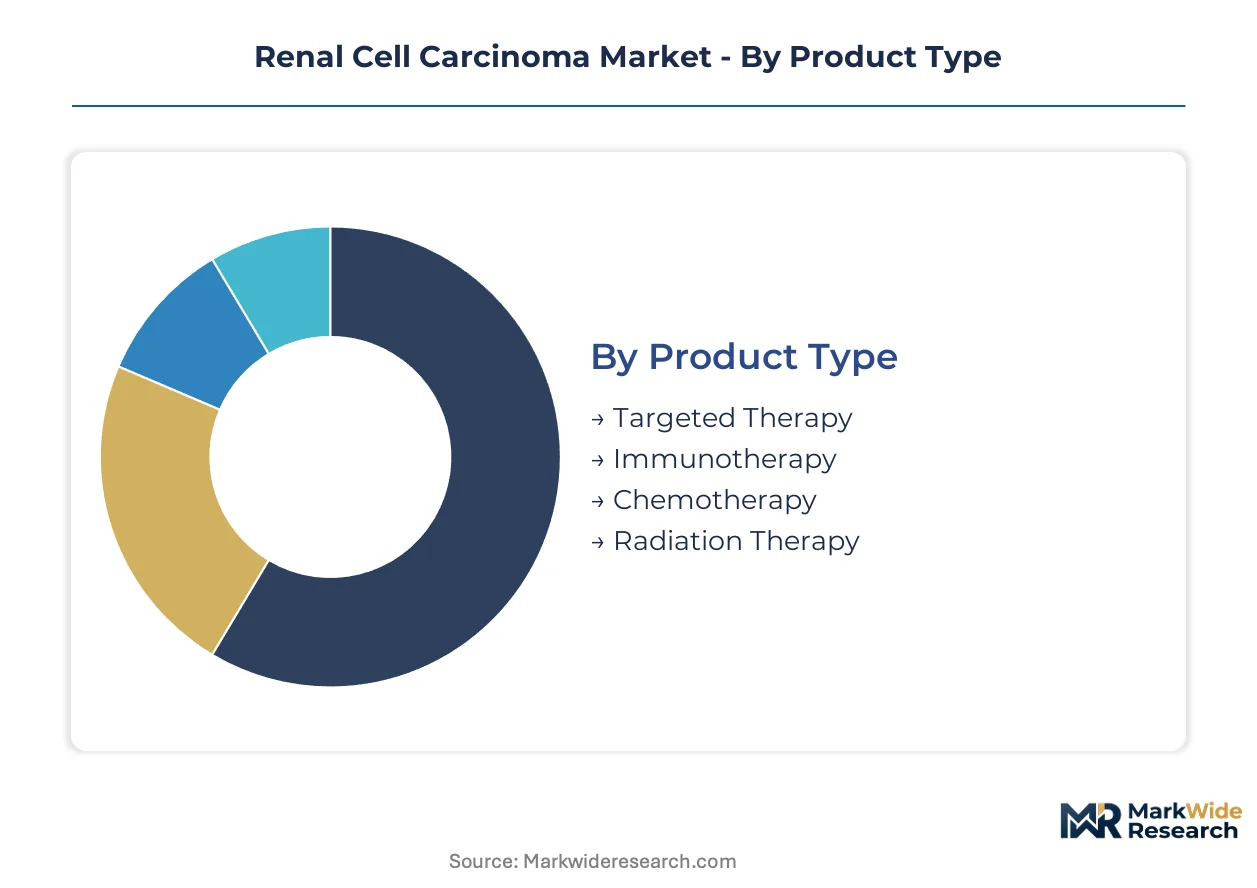
Renal cell carcinoma treatment protocols fragment across multiple dimensions that determine reimbursement pathways, prescribing authority, and manufacturing requirements. Each segmentation axis carries distinct commercial implications for portfolio positioning and channel strategy.
Product Type:
Channel distribution varies sharply by mechanism class, with immunotherapy biologics flowing through specialty pharmacy networks while oral targeted therapies reach patients via retail and mail-order channels.
- Targeted Therapy:Small-molecule VEGF tyrosine kinase inhibitors and mTOR inhibitors dominate second-line and subsequent treatment stages. Demand concentrates in Germany and Japan where pathology-driven prescribing algorithms favor sequenced targeted approaches after immunotherapy failure.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors and CTLA-4 antibodies command frontline metastatic protocols through intravenous infusion in hospital outpatient departments. FDA accelerated approvals and EMA conditional authorizations compress development timelines for novel combination regimens.
- Chemotherapy:Limited application in renal cell carcinoma due to intrinsic chemoresistance of clear cell histology; reserved for rare non-clear cell subtypes and salvage settings.
- Radiation Therapy:Stereotactic body radiation therapy addresses oligometastatic disease and palliative bone lesions; delivery ties to linear accelerator capacity in academic medical centers.
By volume, targeted therapy leads. By growth pace, immunotherapy is ahead.
Delivery Mode:
Patient preference and healthcare resource utilization models favor routes enabling outpatient administration without infusion center dependency.
- Oral:Tyrosine kinase inhibitors and mTOR inhibitors enable home-based administration with periodic monitoring. Japan's aging population drives particular preference for oral regimens that minimize clinic visits.
- Intravenous:Checkpoint inhibitors require infusion infrastructure but support higher reimbursement through buy-and-bill mechanisms in United States hospital outpatient departments.
- Subcutaneous:Emerging delivery innovation for select immunotherapy agents; reduces infusion chair time and appeals to integrated delivery networks seeking throughput efficiency.
- Intramuscular:Minimal role in renal cell carcinoma; limited to supportive care agents rather than disease-modifying therapy.
Oral administration captures the largest patient-days. Subcutaneous formulations are climbing the fastest as developers pursue differentiation.
End User:
Site-of-care economics and formulary control determine prescribing influence, with hospital outpatient departments consolidating purchasing decisions through centralized pharmacy committees.
- Oncology Clinics:Community-based practices drive initial diagnosis and treatment initiation but face declining formulary autonomy as integrated delivery networks absorb independent practices.
- Hospitals:Academic medical centers in the United States and Germany dominate enrollment into combination immunotherapy trials and triplet therapy protocols.
- Ambulatory Surgical Centers:Limited renal cell carcinoma role; primarily handles diagnostic biopsies rather than systemic therapy administration.
- Home Care:Oral targeted therapy administration supported by specialty pharmacy nursing services; expanding as payers push site-of-care migration.
Hospitals lead by revenue concentration. Oncology clinics are gaining share fastest through acquisition by vertically integrated health systems.
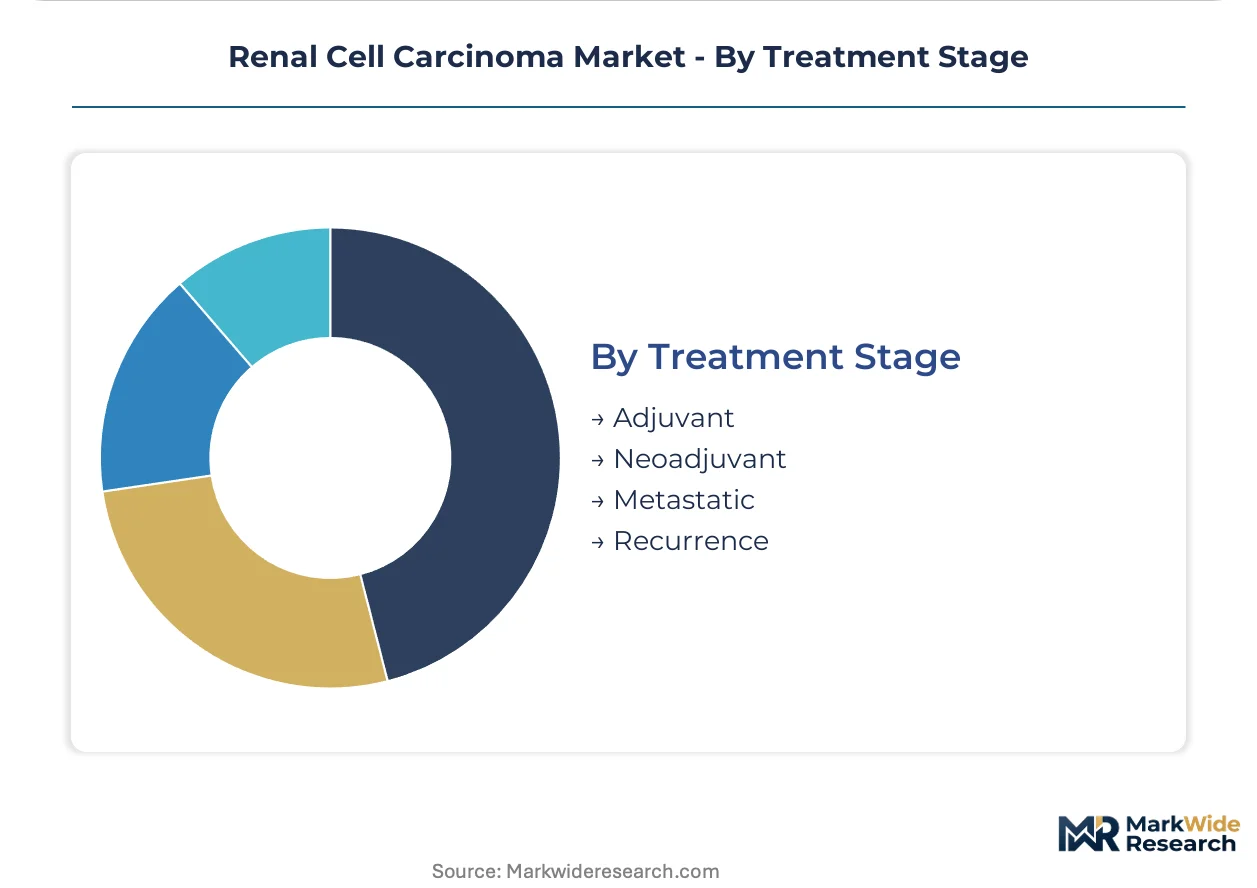
Treatment Stage:
Commercial opportunity is migrating from established metastatic indications toward earlier disease settings with larger addressable populations and longer treatment durations.
- Adjuvant:Post-surgical immunotherapy to prevent recurrence represents the largest volume expansion opportunity as checkpoint inhibitors pursue label expansion beyond metastatic disease.
- Neoadjuvant:Pre-operative systemic therapy to enable partial nephrectomy or treat micrometastatic disease; emerging clinical trial focus in United States academic centers.
- Metastatic:Established first-line and second-line protocols with defined reimbursement pathways; competitive intensity highest as dual checkpoint inhibition displaces prior standards.
- Recurrence:Salvage therapy after adjuvant or metastatic treatment failure; drives demand for sequencing data and resistance mechanism profiling.
Metastatic settings dominate current volume. Adjuvant therapy shows the steepest expansion trajectory as immunotherapy migrates earlier in the disease course.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renal cell carcinoma therapeutic trade flows toward net-importing markets with premium reimbursement frameworks, while manufacturing concentration in Switzerland and the United States shapes outbound supply patterns for active pharmaceutical ingredients and finished biologics.
United States
Oncology clinics in the United States absorb the majority of global checkpoint inhibitor production through hospital outpatient departments with centralized pharmacy committees. FDA accelerated approval pathways compress development timelines for novel combination regimens. The Greater Boston and San Francisco Bay Area clusters host the densest concentration of renal cell carcinoma clinical trial enrollment sites.
Germany
German pathology-driven prescribing algorithms favor sequenced targeted approaches after immunotherapy failure, sustaining demand for VEGF tyrosine kinase inhibitors. EMA conditional marketing authorizations require more rigorous interim data packages than FDA equivalents, shaping European launch sequencing. The Heidelberg-Mannheim corridor anchors academic medical center enrollment into triplet therapy protocols.
Japan
Japan's aging population drives particular preference for oral regimens that minimize clinic visits, supporting targeted therapy retention in later treatment lines. PMDA sakigake priority review status creates parallel access pathways that reshape multinational launch strategies. The Tokyo-Osaka axis concentrates pharmaceutical distribution infrastructure for biologics requiring specialized cold-chain handling.
China
Domestic demand for renal cell carcinoma therapeutics is expanding through NMPA oncology review reforms that streamline approval processes ahead of reimbursement negotiations. The country's national pharmaceutical regulator has accelerated review timelines for innovative oncology agents since 2023. Shanghai and Beijing host the primary clusters for multinational sponsor clinical operations and local partnership formation.
Switzerland
Swissmedic maintains stringent quality standards for biologics manufacturing that position Switzerland as a net exporter of active pharmaceutical ingredients to global markets. The Basel-Zurich corridor concentrates headquarters operations for major oncology developers with integrated manufacturing footprints. Roche's Genentech heritage anchors translational research linkages between Swiss operations and United States clinical networks.
Renal Cell Carcinoma Market Competitive Environment
Concentration sits with large-cap pharmaceutical developers possessing established PD-1 franchise depth and VEGF pathway expertise. The market structure exhibits tiered competition between integrated immunotherapy leaders, targeted therapy specialists, and emerging biotechs with single-asset portfolios. Three archetypes dominate: checkpoint inhibitor platform holders, tyrosine kinase inhibitor portfolio managers, and dual-mechanism combination sponsors. Capacity expansion into biologics manufacturing and strategic partnerships for companion diagnostic co-development represent the dominant competitive moves reshaping positioning.
Within the integrated pharmaceutical tier, Bristol Myers Squibb Company and Merck & Co., Inc. occupy positions defined by PD-1 checkpoint inhibitor platform breadth, while Pfizer Inc. anchors the targeted therapy vector through VEGF pathway alignment. These three entities exemplify the scale-driven end of competitive positioning, with organizational structures supporting parallel development across combination architectures. Novartis AG and Roche sit within the European contingent, representing Swiss-based manufacturing and research integration. AstraZeneca and Sanofi occupy mid-tier positions with oncology diversification strategies, while Bayer AG and Exelixis, Inc. exemplify targeted therapy specialization with narrower portfolio concentration.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd. |
| Pfizer Inc. |
| Novartis AG |
| Bristol Myers Squibb Company |
| Exelixis, Inc. |
| Merck & Co., Inc. |
| AstraZeneca |
| Sanofi |
| Bayer AG |
| Others |
Value Chain & Pricing Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorizations simultaneously gate supplier qualification and enable price differentiation for novel renal cell carcinoma agents, compressing development timelines for qualified developers while demanding rigorous confirmatory infrastructure that smaller entrants cannot fund. This regulatory dual-gate concentrates pricing power among large-cap pharmaceutical holders with parallel development capabilities across combination immunotherapy architectures.
Pricing Analysis
Hospital outpatient departments with centralized pharmacy committees anchor pricing negotiations for checkpoint inhibitor biologics through buy-and-bill mechanisms that sustain premium positioning against oral targeted therapies. Three-tier pricing structure across premium combination regimens, standard single-agent immunotherapy, and economy-tier VEGF inhibitors reflects reimbursement concentration in the United States, Germany, and Japan. Pricing pressure stems from biosimilar entry eroding second-line tyrosine kinase inhibitor margins. Community oncology clinics exhibit highest price sensitivity as integrated delivery networks consolidate formulary control.
Supply Chain Analysis
Specialized cold-chain infrastructure for biologics production concentrates active pharmaceutical ingredient manufacturing in Switzerland and the United States, with finished dose formulation anchored in the Basel-Zurich corridor and Greater Boston clusters. Monoclonal antibody production draws from mammalian cell culture capacity and single-use bioreactor systems, with chromatography resins and cell culture media as critical input dependencies. Single-source vulnerability sits with CMO capacity constraints for combination immunotherapy scale-up. Distribution runs through specialty pharmacy networks for biologics and retail channels for oral targeted therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual checkpoint inhibition is displacing single-agent VEGF inhibition as the first-line metastatic standard, forcing incumbents to defend against substitution by PD-1/CTLA-4 combination protocols that render legacy tyrosine kinase inhibitor portfolios commercially marginal.
For Market Incumbents: Secure adjuvant therapy label expansions ahead of metastatic saturation, and deepen manufacturing partnerships for triplet therapy components to offset CMO capacity constraints. Bristol Myers Squibb Company and Merck & Co., Inc. face pressure from emerging dual-mechanism sponsors combining VEGF pathway inhibition with checkpoint blockade. Backward integration into companion diagnostic co-development represents the critical lever for reimbursement positioning. For New Entrants and Emerging Players: Lead with neoadjuvant therapy protocols in United States academic medical centers, where enrollment competition remains less intense than metastatic first-line settings. China's NMPA oncology review reforms offer the most penetrable regulatory pathway for early commercial traction. Target hospital outpatient departments through integrated delivery network pharmacy committee engagement rather than fragmented community clinic access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biologics manufacturing as combination therapies strain single-use production infrastructure. Five-to-ten year viability favors developers with parallel bets across dual-immunotherapy and VEGF-combination architectures. Mid-cap specialists with single-asset renal cell carcinoma portfolios present acquisition targets contingent on confirmatory trial execution. Watch FDA accelerated approval withdrawal rates as the signal for regulatory risk repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Triplet therapy protocols in United States and Germany academic centers expand addressable patient populations beyond dual checkpoint inhibition. |
| Regulatory Approval Pathway | NMPA oncology review reforms enable earlier China launch sequencing ahead of reimbursement negotiations with national payers. |
| Licensing Agreement | Companion diagnostic co-development partnerships sharpen biomarker stratification and secure favorable formulary positioning. |
| Manufacturing Scale-Up | Biologics capacity expansion addresses CMO constraints for combination immunotherapy production and cold-chain distribution. |
| Pipeline Diversification | Adjuvant therapy indications extend treatment duration and capture larger patient populations than metastatic settings alone. |
Study Parameters
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers and refined through secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling triangulated with top-down pharmaceutical revenue estimates across the nine leading market participants.
Variance in projected values decomposes across treatment line, administration route, histology subtype, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth trajectories weighted by current revenue concentration. Forecast inputs incorporated biomarker-defined patient stratification advances and companion diagnostic adoption curves throughout the projection horizon.
Forecasts assume regulatory continuity in FDA accelerated approval and EMA conditional marketing authorization regimes; material policy shifts would require re-modeling of development timeline assumptions and commercial access sequences. Practitioners should keep alternative scenarios live as reimbursement concentration patterns and biosimilar entry timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Chronic Kidney Disease Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Kidney Transplant Market
Nephrology
Arteriovenous Fistula Treatment Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
US Dialysis Services Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Dialysis Centers Market
Nephrology
Nephrotic Syndrome Market
Nephrology
Global Dialyzer Market
Nephrology
Global Dialysis Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Kidney Stone Extraction Balloon Market