
 Drug-Induced Nephrotoxicity Treatment Market | 2026-2036
Drug-Induced Nephrotoxicity Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Drug-Induced Nephrotoxicity Treatment Market Analytics
The gap between premium biologic renal protective agents and commodity dialysis solutions is expanding as payers tighten formularies and providers seek cost-effective prophylaxis. Novartis AG leverages its oncology-nephrology crossover pipeline to sustain leadership in chemotherapy-induced kidney injury management. Sanofi anchors European hospital contracting through integrated supply agreements for aminoglycoside companion therapies. Pfizer Inc. competes on manufacturing scale, operating multi-site production of intravenous renal protective formulations.
Drug-induced nephrotoxicity treatment encompasses pharmacological and mechanical interventions designed to prevent, mitigate, or reverse acute kidney injury caused by xenobiotic compounds, with renal protective agents typically formulated as N-acetylcysteine derivatives or bicarbonate-buffered infusions targeting proximal tubule oxidative stress. The primary purpose is preserving glomerular filtration rate during high-risk therapeutic regimens including platinum-based chemotherapy and prolonged aminoglycoside courses. Dialysis solutions occupy the largest revenue pool due to recurrent consumable demand in acute settings, while renal protective agents represent the fastest-growing category as prophylactic protocols expand in oncology and infectious disease units. Intravenous delivery dominates hospital administration, though subcutaneous formulations are gaining traction in outpatient nephrology centers seeking to reduce infusion chair time.
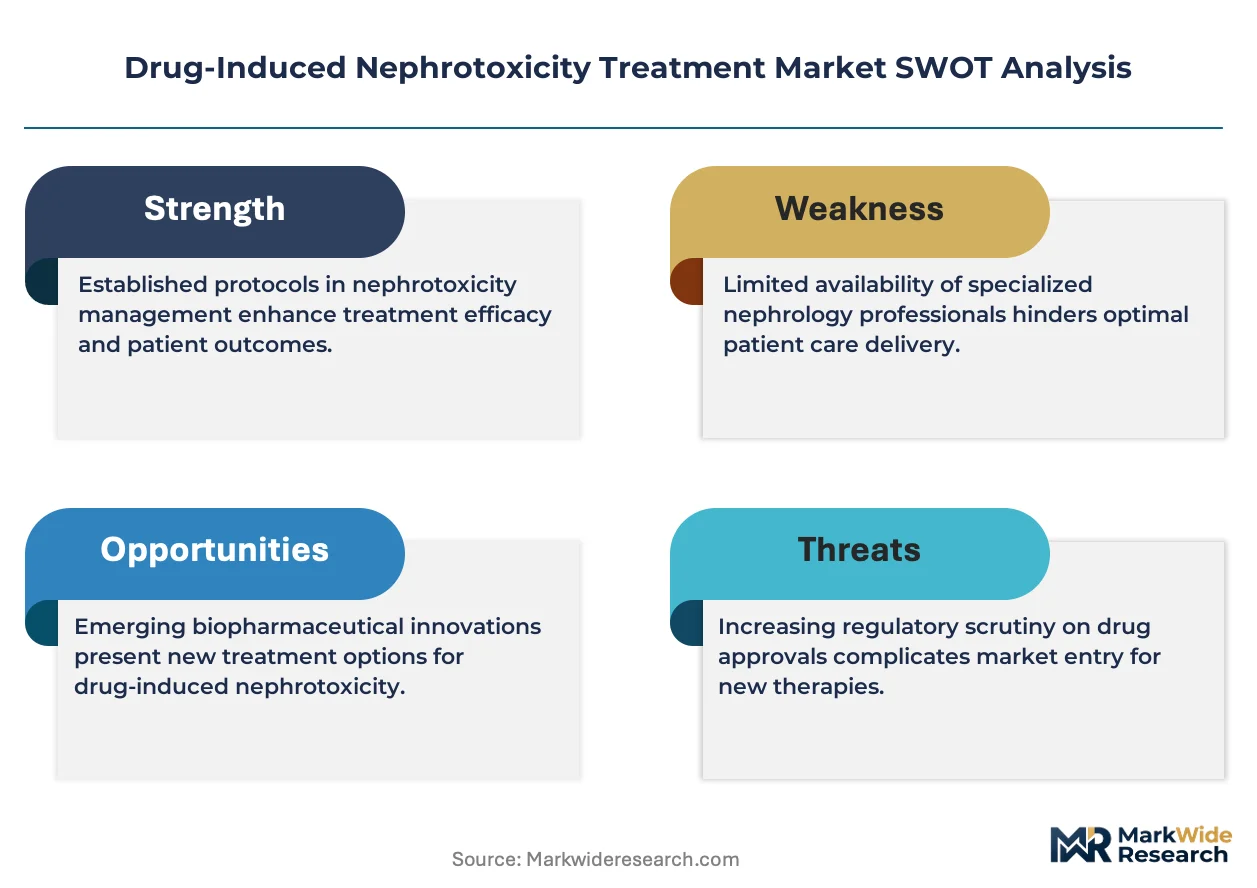
The FDA and EMA jointly shape market access through divergent pharmacovigilance requirements, with the FDA mandating renal function monitoring in drug labels and the EMA enforcing post-authorization safety studies for nephrotoxic compounds under the EU pharmacovigilance legislation. These frameworks elevate R&D costs but create protected markets for agents demonstrating superior kidney safety profiles in head-to-head trials. Stakeholders must monitor evolving payer evidence requirements as health technology assessment bodies tighten reimbursement criteria for prophylactic versus reactive treatment paradigms.
Market Dynamics
Hospital formularies are tightening reimbursement criteria for reactive dialysis interventions while expanding coverage for prophylactic renal protective protocols, compressing the window between diagnosis and preventive intervention.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage determinations now favor early renal protective administration in oncology infusion centers, accelerating protocol adoption ahead of chemotherapy cycles.
- FDA pharmacovigilance mandates:Expanded nephrotoxicity warning requirements for aminoglycoside and platinum-based labels are forcing institutional purchasing of companion protective agents.
- Oncology unit expansion:Hospital construction of dedicated cancer centers in tertiary care networks is embedding renal protection into standard chemotherapy workflows.
Market Restraints
- API supply concentration:N-acetylcysteine active pharmaceutical ingredient production clusters in Chinese chemical manufacturing zones, exposing formulators to export license volatility.
- EMA post-authorization requirements:Mandatory safety studies for nephrotoxic compounds extend commercialization timelines and elevate clinical trial costs for European market entry.
- Dialysis consumable lock-in:Established acute care contracts for bicarbonate-buffered solutions create switching friction against novel protective agent procurement.
Strategic Opportunities
- Outpatient nephrology centers:Subcutaneous formulation development targets ambulatory settings seeking to reduce infusion chair occupancy and capture shift-to-outpatient migration.
- Infectious disease prophylaxis:Extended aminoglycoside regimens for multidrug-resistant infections represent an underpenetrated indication beyond oncology.
- Integrated supply contracting:European hospital procurement coalitions are consolidating vendor relationships, rewarding manufacturers offering bundled nephrotoxic drug and protective agent packages.
Industry Challenges
- Biomarker validation timelines:Novel renal function indicators lack standardized regulatory acceptance, delaying endpoints for protective agent efficacy claims.
- Specialized compounding infrastructure:Intravenous bicarbonate-buffered formulations require cleanroom investments that strain mid-tier hospital pharmacy capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug-Induced Nephrotoxicity Treatment Market |
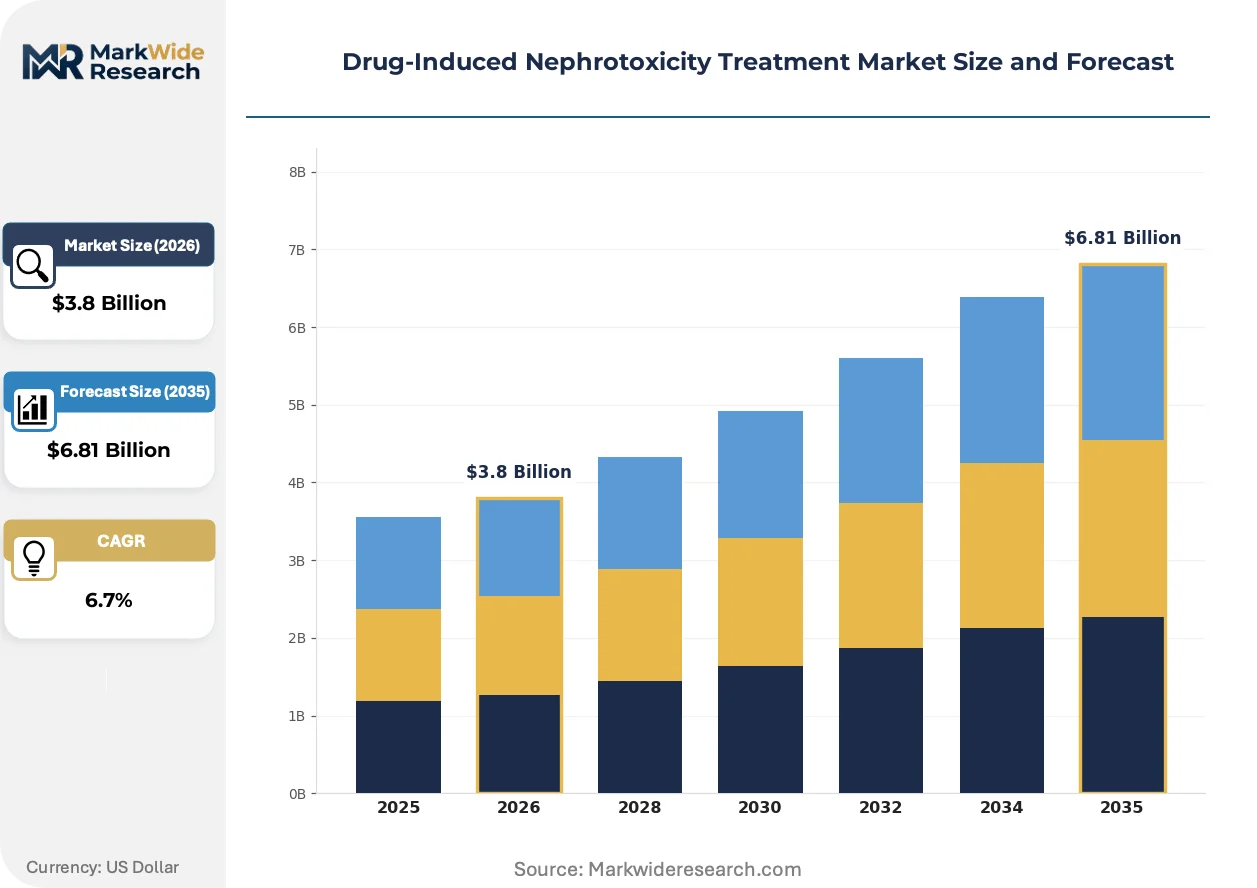
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Aminoglycosides, NSAIDs, Chemotherapy Agents, Antivirals Product Type: Dialysis Solutions, Renal Protective Agents, Rehydration Solutions, Antioxidants End User: Hospitals, Outpatient Clinics, Specialized Nephrology Centers, Research Laboratories Delivery Mode: Intravenous, Oral, Subcutaneous, Inhalation |
| Companies Covered | Amgen Inc., Sanofi, Novartis AG, Johnson & Johnson, Bayer AG, AstraZeneca, F. Hoffmann-La Roche Ltd, Merck & Co. Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug-Induced Nephrotoxicity Treatment Market Evolving Landscape
Preventive pharmacology is displacing reactive intervention across acute kidney injury management, with formulation science and delivery mechanisms converging to compress treatment initiation windows.
Subcutaneous depot formulations of renal protective agents are modularizing outpatient care pathways. Oncology centers in the United States are piloting these alternatives to reduce infusion chair utilization. The technology is modularizing site-of-care economics by enabling administration in ambulatory settings previously restricted to hospital-based intravenous delivery.
REACH authorization requirements for nephrotoxic pharmaceutical intermediates are tightening supply chain documentation obligations across European manufacturing. Chemical suppliers must now demonstrate environmental fate testing for renal stress-inducing compounds. Formulators serving EMA-regulated markets are responding by qualifying alternative synthetic routes that bypass restricted substance classifications.
Hospital purchasing committees are consolidating nephrotoxicity risk management into bundled oncology contracts. Single-source agreements now specify protective agent inclusion alongside chemotherapy procurement, displacing separate therapeutic category bidding. This concentration is most pronounced in United States academic medical centers where pharmacy and therapeutics committees wield centralized formulary control.
Drug-Induced Nephrotoxicity Treatment Market Segmentation
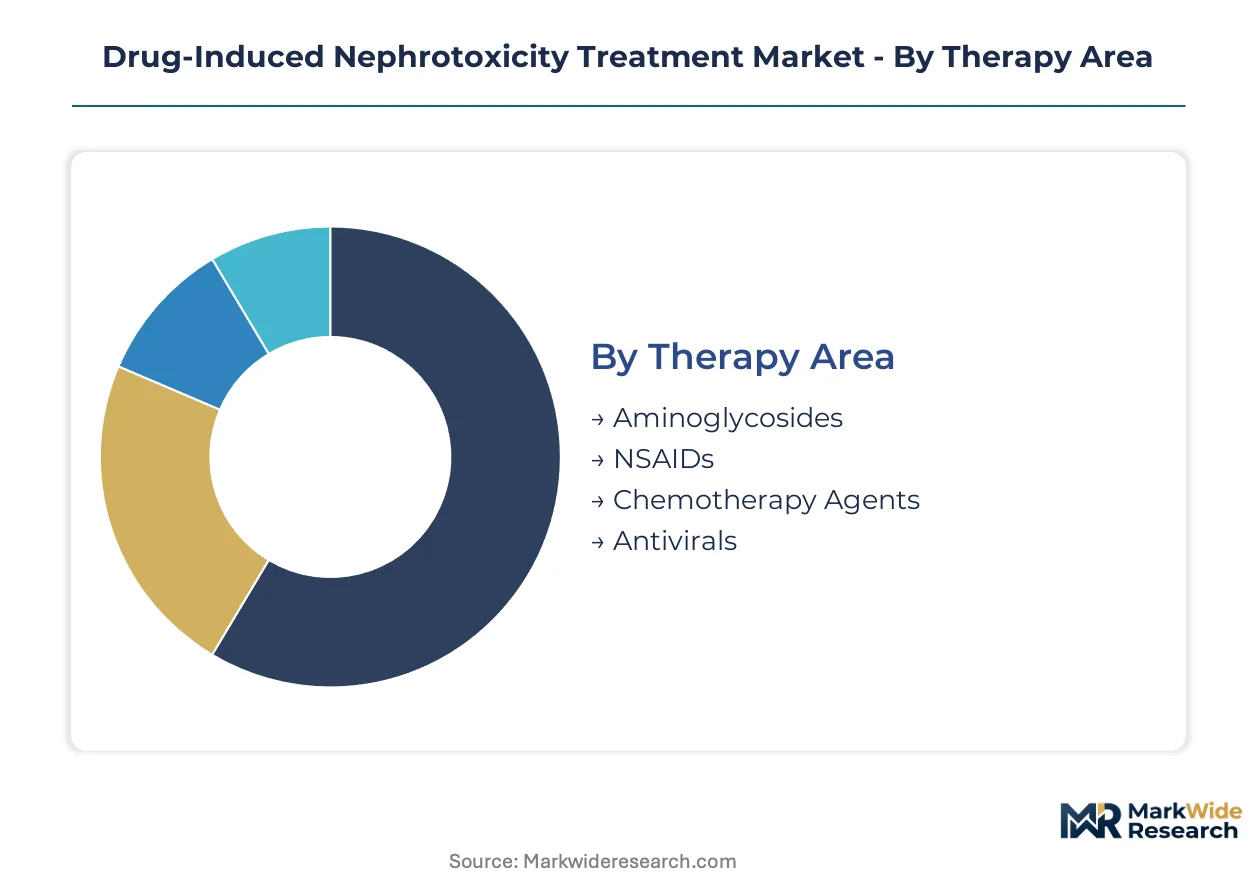
Segmentation in this market reveals how procurement decisions bifurcate between acute intervention and preventive protocols. Hospital formulary committees now evaluate each category through distinct economic lenses—consumable recurring costs versus prophylactic episode-based pricing.
Therapy Area:
Supply concentration for companion protective agents varies sharply by underlying nephrotoxic drug class, with platinum compound co-therapies commanding premium formulation investments.
- Chemotherapy Agents:Cisplatin and carboplatin regimens drive demand for N-acetylcysteine derivatives with bicarbonate buffering. Oncology infusion centers in the United States embed these protective protocols into Medicare-reimbursable chemotherapy bundles.
- Aminoglycosides:Gentamicin and tobramycin courses for multidrug-resistant infections require companion renal protection in extended regimens. European hospital procurement coalitions increasingly specify bundled aminoglycoside-protective agent contracts.
- NSAIDs:Chronic high-dose ibuprofen and ketorolac use in perioperative settings generates reactive protective agent demand.
- Antivirals:Tenofovir and acyclovir nephrotoxicity management concentrates in HIV and transplant specialty centers.
Today's leader: Chemotherapy Agents. Tomorrow's challenger: Aminoglycosides.
Product Type:
Cost tier differentiation separates commodity consumables from premium biologic formulations, with reimbursement margins determining hospital procurement prioritization.
- Dialysis Solutions:Bicarbonate-buffered replacement fluids dominate acute kidney injury management through recurrent consumable demand. Hospital purchasing committees lock into multi-year supply agreements that resist novel protective agent displacement.
- Renal Protective Agents:N-acetylcysteine derivatives and cysteamine-based formulations target proximal tubule oxidative stress. Subcutaneous depot developments are expanding outpatient eligibility and reducing infusion chair dependency.
- Rehydration Solutions:Isotonic crystalloid infusions support renal perfusion in peri-nephrotoxic drug administration.
- Antioxidants:Ascorbic acid and alpha-lipoic acid adjuncts occupy niche complementary therapy positions.
The volume anchor: Dialysis Solutions. The margin expansion path: Renal Protective Agents.
End User:
Customer type stratification tracks the migration of nephrotoxicity management from inpatient emergency response to ambulatory prevention.
- Hospitals:Tertiary care centers integrate renal protection into oncology and infectious disease workflows through pharmacy and therapeutics committee oversight. CMS reimbursement policies favor early intervention protocols in these institutional settings.
- Specialized Nephrology Centers:Dedicated kidney care facilities pioneer subcutaneous administration models and biomarker-guided dosing. These centers capture shift-to-outpatient migration through reduced chair time protocols.
- Outpatient Clinics:Community oncology practices seek simplified protective agent administration for low-risk regimens.
- Research Laboratories:Academic medical centers conduct biomarker validation studies for novel renal function indicators.
Current procurement concentration: Hospitals. Ambulatory growth vector: Specialized Nephrology Centers.
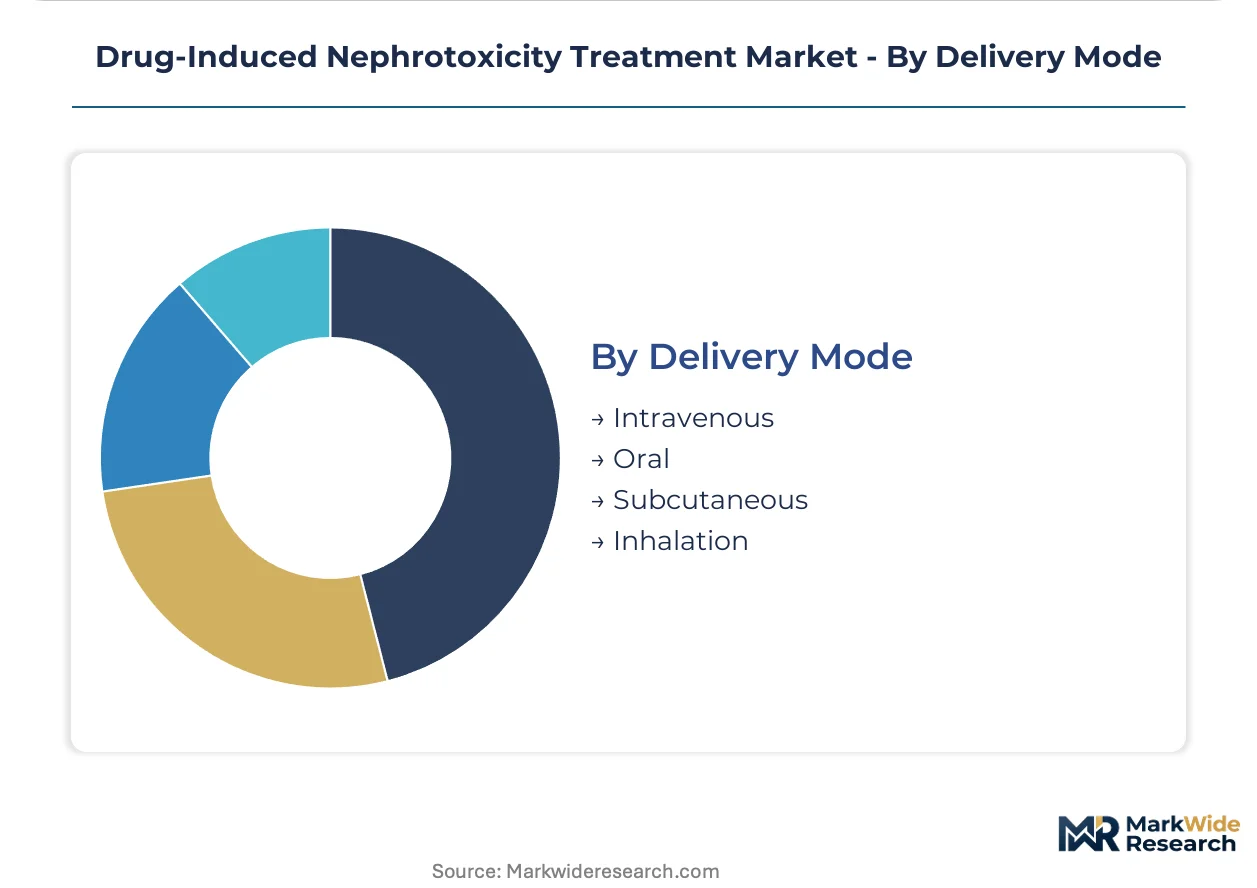
Delivery Mode:
Application requirements dictate route selection, with bioavailability and onset speed determining clinical utility across acute versus preventive use cases.
- Intravenous:Direct vascular administration ensures rapid systemic distribution for acute kidney injury intervention. Hospital pharmacies maintain cleanroom compounding infrastructure for bicarbonate-buffered formulations.
- Subcutaneous:Depot formulations enable ambulatory administration through sustained-release pharmacokinetics. United States oncology pilots demonstrate infusion chair utilization reductions.
- Oral:N-acetylcysteine tablets serve prophylactic protocols in low-risk outpatient settings.
- Inhalation:Nebulized delivery targets pulmonary-renal syndrome adjunctive management in specialized indications.
Established standard: Intravenous. Steepest expansion trajectory: Subcutaneous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement patterns in Germany diverge sharply from those in the United States, with European integrated supply agreements favoring bundled contracts while American institutions prioritize Medicare-reimbursable early intervention protocols.
United States
Oncology infusion centers in Texas and California drive demand for N-acetylcysteine derivatives as CMS coverage determinations embed renal protection into chemotherapy bundles. The FDA mandates expanded nephrotoxicity warnings on aminoglycoside and platinum-based drug labels, forcing institutional purchasing of companion protective agents. Boston's academic medical centers pioneer subcutaneous depot administration pilots to reduce infusion chair occupancy.
Germany
Hospital procurement coalitions in North Rhine-Westphalia consolidate vendor relationships for bundled nephrotoxic drug and protective agent packages. The EMA enforces post-authorization safety studies under EU pharmacovigilance legislation, extending commercialization timelines for novel entrants. Bavaria's tertiary care networks integrate renal protection into standard infectious disease workflows through pharmacy committee oversight.
China
API production concentration in Jiangsu and Zhejiang provinces exposes formulators to export license volatility for N-acetylcysteine manufacturing. The NMPA tightens pharmacovigilance documentation for nephrotoxic pharmaceutical intermediates, elevating supply chain compliance costs. Shanghai's oncology centers expand dedicated cancer center construction, embedding renal protection protocols into chemotherapy administration.
Japan
Specialized nephrology facilities in Tokyo and Osaka pioneer biomarker-guided dosing for renal protective agents. The PMDA requires renal function monitoring in drug labels for platinum-based chemotherapy, accelerating prophylactic protocol adoption. Nagoya's hospital pharmacies invest in cleanroom infrastructure for intravenous bicarbonate-buffered formulation compounding.
United Kingdom
London's academic medical centers conduct validation studies for novel renal function indicators to support protective agent efficacy claims. Health technology assessment bodies tighten reimbursement criteria for prophylactic versus reactive treatment paradigms. The Midlands region concentrates dialysis solution manufacturing through multi-year hospital supply agreements that resist novel protective agent displacement.
Drug-Induced Nephrotoxicity Treatment Market Competitive Landscape
Top-tier vendors anchor integrated oncology-nephrology portfolios, while mid-cap specialists concentrate on formulation delivery innovations. The market structure stratifies across three tiers: diversified pharmaceutical conglomerates with cross-therapeutic pipelines, regional hospital supply contractors with bundled service capabilities, and niche formulation developers pursuing subcutaneous depot technologies. Two dominant competitive moves are reshaping positioning: strategic partnerships between API suppliers and finished dose formulators to secure N-acetylcysteine supply chains, and geographic expansion into outpatient nephrology centers to capture ambulatory care migration.
Within the diversified pharmaceutical tier, Novartis AG, Sanofi, and Pfizer Inc. occupy positions exemplifying distinct competitive archetypes. Novartis represents the oncology-nephrology crossover specialist leveraging integrated therapeutic development. Sanofi anchors European hospital contracting through supply agreement consolidation. Pfizer exemplifies manufacturing scale advantages across multi-site intravenous formulation production.
| Leading Market Players |
|---|
| Amgen Inc. |
| Sanofi |
| Novartis AG |
| Johnson & Johnson |
| Bayer AG |
| AstraZeneca |
| F. Hoffmann-La Roche Ltd |
| Merck & Co. Inc. |
| Pfizer Inc. |
| Others |
Value Network & Pricing Analysis
Cleanroom pharmacy technicians in the United States and Germany command wage premiums that compress margin spreads between premium biologic formulations and commodity dialysis solutions. Labor-cost differentials across these specialized compounding hubs directly shape three-tier pricing stratification, with European hospital procurement coalitions extracting volume discounts that American Medicare-reimbursable centers cannot match.
Pricing Analysis
Bundled oncology-protective agent contracts versus unbundled separate-category purchasing splits the pricing landscape. Contract-based long-term offtake dominates hospital procurement, with price differentiation resting on FDA certification tier and geographic delivery cost. Cost compression in standard-tier N-acetylcysteine derivatives is intensifying because API supply volatility from Chinese chemical zones forces formulators to absorb margin erosion. Community oncology practices in outpatient settings exhibit highest price sensitivity, while tertiary academic medical centers with centralized formulary control demonstrate lowest sensitivity due to bundled reimbursement structures.
Supply Chain Analysis
REACH authorization requirements for nephrotoxic pharmaceutical intermediates gate European market entry through environmental fate documentation. API production concentrates in China, India, and Germany, with finished dose formulation drawing from N-acetylcysteine derivatives, bicarbonate buffer compounds, and cysteamine-based active ingredients. Single-source vulnerability in Jiangsu and Zhejiang chemical manufacturing zones exposes formulators to export license disruption. Distribution runs through hospital pharmacy wholesalers and direct-to-institution contracting for large health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug-induced nephrotoxicity treatment market functions as a stable compounder, with Medicare reimbursement policy locking in prophylactic protocol adoption as a durable demand floor. Chronic disease burden expansion and oncology unit construction sustain predictable volume growth.
For Market Incumbents: Anticipate API supply disruption by securing backward integration into N-acetylcysteine manufacturing or captive supply agreements with qualified Chinese chemical producers. Expand cleanroom compounding capacity in Texas and California oncology corridors to capture CMS-reimbursable early intervention volume. Counter subcutaneous depot formulation entrants by accelerating intravenous-to-ambulatory administration pathway development. For New Entrants and Emerging Players: FDA expanded pharmacovigilance mandates for nephrotoxic drug labeling in the United States open a window for companion protective agent positioning alongside aminoglycoside and platinum-based chemotherapy portfolios. Target infectious disease prophylaxis for multidrug-resistant infections as the most penetrable indication beyond oncology saturation. Pursue European hospital procurement coalition qualification through REACH-compliant synthetic route documentation and bundled contract packaging. For Investors and Strategic Acquirers: Diversified pharmaceutical conglomerates with oncology-nephrology crossover pipelines are the most active acquirer in this space, seeking subcutaneous depot formulation capabilities to complement existing intravenous infrastructure. The market supports long-term viability through persistent regulatory tailwinds and reimbursement policy entrenchment. Acquisition target archetypes include niche formulation developers with ambulatory administration patents and qualified API-to-finished-dose vertical integration. Monitor biomarker validation study completions at London academic medical centers as the signal to watch for protective agent efficacy claim inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Depot Formulation Development | Enables ambulatory administration in United States oncology centers seeking reduced infusion chair utilization. |
| REACH-Compliant Synthetic Route Qualification | Secures European market access through ECHA environmental fate documentation for nephrotoxic intermediates. |
| Integrated Supply Agreement Consolidation | Captures German hospital procurement coalition volume through bundled nephrotoxic drug and protective agent packaging. |
| Cleanroom Compounding Infrastructure Expansion | Supports bicarbonate-buffered intravenous formulation production for Medicare-reimbursable chemotherapy bundles. |
| Biomarker-Guided Dosing Platform Investment | Positions specialized nephrology centers in Tokyo and Osaka for personalized renal protection protocols. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined through bottom-up and top-down triangulation. Primary interviews engaged hospital pharmacy directors, oncology infusion center administrators, formulary committee chairs, regulatory affairs specialists at API manufacturers, and procurement managers at European hospital coalitions. Secondary validation drew from FDA pharmacovigilance databases, EMA post-authorization safety study registries, CMS coverage determination filings, and hospital supply contract documentation.
Granularity-level modeling deployed therapy area, product type, end user, and delivery mode dimensions at the country level, with regional regulatory clusters cross-referenced against reimbursement policy variations. CAGRs were derived through segment-level volume and value build-ups across the projection horizon. Forecast inputs incorporated oncology unit construction pipelines, Medicare reimbursement rulemaking trajectories, and REACH authorization timelines for pharmaceutical intermediates.
Revisions become necessary when biomarker validation studies achieve regulatory acceptance or when API export licensing regimes in Chinese chemical manufacturing zones shift materially. Forecasts reflect assumptions about prophylactic protocol adoption rates and bundled contract penetration that could diverge if health technology assessment bodies alter reimbursement criteria. A model refresh is warranted upon material change in FDA pharmacovigilance labeling requirements or EMA post-authorization safety study mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
US Dialysis Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
End Stage Renal Disease Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Global Hepatorenal Syndrome Treatment Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Blood Dialyzer Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
US Dialysis Services Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Global Hemodialysis Market
Nephrology
Radiation Nephropathy Treatment and Management Market
Nephrology
Renal Anemia Treatment Market
Nephrology
Kidney Transplant Market
Nephrology
US Continuous Renal Replacement Therapy Market