
 Radiation Nephropathy Treatment and Management Market | 2026-2036
Radiation Nephropathy Treatment and Management Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Nephropathy Treatment and Management Market Analytics
ISO 14155 compliance for clinical investigation of medicinal products is collapsing the field of credible trial sponsors in radiation nephropathy therapeutics. Pfizer leverages its global oncology infrastructure to sustain Phase II programs across multiple sites. Daiichi Sankyo anchors its position through deep expertise in renoprotective small molecules. Teva Pharmaceutical Industries competes on injectable formulation scale, particularly in intravenous delivery modes where manufacturing complexity limits new entrants.
Radiation nephropathy treatment and management encompasses pharmaceutical, biologic, device, and nutraceutical interventions designed to prevent, mitigate, or reverse kidney damage resulting from ionizing radiation exposure, typically administered at cumulative doses exceeding 20 Gy to the renal bed. The primary purpose is preserving glomerular filtration rate in cancer patients receiving abdominal or pelvic radiotherapy, thereby reducing dialysis dependency and improving progression-free survival. Pharmaceuticals dominate current revenue, reflecting established reimbursement for ACE inhibitors and statins in renoprotective protocols, while biologics represent the fastest-expanding margin pool as monoclonal antibodies targeting TGF-beta signaling advance through late-stage trials. Devices lag in penetration due to limited interventional options, though renal perfusion monitoring systems are gaining traction in tertiary hospitals.
FDA post-market surveillance requirements and EMA's MDR framework for combination product classification shape trial design and commercial access timelines across North America and Europe. The EPA's radiation exposure guidelines further constrain off-label use of radioprotective agents in non-oncology settings. India's CDSCO has tightened import licensing for biologic renoprotectives, redirecting regional supply toward domestic manufacturers. Stakeholders must monitor evolving reimbursement codes for radiation-induced kidney injury as a distinct diagnostic category versus bundled oncology payments.
Market Dynamics
ISO 14155 compliance requirements for clinical investigations are compressing the field of credible trial sponsors, forcing pharmaceutical developers to consolidate site networks and accelerate protocol standardization to maintain investigational timelines.
Growth Catalysts
- EMA MDR framework:The Medical Device Regulation's clarified classification criteria for combination products is streamlining market access pathways for renal perfusion monitoring systems integrated with renoprotective drug delivery.
- Oncology center expansion:Tertiary hospitals in the United States are establishing dedicated radiation nephropathy management units, creating institutional demand for comprehensive renoprotective protocols.
- TGF-beta signaling inhibitors:Monoclonal antibodies targeting fibrotic pathways in late-stage development are attracting investigator-initiated trial funding from academic medical centers.
Market Restraints
- Biologic manufacturing concentration:Contract development and manufacturing organizations in Switzerland and Germany control critical fill-finish capacity for intravenous renoprotective formulations, creating single-source vulnerability.
- EPA radiation exposure guidelines:The Environmental Protection Agency's restrictive thresholds for radioprotective agent deployment outside oncology settings block expansion into industrial and military applications.
- Reimbursement bundling:Medicare's consolidated payment structures for radiation therapy episodes obscure distinct coding for radiation-induced kidney injury management, compressing provider margins.
Strategic Opportunities
- Renal perfusion monitoring:Integration of continuous hemodynamic sensors with automated ACE inhibitor titration systems creates real-time renoprotection platforms for high-dose radiotherapy protocols.
- CDSCO domestic manufacturing incentives:India's tightened import licensing for biologic renoprotectives redirects regional supply toward local producers with established GMP infrastructure.
- Telemedicine-enabled follow-up:Remote monitoring of glomerular filtration rate trajectories post-radiotherapy reduces tertiary hospital burden while maintaining protocol adherence.
Industry Challenges
- ISO 14155 investigator certification:The collapsing pool of qualified principal investigators for radiation nephropathy trials extends site activation timelines and inflates per-patient costs.
- Legacy EHR integration:Radiation oncology information systems lack standardized APIs for nephrology workflow modules, forcing manual data reconciliation between departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Nephropathy Treatment and Management Market |
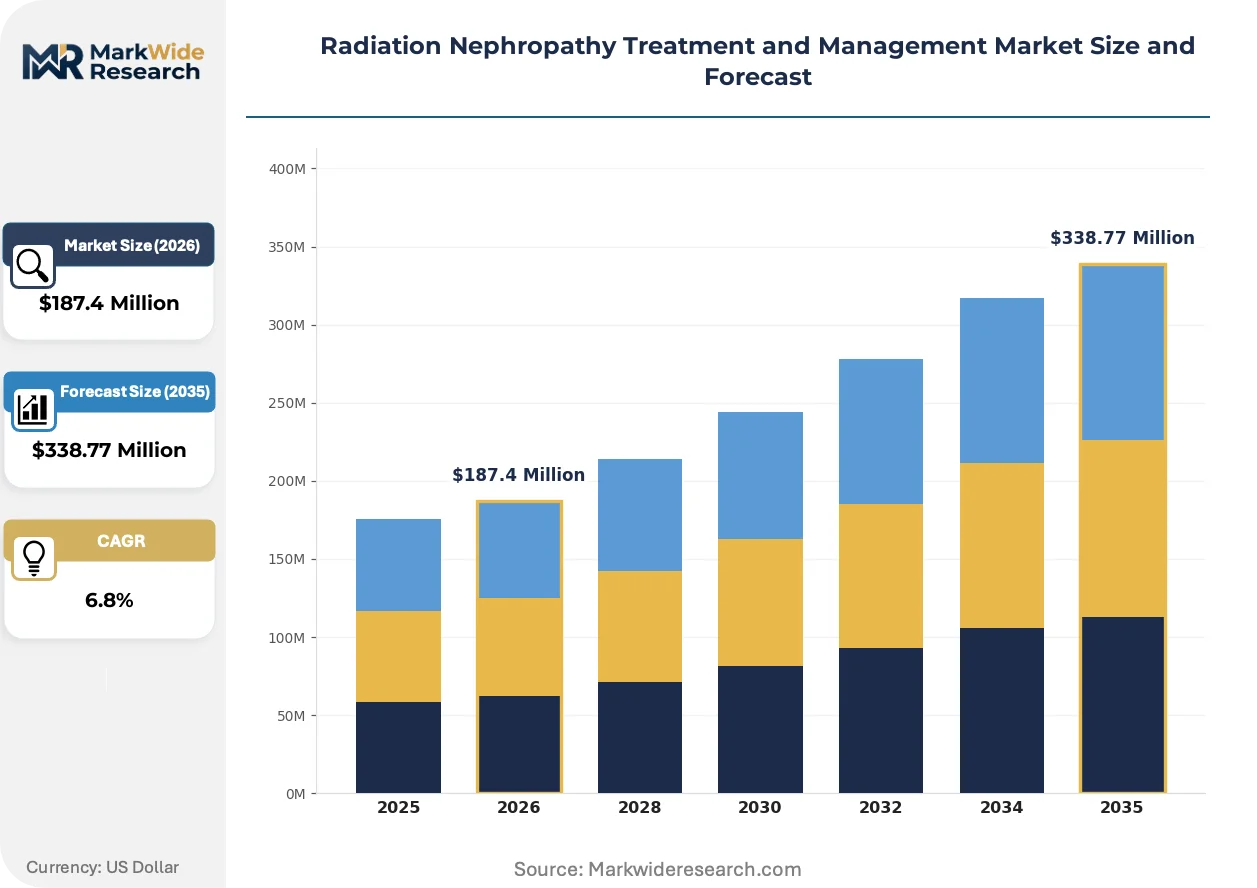
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Biologics, Devices, Nutraceuticals Delivery Mode: Oral, Injectable, Topical, Intravenous End User: Hospitals, Clinics, Homecare, Research Labs Treatment Approach: Conventional, Supportive, Experimental, Palliative |
| Companies Covered | Daiichi Sankyo, GlaxoSmithKline, Teva Pharmaceutical Industries, Pfizer, Par Pharmaceutical Companies, Silvergate Pharmaceuticals, Amgen, F. Hoffmann-La Roche, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Nephropathy Treatment and Management Market Evolving Landscape
Renal protection technology is splitting into two distinct development tracks: precision biomarker-guided interventions for high-value oncology segments and scalable generic protocols for community hospital settings.
Continuous glomerular filtration rate monitoring systems using implanted microsensors are bifurcating the renal perfusion device category. Academic medical centers in the United States and Germany are piloting these systems in abdominal radiotherapy protocols with intensive nephrology co-management. The technology is bifurcating the market into premium real-time monitoring installations versus conventional laboratory-based surveillance, compressing margins for standalone diagnostic equipment.
EMA's Medical Device Regulation recast for combination products is forcing pharmaceutical sponsors to reclassify drug-device renoprotective delivery systems. Manufacturers must now submit technical documentation for integrated perfusion monitors and infusion pumps alongside drug master files. Late-stage trial sponsors are responding by separating device and drug regulatory strategies, delaying synchronized launches by twelve to eighteen months.
Hospital procurement departments are consolidating radiation nephropathy management into bundled oncology service contracts rather than standalone therapeutic categories. This purchasing consolidation pressures pharmaceutical vendors to demonstrate total cost-of-care reductions across dialysis avoidance and progression-free survival metrics. The United Kingdom's National Health Service and several integrated delivery networks in California are most advanced in this contract restructuring.
Radiation Nephropathy Treatment and Management Market Segmentation
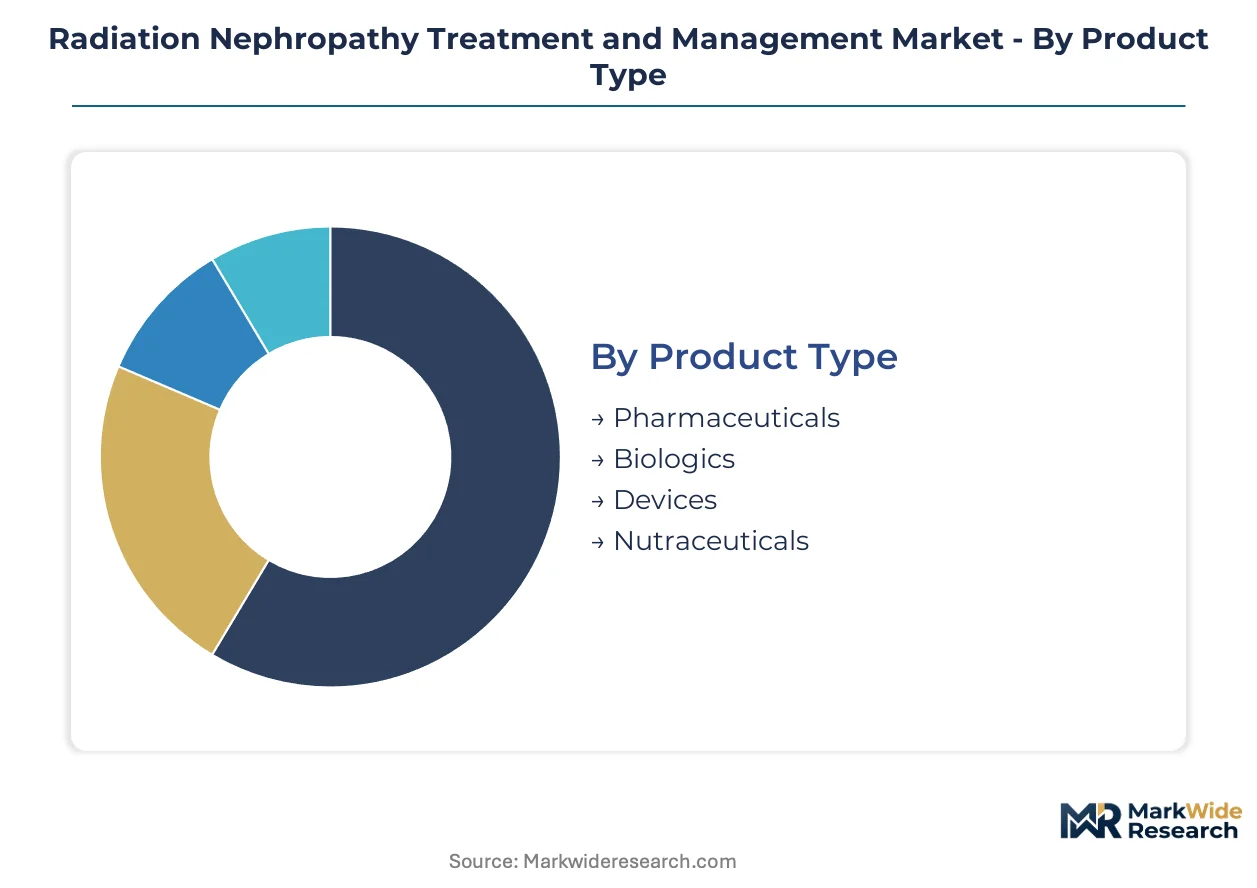
Segmentation in radiation nephropathy treatment reveals distinct procurement patterns across institutional buyers and reimbursement pathways. Product type and delivery mode classifications determine regulatory submission routes, while end-user stratification exposes divergent price sensitivity between tertiary hospitals and community clinics.
Product Type:
Domestic manufacturing dominates pharmaceuticals and nutraceuticals, while biologics and advanced devices rely heavily on imported supply chains from Switzerland and Germany.
- Pharmaceuticals:ACE inhibitors and statins constitute the established revenue base, with formulations manufactured primarily in domestic facilities across the United States and India. Medicare reimbursement for these agents in renoprotective protocols has matured fastest in US oncology centers, though pricing pressure from bundled payment structures compresses margins.
- Biologics:Monoclonal antibodies targeting TGF-beta signaling pathways represent the innovation frontier, with clinical-grade material sourced from contract manufacturers in Basel and Munich. CDSCO's tightened import licensing for India redirects regional supply toward domestic producers with GMP certification, fragmenting sourcing strategies.
- Devices:Renal perfusion monitoring systems integrate with infusion pumps under EMA MDR combination product rules.
- Nutraceuticals:Antioxidant formulations and renal support supplements occupy the price-sensitive outpatient segment.
Pharmaceuticals hold the largest share; momentum sits with biologics.
Delivery Mode:
Cost tier stratification separates premium intravenous formulations from commoditized oral generics, with manufacturing complexity determining competitive moats.
- Intravenous:Requires sterile fill-finish capacity concentrated in Swiss and German CDMOs, creating single-source vulnerability for late-stage trial sponsors. Teva Pharmaceutical Industries competes on manufacturing scale here, where ISO 14155 compliance costs exclude smaller entrants.
- Injectable:Subcutaneous and intramuscular routes serve outpatient clinic settings, with prefilled syringe formats gaining preference in US integrated delivery networks for nursing efficiency.
- Oral:Generic ACE inhibitors and statins dominate volume, with Indian domestic manufacturers capturing regional share under CDSCO incentives.
- Topical:Limited application for radiation dermatitis adjacent to nephropathy protocols; marginal commercial presence.
Intravenous commands premium pricing; oral formulations expand most quickly into community hospital settings.
End User:
Application intensity varies sharply, with tertiary hospitals managing complex multi-agent protocols while homecare remains underpenetrated for monitoring-dependent therapies.
- Hospitals:Tertiary oncology centers in the United States and Germany pilot continuous GFR monitoring with implanted microsensors, requiring intensive nephrology co-management. These institutions establish dedicated radiation nephropathy management units, driving demand for comprehensive renoprotective platforms.
- Clinics:Community oncology practices rely on laboratory-based surveillance and oral pharmaceutical protocols, constrained by limited interventional capabilities and narrower reimbursement.
- Homecare:Telemedicine-enabled GFR monitoring post-radiotherapy reduces tertiary hospital burden while maintaining protocol adherence.
- Research Labs:Academic medical centers sponsor investigator-initiated trials for TGF-beta inhibitors, accessing NIH and foundation funding streams.
Hospitals absorb the majority of value; homecare shows the steepest expansion trajectory as remote monitoring technology matures.
Treatment Approach:
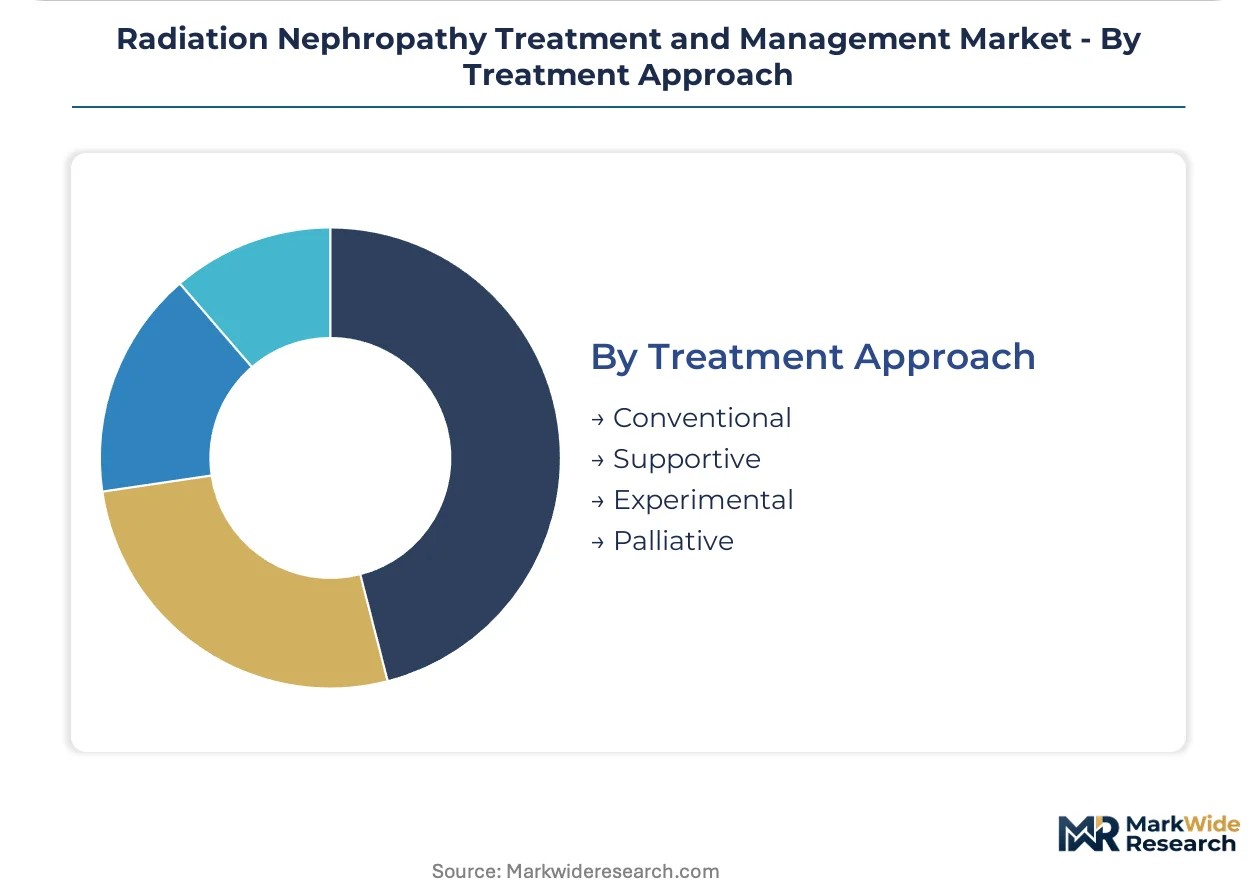
Maturity stratification separates evidence-based conventional protocols from experimental agents navigating ISO 14155 compliance bottlenecks.
- Conventional:ACE inhibitor-based renoprotection with established clinical guidelines dominates US and European practice, supported by mature reimbursement coding.
- Supportive:Hydration protocols and electrolyte management accompany radiotherapy in community settings.
- Experimental:TGF-beta monoclonal antibodies and novel antifibrotic agents face extended timelines due to collapsing pools of ISO 14155-certified principal investigators.
- Palliative:Dialysis-sparing interventions for advanced radiation nephropathy concentrate in academic medical centers with transplant capabilities.
Conventional approaches retain the largest share; experimental therapies face the most significant activation delays from investigator certification shortages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement pathways for radiation-induced kidney injury management have matured fastest in the United States, while EMA's MDR framework and CDSCO's import licensing reforms are reshaping market access across Europe and India respectively.
United States
Tertiary oncology centers in Boston and Houston are establishing dedicated radiation nephropathy management units with intensive nephrology co-management. FDA post-market surveillance requirements for radiation therapy combinations have tightened compliance burdens for trial sponsors. The Medicare reimbursement pathway for ACE inhibitor-based renoprotective protocols concentrates demand in academic medical centers with established dialysis-avoidance programs.
Germany
Contract development and manufacturing organizations in Munich and Basel control critical fill-finish capacity for intravenous renoprotective formulations. EMA's Medical Device Regulation recast forces pharmaceutical sponsors to reclassify drug-device renoprotective delivery systems, delaying synchronized launches. The Heidelberg and Berlin hospital clusters pilot continuous glomerular filtration rate monitoring with implanted microsensors in abdominal radiotherapy protocols.
Switzerland
Swissmedic oversight of biologic manufacturing concentrates high-value monoclonal antibody production in the Basel pharmaceutical cluster. The country's contract manufacturers supply clinical-grade material for TGF-beta signaling inhibitors advancing through late-stage trials. Geneva and Zurich academic hospitals anchor investigator-initiated trial networks across the Alpine region.
India
CDSCO's tightened import licensing for biologic renoprotectives redirects regional supply toward domestic manufacturers with established GMP infrastructure in Hyderabad and Ahmedabad. The PLI scheme for pharmaceuticals incentivizes local production of sterile injectable formulations. Maharashtra's hospital procurement departments are consolidating radiation nephropathy management into bundled oncology service contracts.
United Kingdom
The National Health Service leads contract restructuring that pressures pharmaceutical vendors to demonstrate total cost-of-care reductions across dialysis avoidance metrics. NHS England's specialized commissioning frameworks for radiation-induced kidney injury create distinct procurement pathways from bundled oncology payments. London's academic medical centers attract NIH and foundation funding for TGF-beta inhibitor investigator-initiated trials.
Radiation Nephropathy Treatment and Management Market Competitive Landscape
Player mix skews toward diversified pharmaceutical conglomerates with existing oncology infrastructure. The field compresses around entities capable of sustaining ISO 14155 compliance costs across multi-site Phase II programs. Three archetypes dominate: global oncology platforms leveraging existing trial networks, renoprotective specialists with deep small-molecule expertise, and scale-driven injectable manufacturers. Consolidation through strategic partnerships and site network consolidation represent the dominant competitive moves as credible trial sponsors dwindle.
Within the global oncology platform tier, Pfizer occupies a position exemplifying infrastructure-heavy trial execution across multiple international sites. Daiichi Sankyo sits within the renoprotective specialization archetype, anchoring expertise in small-molecule modalities. Teva Pharmaceutical Industries represents the scale-driven manufacturing tier, particularly in intravenous delivery modes where fill-finish complexity limits new entrants. These three entities collectively illustrate how compliance burden and manufacturing concentration are reshaping competitive positioning in radiation nephropathy therapeutics.
| Leading Market Players |
|---|
| Daiichi Sankyo |
| GlaxoSmithKline |
| Teva Pharmaceutical Industries |
| Pfizer |
| Par Pharmaceutical Companies |
| Silvergate Pharmaceuticals |
| Amgen |
| F. Hoffmann-La Roche |
| Bayer |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Swiss CDMOs and late-stage trial sponsors lock in fill-finish capacity for intravenous renoprotective formulations while anchoring price visibility against raw material volatility in monoclonal antibody production. These contracts concentrate pricing power with Basel and Munich manufacturers who control sterile manufacturing infrastructure under EMA MDR compliance timelines.
Pricing Analysis
Certification level creates the primary spread between premium intravenous biologics and commoditized oral generics. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified monoclonal antibodies from domestic Indian ACE inhibitors and unbranded nutraceuticals. Cost compression in the oral generic tier intensifies because CDSCO domestic manufacturing incentives expanded Hyderabad and Ahmedabad production capacity. Community oncology clinics exhibit the highest price sensitivity, while tertiary hospitals with dedicated radiation nephropathy management units absorb premium pricing for real-time GFR monitoring integration.
Supply Chain Analysis
Sterile fill-finish capacity in Switzerland and Germany underwrites supply security for intravenous renoprotective formulations, with Basel contract manufacturers commanding priority allocation for TGF-beta signaling inhibitors. Clinical-grade monoclonal antibody production draws from Chinese recombinant protein suppliers and Indian active pharmaceutical ingredient producers. Single-source vulnerability concentrates in Swiss-German CDMO corridors where ISO 14155 investigator certification bottlenecks delay alternative site qualification. Distribution runs through hospital procurement departments consolidating radiation nephropathy management into bundled oncology service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
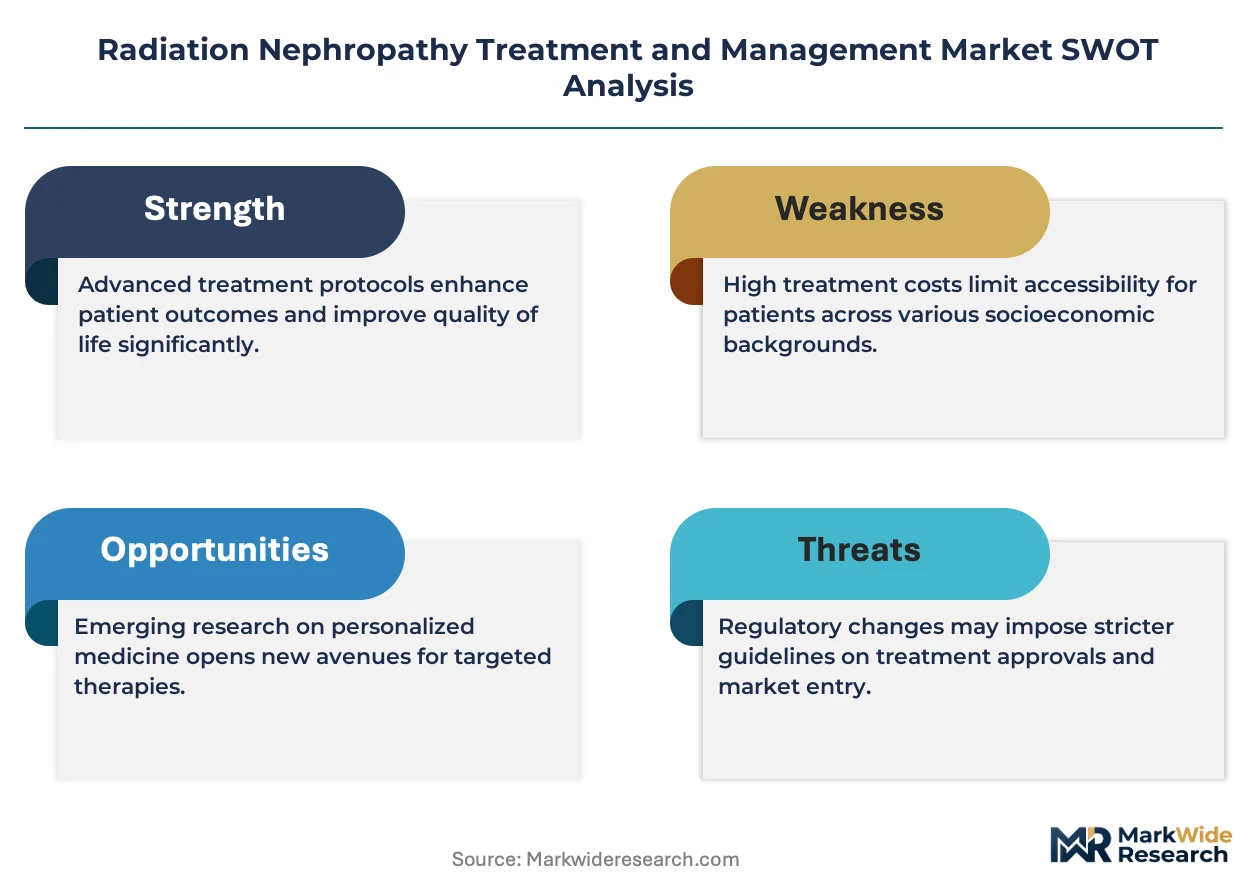
Platform economics now govern competitive advantage as renal perfusion monitoring systems integrate with automated ACE inhibitor titration, creating interoperability standards that lock in hospital system relationships and reshape vendor selection criteria across tertiary oncology centers.
For Market Incumbents: Fortify investigator site networks through exclusive certification partnerships with academic medical centers, insulating against ISO 14155 principal investigator shortages that extend trial activation timelines. Backward integration into sterile fill-finish capacity in Basel or Munich reduces exposure to Swiss-German CDMO single-source vulnerability. Priority investment in telemedicine-enabled GFR monitoring platforms captures homecare expansion trajectories before interoperability standards crystallize. For New Entrants and Emerging Players: Lead with telemedicine-enabled remote monitoring solutions targeting community oncology clinics constrained by limited interventional capabilities and narrower reimbursement bandwidth. India's CDSCO domestic manufacturing incentives offer the most penetrable geography for sterile injectable formulation entry against import-dependent biologic supply chains. Go-to-market positioning should emphasize nursing efficiency through prefilled syringe formats aligned with US integrated delivery network procurement preferences. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among device-platform hybrids with integrated drug delivery and continuous monitoring capabilities, as hospital procurement consolidation favors comprehensive renoprotective protocols over standalone therapeutics. Long-term viability hinges on dialysis-avoidance outcome demonstration across bundled payment structures. Acquisition targets should display established GMP infrastructure with CDSCO or FDA alignment. The signal to watch is NHS England specialized commissioning framework adoption rates for radiation-induced kidney injury as a distinct diagnostic category.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14155 Investigator Certification Partnership | Exclusive site network access accelerates trial activation timelines against collapsing principal investigator pools. |
| CDSCO Domestic Manufacturing Scale-Up | Hyderabad and Ahmedabad GMP facilities capture redirected regional supply under tightened import licensing. |
| Renal Perfusion Monitoring Integration | Continuous GFR sensor platforms lock in tertiary hospital procurement through automated ACE inhibitor titration. |
| Telemedicine-Enabled Homecare Expansion | Remote monitoring reduces tertiary hospital burden while maintaining protocol adherence in community settings. |
| NHS Specialized Commissioning Alignment | Distinct procurement pathways from bundled oncology payments create reimbursement visibility for dialysis-avoidance metrics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across oncology center nephrologists, hospital procurement directors, CDMO manufacturing executives, regulatory affairs specialists, and formulary access managers. Secondary validation incorporated FDA post-market surveillance filings, EMA MDR technical documentation, ClinicalTrials.gov protocol registries, CMS Medicare reimbursement databases, and CDSCO import licensing records. Bottom-up patient-flow modeling and top-down pharmaceutical expenditure triangulation anchored market size estimation.
Across the analysis window, projections integrated treatment approach maturity stratification, delivery mode cost tier dynamics, and end-user application intensity variations. Segmentation dimensions spanned product type regulatory pathways, intravenous versus oral formulation manufacturing complexity, and tertiary hospital versus community clinic procurement patterns. CAGRs derived from procedure volume trajectories in abdominal and pelvic radiotherapy protocols, cross-referenced against renoprotective agent adoption curves in Medicare claims data.
Forecasts assume regulatory continuity in FDA post-market surveillance and EMA MDR combination product classification; material policy shifts would require re-modeling of trial design timelines and commercial access pathways. Practitioner assumptions include stable Medicare reimbursement coding for radiation-induced kidney injury management and sustained CDSCO domestic manufacturing incentive structures. Scenario readiness remains essential as EPA radiation exposure guidelines and NHS commissioning framework restructuring evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Proteinuria Treatment Market
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Plasmapheresis Market
Nephrology
End Stage Renal Disease Market
Nephrology
US Dialysis Services Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Hemodialyzer Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Kidney Fibrosis Treatment Market