
 Dialysis Centers Market | 2026-2036
Dialysis Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Dialysis Centers Market Outlook
Buyer concentration in hospital-based dialysis is pivoting toward integrated health systems that internalize nephrology services. Fresenius Medical Care AG & Co. KGaA dominates hemodialysis machine manufacturing and clinic operations across multiple continents. DaVita Inc. competes through its extensive freestanding clinic network and physician partnership model. U.S. Renal Care, Inc. specializes in joint ventures with regional hospitals to secure referral streams and local market share.
Dialysis centers are clinical facilities that deliver extracorporeal blood purification through hemodialysis or peritoneal dialysis, requiring ultrapure water systems, biocompatible membranes, and controlled ultrafiltration rates to remove uremic toxins and excess fluid from patients with end-stage renal disease. Hemodialysis machines anchor the product type segment due to their capital intensity and recurring consumable demand, while telehealth solutions represent the fastest-growing technology category as remote monitoring reduces in-center visit frequency. In-center treatment still occupies the largest service type share, though home dialysis is gaining structural momentum where reimbursement and training infrastructure align.
FDA oversight of dialyzer and hemodialysis machine safety shapes product standards and market access timelines for device manufacturers entering the United States. CMS bundled payment rules directly influence whether providers invest in home dialysis training programs or expand brick-and-mortar clinic footprints. Stakeholders must monitor how Medicare's ESRD Treatment Choices model and comparable national reimbursement experiments alter site-of-care economics and equipment procurement cycles.
Market Dynamics
Site-of-care migration is restructuring capital deployment across the dialysis sector, as reimbursement incentives and patient preference pull treatment from institutional settings toward residential environments.
Growth Catalysts
- CMS ESRD Treatment Choices Model:Medicare's payment differential for home-based modalities accelerates provider investment in peritoneal dialysis training infrastructure across the United States.
- Telehealth Integration:Remote patient monitoring platforms reduce in-center visit frequency while maintaining clinical oversight, expanding addressable patient populations in rural service areas.
- Brazil:Expanded national health coverage under SUS incorporates home dialysis modalities, creating reimbursement certainty for equipment manufacturers and clinic operators.
Market Restraints
- Ultrapure Water Infrastructure:Capital requirements for water purification systems in hemodialysis facilities constrain expansion in cost-sensitive markets.
- Single-Source Concentrate Supply:Geographic concentration of dialysate concentrate manufacturing creates vulnerability to regional supply disruptions.
- FDA 510(k) Pathway:Extended review timelines for novel dialyzer membrane materials delay product commercialization and revenue recognition.
Strategic Opportunities
- Peritoneal Dialysis First Policy:United Kingdom's clinical commissioning guidelines mandate home-based treatment as default modality, opening equipment and consumables demand.
- Wearable Artificial Kidney:Convergence of miniaturized sorbent technology with continuous renal replacement circuits enables ambulatory treatment paradigms.
- Direct-to-Patient Distribution:Specialty pharmacy channels bypass traditional clinic procurement, capturing margin previously retained by institutional buyers.
Industry Challenges
- Nephrology Nurse Training Bottleneck:Specialized certification requirements for home dialysis training limit workforce scalability.
- Legacy EMR Integration:Proprietary data formats in incumbent dialysis documentation systems obstruct interoperability with remote monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dialysis Centers Market |
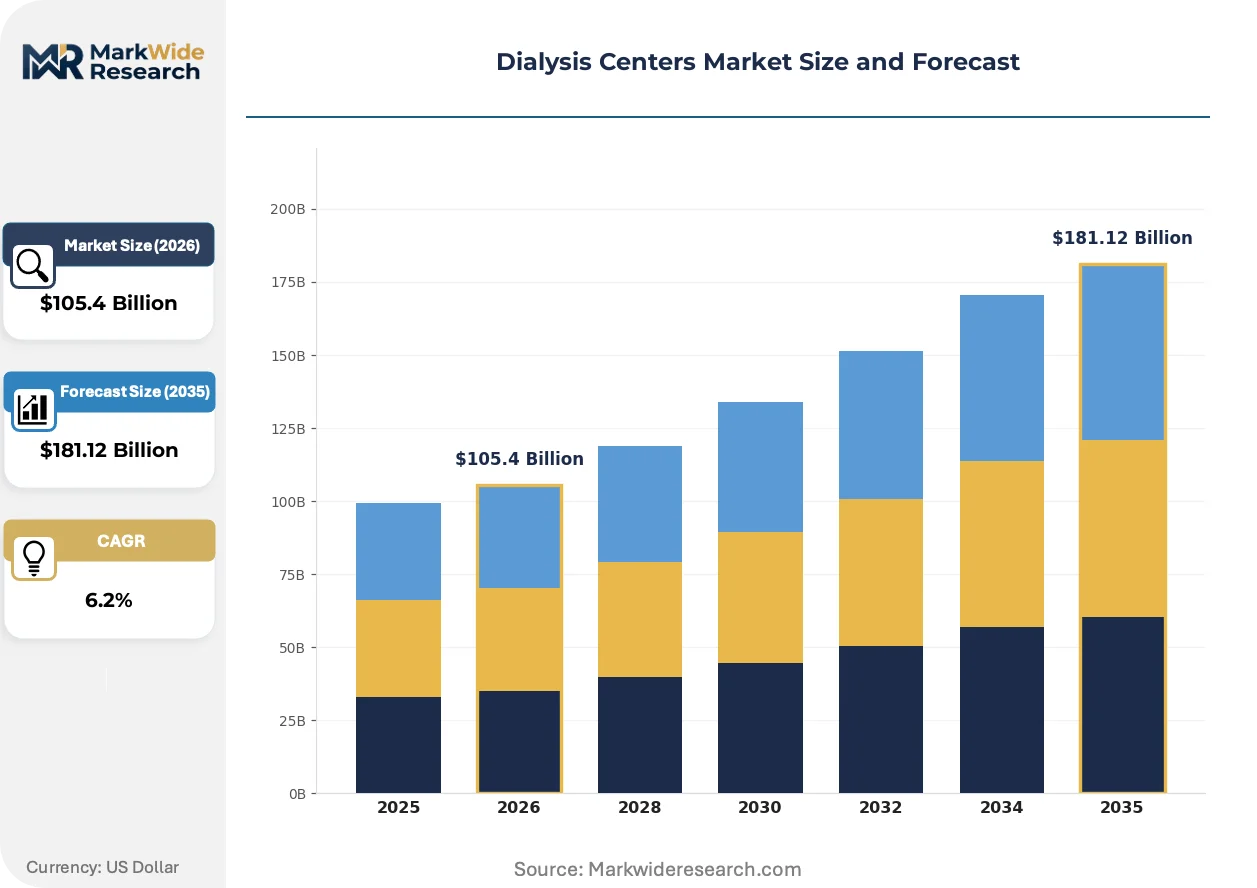
| Market Size in 2026 | $105.4 Billion |
| Market Size in 2035 | $181.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Product Type: Hemodialysis Machines, Peritoneal Dialysis Units, Dialyzers, Accessories Service Type: In-Center Treatment, Home Dialysis, Support Services, Chronic Care Management Technology: Conventional Dialysis, Online Hemodiafiltration, Wearable Devices, Telehealth Solutions |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, DaVita Inc., U.S. Renal Care, Inc., Dialysis Clinic, Inc., Satellite Healthcare, American Renal Associates, Northwest Kidney Centers, Centers for Dialysis Care, Rogosin Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dialysis Centers Market Strategic Shifts
Automation and connectivity are redefining clinical workflow economics, compressing labor intensity while extending treatment surveillance beyond facility walls.
Tablo hemodialysis systems from Outset Medical incorporate cloud-based prescription management and automated self-testing protocols that reduce technician supervision requirements. Freestanding clinic chains and hospital outpatient departments are deploying these platforms to extend operating hours without proportional staffing increases. Remote monitoring capability is decentralizing clinical oversight, enabling single nurses to manage concurrent treatments across dispersed locations.
EU Medical Device Regulation (MDR) reclassification of dialyzers as Class III devices intensifies clinical evidence requirements for market access. Manufacturers must generate post-market surveillance data and periodic safety update reports that exceed previous directive obligations. European hemodialysis machine suppliers are consolidating technical documentation and quality management systems to satisfy notified body scrutiny.
Integrated care contracts now bundle device procurement, consumables supply, and clinical services into single-source agreements spanning multi-year terms. Hospital systems and payers are displacing transactional equipment purchasing with total-cost-of-care arrangements that align vendor incentives with patient outcome metrics. This restructuring is most pronounced in United States Medicare Advantage networks and Brazilian supplementary health plans.
Dialysis Centers Market Segmentation
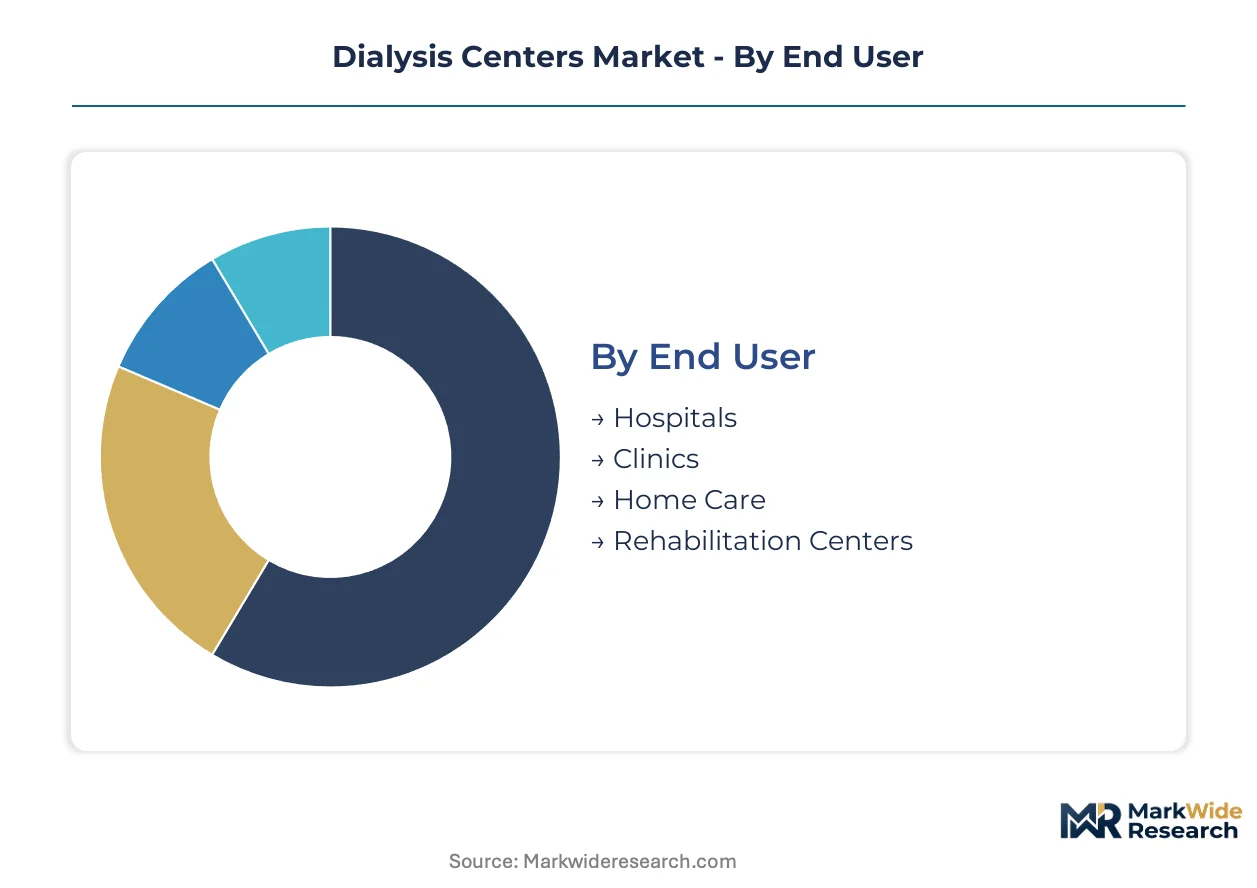
Dialysis center segmentation reveals distinct capital deployment patterns across treatment settings and technology tiers. Equipment procurement cycles and reimbursement differentials create asymmetric growth trajectories that reshape vendor priorities.
End User:
Upgrade cycles vary dramatically by care setting, with acute facilities replacing capital equipment faster than residential environments.
- Hospitals:These facilities deploy high-throughput hemodialysis suites requiring continuous ultrapure water generation and centralized monitoring infrastructure. Demand concentrates in integrated health systems across the United States where value-based contracts reward throughput efficiency and outcome metrics.
- Clinics:Freestanding dialysis centers operate dedicated renal replacement therapy units with streamlined patient flow design and optimized staff-to-station ratios. Fresenius Medical Care AG & Co. KGaA and DaVita Inc. dominate this channel through long-term equipment lease arrangements bundled with consumables supply.
- Home Care:Residential treatment settings utilize compact peritoneal dialysis cycler systems and simplified hemodialysis platforms designed for patient self-administration.
- Rehabilitation Centers:Post-acute facilities provide transitional dialysis support for patients recovering from hospitalization or awaiting transplantation.
Volume placements concentrate in Hospitals; the faster expansion belongs to Home Care.
Product Type:
Capital intensity and consumable attachment rates determine margin architecture across equipment categories.
- Hemodialysis Machines:These systems integrate blood pumps, dialysate proportioning, and ultrafiltration control modules with automated safety interlocks. Demand clusters in Brazil where expanded SUS coverage funds fleet modernization in public hospital networks.
- Peritoneal Dialysis Units:Automated cycler devices deliver nocturnal exchange therapy through programmable fill-dwell-drain sequences with remote data transmission. The United Kingdom's Peritoneal Dialysis First policy accelerates procurement cycles for home-based equipment.
- Dialyzers:Hollow-fiber membrane cartridges provide the primary blood-dialysate interface with biocompatibility profiles varying by synthetic polymer composition.
- Accessories:Bloodlines, fistula needles, and concentrate solutions constitute recurring revenue streams with stable replacement-driven demand.
Revenue concentration sits with Hemodialysis Machines; the steepest expansion trajectory belongs to Peritoneal Dialysis Units.
Service Type:
Site-of-care economics drive divergent staffing models and facility investment requirements.
- In-Center Treatment:Facility-based hemodialysis delivers thrice-weekly sessions with on-site nursing supervision and immediate complication response capability. This segment anchors volume in Medicare-reimbursed markets where bundled payments favor established clinic infrastructure.
- Home Dialysis:Patient-managed peritoneal or hemodialysis therapy reduces overhead while requiring intensive training investment and remote monitoring platforms. CMS ESRD Treatment Choices payment differentials accelerate structural migration toward this modality in the United States.
- Support Services:Technical maintenance, water quality testing, and equipment calibration ensure regulatory compliance and treatment safety.
- Chronic Care Management:Coordinated nephrology, nutrition, and social work services address comorbidity burden in end-stage renal disease populations.
Patient volumes concentrate in In-Center Treatment; the most rapid share gain belongs to Home Dialysis.
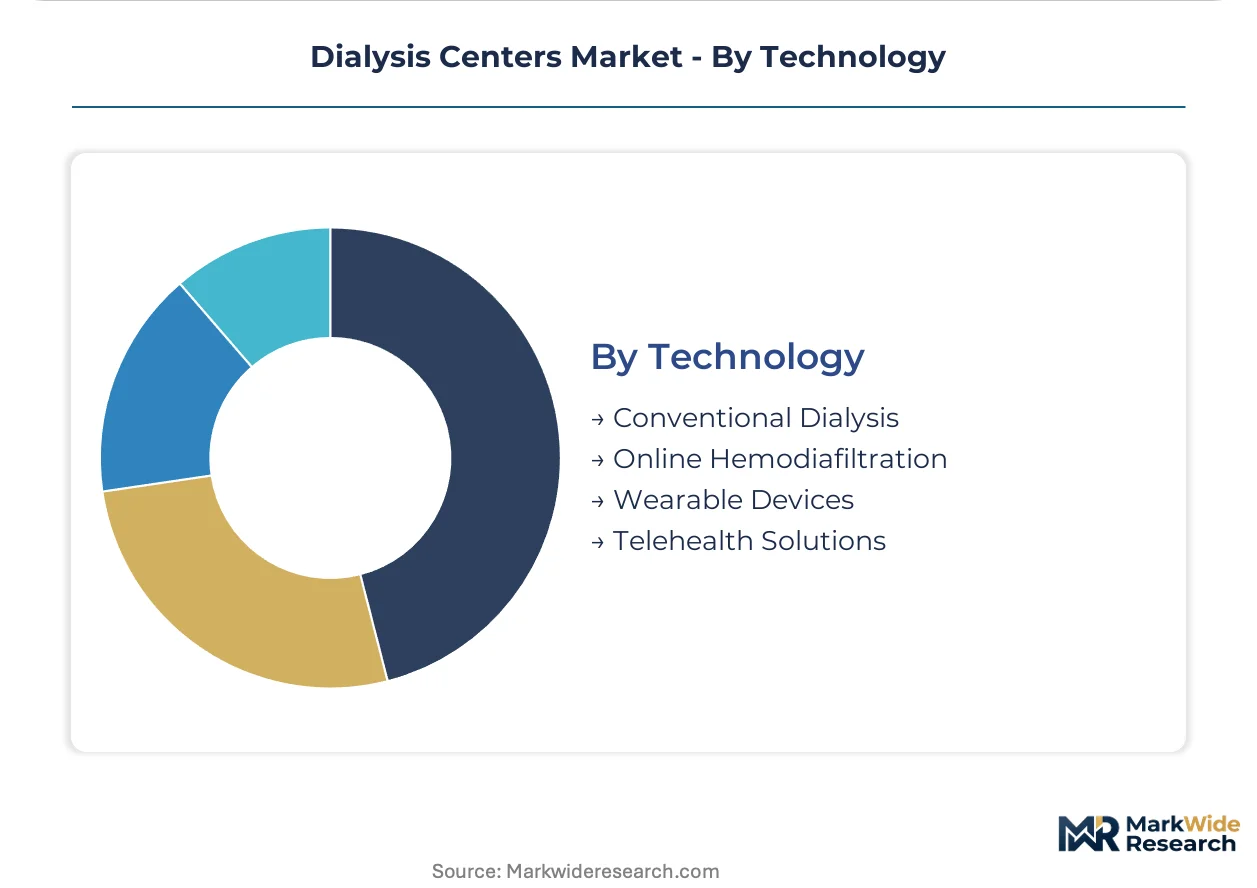
Technology:
Regulatory clearance timelines and clinical evidence requirements stratify competitive entry barriers.
- Conventional Dialysis:Standard diffusive clearance therapy using bicarbonate-buffered dialysate maintains dominant installed base across mature markets. FDA 510(k) pathway familiarity enables predictable commercialization for incremental device improvements.
- Online Hemodiafiltration:Convective-enhanced clearance systems utilize ultrapure substitution fluid generated inline to improve middle-molecule removal. EU MDR Class III reclassification intensifies clinical evidence burdens for European market access.
- Wearable Devices:Miniaturized sorbent-based systems enable ambulatory continuous renal replacement through reduced form factors.
- Telehealth Solutions:Remote patient monitoring platforms transmit treatment data and enable asynchronous clinical oversight between scheduled encounters.
Installed base concentrates in Conventional Dialysis; the most aggressive expansion belongs to Telehealth Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States health systems concentrate the largest installed base of dialysis capacity, with integrated care models and bundled payment experiments accelerating site-of-care migration toward home-based modalities.
United States
Medicare's ESRD Treatment Choices model creates payment differentials favoring peritoneal dialysis adoption across Medicare Advantage networks. CMS bundled payment rules directly influence whether providers expand brick-and-mortar clinic footprints or invest in home training infrastructure. Texas and Florida hospital systems anchor the largest concentration of freestanding clinic joint ventures with national operators.
Germany
Aging demographics and high chronic kidney disease prevalence sustain robust replacement demand for hemodialysis equipment in hospital outpatient departments. EU Medical Device Regulation reclassification of dialyzers as Class III devices intensifies clinical evidence requirements for market access. Bavarian medical technology clusters concentrate dialyzer membrane manufacturing and hemodialysis machine assembly operations.
Japan
Super-aged population structure generates sustained demand for both in-center and home dialysis modalities through universal health coverage. METI industrial policy supports domestic manufacturing of compact peritoneal dialysis cyclers designed for residential use. Osaka-Kobe industrial corridor hosts concentrated production of synthetic hollow-fiber membranes for export markets.
Brazil
Expanded SUS national health coverage incorporates home dialysis modalities, creating reimbursement certainty for equipment manufacturers and clinic operators. ANVISA regulatory oversight shapes product registration timelines for imported hemodialysis machines entering the public procurement system. São Paulo state health networks anchor the largest concentration of public hospital dialysis modernization programs.
United Kingdom
Clinical commissioning guidelines mandate peritoneal dialysis as the default treatment modality, opening equipment and consumables demand for home-based systems. NHS England integrated care contracts bundle device procurement with clinical services across multi-year terms. London and Manchester renal networks lead structural migration from thrice-weekly in-center hemodialysis toward patient-managed home therapies.
Dialysis Centers Market Competitive Environment
German producers anchor one tier of equipment manufacturing; United States clinic operators hold another tier of service delivery consolidation. The sector presents a bifurcated structure with concentrated machine manufacturing and fragmented-to-consolidated clinic operations depending on geography. Strategic archetypes include integrated device-and-service conglomerates, pure-play clinic chains, and regional hospital joint venture specialists. Dominant competitive moves encompass long-term equipment lease arrangements bundled with consumables supply, and vertical integration into water purification system manufacturing.
Among Germany-based integrated conglomerates, Fresenius Medical Care AG & Co. KGaA exemplifies the device-and-service archetype through its dual presence in hemodialysis machine manufacturing and clinic operations. DaVita Inc. occupies a position representing the pure-play clinic chain model with extensive freestanding networks. U.S. Renal Care, Inc. sits within the regional joint venture specialist tier, securing referral streams through hospital partnerships.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| DaVita Inc. |
| U.S. Renal Care, Inc. |
| Dialysis Clinic, Inc. |
| Satellite Healthcare |
| American Renal Associates |
| Northwest Kidney Centers |
| Centers for Dialysis Care |
| Rogosin Institute |
| Others |
Value Chain & Pricing Dynamics
Integrated health systems and Medicare Advantage networks concentrate procurement volume for hemodialysis equipment, locking in multi-year bundled payment contracts that favor total-cost-of-care pricing over transactional per-unit rates. This buyer consolidation shifts pricing power toward vendors capable of integrating device supply, consumables logistics, and clinical service delivery under single-source agreements.
Pricing Analysis
Volume placements anchor the low-margin baseline, while premium-margin capture concentrates in telehealth-enabled platforms and wearable device categories. Pricing stratifies across premium, standard, and economy tiers, with FDA 510(k) clearance tier and remote monitoring capability serving as primary differentiation drivers. Cost compression in standard hemodialysis machines is intensifying because Brazilian SUS procurement and U.S. hospital GPO contracts enforce aggressive competitive bidding. Dialysis clinic chains exhibit highest price sensitivity due to thin reimbursement spreads, whereas integrated health systems prioritize outcome-linked value metrics over unit cost.
Supply Chain Analysis
FDA and EU MDR certification requirements gate supplier qualification, extending onboarding timelines for membrane manufacturers and concentrate producers seeking entry into regulated markets. Manufacturing concentration clusters in Germany, Japan, and the United States for hemodialysis machines, while hollow-fiber membrane production draws from Japan and Germany. Raw material dependencies span medical-grade polymers, sorbent materials, and ultrapure water generation components. Single-source vulnerability in dialysate concentrate supply creates exposure to regional production disruptions. Distribution runs through direct-to-hospital contracts, specialty pharmacy channels for home dialysis, and long-term equipment lease arrangements bundled with consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dialysis center markets are becoming a vertical-integration race as equipment manufacturers acquire clinic operations and service providers backward-integrate into water purification and consumables production to capture margin pools previously retained by suppliers.
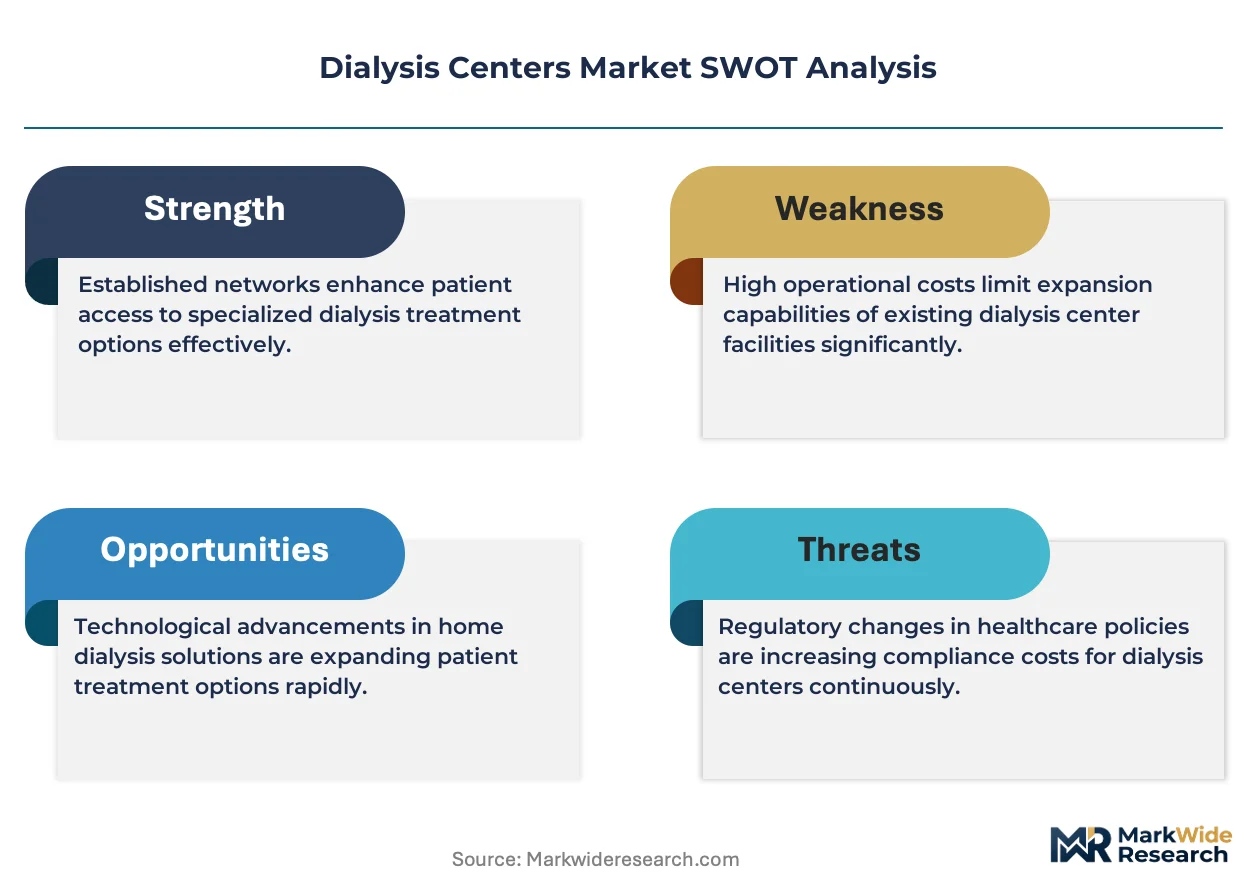
For Market Incumbents: Deploy remote monitoring platform integration to defend against telehealth-native entrants and pure-play software vendors. Lock in hospital joint ventures through exclusive equipment lease terms that bundle training infrastructure and consumables supply. Deepen backward integration into ultrapure water system manufacturing to reduce third-party dependency and protect margin from concentrate supply volatility. For New Entrants and Emerging Players: Begin with peritoneal dialysis cycler systems in Brazil and the United Kingdom, where national reimbursement policies create immediate addressable demand without entrenched incumbent relationships. Target rural U.S. service areas where telehealth-enabled remote monitoring reduces the capital barrier to patient acquisition. Pursue direct-to-patient distribution through specialty pharmacy partnerships to bypass clinic procurement gatekeepers. For Investors and Strategic Acquirers: The window for entry favors regional hospital joint venture specialists with established referral streams and local market share in Medicare Advantage-dense geographies. Long-term viability hinges on positioning for site-of-care migration acceleration rather than in-center capacity expansion. Watch CMS ESRD Treatment Choices model participation rates as the inflection signal for home dialysis infrastructure investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Home Dialysis Training Infrastructure Buildout | CMS payment differentials reward peritoneal dialysis adoption across Medicare networks. |
| Telehealth Platform Integration | Remote monitoring reduces labor intensity while extending clinical oversight to rural patients. |
| EU MDR Class III Certification Pathway | MDR reclassification intensifies evidence requirements for dialyzer market access. |
| Hospital System Joint Venture Expansion | Integrated care contracts bundle device procurement with multi-year clinical service agreements. |
| Wearable Artificial Kidney Development | Miniaturized sorbent technology enables ambulatory treatment beyond facility walls. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this dialysis centers market analysis, supplemented by primary interviews with nephrology practice administrators, biomedical engineering directors, hospital purchasing committee members, and GPO contracts managers. Secondary sources encompassed FDA 510(k) device clearances, CMS Medicare reimbursement databases, ANVISA registration records, and EU MDR technical documentation. Bottom-up patient volume modeling and top-down healthcare expenditure triangulation validated market sizing across the analysis window.
Data-stream reconciliation between equipment shipment records, clinic capacity surveys, and reimbursement claim patterns informed the forecast framework. Segmentation modeling spanned end user settings, product type tiers, service delivery modes, and technology categories including conventional, online hemodiafiltration, and telehealth solutions. CAGRs were derived from regression analysis against chronic kidney disease prevalence trajectories and policy-driven site-of-care migration assumptions. Forecast inputs incorporated Medicare Advantage penetration rates and SUS coverage expansion timelines.
Underlying measurement precision varies by segment; in-center treatment and hemodialysis machine volumes carry tighter precision than emerging wearable device and home dialysis adoption forecasts. Projections reflect assumptions about CMS policy continuity and EU MDR implementation pace. A model refresh is warranted upon material change in Medicare reimbursement differential structures or ANVISA regulatory timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Kidney Transplant Medicine Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Renal Stent Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
Chronic Kidney Disease Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
US Dialysis Market
Nephrology
Dialysis Service Market
Nephrology
Hemodialyzer Market
Nephrology
Late Stage Chronic Kidney Disease Therapeutics Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
Lupus Nephritis Treatment Market