
 Andersen Tawil Syndrome Treatment Market | 2026-2036
Andersen Tawil Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Andersen Tawil Syndrome Treatment Market Outlook
Multi-sourced clinical supply is realigning how developers secure active pharmaceutical ingredients and comparator drugs for Andersen Tawil syndrome programs. Teva Pharmaceutical Industries leverages its established neurology portfolio to sustain engagement with movement disorder specialists who encounter periodic paralysis cases. Pfizer Inc. anchors its rare disease credibility through channel relationships with academic medical center pharmacies. Sun Pharmaceutical Industries competes on cost-access dimensions for hospitals managing long-term potassium channel therapy.
Andersen Tawil syndrome treatment addresses a rare channelopathy caused by KCNJ2 gene mutations that disrupt cardiac and skeletal muscle ion channel function, requiring therapies that stabilize membrane excitability across both tissue types. The primary purpose spans acute attack prevention, arrhythmia risk reduction, and functional rehabilitation for patients with episodic weakness. Medication dominates current clinical practice as the established revenue pool, while gene therapy represents the fastest-growing segment as vector delivery technologies mature for cardiac-targeted interventions. Intravenous delivery occupies the critical-care margin tier for acute flaccid paralysis episodes, whereas oral formulations sustain the chronic maintenance volume base.
The FDA Orphan Drug program shapes development economics through tax credits and market exclusivity provisions that offset small-population trial costs. EMA's orphan designation framework creates parallel European access pathways for sponsors pursuing centralized marketing authorization. Payers and clinicians must monitor how gene therapy reimbursement mechanisms evolve for ultra-rare indications with single-dose curative potential.
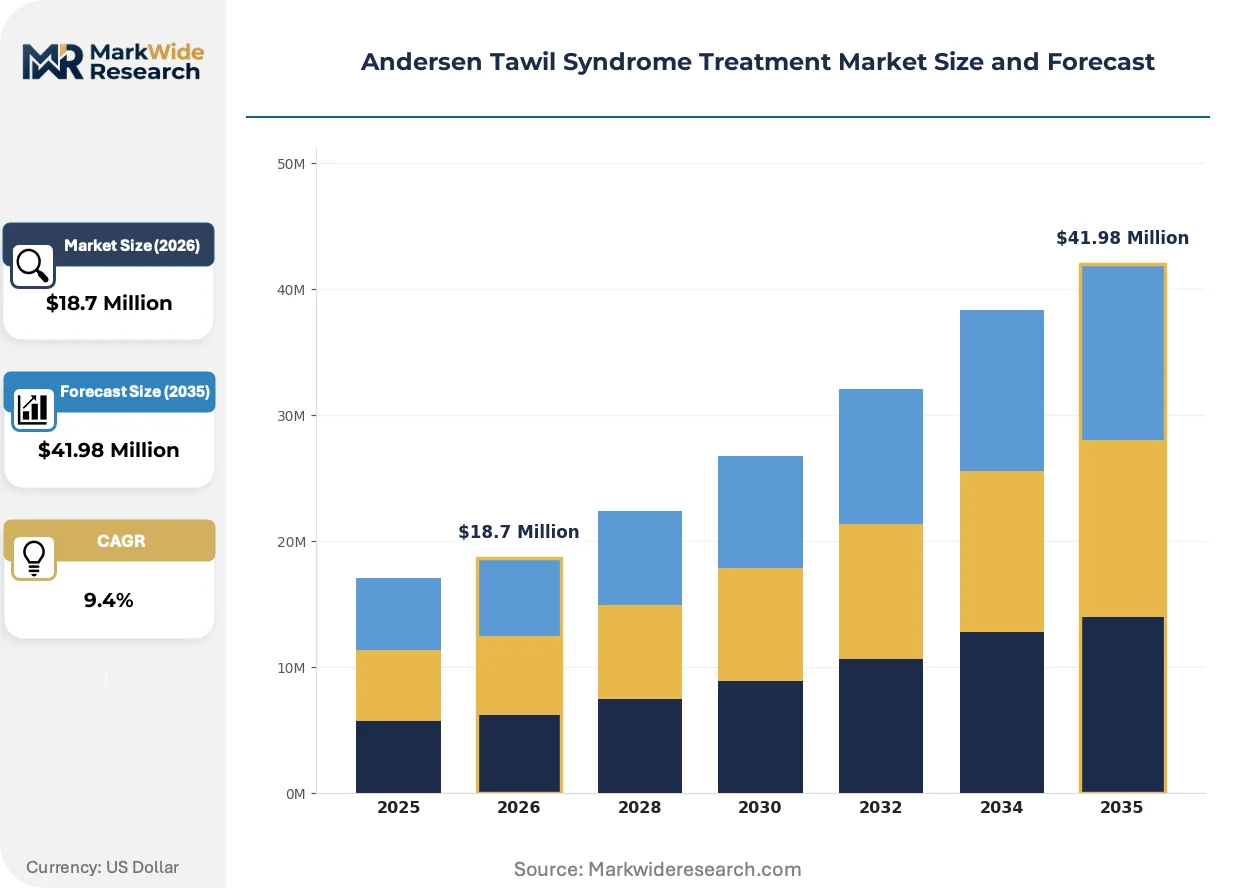
Market Dynamics
Gene therapy vector platforms are compressing development timelines for ultra-rare channelopathies, forcing sponsors to recalibrate clinical trial designs around cardiac safety endpoints that satisfy both FDA and EMA requirements simultaneously.
Growth Catalysts
- FDA Orphan Drug tax credits:The credit structure defrays trial costs for single-dose curative candidates targeting KCNJ2 mutations, enabling smaller biotech sponsors to advance programs without major pharma backing.
- Academic medical center expansion:Specialized neuromuscular centers in Boston, London, and Tokyo are consolidating patient registries that accelerate natural history studies and biomarker validation for periodic paralysis subtypes.
- AAV vector manufacturing scale-up:Contract development organizations are building dedicated cardiac-targeted viral production lines that reduce per-dose costs for gene therapy candidates entering Phase II.
Market Restraints
- Plasma-derived potassium channel modulator supply:Dependence on fractionation facilities in the United States and Germany creates single-source vulnerability for acute attack management protocols.
- EMA centralized authorization complexity:Divergent member state reimbursement mechanisms for ultra-rare indications fragment commercial launch sequencing despite unified marketing approval.
- Small-molecule substitution pressure:Generic carbonic anhydrase inhibitors and potassium-sparing diuretics constrain pricing power for branded membrane stabilizers in chronic maintenance settings.
Strategic Opportunities
- Japan's SAKIGAKE designation:The PMDA's priority review pathway offers conditional approval based on single-arm trials for serious rare diseases, compressing time-to-market for cardiac gene therapies.
- Remote patient monitoring integration:Wearable ECG and muscle function sensors enable real-time attack prediction that shifts care from emergency departments to home-based intervention.
- Patient advocacy network leverage:Periodic Paralysis International's registry infrastructure provides de facto trial-ready cohorts that reduce screening failure rates in natural history-matched studies.
Industry Challenges
- Electrophysiologist-geneticist coordination:Care fragmentation between cardiac arrhythmia specialists and neuromuscular clinics delays definitive diagnosis and appropriate therapy initiation.
- Gene therapy manufacturing facility qualification:FDA's Chemistry, Manufacturing, and Controls requirements for AAV products demand 18-24 month facility validation timelines that extend cash runway needs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Andersen Tawil Syndrome Treatment Market |
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medication, Gene Therapy, Supportive Care, Rehabilitation Delivery Mode: Oral, Intravenous, Subcutaneous, Transdermal End User: Hospitals, Clinics, Home Care, Research Institutions Application: Symptom Management, Genetic Counseling, Clinical Trials, Patient Monitoring |
| Companies Covered | Teva Pharmaceutical Industries, Pfizer Inc., Sun Pharmaceutical Industries, Novartis AG, Zydus Lifesciences, Bristol-Myers Squibb Company, Vertex Pharmaceuticals Incorporated, Sanofi, Strongbridge Biopharma (Xeris Biopharma), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Andersen Tawil Syndrome Treatment Market Strategic Shifts
Cardiac-targeted delivery mechanisms are displacing systemic administration as the dominant vector design paradigm, while real-world evidence frameworks reshape how sponsors demonstrate long-term efficacy for single-intervention therapies.
Organoid-based cardiac channelopathy models are decentralizing preclinical safety assessment from large animal facilities to academic screening laboratories. Research hospitals in Rotterdam and Toronto now maintain biobanks of patient-derived cardiomyocytes that predict arrhythmia risk without primate telemetry studies. This compression of early-phase validation is shortening IND-enabling timelines by 8-14 months for KCNJ2-targeted programs.
The FDA's Complex Innovative Trial Designs pilot program is accelerating adaptive protocols that incorporate biomarker-driven enrollment for ultra-rare indications. Sponsors can now modify sample sizes mid-trial based on electrophysiological response data, reducing the number of patients exposed to placebo. Cardiac gene therapy developers are prioritizing this pathway to minimize recruitment burden in dispersed patient populations.
Hospital pharmacy procurement for rare disease biologics is consolidating through specialty distributor networks that manage cold-chain logistics and patient assistance programs as bundled services. Academic medical centers in the United States are outsourcing inventory risk for high-cost gene therapies to third-party logistics providers that maintain consignment stock at the point of care. This shift transfers working capital burden from hospital balance sheets to manufacturer or distributor accounts.
Andersen Tawil Syndrome Treatment Market Segmentation
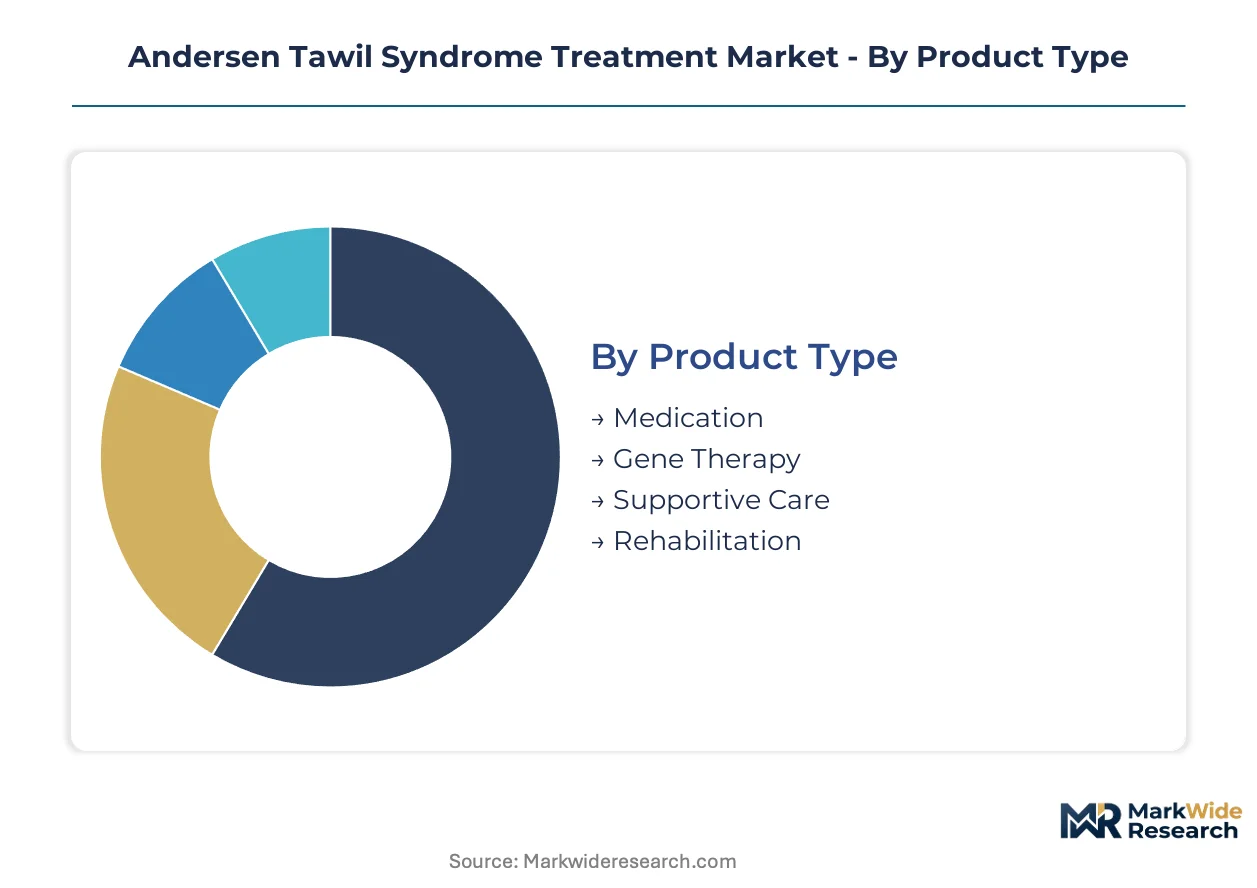
Treatment modalities for Andersen Tawil syndrome fragment across acute intervention and chronic maintenance paradigms, with supply chains diverging between small-molecule manufacturing and viral vector bioproduction. Understanding these segment boundaries clarifies how capital allocates between established pharmaceutical infrastructure and emerging gene therapy platforms.
Product Type:
Supply concentration for active pharmaceutical ingredients and viral vectors determines which therapeutic categories attract development investment and manufacturing capacity.
- Medication:Small-molecule potassium channel stabilizers and carbonic anhydrase inhibitors constitute the established revenue base, with formulation supply anchored by contract manufacturers in the United States and India serving hospital formularies. Demand concentrates in academic medical center pharmacies managing chronic maintenance protocols for periodic paralysis prevention.
- Gene Therapy:AAV-mediated KCNJ2 correction programs represent the steepest expansion trajectory as cardiac-targeted vector designs mature, though manufacturing capacity constraints at dedicated viral production facilities limit near-term supply. Sponsors prioritize this segment for single-dose curative potential despite 18-24 month facility qualification timelines.
- Supportive Care:Electrolyte management and cardiac monitoring devices bridge acute episodes.
- Rehabilitation:Physical therapy protocols address residual weakness between paralytic attacks.
Today's leader: Medication. Tomorrow's challenger: Gene Therapy.
Delivery Mode:
Route of administration separates emergency intervention from outpatient maintenance, with cost tiers reflecting site-of-care requirements and formulation complexity.
- Oral:Sustained-release potassium supplements and membrane stabilizers dominate chronic volume, with generic substitution pressure constraining branded pricing power in maintenance settings.
- Intravenous:Acute flaccid paralysis management requires hospital-based infusion capabilities, with supply vulnerability concentrated at fractionation facilities in the United States and Germany.
- Subcutaneous:Emerging depot formulations for attack prophylaxis.
- Transdermal:Investigational ion channel modulator patches for localized delivery.
Volume concentrates in oral maintenance. Margin concentrates in intravenous rescue.
End User:
Site-of-care migration shifts inventory risk and working capital burden across institutional and home-based settings.
- Hospitals:Academic medical centers in Boston, London, and Tokyo anchor specialized neuromuscular programs, consolidating patient registries and emergency intervention capabilities for acute periodic paralysis episodes.
- Clinics:Movement disorder specialists in referral networks manage diagnostic workup and therapy initiation.
- Home Care:Remote patient monitoring integration enables attack prediction and early intervention outside institutional settings.
- Research Institutions:Biobanks in Rotterdam and Toronto maintain patient-derived cardiomyocyte models for preclinical validation.
Care fragmentation between electrophysiologists and geneticists delays diagnosis in clinics. Integrated centers compress time-to-therapy.
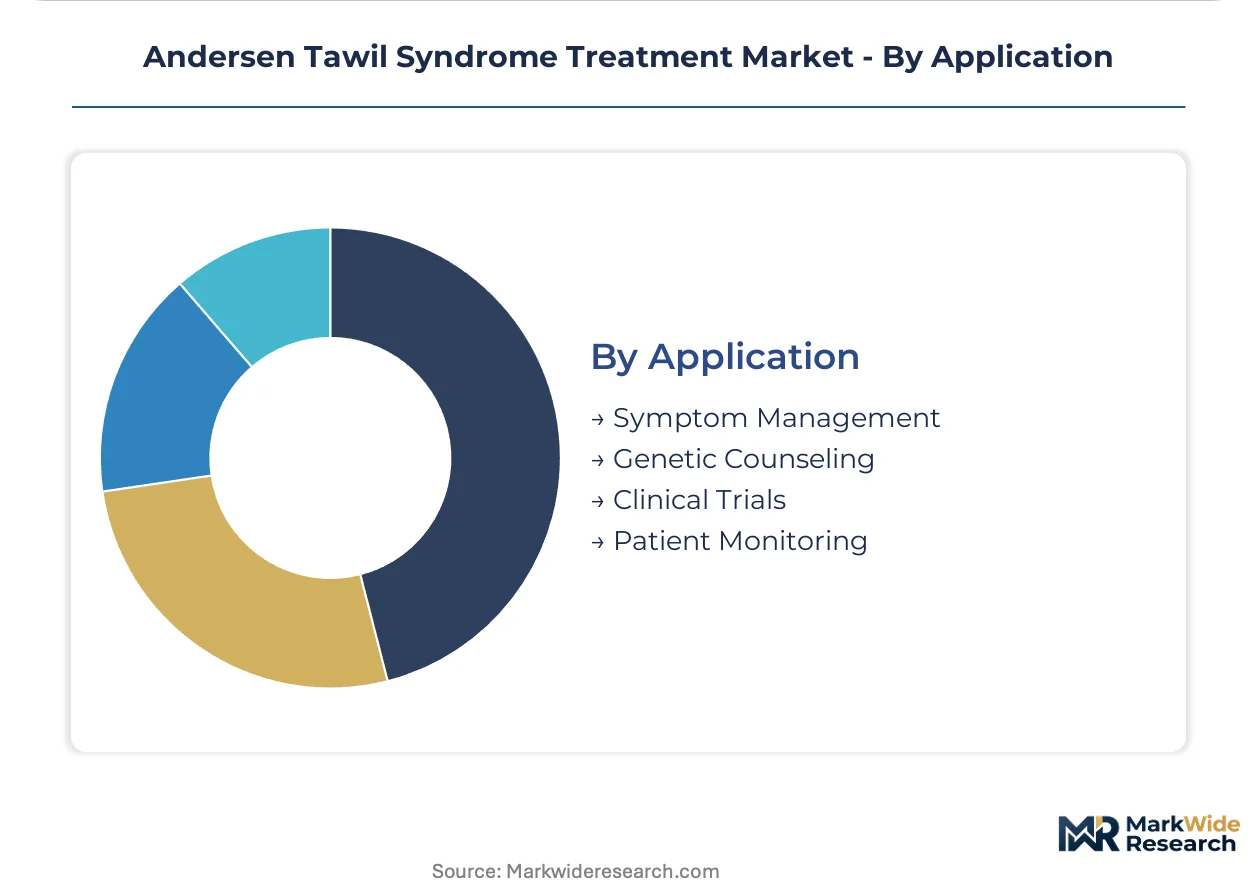
Application:
Functional purpose separates revenue-generating treatment from enabling services that accelerate development timelines and patient access.
- Symptom Management:Acute attack prevention and arrhythmia risk reduction constitute the core therapeutic revenue pool, with medication and device-based interventions targeting membrane excitability stabilization.
- Genetic Counseling:KCNJ2 variant interpretation services guide family planning and cascade screening decisions.
- Clinical Trials:FDA's Complex Innovative Trial Designs pilot program enables adaptive protocols that reduce placebo exposure in biomarker-driven enrollment.
- Patient Monitoring:Wearable ECG and muscle function sensors enable real-time attack prediction.
Symptom management captures current spend. Clinical trials and monitoring infrastructure enable future market expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's academic medical corridor anchors specialized neuromuscular capacity for Andersen Tawil syndrome, with patient registries at Massachusetts General Hospital and Boston Children's Hospital compressing diagnostic timelines. Clustered electrophysiology expertise draws international referrals for KCNJ2 variant confirmation.
United States
FDA Orphan Drug tax credits sustain biotech sponsor viability for single-dose curative programs targeting ultra-rare channelopathies. The agency's Complex Innovative Trial Designs pilot enables adaptive protocols that reduce placebo exposure in biomarker-driven enrollment. Academic medical centers in Rochester, Minnesota and Durham, North Carolina maintain parallel natural history cohorts.
Germany
EMA centralized authorization creates unified marketing pathways for membrane stabilizers and gene therapy candidates, though member state reimbursement fragmentation persists. The Paul-Ehrlich-Institut oversees viral vector batch release for cardiac-targeted AAV programs entering European markets. Heidelberg and Munich university hospitals coordinate periodic paralysis referral networks across Central Europe.
Japan
PMDA's SAKIGAKE designation offers conditional approval based on single-arm trials for serious rare diseases, compressing time-to-market for cardiac gene therapies. METI funding supports domestic AAV manufacturing scale-up at contract development organizations in Kobe and Tsukuba. Tokyo Medical and Dental University anchors the national patient registry for Andersen Tawil subtype classification.
United Kingdom
NHS England's specialized commissioning framework concentrates ultra-rare disease treatment at designated neuromuscular centers in London, Oxford, and Newcastle. The MHRA's Innovative Licensing and Access Pathway accelerates conditional approvals for therapies addressing unmet need in channelopathy populations. Genomics England's 100,000 Genomes Project identified novel KCNJ2 variants informing natural history studies.
Canada
Health Canada's Orphan Drug Regulatory Framework provides fee waivers and priority review for therapies targeting patient populations below five per ten thousand. Provincial formularies negotiate distinct reimbursement contracts for high-cost biologics, creating administrative burden for sponsors. Toronto's Hospital for Sick Children maintains North America's largest pediatric periodic paralysis biobank.
Andersen Tawil Syndrome Treatment Market Competitive Environment
Global majors compete with regional champions across development-stage pipelines and commercial infrastructure for rare channelopathies. The vendor base stratifies into three tiers: established neurology portfolios with movement disorder specialist relationships, rare disease pure-plays leveraging orphan regulatory pathways, and emerging gene therapy platforms building cardiac-targeted vector capabilities. Consolidation pressure intensifies as AAV manufacturing scale requirements favor sponsors with dedicated viral production facilities or locked-in CDMO partnerships.
Within the established pharmaceutical tier, Teva Pharmaceutical Industries and Pfizer Inc. occupy positions anchored by neurology and rare disease channel relationships respectively. Sun Pharmaceutical Industries exemplifies cost-access competition for hospital formularies managing chronic potassium channel therapy. These three entities represent divergent strategic postures: legacy neurology engagement, academic medical center pharmacy anchoring, and emerging market volume capture.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Pfizer Inc. |
| Sun Pharmaceutical Industries |
| Novartis AG |
| Zydus Lifesciences |
| Bristol-Myers Squibb Company |
| Vertex Pharmaceuticals Incorporated |
| Sanofi |
| Strongbridge Biopharma (Xeris Biopharma) |
| Others |
Value Chain & Pricing Dynamics
Plasma fractionation facility utilization rates in the United States and Germany cascade directly into tiered pricing for acute attack management protocols, with hospital procurement managers negotiating volume-based contracts that separate premium branded membrane stabilizers from generic carbonic anhydrase inhibitor alternatives.
Pricing Analysis
Input-cost pass-through from AAV vector manufacturing dominates gene therapy pricing, with facility qualification timelines and single-source viral production lines feeding into premium positioning for cardiac-targeted KCNJ2 correction programs. Price differentiation separates FDA Orphan Drug-designated biologics with market exclusivity from chronic maintenance small molecules facing generic substitution pressure. Pricing pressure stems from carbonic anhydrase inhibitor commoditization in outpatient settings. Academic medical center pharmacies exhibit lowest price sensitivity due to bundled reimbursement frameworks, while community hospitals managing sporadic periodic paralysis cases demonstrate highest sensitivity to per-dose costs.
Supply Chain Analysis
Regional distribution centers operated by specialty pharmaceutical distributors in the United States, Germany, and Japan maintain cold-chain logistics for gene therapy consignment stock at academic medical centers. Active pharmaceutical ingredient sourcing draws from contract manufacturers in India and the United States, while AAV vector bioproduction concentrates at dedicated facilities in Massachusetts, Bavaria, and Kobe. Single-source vulnerability at plasma fractionation sites creates supply risk for acute intravenous potassium channel modulators. Distribution runs through hub-and-spoke networks anchored by hospital pharmacy consignment models that transfer inventory risk to manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Andersen Tawil syndrome treatment market functions as a regulatory compounder where FDA Orphan Drug tax credits and EMA centralized authorization pathways structurally expand addressable margins for developers targeting KCNJ2 channelopathies.
For Market Incumbents: Anticipate gene therapy platform consolidation by securing locked-in CDMO partnerships for cardiac-targeted AAV manufacturing before facility qualification timelines extend cash runway requirements. Defend formulary position at academic medical centers through integrated patient registry sponsorship that reduces competitor screening efficiency. Vertical integration into patient-derived cardiomyocyte biobank access provides preclinical differentiation against emerging platform entrants. For New Entrants and Emerging Players: Capture Japan's SAKIGAKE designation pathway for conditional approval based on single-arm trials, compressing time-to-market versus FDA and EMA sequential submissions. Target remote patient monitoring integration as the most penetrable white space, with wearable ECG and muscle function sensors enabling attack prediction that shifts care from emergency departments to home-based intervention. Pursue licensing arrangements with Periodic Paralysis International's registry infrastructure to access de facto trial-ready cohorts. For Investors and Strategic Acquirers: Asymmetric upside sits with rare disease pure-plays possessing locked-in AAV manufacturing partnerships and active FDA Complex Innovative Trial Designs pilot program enrollment. Long-term viability across the analysis window hinges on gene therapy reimbursement mechanism maturation for single-dose curative indications. Watch PMDA SAKIGAKE approval velocity as the signal indicating regulatory pathway compression feasibility for cardiac gene therapy platforms.| Strategic Initiative | Industry Significance |
|---|---|
| AAV Manufacturing Scale-Up | Locked-in CDMO partnerships at Kobe and Tsukuba facilities reduce per-dose production costs for cardiac-targeted vectors. |
| FDA Complex Innovative Trial Designs Enrollment | Adaptive protocols incorporating biomarker-driven endpoints reduce placebo exposure in dispersed periodic paralysis populations. |
| Patient Registry Sponsorship | Academic medical center partnerships at Massachusetts General and Boston Children's compress diagnostic timelines and competitor access. |
| Remote Monitoring Platform Integration | Wearable ECG and muscle function sensors enable real-time attack prediction shifting site-of-care from hospitals to home settings. |
| Orphan Drug Designation Pathway Stacking | Sequential FDA, EMA, and PMDA submissions maximize tax credit capture and market exclusivity duration across regulatory clusters. |
Study Parameters
Bottom-up patient population modeling reconciled against top-down pharmaceutical supply tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at academic medical centers, and payer access specialists were cross-validated against secondary sources including FDA Orphan Drug Designation filings, EMA centralized authorization submissions, ClinicalTrials.gov registry entries, and hospital procurement database extracts. Triangulation between demand-side patient cohort projections and supply-side manufacturing capacity announcements ensures segmentation integrity.
Input-output matrices mapping KCNJ2 variant prevalence to treatment line penetration and dosage form adoption across oral, intravenous, and emerging gene therapy delivery modes structure the forecast framework. Segmentation dimensions include product type, delivery mode, end user site-of-care, and application purpose, with CAGRs derived from natural history study enrollment trajectories and regulatory approval pathway velocity. Forecast inputs incorporate AAV vector manufacturing scale-up timelines and orphan drug designation grant rates.
Gene therapy manufacturing facility qualification delays, divergent member state reimbursement fragmentation despite EMA centralized authorization, and small-molecule generic substitution acceleration are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Treatment
Psittacosis Treatment Market
Medical Treatment
Japan Radiotherapy Market
Medical Treatment
Gallbladder Treatment Market
Medical Treatment
Trauma and Extremities Market
Medical Treatment
Systemic Inflammatory Response Syndrome Treatment Market
Medical Treatment
Influenza Treatment Market
Medical Treatment
Chagas Disease Treatment Market
Medical Treatment
Single-Dose Therapy Market
Medical Treatment
Lyme Disease Treatment Market
Medical Treatment
Menopause Treatment Market
Medical Treatment
CINV Treatment Market
Medical Treatment
Skin Grafts Market
Medical Treatment
Global Leishmaniasis Treatment Market
Medical Treatment
Hypothermia Management Market
Medical Treatment
Acupuncture Treatment Market
Medical Treatment
Filariasis Treatment Market