
 US SNF Based Dialysis Market | 2026-2036
US SNF Based Dialysis Market Size, Share, and Industry Trends Forecast 2026-2036
US SNF Based Dialysis Market Intelligence
CMS Conditions of Participation for dialysis services is hardening the cost-of-entry calculus for new SNF operators. Genesis Healthcare leverages vertical integration across facility networks and in-house nephrology staffing to sustain operational scale in competitive states. Carespring anchors its position through dedicated dialysis wing investments that differentiate its SNF portfolio from general post-acute competitors.
US SNF based dialysis delivers renal replacement therapy within skilled nursing facilities using hemodialysis or peritoneal dialysis systems, typically requiring vascular access maintenance, dialysate delivery infrastructure, and on-site clinical monitoring for patients too frail for outpatient clinic transport. The primary purpose is to stabilize end-stage renal disease patients during post-acute recovery episodes while preventing costly acute hospitalization. Hemodialysis occupies the dominant revenue share given equipment standardization and reimbursement familiarity, while peritoneal dialysis represents the fastest-expanding modality as portable cycler technology reduces infrastructure burdens for smaller SNFs. Telehealth solutions within the technology dimension are capturing margin pools through remote nephrologist oversight that extends specialist reach without full-time staffing costs.
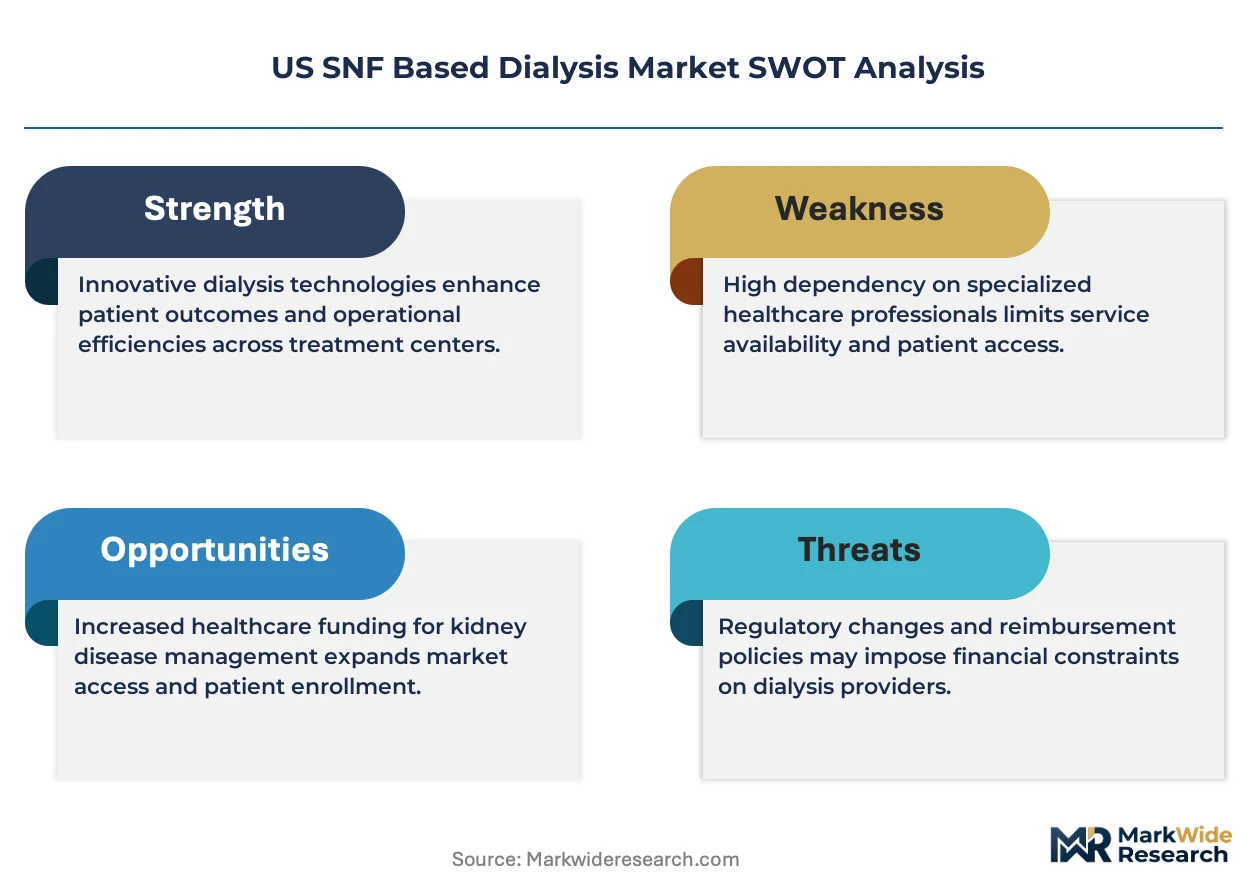
FDA device clearance requirements, CMS Conditions of Participation, and state-level Department of Health licensing standards collectively govern equipment validation, staff credentialing, and facility certification for in-facility dialysis operations. These overlapping frameworks elevate compliance spending but also create barriers that protect incumbents with established quality systems. Stakeholders must monitor CMS innovation center demonstrations for site-neutral payment shifts that could compress reimbursement advantages currently held by SNF-based programs.
Market Dynamics
CMS Conditions of Participation for dialysis services are hardening capital requirements for new SNF entrants, forcing operators to front-load compliance infrastructure before treating a single patient.
Growth Catalysts
- Texas bed density concentration:The state's overlapping elderly population expansion and SNF infrastructure buildout creates concentrated demand pools for in-facility renal services.
- Portable cycler technology maturation:Peritoneal dialysis systems now deploy with minimal plumbing retrofit, lowering facility conversion costs for smaller skilled nursing operators.
- Hospital readmission penalty frameworks:Medicare's value-based purchasing programs reward SNFs that stabilize ESRD patients in-house rather than transferring to acute settings.
Market Restraints
- Water purification infrastructure:Hemodialysis requires reverse osmosis systems and dialysate delivery loops that add $150,000-$400,000 per facility conversion.
- Nephrology staffing concentration:Board-certified specialists cluster in metropolitan hospital systems, leaving rural SNFs dependent on locum tenens or telehealth coverage.
- Peritoneal dialysis infection protocols:CMS Conditions of Participation mandate rigorous catheter site monitoring that strains nursing labor hours.
Strategic Opportunities
- Florida's post-acute corridor expansion:The I-4 and I-75 corridors show underpenetrated SNF bed growth where dialysis-ready facilities remain scarce.
- Telehealth nephrology convergence:Remote patient monitoring platforms paired with video consultation are collapsing specialist access barriers for mid-size operators.
- California's Medi-Cal managed care incentives:County-level contracts reward SNFs offering dialysis bundling that reduces emergency department utilization.
Industry Challenges
- Biomedical technician scarcity:Hemodialysis machine maintenance requires factory-certified repair capacity that competes with hospital systems for limited vendor field service.
- Multi-agency compliance synchronization:FDA device clearance, state Department of Health licensing, and CMS certification create overlapping inspection timelines that delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US SNF Based Dialysis Market |
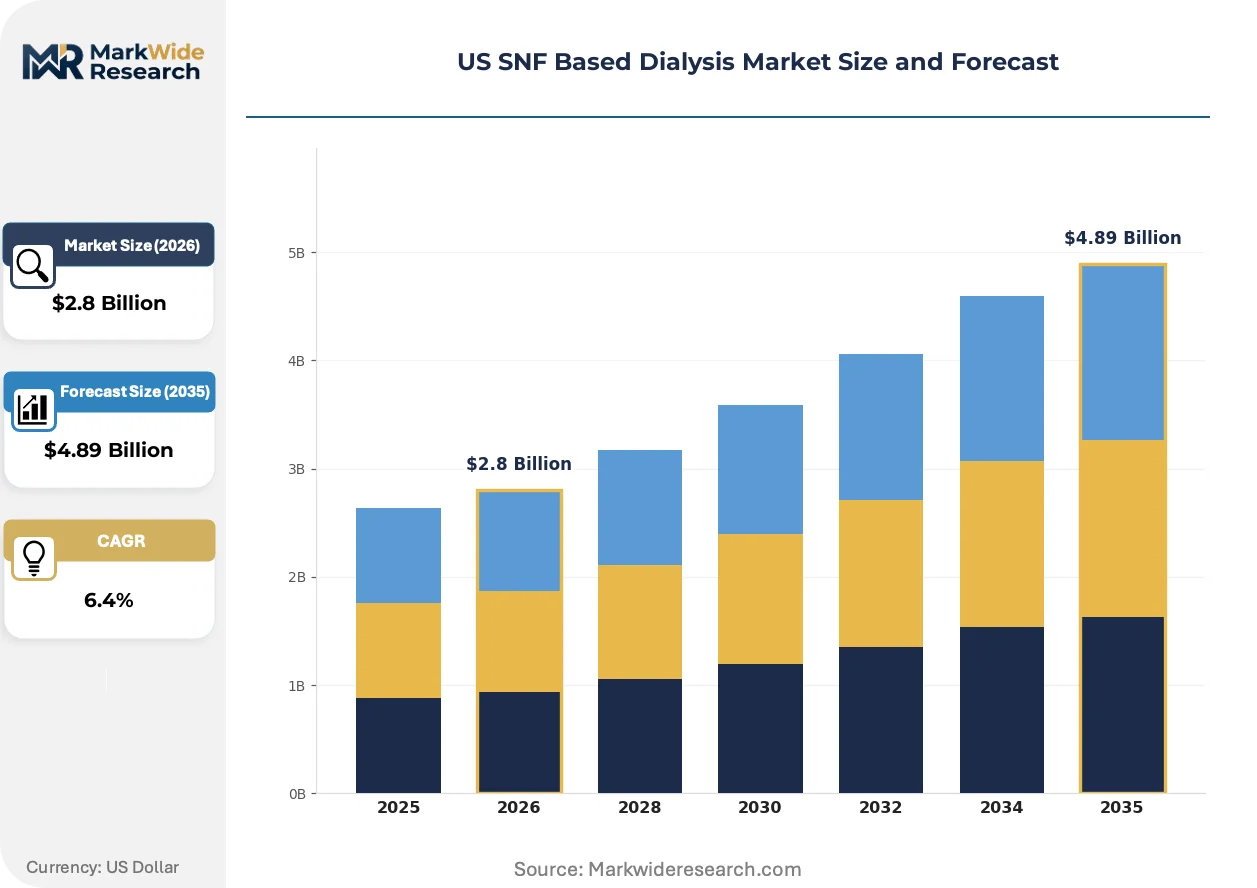
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemodialysis, Peritoneal Dialysis, Automated Dialysis, Continuous Ambulatory Dialysis End User: Skilled Nursing Facilities, Home Patients, Hospitals, Outpatient Clinics Delivery Mode: In-center Dialysis, Home Care, Mobile Units, Community Health Technology: Conventional Machines, Portable Devices, Telehealth Solutions, Robotic Assistance |
| Companies Covered | Carespring, Arbors Of Ohio, Genesis Healthcare, The Alden Network, MediLodge, Brickyard Healthcare, Generations Healthcare Network, Avalon Health Care, Plaza Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US SNF Based Dialysis Market Strategic Shifts & Innovations
Technology convergence between remote monitoring platforms and portable dialysis systems is collapsing the traditional trade-off between clinical intensity and facility flexibility.
Tablet-based cycler interfaces with cloud-connected vitals monitoring are absorbing the documentation burden that previously required bedside nursing presence during nocturnal peritoneal sessions. Mid-size SNFs in Florida and Arizona are adopting these systems faster than large chains, using reduced labor intensity to justify per-bed investments. The technology is absorbing margin pressure from stagnant Medicare reimbursement rates by extending nurse-to-patient ratios without quality compromise.
CMS Innovation Center demonstrations for site-neutral dialysis payments are forcing SNF operators to document cost parity with freestanding clinics. The policy trajectory threatens the historical reimbursement premium that justified in-facility capital deployment. Texas and California SNF networks are responding by consolidating purchasing through group purchasing organizations to extract equipment discounts that preserve margins under compressed rates.
Renal pharmaceutical bundling is reshaping how SNFs contract with dialysis service vendors. Post-acute operators increasingly demand all-inclusive per-treatment pricing that wraps erythropoiesis-stimulating agents, iron supplementation, and laboratory monitoring into single episode rates. This contracting evolution is most visible in competitive Medicare Advantage markets where SNFs compete for managed care network inclusion based on total cost predictability.
US SNF Based Dialysis Market Segmentation
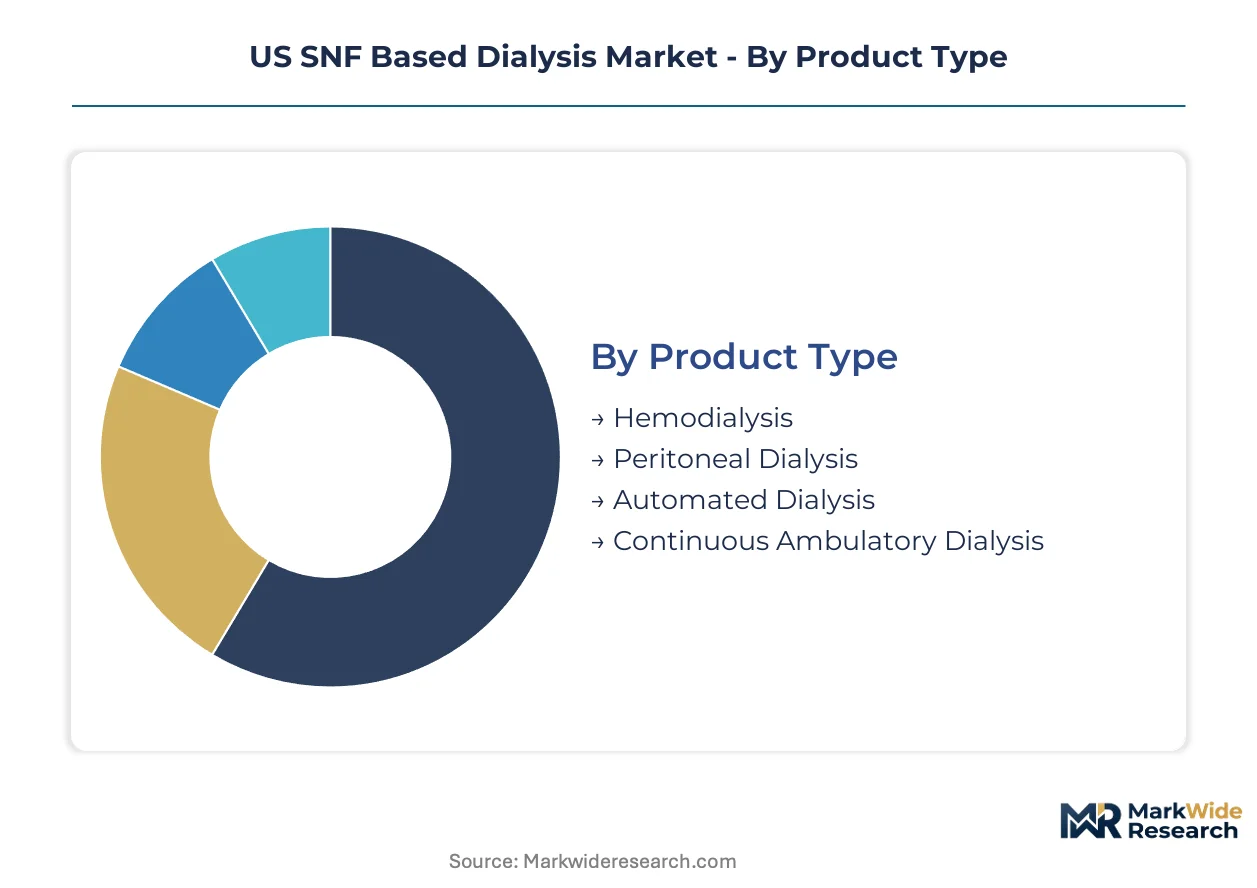
Segmentation reveals how capital allocation and reimbursement incentives fragment the US SNF based dialysis landscape. Product modality, care setting, and technology sophistication each command distinct margin profiles and compliance burdens.
Product Type:
Reimbursement familiarity drives buyer preference more than clinical outcomes alone.
- Hemodialysis:Blood filtration through external dialyzer circuits dominates SNF installations due to standardized Medicare billing codes and vendor service networks. Texas and Florida facilities concentrate demand here where elderly ESRD populations exceed peritoneal training capacity.
- Peritoneal Dialysis:Intraperitoneal fluid exchange via catheter leverages portable cycler technology that eliminates reverse osmosis infrastructure. California Medi-Cal managed care contracts favor this modality for reduced emergency department utilization.
- Automated Dialysis:Programmable nocturnal cycling systems reduce daytime nursing labor intensity.
- Continuous Ambulatory Dialysis:Manual exchange protocols suit patients with residual renal function.
Hemodialysis sits at the top of the volume ranking, with peritoneal dialysis climbing the fastest.
End User:
Site-of-care economics determine contracting leverage between operators and dialysis service vendors.
- Skilled Nursing Facilities:Post-acute operators bundle dialysis into per-diem rates, capturing margin from reduced transport costs and hospital readmission penalties. Arizona and Nevada SNFs lead adoption of in-house programs.
- Home Patients:Residential peritoneal dialysis with remote monitoring collapses facility overhead but requires caregiver training infrastructure.
- Hospitals:Acute inpatient dialysis serves hemodynamically unstable patients.
- Outpatient Clinics:Freestanding centers compete on convenience.
Skilled nursing facilities anchor current revenue concentration, though home patients are gaining share fastest as portable technology matures.
Delivery Mode:
Capital intensity and staffing models diverge sharply across physical versus virtual care channels.
- In-center Dialysis:Fixed-site hemodialysis suites within SNF wings require FDA-cleared water purification systems and CMS-certified biomedical technicians. Georgia and North Carolina operators favor this for predictable census planning.
- Home Care:Patient-directed peritoneal dialysis with telehealth oversight extends specialist reach without permanent staffing.
- Mobile Units:Van-based hemodialysis serves rural geographies.
- Community Health:Shared dialysis stations reduce per-treatment costs.
In-center dialysis maintains the steepest volume base, while home care shows the steepest expansion trajectory.
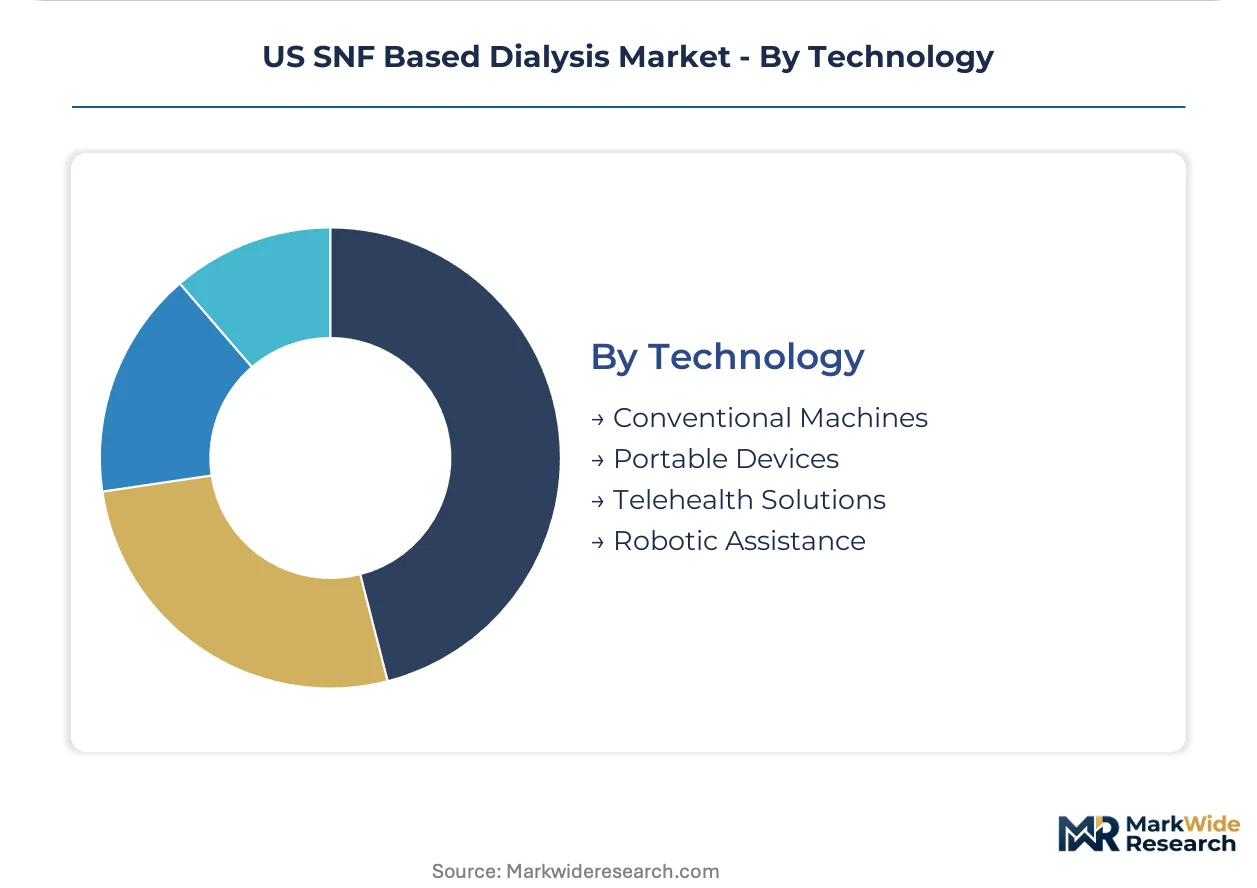
Technology:
Equipment sophistication determines which operators can meet tightening CMS Conditions of Participation.
- Conventional Machines:Stationary hemodialysis consoles with integrated dialysate delivery dominate existing SNF installations. Midwest operators prioritize these for technician familiarity and spare parts availability.
- Portable Devices:Battery-operated systems enable bedside treatment without dedicated plumbing infrastructure.
- Telehealth Solutions:Cloud-connected vitals monitoring with video nephrology consultation reduces rural staffing gaps.
- Robotic Assistance:Automated cannulation and line management systems address nursing labor scarcity.
Conventional machines still command the largest installed base, with telehealth solutions expanding most quickly as labor costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Board-certified nephrologists and dialysis-trained nurses cluster in Texas, Florida, and California, anchoring the geographic concentration of SNF-based dialysis capacity. These three states absorb the bulk of capital deployment as operators chase elderly population growth and favorable reimbursement environments. Sub-regional variation within each state determines where new programs launch versus where existing facilities expand.
Texas
Houston and Dallas-Fort Worth metro areas drive demand through overlapping SNF bed construction and ESRD prevalence expansion. CMS Conditions of Participation enforcement tightens fastest here, forcing operators to front-load compliance infrastructure. The I-35 corridor from San Antonio to Austin shows underpenetrated capacity where mid-size operators target greenfield dialysis wing investments.
Florida
Snowbird migration patterns and year-round elderly residency inflate per-capita dialysis need across the Tampa-Orlando corridor. State Department of Health licensing standards for in-facility water purification exceed federal baselines, elevating capital thresholds for new entrants. The I-4 corridor between Daytona Beach and Lakeland remains dialysis-ready facility scarce despite rapid SNF bed growth.
California
Los Angeles County and Orange County concentrate both SNF infrastructure and Medi-Cal managed care contract volume. County-level contracts reward dialysis bundling that reduces emergency department utilization, reshaping vendor selection criteria. The Inland Empire and Central Valley show emerging demand as SNF operators follow population dispersal from coastal metros.
Arizona
Phoenix and Tucson metro areas attract post-acute operators through lower facility conversion costs and lighter state-level staffing mandates. Medicare Advantage penetration runs higher here than national averages, accelerating all-inclusive per-treatment contracting with dialysis service vendors. Rural Mohave and Yuma counties depend on telehealth nephrology coverage to sustain programs.
Ohio
Cleveland and Cincinnati anchor the Midwest's strongest SNF dialysis concentration outside the Sun Belt. Arbors Of Ohio and similar regional operators exploit lower biomedical technician wage costs to sustain hemodialysis machine maintenance networks. State Medicaid waiver programs for nursing facility level-of-care determinations shape patient eligibility flows.
US SNF Based Dialysis Market Key Industry Players
The competitive structure tilts toward vertically integrated post-acute chains and specialized dialysis service vendors. Consolidation pressure intensifies as CMS site-neutral payment demonstrations threaten historical reimbursement premiums. Two archetypes dominate: multi-state SNF operators with captive nephrology staffing, and dialysis-focused vendors supplying equipment and clinical labor to facility partners. Competitive moves concentrate on group purchasing organization consolidation and telehealth platform licensing to collapse specialist access costs.
Within the integrated post-acute tier, Genesis Healthcare exemplifies scale-driven positioning across competitive states, while Carespring anchors differentiation through dedicated dialysis wing investments. Avalon Health Care occupies a position between these poles, balancing geographic breadth with modality-specific infrastructure. MediLodge and The Alden Network represent regional concentration strategies that exploit state-level regulatory familiarity to defend local market position.
| Leading Market Players |
|---|
| Carespring |
| Arbors Of Ohio |
| Genesis Healthcare |
| The Alden Network |
| MediLodge |
| Brickyard Healthcare |
| Generations Healthcare Network |
| Avalon Health Care |
| Plaza Healthcare |
| Others |
Cost & Logistics Intelligence
Reverse osmosis membrane pricing indices cascade through SNF dialysis supply chains into three distinct service tiers. Equipment-heavy hemodialysis programs absorb premium capital costs that peritoneal cycler deployments sidestep, while telehealth-augmented models occupy a mid-market position on labor substitution.
Pricing Analysis
Bundled per-treatment rates dominate SNF dialysis contracting against unbundled fee-for-service alternatives. Price differentiation hinges on nephrologist staffing intensity and FDA device certification tier, with Medicare Advantage plans showing lowest price sensitivity and independent rural facilities highest. Cost compression in standard-tier services is intensifying because CMS site-neutral payment demonstrations threaten historical reimbursement premiums.
Supply Chain Analysis
Factory-certified biomedical technician scarcity in Ohio and Texas concentrates hemodialysis machine maintenance capacity around regional hospital systems. Equipment sourcing draws from domestic FDA-cleared manufacturers and European dialyzer suppliers, with dialysate concentrate and vascular access kits as critical consumables. Single-source vulnerability in reverse osmosis membrane supply creates exposure to pharmaceutical-grade polymer allocation. Distribution runs through specialized dialysis service vendors that embed clinical labor with equipment leases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US SNF dialysis rests on portable cycler technology reducing per-bed infrastructure outlays and telehealth platforms collapsing specialist staffing premiums. Operators capturing these cost-down trajectories while preserving quality benchmarks will widen spreads against legacy hemodialysis-dependent competitors.
For Market Incumbents: Extend captive nephrology staffing networks into telehealth overlays that preserve rural program viability without permanent specialist deployment. Consolidate purchasing through group purchasing organizations to extract equipment discounts that defend spreads under compressed CMS reimbursement. Genesis Healthcare and Carespring demonstrate how vertical integration of clinical labor with facility operations creates switching costs against dialysis service vendors. For New Entrants and Emerging Players: The premium-economy price-point gap in rural Texas and Florida I-4 corridor markets offers white-space entry below integrated chain rates. Target greenfield peritoneal dialysis programs in underpenetrated SNF bed growth zones where portable cycler technology eliminates reverse osmosis capital barriers. Partner with telehealth nephrology platforms to collapse specialist access costs without full-time hiring. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-size SNF operators in Arizona and Nevada possessing Medicare Advantage contracting density but lacking in-house dialysis infrastructure. Long-term viability favors platforms with scalable peritoneal dialysis adoption and telehealth integration rather than hemodialysis-heavy legacy footprints. Watch CMS Innovation Center site-neutral payment demonstration expansion as the critical inflection signal for reimbursement compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Nephrology Platform Licensing | Extends specialist reach to rural SNFs without permanent staffing costs. |
| Peritoneal Dialysis Cycler Fleet Expansion | Reduces facility conversion capital versus hemodialysis infrastructure. |
| Group Purchasing Organization Consolidation | Extracts equipment discounts preserving margins under CMS rate pressure. |
| CMS Conditions of Participation Pre-Certification | Accelerates program launch timelines against inspection backlog. |
| Medicare Advantage Bundled Contracting | Captures managed care network inclusion through total cost predictability. |
Research Approach
Multiple input streams — SNF operator interviews, dialysis service vendor discussions, CMS reimbursement database analysis — were reconciled to construct market estimates. Primary fieldwork engaged post-acute care executives, biomedical engineering directors, nephrology practice administrators, and GPO contracting managers across Texas, Florida, California, Arizona, and Ohio. Secondary validation drew from FDA 510(k) device clearances, CMS Medicare cost reports, state Department of Health licensing records, and hospital procurement databases. Bottom-up facility census modeling and top-down reimbursement flow analysis were cross-referenced for triangulation.
Historical utilization trends were cross-referenced against expert panel input on technology adoption curves across the projection horizon. Segmentation dimensions modeled include dialysis modality, care delivery setting, technology sophistication tier, and state-level regulatory cluster. CAGRs were derived from slope analysis of reimbursement rate trajectories and capital deployment patterns. Forecast inputs incorporated portable cycler technology maturation curves and telehealth platform penetration benchmarks specific to post-acute renal care.
Caveats apply where CMS site-neutral payment rule finalization or FDA device clearance delays could materially shift the outlook. Forecasts reflect assumptions on Medicare Advantage penetration rates and state-level Medicaid waiver stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Passive Prosthetics Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Small Bowel Enteroscopes Market
Medical Devices
Gum Grafting Market
Medical Devices
Breast Prosthesis Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Global Venous Blood Collection Devices Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Peripheral Nerve Stimulators Market