
 Nephrosclerosis Treatment Market | 2026-2036
Nephrosclerosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Nephrosclerosis Treatment Market Analytics
Next-generation renoprotective efficacy standards is unwinding older prescribing patterns across nephrosclerosis care. Pfizer Inc. leverages its cardiovascular-nephrology crossover pipeline to sustain institutional formulary presence. Novartis AG anchors European nephrology practice through long-standing ACE inhibitor franchises. AstraZeneca differentiates via SGLT2 inhibitor expansion into chronic kidney disease protocols.
Nephrosclerosis denotes pathological hardening and constriction of renal arterioles, typically characterized by hyaline thickening of vessel walls and progressive glomerular ischemia, which impairs filtration and elevates systemic blood pressure. The condition serves as both a sequela of chronic hypertension and an independent accelerant of end-stage renal disease, requiring pharmacological intervention to preserve residual kidney function. Antihypertensives and ACE inhibitors capture dominant share as first-line modalities, while oral delivery mode retains volume leadership due to outpatient manageability and payer preference for non-infusion therapy. Hospitals and nephrology clinics concentrate margin pools through bundled chronic kidney disease management contracts.
FDA renal impairment guidance and EMA pharmacovigilance standards for cardiovascular-renal drugs shape trial design and label claims across the development pipeline. The European Medicines Agency's evolving renal safety requirements and Japan's PMDA geriatric dosing protocols add compliance layers for multinational sponsors. Stakeholders must monitor how renal outcome trials redirect investment between established antihypertensive classes and emerging fibrosis-targeting mechanisms.
Market Dynamics
Renal outcome trials are forcing cardiovascular drug developers to redesign Phase III protocols around hard kidney endpoints rather than surrogate blood pressure metrics, compressing timelines for nephrology-specific label expansions.
Growth Catalysts
- EMA pharmacovigilance standards:Tighter renal safety monitoring for cardiovascular drugs creates demand for dedicated nephrology trial infrastructure and specialized CRO services.
- Hospital-based bundled contracts:Chronic kidney disease management agreements concentrate purchasing power within integrated health systems, favoring suppliers with full protocol portfolios.
- Japan's PMDA geriatric dosing protocols:Explicit guidance for dose adjustment in elderly patients with impaired renal function accelerates market entry for reformulated antihypertensives.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of ACE inhibitor intermediates clusters in specific Asian manufacturing zones, exposing supply chains to single-source vulnerability.
- FDA renal impairment guidance complexity:Evolving requirements for pharmacokinetic studies in severe renal dysfunction extend development timelines and inflate trial costs.
- Generic substitution pressure:Patent expirations on established ARB molecules compress branded pricing power in outpatient pharmacy channels.
Strategic Opportunities
- Germany's dialysis infrastructure density:Established networks of nephrology clinics create ready channels for novel fibrosis-targeting agents entering chronic kidney disease protocols.
- SGLT2 inhibitor expansion:Cardiology-to-nephrology indication broadening opens reimbursement pathways previously restricted to endocrinology budgets.
- Remote patient monitoring integration:Home blood pressure telemetry paired with medication adherence platforms enables risk-based contracting with Medicare Advantage plans.
Industry Challenges
- Nephrology trial recruitment:Competing cardiovascular outcome studies drain the limited pool of patients with diabetic kidney disease eligible for interventional protocols.
- Legacy electronic health record interoperability:Disconnected renal function databases across hospital systems impede real-world evidence generation for payer negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nephrosclerosis Treatment Market |
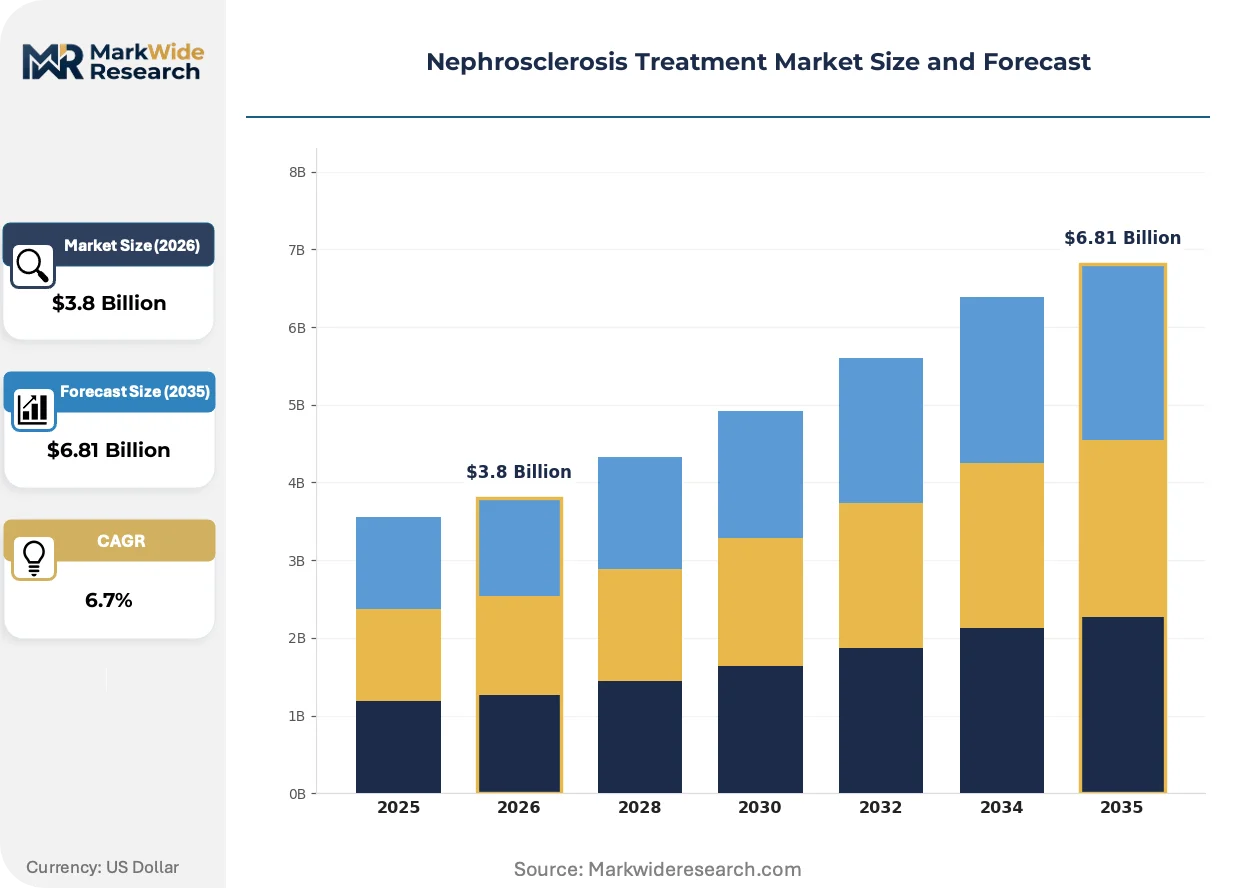
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihypertensives, Diuretics, ACE Inhibitors, Statins Delivery Mode: Oral, Injectable, Intravenous, Topical End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Therapy Area: Cardiology, Nephrology, Internal Medicine, Primary Care |
| Companies Covered | Merck Ltd., Teva Pharmaceutical Industries Ltd., Akorn Inc., Pfizer Inc., Bristol-Myers Squibb Company, Astellas Pharmaceuticals, AstraZeneca, Novartis AG, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nephrosclerosis Treatment Market Evolving Landscape
Precision dosing algorithms and biomarker-guided therapy selection are displacing empirical prescribing in nephrosclerosis management, compressing the gap between cardiovascular and renal specialty care.
Sodium-glucose cotransporter-2 inhibitors are decomposing the traditional boundary between diabetes and nephrology prescribing, with cardiologists now initiating these agents for albuminuria reduction independent of glycemic status. Nephrology departments in US academic medical centers are absorbing these patients into co-managed protocols. The structural consequence is a compression of referral patterns that previously funneled progressive chronic kidney disease exclusively to endocrinology.
REACH registration requirements in Europe now mandate explicit renal hazard classification for industrial chemicals with systemic exposure potential, forcing pharmaceutical manufacturers to front-load nephrotoxicity screening in early discovery. Contract research organizations serving the sector have expanded rodent renal function panels to satisfy dossier expectations. German and French regulatory submissions now face extended review cycles where renal safety signals trigger mandatory expert consultation.
Integrated pharmacy benefit managers are consolidating antihypertensive formulary decisions across commercial and Medicare lines, compressing physician autonomy in agent selection. Nephrology practices in the United States are responding by developing in-house specialty pharmacies to capture dispensing margin and preserve therapeutic flexibility. This channel consolidation is most advanced in Florida and Texas markets where vertically integrated health plans dominate regional coverage.
Nephrosclerosis Treatment Market Segmentation
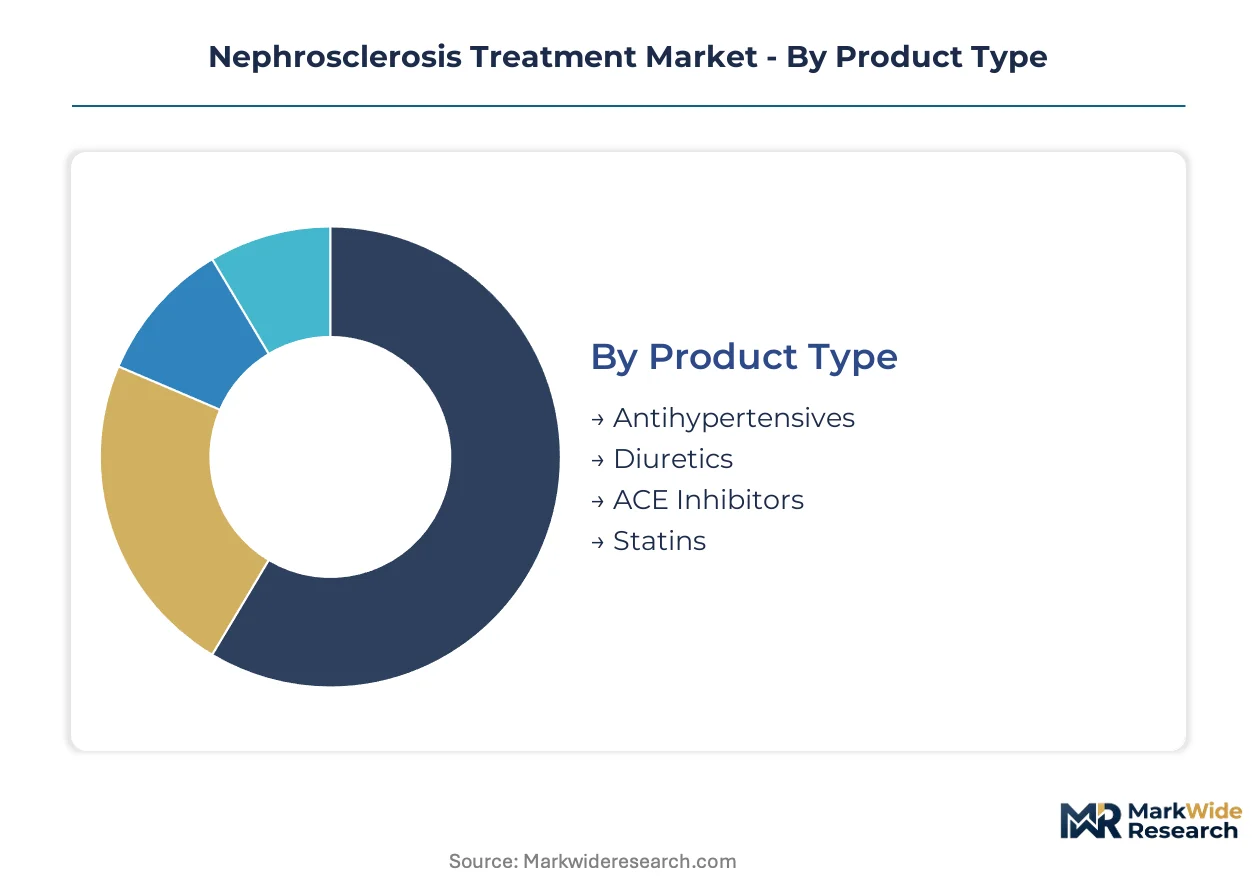
Segmentation in nephrosclerosis treatment reveals how prescribing authority, reimbursement pathways, and patient acuity reshape demand across product categories. Understanding these fault lines enables suppliers to align portfolio investments with where clinical decision-making and purchasing power actually concentrate.
Product Type:
Generic substitution pressure varies sharply across pharmacological classes, with some segments facing commoditization while others retain therapeutic distinctiveness.
- Antihypertensives:Calcium channel blockers and beta-blockers form the backbone of blood pressure control in hypertensive nephropathy. Demand concentrates in outpatient pharmacy channels across the United States and Germany, where payer formularies drive preferential prescribing toward specific molecules with established renal safety profiles.
- ACE Inhibitors:These agents reduce intraglomerular pressure through efferent arteriolar dilation, preserving filtration function in progressive disease. Japanese nephrology practices favor long-acting formulations compliant with PMDA geriatric dosing protocols, creating sustained demand for reformulated derivatives.
- Diuretics:Loop and thiazide diuretics manage volume overload in sodium-retentive patients.
- Statins:Lipid-lowering therapy addresses cardiovascular comorbidity in chronic kidney disease populations.
Antihypertensives retain volume leadership; ACE Inhibitors hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification separates inpatient acute intervention from chronic outpatient maintenance, with reimbursement differentials widening between administration settings.
- Oral:Tablets and capsules dominate chronic maintenance therapy due to outpatient manageability and Medicare Part D coverage alignment. Payer preference for non-infusion therapy reinforces volume concentration in retail pharmacy and mail-order channels.
- Injectable:Subcutaneous formulations serve hospitalized patients with acute hypertensive crises or oral intolerance. German bundled dialysis contracts increasingly specify injectable antihypertensives for in-clinic administration.
- Intravenous:Reserved for emergency blood pressure management and perioperative care in surgical nephrology.
- Topical:Minimal penetration in nephrosclerosis; limited to adjuvant applications.
Oral formulations capture the largest patient population; injectable delivery is climbing fastest through integrated kidney care contracts.
End User:
Customer type fragmentation reflects diverging procurement sophistication, with institutional buyers extracting price concessions unavailable to dispersed outpatient settings.
- Hospitals:Academic medical centers and community hospital systems command purchasing leverage through therapeutic interchange committees and 340B drug pricing programs. Nephrology departments within these institutions increasingly bundle chronic kidney disease management contracts that lock in preferred agent selection.
- Clinics:Independent nephrology practices and dialysis centers face reimbursement compression under Medicare's ESRD prospective payment system. Florida and Texas markets show advanced vertical integration where clinic-owned specialty pharmacies capture dispensing margin.
- Home Care:Home health agencies manage post-discharge medication adherence for complex patients.
- Rehabilitation Centers:Skilled nursing facilities handle transitional care for acute kidney injury recovery.
Hospitals concentrate purchasing power; clinics are gaining share fastest through specialty pharmacy integration.
Therapy Area:
Prescribing authority migration between specialties is redrawing competitive boundaries, with cardiology encroaching on traditional nephrology domains.
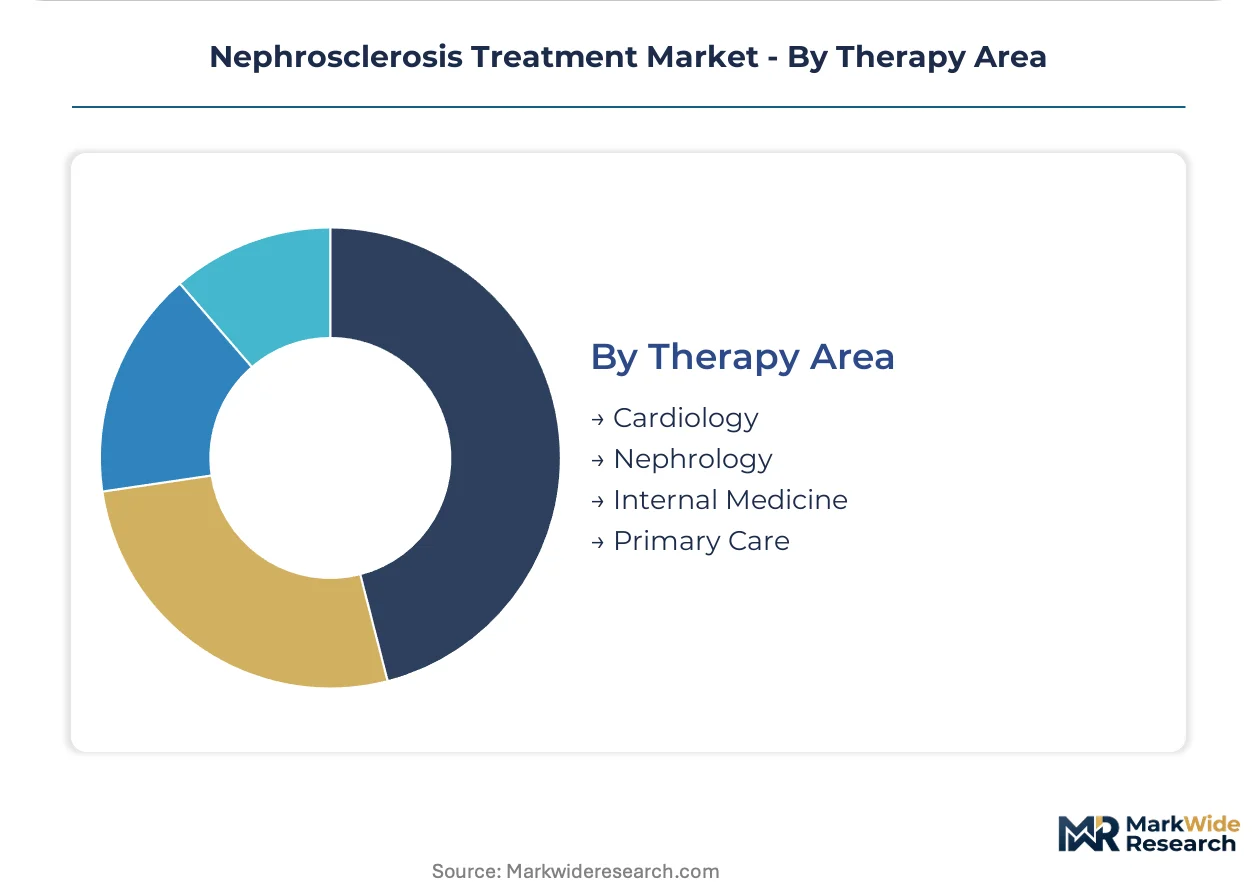
- Nephrology:Board-certified nephrologists retain authority over advanced chronic kidney disease and dialysis-dependent populations. United States academic medical centers are absorbing SGLT2 inhibitor initiations from cardiology into co-managed protocols, preserving specialty relevance.
- Cardiology:Cardiologists now initiate renoprotective therapy for albuminuric patients independent of glycemic status, compressing traditional referral patterns. European and Japanese cardiology practices are expanding nephrology-relevant prescribing through updated society guidelines.
- Internal Medicine:Hospitalists and generalists manage early-stage hypertensive nephropathy detection.
- Primary Care:Family physicians handle initial blood pressure control and specialist referral triage.
Nephrology retains procedural authority; cardiology is expanding fastest through indication broadening and guideline updates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for active pharmaceutical ingredients tilts the trade balance across major nephrosclerosis markets, with finished formulation exports running ahead of intermediate chemical imports in Germany and Japan while the United States remains a net importer of generic antihypertensive raw materials.
United States
Medicare Advantage bundled contracts concentrate purchasing power within integrated health systems across Florida and Texas, where vertically aligned plans dominate regional coverage. FDA renal impairment guidance for cardiovascular drugs extends development timelines for sponsors targeting chronic kidney disease label expansions. Boston and San Francisco academic medical centers absorb SGLT2 inhibitor initiations from cardiology into co-managed nephrology protocols.
Germany
Established dialysis infrastructure networks create ready distribution channels for novel fibrosis-targeting agents entering chronic kidney disease management. EMA pharmacovigilance standards mandate explicit renal safety monitoring in cardiovascular drug trials, forcing front-loaded nephrotoxicity screening. The Rhine-Ruhr and Bavarian nephrology clinic clusters specify injectable antihypertensives for in-clinic administration under bundled contracts.
Japan
Aging demographics sustain patient volumes for antihypertensive therapy within PMDA geriatric dosing compliance frameworks. METI industrial policy supports domestic manufacturing of reformulated long-acting ACE inhibitors tailored to elderly renal function profiles. Osaka and Nagoya pharmaceutical production zones supply regional Asian markets with PMDA-compliant antihypertensive derivatives.
United Kingdom
NHS Integrated Care Systems consolidate antihypertensive formulary decisions across primary and secondary care boundaries, compressing physician agent selection autonomy. NICE technology appraisals increasingly require hard renal endpoints rather than surrogate blood pressure metrics for reimbursement eligibility. The Greater Manchester and West Midlands nephrology networks pilot risk-based contracting with home blood pressure telemetry platforms.
India
Domestic manufacturing of ACE inhibitor intermediates clusters in Andhra Pradesh and Gujarat, supplying global generic markets with cost-competitive active pharmaceutical ingredients. CDSCO accelerated approval pathways for reformulated antihypertensives attract multinational sponsors seeking geriatric-specific dosing protocols. Hyderabad and Ahmedabad contract research organizations expand rodent renal function panels to satisfy European REACH registration requirements for pharmaceutical intermediates.
Nephrosclerosis Treatment Market Competitive Landscape
Concentration sits with diversified pharmaceutical conglomerates that leverage cardiovascular-nephrology crossover pipelines to sustain institutional formulary presence. The market structure tiers between global innovators with renal outcome trial capabilities, generic manufacturers competing on API cost position, and regional specialists capturing bundled dialysis contracts. Two dominant competitive moves define current positioning: strategic partnerships between cardiology and nephrology service lines to capture SGLT2 inhibitor prescribing migration, and backward integration into active pharmaceutical ingredient production to secure supply chain resilience against Asian manufacturing concentration.
Among the diversified pharmaceutical majors, Pfizer Inc., Novartis AG, and AstraZeneca occupy positions that exemplify distinct competitive archetypes. Pfizer represents the cardiovascular-nephrology crossover model with institutional formulary leverage across hospital systems. Novartis anchors European nephrology practice through established ACE inhibitor franchises and long-standing prescriber relationships. AstraZeneca exemplifies indication-broadening strategy, with SGLT2 inhibitor expansion into chronic kidney disease protocols opening reimbursement pathways beyond traditional endocrinology budgets.
| Leading Market Players |
|---|
| Merck Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Akorn Inc. |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| Astellas Pharmaceuticals |
| AstraZeneca |
| Novartis AG |
| Sanofi |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day API inventory buffers at European formulation sites compress margin recovery timelines when Asian intermediate prices spike, concentrating pricing power with manufacturers holding captive synthesis capabilities or long-term offtake agreements with Indian and Chinese suppliers.
Pricing Analysis
Hospital procurement committees anchor antihypertensive pricing through therapeutic interchange protocols and 340B drug pricing programs. Three-tier pricing structure across originator brands, authorized generics, and commodity generics segments the market by prescriber autonomy and reimbursement pathway. Pricing pressure stems from Medicare Advantage bundled contracts that extract volume discounts for chronic kidney disease management protocols. Dialysis-dependent populations show lowest price sensitivity due to limited therapeutic alternatives, while outpatient pharmacy channels face intense generic substitution pressure.
Supply Chain Analysis
Strategic stockpiling of ACE inhibitor intermediates dominates procurement strategy among multinational sponsors exposed to REACH registration delays and EMA pharmacovigilance documentation requirements. Active pharmaceutical ingredient synthesis clusters in Andhra Pradesh and Gujarat, India, with formulation finishing concentrated in Germany, Japan, and the United States. Key dependencies include lisinopril dihydrate, enalapril maleate precursors, and specialized renal safety testing reagents. Single-source vulnerability in thiazide diuretic intermediate production creates tariff exposure risk. Distribution runs through integrated pharmacy benefit managers and hospital 340B programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized nephrology trial infrastructure represents the critical scarcity asset, with limited CRO capacity for renal outcome studies and competing cardiovascular protocols draining eligible patient pools faster than recruitment networks can expand.
For Market Incumbents: Consolidate formulary position through backward integration into API production for ACE inhibitor intermediates, securing supply resilience against Indian manufacturing concentration. Deepen hospital system partnerships to capture SGLT2 inhibitor prescribing migration from cardiology into co-managed nephrology protocols. Lock in bundled dialysis contracts in Germany and Florida markets before vertical integration by regional clinic chains accelerates. For New Entrants and Emerging Players: Anchor in fibrosis-targeting mechanisms for chronic kidney disease progression, where clinical unmet need exceeds competitive intensity. Target Japan's PMDA geriatric dosing protocols as the most penetrable regulatory pathway for reformulated long-acting antihypertensives. Build go-to-market presence through specialty pharmacy integration in vertically integrated Texas and Florida health systems. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because nephrology-specific CRO capabilities and renal outcome trial infrastructure are accumulating scarcity premiums as cardiovascular drug developers front-load nephrotoxicity screening. Acquisition targets should display established FDA renal impairment guidance compliance and EMA pharmacovigilance dossier experience. Watch for inflection when SGLT2 inhibitor label expansions trigger hospital formulary renegotiation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Renal Outcome Trial Infrastructure Investment | EMA pharmacovigilance standards mandate dedicated nephrology CRO capacity for cardiovascular drug submissions. |
| API Backward Integration | Captive supply of ACE inhibitor intermediates insulates against single-source concentration in Indian manufacturing zones. |
| Specialty Pharmacy Channel Development | Vertically integrated Florida and Texas clinic networks capture dispensing margin under Medicare Advantage risk contracts. |
| SGLT2 Indication Broadening | FDA renal impairment guidance compliance opens reimbursement pathways beyond endocrinology budgets into nephrology protocols. |
| Precision Dosing Algorithm Partnerships | Home blood pressure telemetry integration enables risk-based contracting with Medicare Advantage plans. |
Research Methodology
A spread of perspectives from nephrology department heads, formulary directors at integrated health systems, regulatory affairs leads at cardiovascular-nephrology crossover sponsors, and procurement managers at German dialysis clinic networks converged on the working assumptions. Primary interview insights triangulated against FDA renal impairment guidance documents, EMA pharmacovigilance assessment reports, ClinicalTrials.gov renal outcome study protocols, and Medicare Advantage bundled contract filings. Bottom-up patient volume estimates and top-down pharmaceutical revenue allocations were reconciled across the analysis window.
Segmentation dimensions modeled include pharmacological class, delivery mode, end-user institution type, and therapy area prescribing authority across the projection horizon. CAGRs were derived from trend extrapolation of hospital-based adoption curves and payer formulary placement velocity. Forecast inputs incorporated PMDA geriatric dosing protocol compliance rates, REACH registration requirement expansion timelines, and specialty pharmacy integration penetration in Florida and Texas markets.
Underlying assumptions cover sustained FDA and EMA renal safety monitoring intensity, with deviation risk concentrated in generic substitution acceleration for ARB molecules and API supply disruption from Indian manufacturing zones. Revision becomes warranted when SGLT2 inhibitor cardiology-to-nephrology prescribing migration crosses institutional protocol adoption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Global Hemodialysis Market
Nephrology
Global Renal Medical Devices and Services Market
Nephrology
Global Dialysis Market
Nephrology
US Dialysis Centers Market
Nephrology
Plasmapheresis Market
Nephrology
Kidney/Renal Function Test Market
Nephrology
Global Dialyzer Market
Nephrology
Global Diabetic Nephropathy Market
Nephrology
Renal Cell Carcinoma Market
Nephrology
Hemodialyzer Market
Nephrology
Complement 3 Glomerulopathy (C3G) Treatment Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Arteriovenous Fistula Treatment Market