
 Blood Dialyzer Market | 2026-2036
Blood Dialyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Dialyzer Market Outlook
Home healthcare procurement is expanding as payers push renal care beyond traditional clinic settings. Fresenius Medical Care AG & Co. KGaA leverages its vertically integrated dialysis service network to secure captive dialyzer demand. Baxter International Inc. competes through specialized CRRT-compatible membrane portfolios. Asahi Kasei Corporation anchors Asian supply chains with hollow-fiber manufacturing scale.
A blood dialyzer is a hollow-fiber membrane device that removes metabolic waste and excess fluid from blood during extracorporeal renal replacement, typically operating with ultrafiltration coefficients between 10-60 mL/h/mmHg depending on membrane permeability. High-flux dialyzers dominate value pools due to superior middle-molecule clearance and reduced treatment times, while synthetic dialyzers lead volume growth as polysulfone and polyethersulfone membranes displace cellulosic alternatives. Dialysis centers represent the most concentrated end-user channel, though home healthcare segments attract investment as portable hemodialysis technology matures.
The FDA enforces 510(k) clearance and biocompatibility standards under ISO 10993 for all dialyzer membranes entering the US market, while the EU Medical Device Regulation requires notified-body certification and post-market surveillance through EUDAMED. Japan's PMDA mandates Japan Industrial Standards compliance for imported dialyzers, creating additional testing layers for Western manufacturers. Stakeholders must monitor reimbursement rate negotiations between CMS and dialysis providers, as these directly constrain the total addressable spend on consumable devices.
Market Dynamics
Fresenius Medical Care's vertically integrated dialysis service network captures captive dialyzer demand, while Medicare reimbursement policies lock in volume commitments that shape manufacturer capacity planning across the United States.
Growth Catalysts
- High-flux membrane adoption:Polysulfone and polyethersulfone synthetic membranes displace cellulosic alternatives in dialysis centers seeking superior middle-molecule clearance.
- CMS reimbursement stability:Medicare's bundled payment model for dialysis treatment sustains predictable procurement volumes for Class II medical device manufacturers.
- Aging demographics:Chronic kidney disease prevalence rises among populations over 65, expanding hospital and clinic procurement of extracorporeal renal replacement devices.
Market Restraints
- Biocompatibility testing costs:FDA's strengthened ISO 10993 compliance requirements for hollow-fiber membranes inflate pre-market validation expenses for new entrants.
- Supply concentration:Hollow-fiber manufacturing scale concentrates in Asian production clusters, exposing Western brands to logistics disruptions and tariff exposure.
- Home hemodialysis limitations:Portable system complexity and training requirements constrain patient self-administration despite payer pressure for site-of-care migration.
Strategic Opportunities
- Portable hemodialysis maturation:Device miniaturization and membrane efficiency gains enable home healthcare segments previously restricted to clinic settings.
- CRRT membrane specialization:Continuous renal replacement therapy-compatible portfolios address ICU demand for acute kidney injury management outside chronic dialysis.
- EU MDR certification leverage:Notified-body certification under the Medical Device Regulation creates competitive differentiation for manufacturers with EUDAMED surveillance capabilities.
Industry Challenges
- 510(k) clearance timelines:FDA backlog for Class II device submissions extends time-to-revenue for membrane innovations.
- Membrane characterization expertise:Ultrafiltration coefficient optimization and endotoxin retention validation require specialized polymer science talent in short supply.
- Legacy clinic infrastructure:Water purification system incompatibility with high-flux dialyzers forces capital reinvestment at dialysis centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Dialyzer Market |
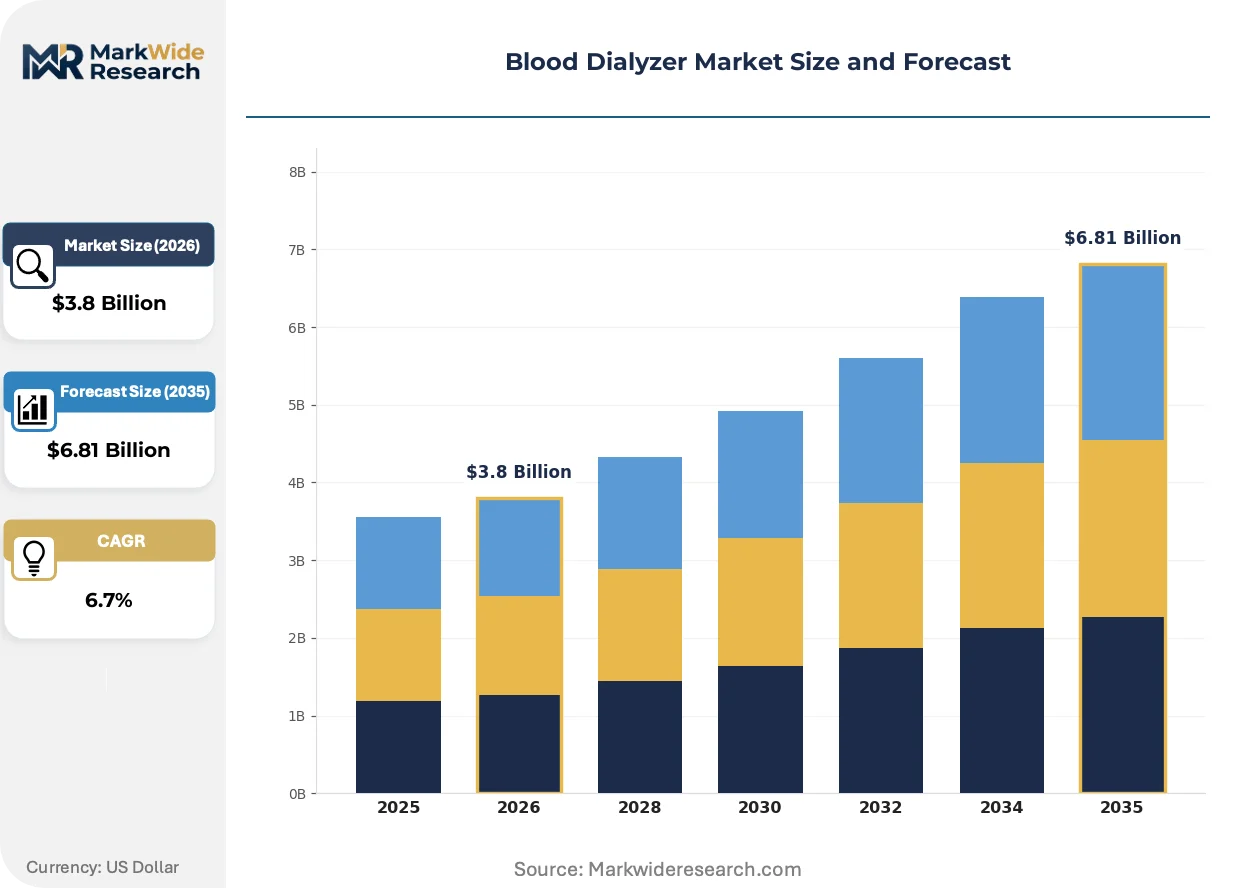
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Flux Dialyzers, Low-Flux Dialyzers, Synthetic Dialyzers, Cellulosic Dialyzers End User: Hospitals, Dialysis Centers, Home Healthcare, Specialty Clinics Material: Polyethersulfone, Cellulose Acetate, Polyamide, Polypropylene Technology: Hemodialysis, Continuous Renal Replacement Therapy, Hybrid Systems, Portable Dialysis |
| Companies Covered | Fresenius Medical Care AG & Co. KGaA, Baxter International Inc., B. Braun Melsungen AG, Nikkiso Co., Ltd., Nipro Corporation, Medtronic plc, Asahi Kasei Corporation, Toray Industries, Inc., Kawasumi Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Dialyzer Market Strategic Shifts
Synthetic membrane chemistry advances and portable system engineering are compressing treatment site requirements while regulatory frameworks in major markets tighten post-market surveillance obligations.
Hollow-fiber dialyzers with enhanced biocompatibility coatings are decentralizing renal replacement therapy from centralized dialysis centers toward residential settings. Home healthcare agencies and payer networks are accelerating adoption of compact systems with simplified priming protocols. This migration is decentralizing the historical site-of-care monopoly held by outpatient dialysis clinics and redistributing device consumption across dispersed patient populations.
The EU Medical Device Regulation mandates notified-body certification and EUDAMED post-market surveillance for all dialyzers entering European markets. Manufacturers must maintain technical documentation and vigilance reporting systems that exceed prior Medical Device Directive requirements. High-flux synthetic dialyzer categories face the steepest compliance burdens as notified bodies scrutinize membrane biocompatibility data more intensively than legacy cellulose-based alternatives.
Renal care procurement is consolidating under large dialysis organization purchasing coalitions that negotiate multi-year supply agreements with price-volume guarantees. Independent dialysis centers and regional hospital systems are losing negotiating leverage as buying power concentrates among vertically integrated service providers. This concentration is most visible in the United States, where Fresenius Medical Care and DaVita control the majority of treatment sites and captive dialyzer offtake.
Blood Dialyzer Market Segmentation
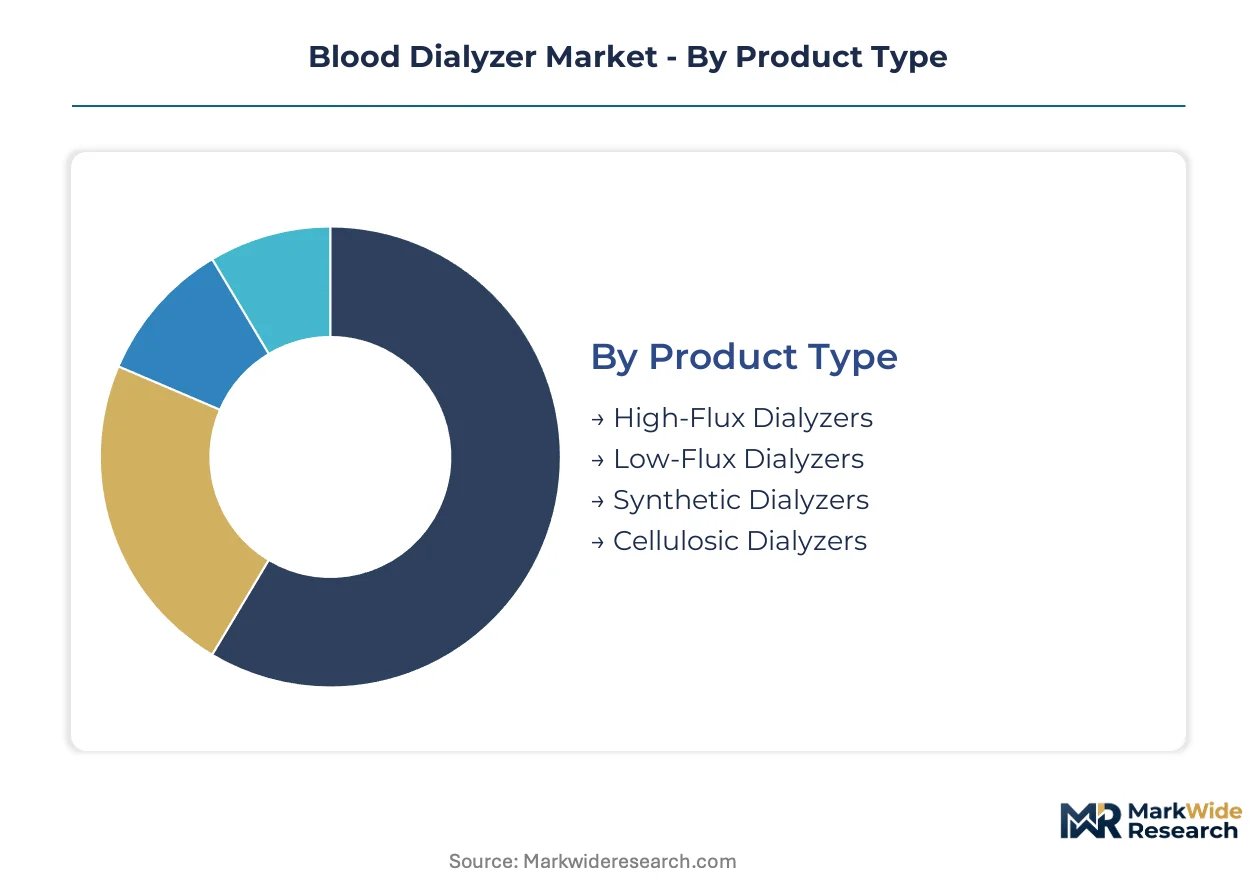
Blood dialyzer procurement patterns diverge sharply across membrane permeability classes and treatment settings. Certification requirements from FDA, EU MDR, and Japan's PMDA create tiered compliance burdens that reshape manufacturer prioritization and pricing architecture.
Product Type:
FDA 510(k) clearance timelines vary by membrane chemistry, with synthetic high-flux categories facing extended ISO 10993 biocompatibility validation compared to legacy cellulosic alternatives.
- High-Flux Dialyzers:Polysulfone and polyethersulfone membranes achieve ultrafiltration coefficients above 20 mL/h/mmHg for superior middle-molecule clearance. Dialysis centers in the United States concentrate procurement here as Medicare bundled payments reward reduced treatment times.
- Synthetic Dialyzers:Polymer-based hollow-fiber construction displaces cellulosic alternatives across European markets where EU MDR notified bodies scrutinize membrane biocompatibility data intensively. German and French hospital systems drive volume as they retrofit water purification infrastructure.
- Low-Flux Dialyzers:Cellulose-derived membranes with restricted permeability serve cost-sensitive procurement in emerging markets with limited reimbursement depth.
- Cellulosic Dialyzers:Cuprophane and regenerated cellulose constructions retain niche demand in Japan where PMDA maintains distinct Japan Industrial Standards compliance pathways.
High-flux dialyzers sit at the top of the volume ranking, with synthetic dialyzers climbing the fastest.
End User:
Site-of-care economics determine membrane specification, with hospital-based acute care requiring broader CRRT compatibility than outpatient chronic programs.
- Dialysis Centers:Outpatient clinic networks in the United States generate concentrated procurement through Fresenius Medical Care and DaVita purchasing coalitions. Medicare reimbursement stability locks in multi-year supply agreements with volume guarantees.
- Home Healthcare:Portable system adoption accelerates as payers push site-of-care migration beyond traditional clinic infrastructure. Training requirements and water treatment complexity constrain patient self-administration despite technology maturation.
- Hospitals:Acute kidney injury management in ICU settings demands CRRT-compatible membrane portfolios with extended biocompatibility coatings.
- Specialty Clinics:Nephrology-focused facilities in Germany and Switzerland pursue premium membrane specifications for complex patient populations.
Dialysis centers capture the largest revenue share, while home healthcare segments show the steepest expansion trajectory.
Material:
Polymer science capabilities concentrate manufacturing gravity, with Asian production clusters dominating hollow-fiber extrusion scale.
- Polyethersulfone:Hydrophilic synthetic membranes achieve optimal sieving coefficients for middle-molecule removal. Japanese manufacturers anchor supply chains through Asahi Kasei's hollow-fiber production scale.
- Cellulose Acetate:Modified natural polymer retains cost advantage in price-sensitive procurement channels with less stringent biocompatibility requirements.
- Polyamide:Nylon-based membranes serve specialized CRRT applications requiring enhanced endotoxin retention validation.
- Polypropylene:Hydrophobic polymer constructions feature in specific hollow-fiber support structures rather than primary filtration membranes.
Polyethersulfone leads procurement volume, with polyamide gaining share fastest in acute care segments.
Technology:
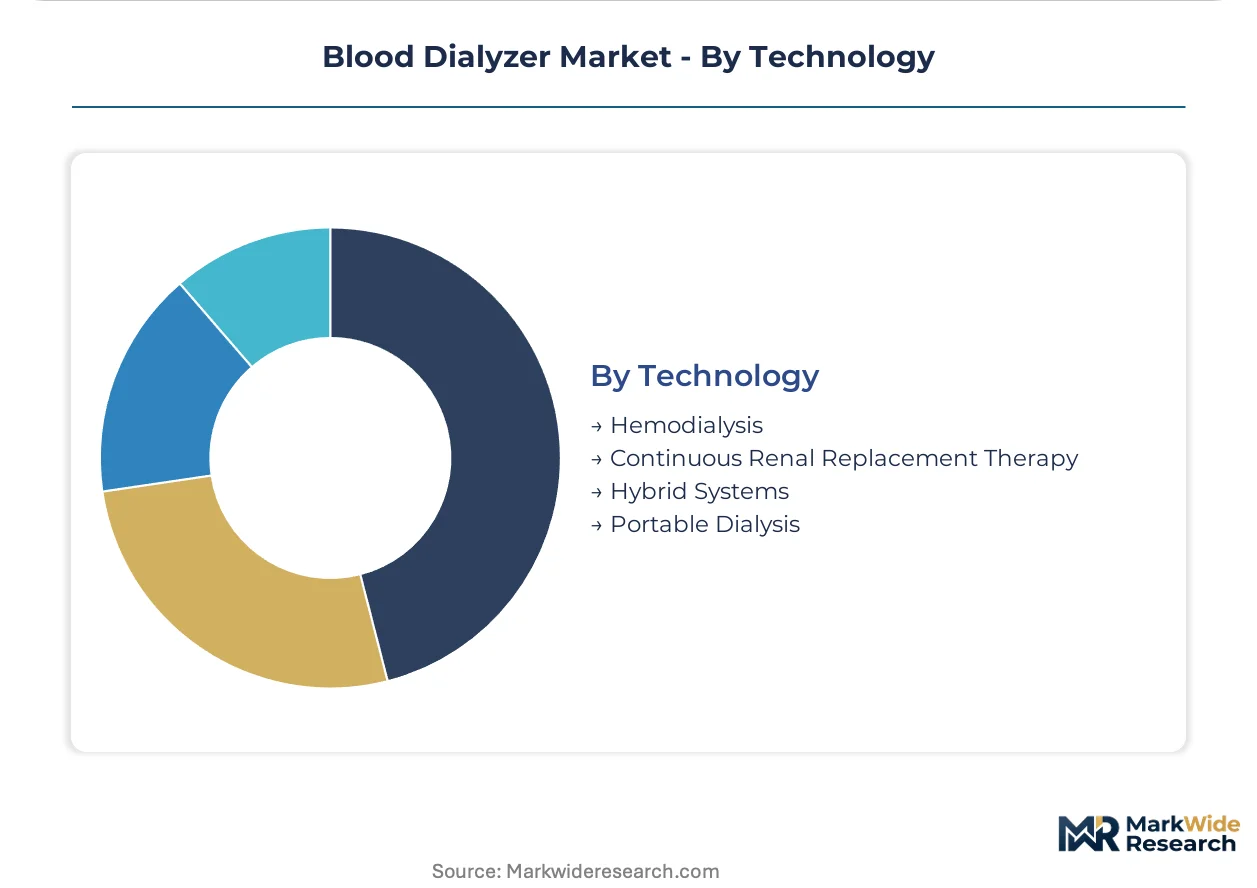
Device miniaturization and membrane efficiency gains compress treatment site requirements while regulatory frameworks tighten post-market surveillance.
- Hemodialysis:Standard intermittent extracorporeal renal replacement dominates chronic kidney disease management. United States dialysis centers operate over 90 percent of installed base capacity.
- Portable Dialysis:Compact system engineering enables residential treatment previously restricted to clinic settings. Simplified priming protocols accelerate home healthcare agency adoption.
- Continuous Renal Replacement Therapy:ICU-based acute kidney injury management requires specialized membrane portfolios with extended biocompatibility specifications.
- Hybrid Systems:Combined intermittent and continuous modalities serve transitional patient populations in hospital step-down units.
Hemodialysis maintains volume dominance, with portable dialysis expanding most quickly as device engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renal replacement therapy specialists concentrate in Germany, Japan, and the United States, where hollow-fiber membrane engineering talent pools anchor regional production capabilities. These workforce clusters shape dialyzer procurement patterns and regulatory compliance architectures across major markets.
United States
Medicare's bundled payment model for dialysis treatment locks in predictable procurement volumes for dialyzer manufacturers serving Fresenius Medical Care and DaVita clinic networks. FDA enforces 510(k) clearance and ISO 10993 biocompatibility standards that extend validation timelines for synthetic membrane innovations. Boston and Minneapolis medical device clusters host polymer science talent specializing in ultrafiltration coefficient optimization.
Germany
Hospital-based dialysis centers in Bavaria and Baden-Württemberg drive premium membrane specifications as nephrology-focused facilities retrofit water purification infrastructure for high-flux dialyzers. EU Medical Device Regulation mandates notified-body certification and EUDAMED post-market surveillance that exceeds prior directive requirements. Freiburg and Heidelberg industrial zones concentrate hollow-fiber manufacturing engineering expertise.
Japan
PMDA maintains distinct Japan Industrial Standards compliance pathways for imported dialyzers that create additional testing layers for Western manufacturers seeking market entry. Tokyo and Osaka metropolitan areas anchor domestic hollow-fiber production scale through Asahi Kasei's manufacturing footprint. Aging demographics expand chronic kidney disease prevalence among populations over 65.
China
NMPA regulatory pathways for Class II medical devices are strengthening biocompatibility documentation requirements that reshape manufacturer compliance burdens for imported dialyzers. Shanghai and Suzhou medical device industrial parks attract foreign joint ventures seeking localized production capabilities. Dialysis center expansion accelerates as reimbursement depth improves in tier-one cities.
Switzerland
Swissmedic certification requirements for hollow-fiber membranes emphasize post-market vigilance reporting systems that exceed baseline EU MDR obligations. Basel and Zurich life sciences clusters host specialized polymer science talent for membrane characterization and endotoxin retention validation. Specialty nephrology clinics in Geneva and Lausanne pursue premium dialyzer specifications for complex patient populations.
Blood Dialyzer Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across membrane chemistry and dialysis service provision. The vendor base stratifies into three tiers: vertically integrated therapy providers controlling captive dialyzer demand, diversified medical technology conglomerates with renal care divisions, and specialized hollow-fiber membrane fabricators. Dominant competitive moves include backward integration into hollow-fiber manufacturing and geographic expansion through notified-body certification leverage in EU markets.
Among diversified medical technology conglomerates, Fresenius Medical Care AG & Co. KGaA exemplifies the vertically integrated archetype through its dialysis service network. Baxter International Inc. occupies a position within the specialized portfolio tier. Asahi Kasei Corporation anchors Asian supply chain concentration. These three entities represent distinct strategic postures: therapy provision integration, acute care specialization, and materials-scale manufacturing respectively.
| Leading Market Players |
|---|
| Fresenius Medical Care AG & Co. KGaA |
| Baxter International Inc. |
| B. Braun Melsungen AG |
| Nikkiso Co., Ltd. |
| Nipro Corporation |
| Medtronic plc |
| Asahi Kasei Corporation |
| Toray Industries, Inc. |
| Kawasumi Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
Medicare's bundled payment model for dialysis treatment locks in multi-year procurement commitments that force manufacturers to optimize hollow-fiber production scale and absorb biocompatibility testing costs into contract pricing. This demand-side pressure concentrates pricing power among vertically integrated therapy providers while squeezing margins for standalone membrane suppliers.
Pricing Analysis
Capacity additions in China are reshaping price floors for cellulosic dialyzers as NMPA-compliant domestic production scales compete with imported synthetic alternatives. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared high-flux membranes from EU MDR-certified mid-tier products and basic cellulose variants. Price differentiation hinges on ISO 10993 validation depth and hollow-fiber manufacturing geography. Cost compression in economy tiers is intensifying because Asian producers are expanding polysulfone extrusion capacity. Dialysis centers under Fresenius and DaVita purchasing coalitions exhibit lowest price sensitivity due to Medicare reimbursement stability, while independent clinics in emerging markets face acute budget constraints.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns that position dialyzer inventory within 48-hour delivery windows of major dialysis center networks. Hollow-fiber membrane production concentrates in Japan, Germany, and China, with Asahi Kasei and Toray Industries anchoring Asian supply chains. Raw material dependencies draw from polysulfone resin suppliers in the US and polyethersulfone polymer producers in Western Europe. Tariff exposure on Chinese-manufactured cellulosic membranes creates supply chain risk as trade policy shifts. Distribution runs through vertically integrated dialysis service providers that control captive offtake and lock in multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The blood dialyzer market functions as a regulatory compounder where FDA's strengthened ISO 10993 requirements and EU MDR notified-body certification create escalating compliance barriers that consolidate advantage among incumbents with established validation infrastructure.
For Market Incumbents: Deepen backward integration into hollow-fiber extrusion capacity to defend against Asian cost competitors and secure captive supply of polysulfone membranes. Expand EUDAMED surveillance capabilities to leverage EU MDR certification as competitive differentiation against cellulose-based alternatives facing steeper notified-body scrutiny. Prioritize CRRT-compatible membrane R&D to capture ICU demand outside saturated chronic dialysis channels. For New Entrants and Emerging Players: Home healthcare agencies seeking portable hemodialysis systems represent the most penetrable buyer archetype as site-of-care migration accelerates and training protocols standardize. Target specialty nephrology clinics in Switzerland and Germany with premium membrane specifications for complex patient populations underserved by large dialysis organization purchasing coalitions. Pursue notified-body certification partnerships with established EU MDR consultants to compress time-to-revenue. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized hollow-fiber membrane fabricators possessing Japan Industrial Standards compliance and PMDA pathway expertise for Western market entry. Long-term viability over the projection horizon favors targets with polymer science talent pools in Freiburg, Boston, or Tokyo clusters. Monitor CMS reimbursement rate negotiations as the critical inflection signal for dialyzer procurement volume commitments.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified-Body Certification | EUDAMED surveillance capabilities differentiate synthetic membrane portfolios from cellulose alternatives in German hospital procurement. |
| Backward Integration into Hollow-Fiber Manufacturing | In-house polysulfone extrusion capacity reduces tariff exposure and secures supply continuity for high-flux dialyzer production. |
| CRRT-Compatible Membrane Development | ICU-focused portfolios capture acute kidney injury demand outside Medicare bundled payment constraints in US hospital systems. |
| Home Healthcare Distribution Partnership | Simplified priming protocols for portable systems accelerate residential dialysis adoption beyond traditional clinic infrastructure. |
| Japan Industrial Standards Compliance | PMDA pathway expertise unlocks Tokyo and Osaka metropolitan demand among aging populations over 65. |
Study Parameters
Direct dialogue with dialysis center operations directors, hospital biomedical engineers, GPO contracts managers, and nephrology clinicians grounded qualitative insights in procurement decision dynamics. Secondary validation drew from FDA 510(k) filings, EUDAMED vigilance reports, CMS Medicare reimbursement databases, and Japan PMDA approval records. Bottom-up and top-down triangulation reconciled manufacturer shipment data with dialysis center capacity utilization across the analysis window.
Bottom-up modeling segmented volume and value outputs by membrane permeability class, treatment setting, material chemistry, and regulatory certification tier. Top-down cross-checks incorporated chronic kidney disease epidemiology, dialysis center expansion rates, and Medicare beneficiary growth. CAGRs derived from polynomial trend fitting of historic procurement patterns adjusted for reimbursement policy stability and biocompatibility testing cost inflation. Industry-specific inputs included ultrafiltration coefficient optimization trajectories and hollow-fiber manufacturing scale expansion timelines.
Underlying measurement precision varies by segment; high-flux synthetic dialyzers and dialysis center procurement channels carry tighter precision than emerging portable system categories. Forecasts reflect documented assumptions regarding CMS reimbursement continuity, EU MDR notified-body capacity constraints, and PMDA import testing layer stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
US Continuous Renal Replacement Therapy Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Renal Denervation Market
Nephrology
Chronic Kidney Disease Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Hemodialysis Services Market
Nephrology
ICU-Acquired Acute Kidney Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Nephrosclerosis Treatment Market
Nephrology
Renal Insufficiency Treatment Market
Nephrology
Global Hemodialysis Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Peritoneal Dialysis Market
Nephrology
Global Dialyzer Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Global Dialysis Market