
 Glomerulonephritis Treatment Market | 2026-2036
Glomerulonephritis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Glomerulonephritis Treatment Market Foresight
The EU Green Deal's pharmaceutical sustainability criteria is decoupling procurement standards from traditional cost-only metrics across European nephrology networks. Pfizer Inc leverages its corticosteroid manufacturing scale to supply specialist hospitals across multiple continents. Novartis anchors its position through biologics R&D intensity focused on lupus nephritis and related autoimmune renal indications. Roche differentiates via diagnostic-therapeutic integration that supports precision immunosuppression protocols in nephrology clinics.
Glomerulonephritis treatment encompasses pharmacological interventions targeting immune-mediated inflammation of the glomerular filtration apparatus, with corticosteroids functioning as first-line anti-inflammatory agents and biologics selectively modulating B-cell and complement pathways to preserve renal function. Immunosuppressants occupy the largest revenue pool given their established reimbursement across Medicare and European statutory health systems, while biologics represent the fastest-expanding segment driven by FDA breakthrough therapy designations for refractory lupus nephritis and anti-GBM disease. The therapy area segmentation reveals primary glomerulonephritis as the most clinically addressed category, with rapidly progressive variants commanding premium pricing due to acute dialysis avoidance value.
The FDA, EMA, and WHO collectively shape market access through renal-specific clinical trial endpoints and post-market pharmacovigilance requirements for immunosuppressive agents. The FDA's Rare Disease Program and EMA's PRIME designation accelerate development timelines for novel biologics targeting small patient populations with high unmet need. Stakeholders must monitor evolving complement inhibitor label expansions and biosimilar entry timelines for established TNF-alpha and B-cell depleting therapies.
Market Dynamics
FDA breakthrough therapy designations for complement inhibitors and B-cell modulators are compressing clinical development timelines while reshaping competitive entry sequences in autoimmune renal disease.
Growth Catalysts
- EMA PRIME Designation:The European Medicines Agency's priority medicines scheme accelerates regulatory assessment for lupus nephritis biologics, reducing time-to-market for novel immunomodulators targeting small patient populations with high unmet need.
- Specialist Hospital Infrastructure:Tertiary nephrology centers in Germany, Japan, and the United States are expanding dedicated glomerular disease units equipped for advanced immunosuppressive protocols and rapid biopsy-to-treatment pathways.
- Complement Pathway Inhibition:Next-generation C5a and C3 inhibitors are demonstrating renal function preservation in refractory anti-GBM disease, creating new therapeutic categories beyond corticosteroid-refractory cases.
Market Restraints
- Biologics Manufacturing Concentration:Single-source contract manufacturing organizations in Switzerland and Ireland control critical fill-finish capacity for monoclonal antibodies, creating supply vulnerability for chronic immunosuppressive therapies.
- Reimbursement Compression:Medicare's inflation rebate provisions under the Inflation Reduction Act are narrowing net pricing flexibility for established corticosteroid and calcineurin inhibitor regimens.
- Diagnostic Latency:Mean time from symptom onset to renal biopsy exceeds 90 days in non-specialist settings, delaying immunosuppressive initiation and reducing therapeutic window efficacy.
Strategic Opportunities
- Home-Based Monitoring:Point-of-care creatinine and proteinuria testing devices are enabling decentralized disease management, reducing specialist visit burden for stable maintenance-phase patients in rural United States markets.
- EU Green Deal Procurement:The European Union's pharmaceutical sustainability criteria are creating preferential purchasing pathways for manufacturers with validated carbon-neutral production processes across nephrology networks.
- AI-Assisted Pathology:Machine learning algorithms applied to renal biopsy histology are automating glomerular lesion classification, accelerating diagnostic workflows in high-volume Japanese and German pathology labs.
Industry Challenges
- Nephrology Workforce Constraints:Fellowship-trained glomerular disease specialists number fewer than 400 across the United States, creating bottlenecks for complex case management and clinical trial enrollment.
- Biomarker Validation Timelines:FDA qualification of novel renal function surrogate endpoints requires 5-7 year longitudinal studies, delaying label expansion for accelerated-approval biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glomerulonephritis Treatment Market |
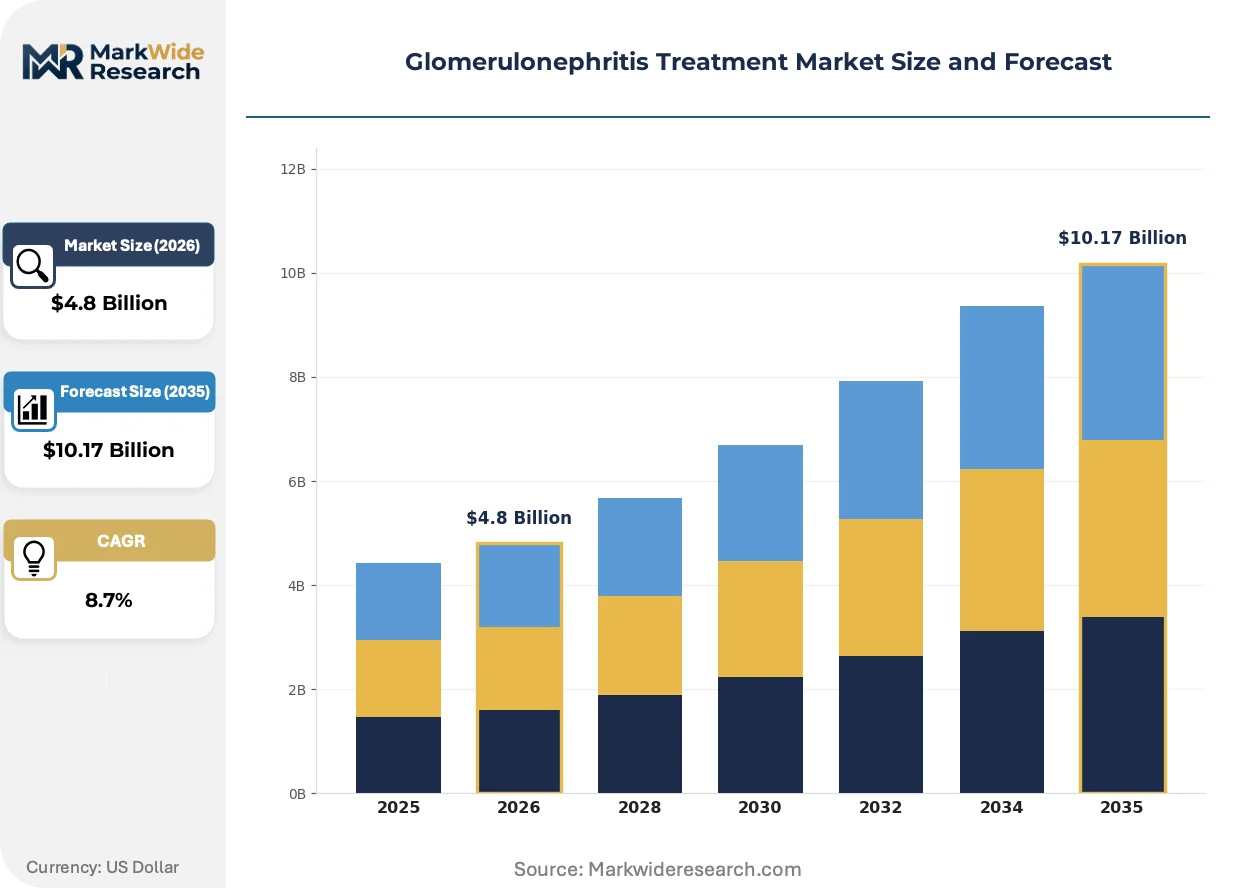
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Immunosuppressants, Antihypertensives, Corticosteroids, Biologics Therapy Area: Primary Glomerulonephritis, Secondary Glomerulonephritis, Rapidly Progressive, Chronic End User: Nephrology Clinics, Dialysis Centers, Specialist Hospitals, Research Institutes Delivery Mode: Oral, Intravenous, Subcutaneous, Intramuscular |
| Companies Covered | Pfizer Inc, Merck, Novartis AG, Roche, AstraZeneca, Visterra, Biogen Inc, Otsuka Pharmaceutical, Bristol Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glomerulonephritis Treatment Market Shifts & Advancements
Precision immunosuppression protocols are displacing empiric dosing regimens as diagnostic-therapeutic integration becomes standard in tertiary nephrology practice.
Machine learning algorithms applied to electronic health record data and renal biopsy imaging are automating treatment response prediction and adverse event risk stratification. Large academic medical centers in Boston and Tokyo are deploying these tools to optimize cyclophosphamide versus rituximab selection in lupus nephritis. The technology is automating previously manual case review processes that consumed 4-6 hours per complex patient.
The European Union's Medical Device Regulation is tightening post-market surveillance requirements for companion diagnostics used in immunosuppressive therapy selection. Manufacturers must now submit annual safety reports and real-world performance data for assays guiding biologic prescribing. Nephrology clinics in France and Germany are restructuring procurement contracts to include diagnostic performance guarantees.
Specialist hospitals are consolidating biologic purchasing through centralized pharmacy and therapeutics committees, displacing individual physician preference in formulary decisions. This concentration is shifting negotiation leverage toward institutional buyers and demanding outcome-based contracts from manufacturers. The pattern is most visible in United States academic medical centers and Japanese university hospitals with integrated delivery networks.
Glomerulonephritis Treatment Market Segmentation
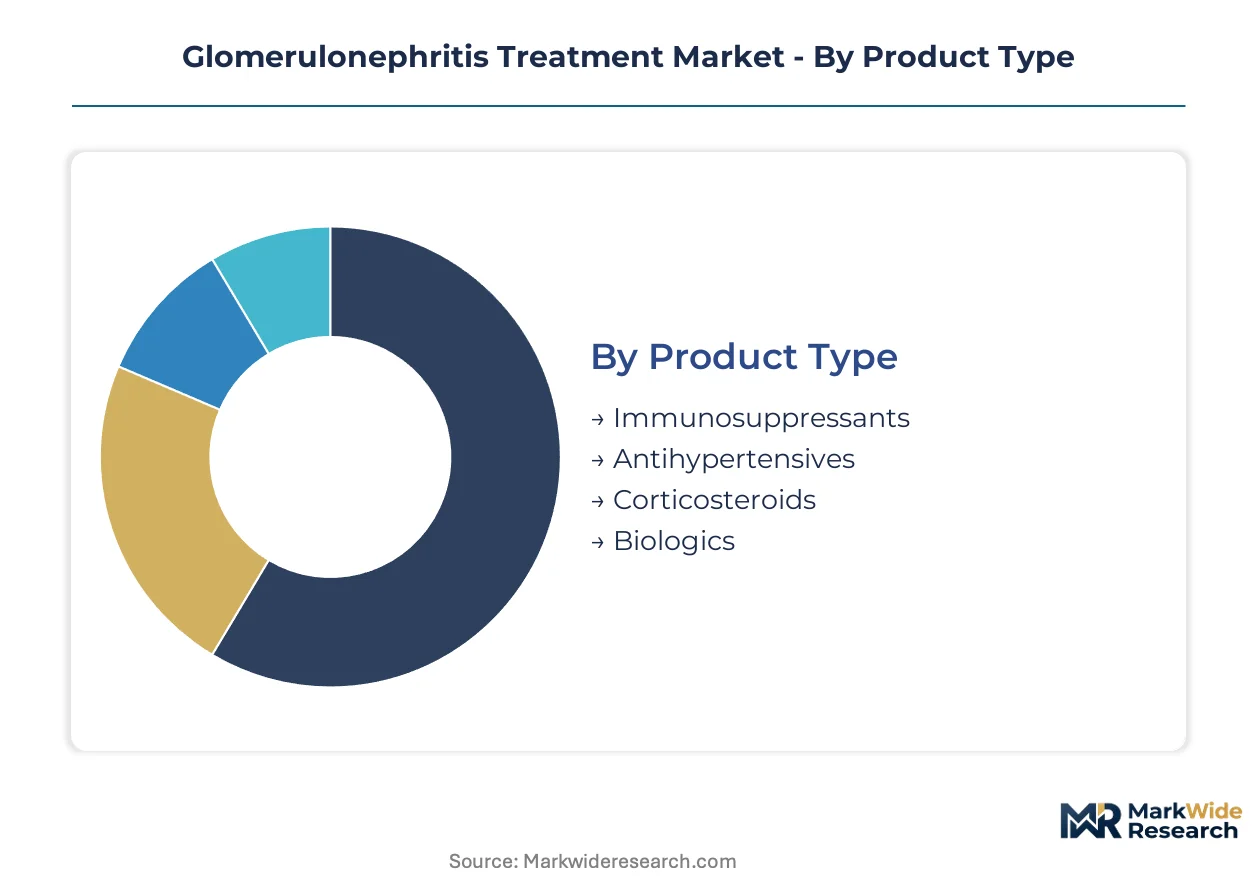
Glomerulonephritis treatment segmentation reveals divergent commercial strategies across pharmacological mechanisms and care settings. Understanding volume concentration versus premium pricing dynamics within each category enables targeted resource allocation for manufacturers and procurement optimization for provider networks.
Product Type:
Volume leadership sits with established small-molecule therapies, while biologics command premium positioning through targeted immunomodulation.
- Immunosuppressants:Calcineurin inhibitors and antimetabolites form the backbone of maintenance protocols across Medicare and European statutory systems. Demand concentrates in specialist hospitals across Germany and the United States where reimbursement pathways for chronic immunosuppression are well-established.
- Corticosteroids:First-line anti-inflammatory agents with standardized dosing protocols dominate initial treatment episodes. Nephrology clinics in Japan leverage these for rapid biopsy-to-treatment pathways, though long-term toxicity profiles limit duration in lupus nephritis protocols.
- Biologics:Monoclonal antibodies targeting B-cell and complement pathways attract FDA breakthrough therapy designations for refractory indications. Manufacturing concentration in Swiss and Irish contract organizations creates supply vulnerability for chronic dosing regimens.
- Antihypertensives:ACE inhibitors and ARBs serve dual renoprotective and blood pressure control functions in proteinuric disease management.
Today's leader: Immunosuppressants. Tomorrow's challenger: Biologics.
Therapy Area:
Clinical urgency and disease trajectory determine pricing power across acute versus chronic management paradigms.
- Primary Glomerulonephritis:Immune-mediated glomerular injury without systemic disease association represents the most clinically addressed category. Specialist hospital infrastructure in the United States and Japan supports dedicated glomerular disease units with rapid diagnostic workflows.
- Rapidly Progressive:Crescentic variants with acute renal failure risk command premium pricing due to dialysis avoidance value. Nephrology clinics prioritize these cases for urgent biologic initiation under FDA accelerated approval pathways.
- Secondary Glomerulonephritis:Renal manifestations of systemic conditions like lupus or infection require coordinated specialty management.
- Chronic:Long-standing disease with established renal impairment focuses on progression delay rather than remission induction.
Rapidly Progressive segments are gaining share fastest through emergency protocol adoption.
End User:
Care setting sophistication determines protocol complexity and biologic eligibility.
- Specialist Hospitals:Tertiary centers with integrated pathology and pharmacy services manage complex immunosuppressive protocols. German university hospitals and United States academic medical centers consolidate purchasing through centralized therapeutics committees.
- Nephrology Clinics:Outpatient-focused settings handle stable maintenance-phase patients with oral immunosuppressant regimens. Japanese clinics deploy point-of-care monitoring to reduce specialist visit burden in rural prefectures.
- Dialysis Centers:End-stage renal disease facilities manage treatment failures requiring renal replacement therapy.
- Research Institutes:Academic centers drive clinical trial enrollment for novel complement inhibitors and biomarker validation studies.
Specialist Hospitals currently anchor revenue concentration. Nephrology Clinics represent the steepest expansion trajectory through decentralized care models.
Delivery Mode:
Route selection balances bioavailability requirements with patient self-administration capabilities.
- Intravenous:Hospital-administered biologics and pulse corticosteroid protocols enable tight therapeutic monitoring. United States specialist hospitals favor this route for rituximab and complement inhibitor induction.
- Subcutaneous:Self-administered biologics reduce infusion center burden for maintenance-phase patients. Japanese nephrology clinics are expanding home-based training programs for stable lupus nephritis cases.
- Oral:Small-molecule immunosuppressants and corticosteroids support outpatient chronic management.
- Intramuscular:Limited applications for depot corticosteroid formulations in select maintenance protocols.
Intravenous dominates acute revenue. Subcutaneous is climbing the fastest through patient convenience prioritization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fellowship-trained glomerular disease specialists concentrate in tertiary centers across the United States, Germany, and Japan, anchoring demand for advanced immunosuppressive protocols and biologic therapies in these markets.
United States
Academic medical centers in Boston and New York Metro deploy AI-assisted renal biopsy pathology to compress diagnostic latency. The FDA's Rare Disease Program accelerates breakthrough therapy designations for complement inhibitors targeting anti-GBM disease. Specialist hospital infrastructure in these clusters supports centralized pharmacy and therapeutics committees that consolidate biologic purchasing.
Germany
University hospitals in Bavaria and North Rhine-Westphalia operate dedicated glomerular disease units with rapid biopsy-to-treatment pathways. EMA PRIME designation reduces regulatory assessment timelines for lupus nephritis biologics entering European markets. The EU Green Deal's pharmaceutical sustainability criteria are restructuring procurement contracts across these nephrology networks.
Japan
Metropolitan Tokyo and Osaka prefectures concentrate point-of-care creatinine monitoring for decentralized maintenance-phase management. PMDA accelerated approval pathways support rapid market entry for B-cell modulators in refractory indications. Japanese university hospitals with integrated delivery networks are expanding home-based subcutaneous biologic training programs.
Switzerland
Swissmedic oversees regulatory frameworks for biologics manufactured in Basel and Zurich contract manufacturing clusters. Single-source fill-finish capacity for monoclonal antibodies creates supply vulnerability for chronic immunosuppressive therapies. These production nodes serve specialist hospitals across multiple continents.
United Kingdom
London and Southeast England nephrology clinics participate in longitudinal biomarker validation studies for novel renal function surrogate endpoints. The MHRA operates post-Brexit recognition procedures for EMA-approved immunosuppressive agents. Research institutes in this cluster drive clinical trial enrollment for complement inhibitor label expansions.
Glomerulonephritis Treatment Market Competitive Landscape
Capital-heavy pharmaceutical manufacturers compete with asset-light biotech developers for positioning in autoimmune renal disease. The vendor base stratifies across three tiers: diversified giants with corticosteroid manufacturing scale, mid-cap biologics specialists with FDA breakthrough designations, and emerging complement pathway innovators. Dominant competitive moves include diagnostic-therapeutic integration partnerships and centralized hospital formulary contracting.
Among diversified pharmaceutical incumbents, Pfizer Inc and Novartis AG occupy positions anchored by manufacturing scale and biologics R&D intensity respectively. Roche exemplifies the diagnostic-therapeutic integration archetype through precision immunosuppression protocols. These three entities represent distinct strategic postures: supply security, pipeline depth, and clinical workflow embedding.
| Leading Market Players |
|---|
| Pfizer Inc |
| Merck |
| Novartis AG |
| Roche |
| AstraZeneca |
| Visterra |
| Biogen Inc |
| Otsuka Pharmaceutical |
| Bristol Myers Squibb Company |
| Others |
Supply & Pricing Matrix
The EU Green Deal's pharmaceutical sustainability criteria gates qualified supply for premium-tier biologics while compressing margins on carbon-intensive corticosteroid manufacturing. Manufacturers lacking validated carbon-neutral production processes face exclusion from European nephrology network procurement, redirecting pricing power toward compliant suppliers with Swiss and Irish fill-finish capacity.
Pricing Analysis
Bundled diagnostic-therapeutic protocols command premium positioning against unbundled small-molecule regimens in tertiary nephrology centers. Three-tier pricing structure across premium biologics, standard immunosuppressants, and economy corticosteroids tracks FDA breakthrough designation status and manufacturing complexity. Pricing pressure stems from Medicare's inflation rebate provisions narrowing net pricing flexibility for established calcineurin inhibitor regimens. Dialysis centers exhibit highest price sensitivity due to fixed reimbursement schedules, while specialist hospitals prioritize clinical outcomes over acquisition cost.
Supply Chain Analysis
Domestic-content mandates in the United States and Japan are reshaping sourcing for critical monoclonal antibody fill-finish capacity. Supply concentrates in Switzerland, Ireland, and Singapore for biologics manufacturing, with corticosteroid active pharmaceutical ingredients drawing from India and China. Single-source contract manufacturing organization dependence creates vulnerability for chronic immunosuppressive dosing regimens. Distribution runs through centralized hospital pharmacy and therapeutics committees in academic medical centers, displacing traditional wholesaler channels for biologic therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glomerulonephritis treatment market functions as a stable compounder anchored by irreversible nephrology workforce scarcity that perpetuates premium pricing for specialist-administered therapies.
For Market Incumbents: Acquire AI-assisted renal pathology platforms to compress diagnostic latency and secure formulary positioning against biosimilar entrants. Lock in exclusive fill-finish capacity with Swiss and Irish contract manufacturing organizations before capacity constraints intensify. Prioritize EMA PRIME designation pathways to accelerate European market entry for lupus nephritis biologics ahead of complement inhibitor label expansions. For New Entrants and Emerging Players: Capture home-based subcutaneous biologic administration protocols in Japanese rural prefectures and United States Medicare Advantage markets where specialist visit burden creates patient willingness to self-administer. Target nephrology clinics with point-of-care monitoring integration rather than competing for specialist hospital formulary access. Lead with outcome-based contracts that guarantee renal function preservation metrics to differentiate from established corticosteroid regimens. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap biologics developers with FDA breakthrough therapy designations because regulatory acceleration compresses time-to-revenue and creates scarcity value for acquirers seeking pipeline depth. Monitor complement inhibitor label expansion timelines as the critical inflection signal for portfolio rebalancing toward autoimmune renal disease exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Therapeutic Integration Partnership | Roche's precision immunosuppression protocols embed clinical workflow dependency that displaces competing biologics from hospital formularies. |
| EMA PRIME Designation Pursuit | Novartis leverages accelerated regulatory assessment to compress European market entry timelines for lupus nephritis monoclonal antibodies. |
| Carbon-Neutral Manufacturing Certification | Pfizer's validated sustainable production processes unlock preferential procurement pathways under EU Green Deal pharmaceutical sustainability criteria. |
| Home-Based Subcutaneous Training Program | Japanese nephrology clinics deploying patient self-administration protocols reduce infusion center burden and expand addressable rural markets. |
| AI-Assisted Renal Biopsy Pathology Deployment | Boston academic medical centers automate glomerular lesion classification to accelerate biopsy-to-treatment pathways and optimize biologic selection. |
Research Methodology
Coverage spans the United States, Germany, Japan, Switzerland, and the United Kingdom, with primary inputs from each market's tertiary nephrology centers and regulatory authorities. The analysis combines structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare reimbursement databases. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchor volume and value estimates across the analysis window.
Granularity-level modeling disaggregates the market by pharmacological mechanism, therapy area urgency, care setting sophistication, and administration route throughout the projection horizon. Treatment line positioning, patient population severity, and regional regulatory cluster differentiation inform segment-level CAGRs derived from historical approval velocity and reimbursement pathway maturation. Forecast inputs incorporate immunosuppressant biosimilar entry timelines, complement inhibitor clinical trial readouts, and nephrology specialist workforce growth constraints.
Regulatory approval delays, biosimilar launch acceleration, and nephrology fellowship training expansion are the dominant revision risks that could compress or extend projected growth trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
End Stage Renal Disease Market
Nephrology
Hollow Fiber Dialyzers Market
Nephrology
Renal Denervation Market
Nephrology
US Dialysis Centers Market
Nephrology
US Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Lupus Nephritis Treatment Market
Nephrology
Blood Dialyzer Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Ketoanalogue for Kidney Disease Market
Nephrology
Nephrology Stents and Catheters Market
Nephrology
Dialysis Service Market
Nephrology
Global Nephroblastoma Treatment Market
Nephrology
Aldosterone-Renin Screening Market
Nephrology
Drug-Induced Nephrotoxicity Treatment Market
Nephrology
Renal Artery Stenosis Treatment Market