
 Solar Simulator Market | 2026-2036
Solar Simulator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Simulator Market Intelligence
The direct sales channel for high-specification solar simulators is fragmenting as regional distributors gain technical expertise. Newport Corporation leverages its broad portfolio in photonics to serve large research institutions directly. Eternalsun specializes in steady-state simulators for quality control in PV production lines. Sciencetech competes by offering highly customized systems for niche academic and material research applications.
A solar simulator is an artificial light source that replicates the spectral distribution and intensity of natural sunlight, often conforming to the IEC 60904-9 standard. Its primary purpose is to provide a stable, repeatable environment for testing photovoltaic devices and materials. The Class AAA product type commands the highest value, delivering superior performance for critical R&D applications in research laboratories. Within light sources, LED arrays are challenging the dominance of traditional xenon lamps due to longer operational life and spectral tunability.
Product design and market access are shaped by international standards, primarily the IEC 60904 series, which defines simulator classifications. In Europe, CE marking is mandatory for ensuring electrical safety and electromagnetic compatibility. Chinese manufacturers must adhere to specific GB standards for domestic market access and export. The key decision for equipment buyers now revolves around balancing the upfront cost of next-generation LED systems against the proven performance of xenon-based simulators.
Market Dynamics
The central tension in the solar simulator market is the performance-cost trade-off between established xenon-arc technology and next-generation LED systems. This dynamic is amplified by the material science race in photovoltaics, where novel materials demand testing capabilities that push the boundaries of the IEC 60904-9 standard.
Growth Catalysts
- Next-Generation Photovoltaics:The development of high-efficiency perovskite and tandem solar cells requires simulators with superior spectral stability and tunability for accurate performance characterization, driving upgrades in R&D labs.
- National Energy Policies:China's "dual carbon goals" and extensive government support for its solar manufacturing ecosystem create sustained demand for simulators in both production quality control and advanced research.
- Stringent Testing Standards:Adherence to the IEC 60904 series is critical for market access and bankability, compelling manufacturers and certification bodies to invest in higher-classification (Class AAA) simulators for reliable data.
Market Restraints
- High Capital Cost:The significant upfront investment required for Class AAA LED-based solar simulators acts as a barrier for smaller academic institutions and startups, despite their superior long-term performance.
- Xenon Lamp Lifecycle:Traditional xenon arc lamps have a limited operational life and degrade over time, requiring frequent and costly replacements that increase the total cost of ownership and introduce measurement variability.
- Technical Expertise Gap:Operating and maintaining advanced, spectrally tunable simulators requires specialized knowledge in optics and physics, creating a personnel bottleneck for some end-users.
Strategic Opportunities
- Emerging PV Applications:Untapped demand exists for simulators tailored to test niche applications like indoor photovoltaics, agrivoltaics, and vehicle-integrated solar panels, each requiring unique spectral conditions.
- Regulatory Incentives for R&D:The EU Green Deal and similar initiatives provide funding and policy support for renewable energy research, creating opportunities for simulator sales to publicly funded universities and institutes.
- Manufacturing Expansion in India:India's Production Linked Incentive (PLI) scheme for solar manufacturing is stimulating the setup of new production lines, which will require a corresponding investment in quality control and testing equipment.
Industry Challenges
- Standardization for Novel Materials:Existing IEC standards were developed for silicon-based cells and do not fully address the unique degradation and stabilization behaviors of perovskites, leading to testing inconsistencies.
- Supply Chain for Optics:The supply of specialized components, such as high-purity quartz for lamps and specific optical filters, is concentrated among a few suppliers, posing a risk of bottlenecks.
- Software and Data Integration:Integrating new simulators with legacy laboratory information management systems (LIMS) and automating data analysis across different test benches remains a significant operational hurdle for many labs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Simulator Market |
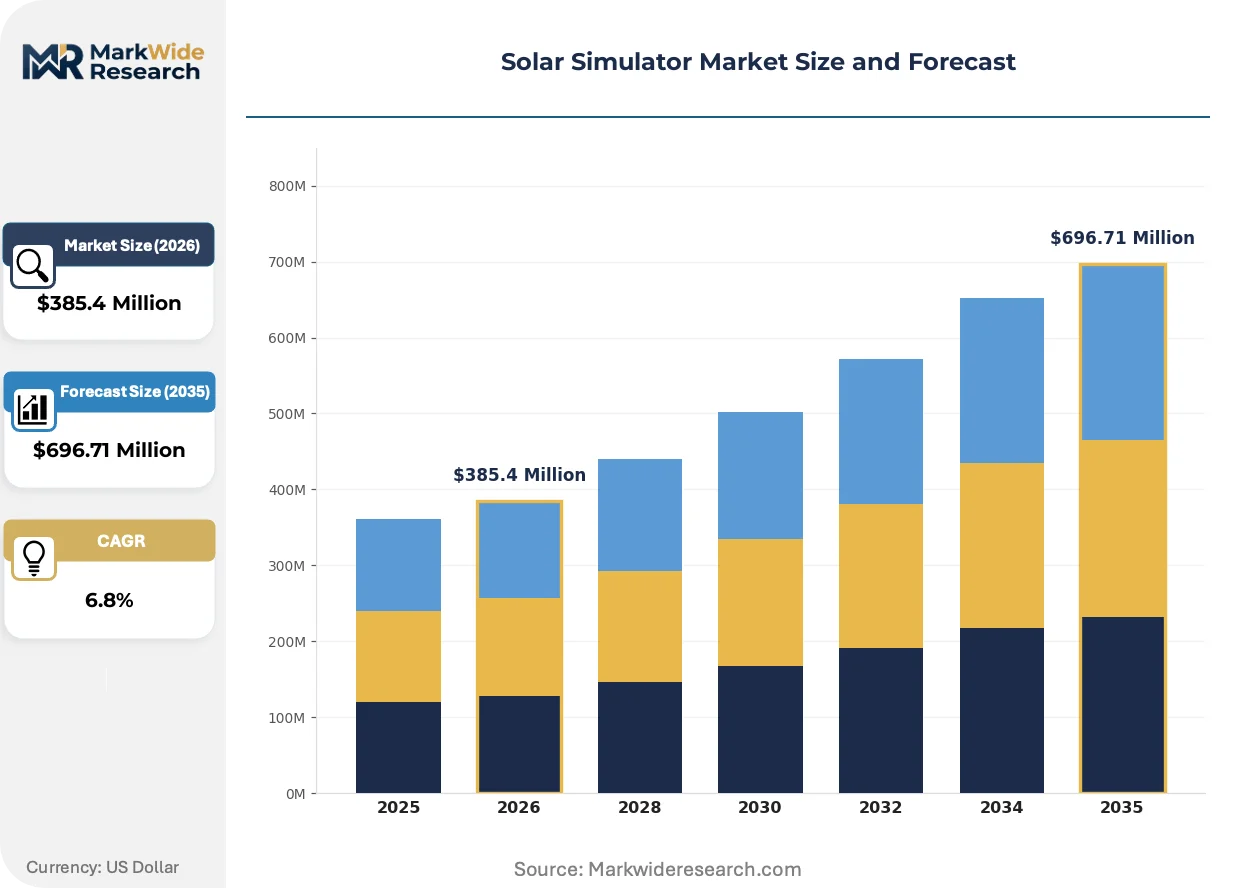
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Light Source Type: Xenon Lamp, Metal Halide Lamp, LED Array, Quartz Tungsten Halogen, Fluorescent Lamp Application: Photovoltaic Cell Testing, Material Research, Outdoor Equipment Simulation, Agricultural Research, Semiconductor Inspection Product Type: Class AAA, Class AA, Class A, Class B End User Industry: Research Laboratories, Quality Control Centers, Electronics Manufacturers, Academic Institutions |
| Companies Covered | Sciencetech, Wacom Electric, Newport Corporation, OAI, Eternalsun, Abet Technologies, Solar Light, MKS, AMETEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Simulator Market Strategic Shifts & Innovations
The market's evolution is defined by a push for greater fidelity in replicating solar radiation to meet the stringent validation needs of next-generation photovoltaic materials. This pursuit of precision is influencing product design, regulatory interpretation, and channel strategies across the industry.
LED-based solar simulators provide highly stable, spectrally tunable output that can be adjusted almost instantaneously. Research laboratories and PV manufacturers are increasingly adopting this technology for advanced characterization of materials like perovskites. This technology is digitizing the process of light-source replication, enabling dynamic testing cycles that mimic real-world diurnal and atmospheric variations far more accurately than static xenon sources.
The IEC 60904-9 standard provides a critical framework for classifying solar simulator performance based on spectral match, spatial non-uniformity, and temporal instability. This globally recognized standard directly shapes equipment design, as achieving a Class AAA rating is a key marketing and performance benchmark. Certification bodies and financial institutions involved in utility-scale solar projects are most affected, as they mandate testing with compliant equipment to validate energy yield predictions.
A shift in sales channels is altering competitive dynamics for high-specification systems. Technically skilled regional distributors are becoming a more important route to market, challenging the traditional direct-sales model from manufacturers to large research institutions. This pattern is particularly evident in Europe's fragmented academic landscape and China's rapidly expanding industrial R&D sector, where local partners provide crucial application support and faster service.
Solar Simulator Market Segmentation
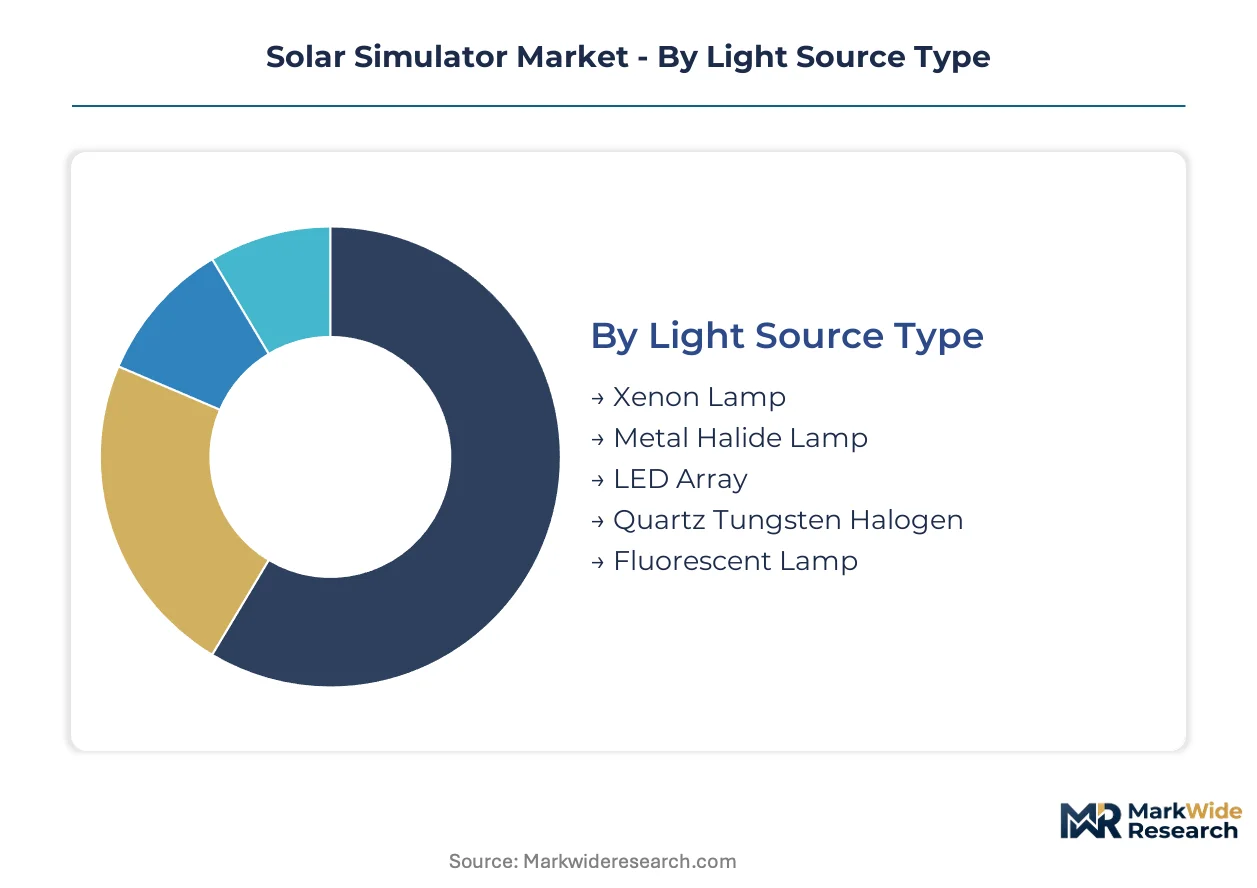
The solar simulator market's segmentation provides a detailed lens into its diverse technological components, application areas, and end-user requirements. Understanding these distinct categories helps identify specific demand drivers and the varying performance needs across different industry verticals.
Light Source Type:
The light source type segment illustrates the market's technological progression, from established lamp technologies to rapidly evolving solid-state solutions.
- LED Array:This advanced light source utilizes individually controllable light-emitting diodes to achieve superior spectral tunability and temporal stability. Demand for LED arrays is concentrating in advanced R&D laboratories, particularly for testing next-generation perovskite solar cells that require precise spectral matching.
- Xenon Lamp:Xenon lamps generate a continuous spectrum that closely mimics natural sunlight, making them a traditional choice for solar simulation. Widespread adoption persists in quality control centers due to their proven performance and established testing protocols under the IEC 60904-9 standard.
- Metal Halide Lamp:Metal halide lamps offer a cost-effective solution for specific spectral ranges, often employed in less stringent testing environments.
- Quartz Tungsten Halogen:These lamps provide a stable output in the visible and near-infrared spectrum, suitable for calibration and certain material characterization tasks.
- Fluorescent Lamp:Fluorescent lamps are typically used for low-cost, less demanding applications such as indoor light harvesting research, given their limited spectral range.
Xenon Lamp technology retains significant market presence; LED Array systems demonstrate the steepest expansion curve.
Application:
Application segmentation highlights the diverse operational contexts where solar simulators provide critical environmental replication.
- Photovoltaic Cell Testing:This application involves measuring the electrical performance and efficiency of solar cells and modules under standardized light conditions. Demand is sustained by the continuous expansion of global solar manufacturing capacity, particularly in China and India, which necessitates rigorous quality assurance.
- Material Research:Solar simulators are essential for characterizing new photovoltaic materials, thin films, and coatings to understand their optical and electrical properties. Research institutions globally drive this segment, seeking precise spectral control for novel material development and degradation studies.
- Outdoor Equipment Simulation:Simulators are used to test the durability and performance of various outdoor equipment, including automotive components and weather-resistant materials.
- Agricultural Research:This segment employs simulators to study plant growth and photosynthesis under controlled light conditions, supporting agrivoltaics and vertical farming innovations.
- Semiconductor Inspection:Solar simulators assist in inspecting semiconductor wafers and devices for defects or performance anomalies under specific illumination.
Photovoltaic Cell Testing consistently captures the largest share of simulator deployments, while Material Research applications are experiencing significant growth.
Product Type:
Product type segmentation differentiates simulator offerings based on performance specifications and corresponding investment levels.
- Class AAA:These simulators meet the highest standards for spectral match, spatial non-uniformity, and temporal instability, as defined by IEC 60904-9. Research laboratories and certification bodies require Class AAA systems for critical R&D and precise validation of high-efficiency devices.
- Class AA:Class AA simulators offer a balanced performance profile, with slightly relaxed specifications compared to Class AAA, making them suitable for production line quality control. Electronics manufacturers and quality assurance centers frequently deploy these systems for routine testing.
- Class A:Class A simulators provide a good balance of performance and cost, often utilized for educational purposes or less demanding research applications.
- Class B:These simulators represent the entry-level segment, offering basic solar simulation capabilities for initial material screening or educational demonstrations.
Class AAA products command the highest premium due to their precision, while Class AA systems achieve broader market penetration for industrial quality control.
End User Industry:
End user industry segmentation reveals the primary institutional and commercial purchasers driving demand for solar simulation technology.
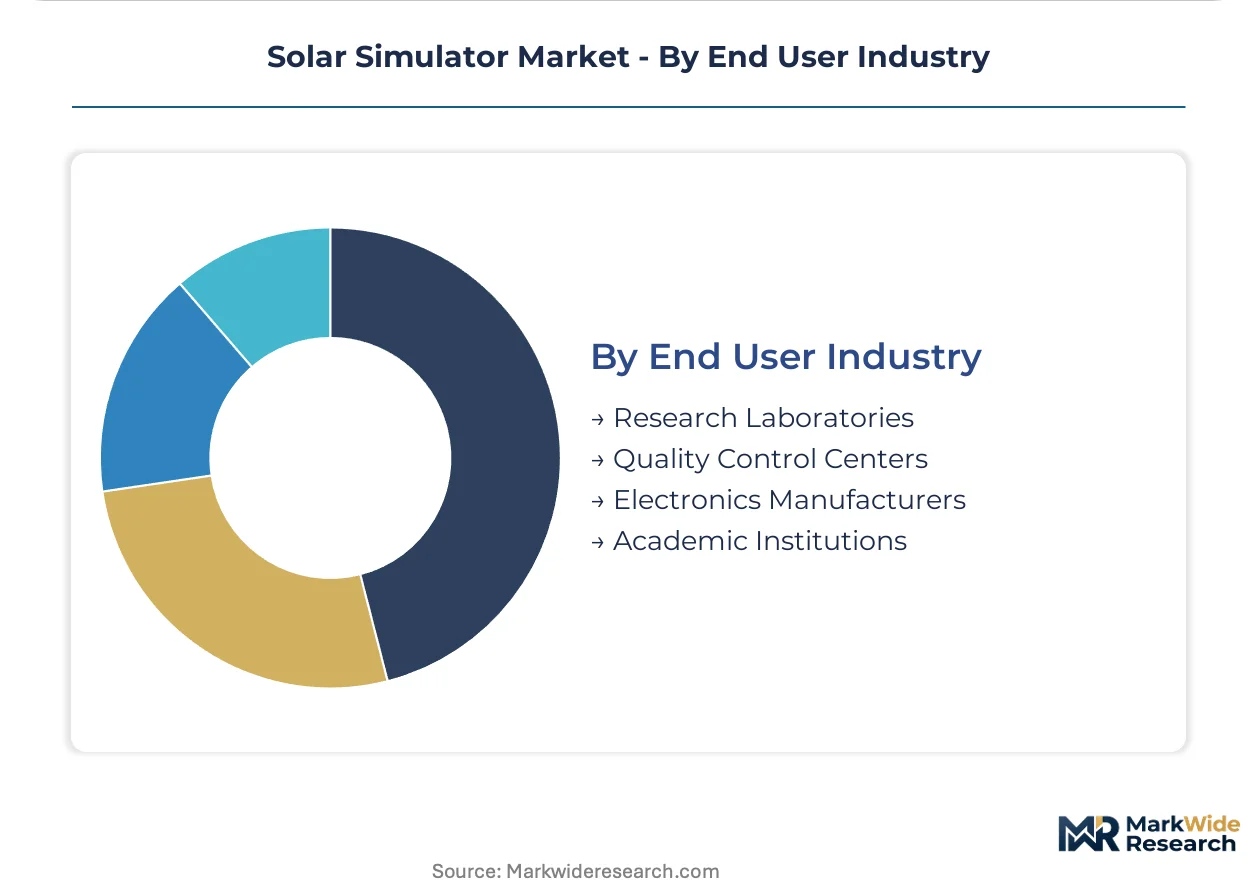
- Research Laboratories:These facilities, often affiliated with universities or government agencies, utilize simulators for fundamental and applied research into new photovoltaic materials and device architectures. Their demand emphasizes high precision and spectral tunability.
- Quality Control Centers:Located within manufacturing facilities or independent testing houses, these centers use simulators to ensure solar products meet international standards. Their focus is on throughput, repeatability, and adherence to IEC standards.
- Electronics Manufacturers:Beyond solar cells, electronics manufacturers employ simulators for testing light-sensitive components or assessing product reliability under various light conditions.
- Academic Institutions:Universities and colleges integrate solar simulators into their curricula and research projects, fostering next-generation PV scientists and engineers.
Research Laboratories are central to innovation in solar technology, while Quality Control Centers are indispensable for ensuring market compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for solar simulators exhibits a regional asymmetry, with cost-effective manufacturing in China contrasting with high-value R&D investments in Europe and North America. Global demand for advanced testing equipment continues to rise. This dynamic influences market access and technology adoption worldwide.
China
China's vast solar panel manufacturing capacity and ambitious "dual carbon goals" drive significant demand for solar simulators. Chinese manufacturers must adhere to specific GB standards for both domestic market access and export compliance. The Yangtze River Delta region, a hub for PV production, sees continuous investment in quality control and advanced research facilities.
India
India's rapid expansion in solar manufacturing, supported by national policies, fuels demand for quality control and testing equipment. The Production Linked Incentive (PLI) scheme for solar manufacturing stimulates the setup of new production lines requiring simulators. States like Gujarat and Karnataka are witnessing increased investment in PV module assembly and associated testing infrastructure.
Germany
German research institutions require high-precision solar simulators for next-generation photovoltaic material development. The EU Green Deal provides funding and policy support for renewable energy research across European universities and institutes. Bavaria and North Rhine-Westphalia house numerous Fraunhofer Institutes and university labs driving advanced PV research.
United States
United States research laboratories require superior spectral stability and tunability for accurate performance characterization of novel PV materials. Federal funding for renewable energy research supports investment in high-classification Class AAA simulators. Academic research hubs in California and the Northeast corridor lead innovation in perovskite and tandem solar cell development.
Solar Simulator Market Key Industry Players
High-precision R&D specialists and volume-oriented quality control suppliers split the solar simulator market. The industry exhibits a tiered structure, with a few large photonics companies alongside numerous niche providers. Specialist manufacturers focus on technology leadership, while others prioritize cost-effectiveness and broad market access for production lines. Companies actively pursue portfolio diversification, geographic expansion, and technology licensing to capture diverse end-user requirements across different regions.
Specialists catering to advanced research and high-volume production define the competitive landscape. Newport Corporation, with its broad photonics portfolio, exemplifies a major player serving large research institutions directly. Eternalsun occupies a position as a provider of steady-state simulators, critical for quality control in PV production lines. Sciencetech represents another archetype, offering highly customized systems for niche academic and material research applications. These companies align their offerings to specific segments, from critical R&D to industrial quality assurance.
| Leading Market Players |
|---|
| Sciencetech |
| Wacom Electric |
| Newport Corporation |
| OAI |
| Eternalsun |
| Abet Technologies |
| Solar Light |
| MKS |
| AMETEK |
| Others |
Cost & Logistics Intelligence
Pacific shipping lanes' cost dynamics influence global solar simulator pricing, reflecting supply concentration in key manufacturing hubs and driving differentiated pricing across customer segments. This market's pricing is tightly linked to the specialized components and technical expertise required for high-precision light sources.
Pricing Analysis
Configured-to-order pricing and specialized project-based models dominate the high-specification solar simulator market. Price differentiation stems from the customization level required for niche research and the stringent certification level (Class AAA) demanded by advanced R&D. Pricing pressure intensifies for Class AA systems due to competition from established xenon-based alternatives. Academic institutions and startups exhibit higher price sensitivity compared to large research institutions and certification bodies.
Supply Chain Analysis
The supply of specialized components, such as high-purity quartz for xenon lamps and specific optical filters for LED arrays, concentrates in a few global suppliers. China's extensive PV manufacturing ecosystem also supports a growing component supply base, while Germany and Japan contribute high-precision optical elements. Single-source vulnerability for critical optical components presents a significant structural risk. Distribution runs through a dual model, with direct sales to major research institutions and regional distributors serving fragmented academic landscapes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar simulator market is experiencing a cyclical recovery, primarily driven by national energy policies and extensive government support for renewable energy research.
For Market Incumbents:Build intellectual property moats around advanced LED array technology and proprietary spectral control algorithms. Invest in continuous R&D to meet testing demands of next-generation perovskite solar cells, mitigating threats from rapidly evolving PV material science. Secure long-term supply agreements for critical optical components to reduce single-source vulnerability. Expand global IEC 60904-9 certification efforts to reinforce market leadership in precision testing.
For New Entrants and Emerging Players:Untapped niche applications like indoor photovoltaics and agrivoltaics represent penetrable entry points for specialized simulator solutions. Focus product development on unique spectral conditions required for vehicle-integrated solar panels. Partner with specialized academic research institutions to co-develop tailored testing platforms. Leverage advanced software integration for data analysis, providing a differentiated go-to-market angle.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized technology providers with strong IP in LED-based simulation and spectral tunability. The long-term viability of advanced PV materials ensures sustained demand for high-precision testing equipment. Target acquisition archetypes include companies with proprietary optical designs or advanced software for data integration. Increased regulatory mandates for novel PV material testing signal an inflection point for accelerated growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced LED Array R&D | Newport Corporation gains a competitive edge in precise spectral control for perovskite solar cell characterization. |
| Global IEC 60904-9 Certification | Eternalsun strengthens its position in quality control by ensuring compliance for PV production lines. |
| Niche Application Product Development | Sciencetech captures new demand in indoor photovoltaics by tailoring systems for unique spectral needs. |
| Optical Component Supply Chain Partnerships | Manufacturers mitigate supply chain risks by diversifying sources for high-purity quartz and specialized filters. |
| Regional Distributor Training Programs | Companies enhance market access and customer support through technically proficient local partners in Europe and China. |
Research Approach
A standing panel of photovoltaic cell researchers, quality control engineers, optical component suppliers, and certification body representatives provided ongoing calibration. This approach combined primary interviews with industry stakeholders and secondary validation from IEC standards documents, academic journals on perovskite cells, and national energy policy reports. Bottom-up and top-down triangulation ensured robust data consistency.
Scenario-bracketing anchored the analytical framework, modeling market behavior across the analysis window. Segmentation dimensions included light source type, application, product type, end user industry, and PV material type. Compound annual growth rates were derived from historical trends and projected adoption curves, considering PV manufacturing capacity and R&D funding for novel materials as key inputs.
Macroeconomic conditions sit as an overlay; deviation in global R&D spending or renewable energy investment would shift the trajectory. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Cross-checking against International Energy Agency (IEA) reports on solar deployment is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
US Solar Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Turkey Solar Energy Market