
 Saudi Arabia Solar PV Module Market | 2026-2036
Saudi Arabia Solar PV Module Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Solar PV Module Market Intelligence
The direct procurement channel between module manufacturers and Saudi IPPs is narrowing as developers seek long-term supply security. Trina Solar leverages its high-volume manufacturing base to secure multi-year offtake agreements with kingdom-based project sponsors. Abdul Latif Jameel Energy & Environmental Services anchors its position through integrated EPC and financing capabilities that reduce counterparty risk for local utilities. ACWA Power competes by controlling development timelines from origination through operations, locking in captive module demand across its project pipeline.
A solar PV module is a packaged assembly of photovoltaic cells laminated between protective glass and encapsulant layers, typically rated between 400 and 700 watts under standard test conditions, designed to convert incident sunlight into direct-current electricity for grid or off-grid applications. Monocrystalline modules command premium placement in utility-scale tenders where land constraints favor maximum output per square meter. Bifacial technology is gaining fastest traction among desert installations that exploit reflected irradiance from sandy terrain to boost yield. Thin film occupies a niche in building-integrated applications where weight and flexibility outweigh efficiency metrics.
SASO mandates thermal cycling and humidity-freeze testing protocols that exceed baseline IEC standards, filtering out suppliers lacking desert-proven product validation. The Saudi Electricity and Co-generation Regulatory Authority shapes grid connection timelines that directly influence module procurement scheduling for hybrid and grid-tied configurations. The Ministry of Energy's renewable energy project development office coordinates auction design that rewards module efficiency and local content commitments. Stakeholders must monitor how domestic manufacturing incentives under the National Industrial Development Center reshape supplier qualification criteria and logistics patterns.
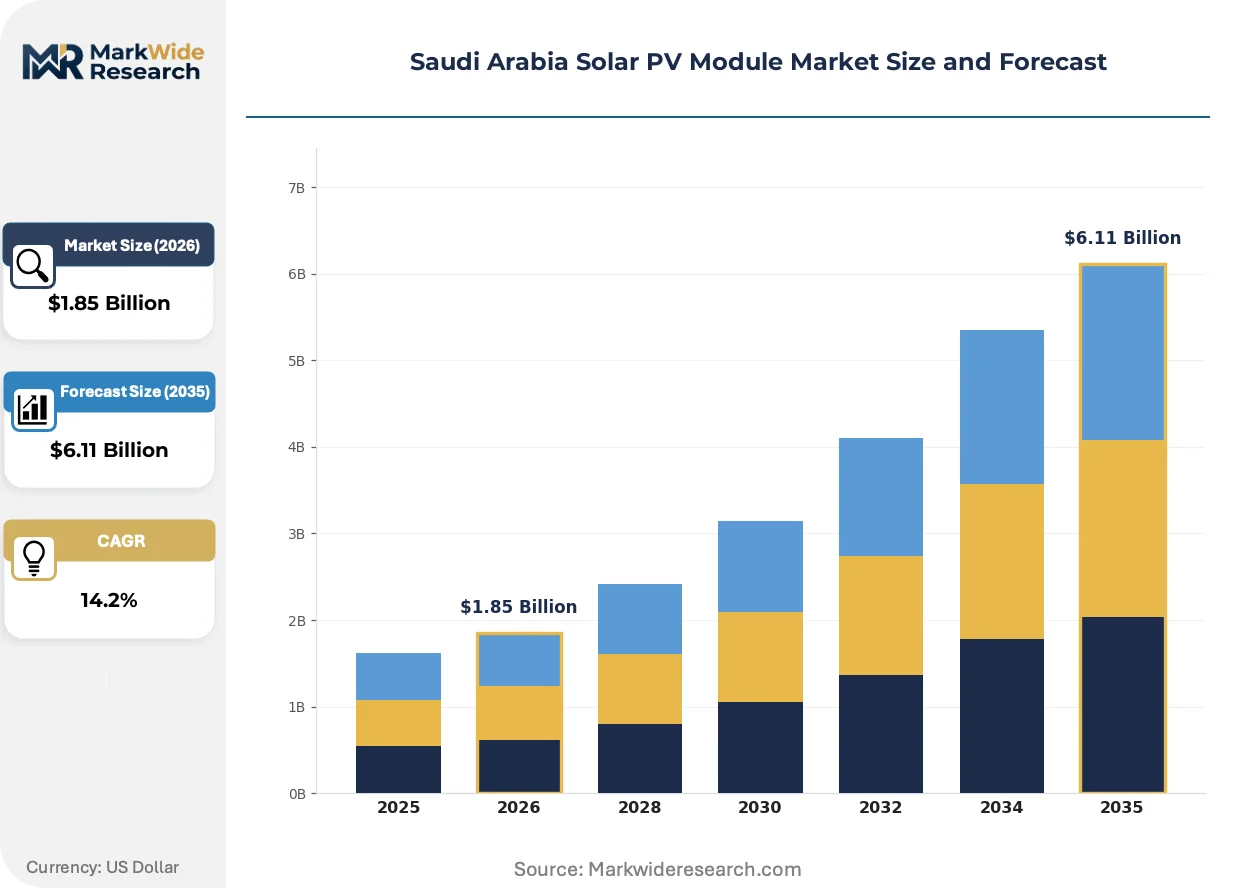
Market Dynamics
Utility-scale developers in Saudi Arabia are consolidating procurement power through multi-year offtake frameworks that bypass traditional distributor networks entirely. This channel compression is forcing module manufacturers to co-locate technical support teams in Riyadh and Jeddah to retain contract eligibility.
Growth Catalysts
- Saudi Vision 2030 renewable targets:The kingdom's 50% clean electricity mandate by 2030 is accelerating gigawatt-scale solar park development in Riyadh and Makkah regions.
- SASO desert durability standards:Tightened certification protocols for thermal cycling and humidity-freeze testing are filtering out underqualified suppliers and raising barriers to entry.
- Bifacial module technology:Reflected irradiance capture from sandy terrain is boosting yield premiums for double-sided cell architectures in Neom and Red Sea coastal installations.
Market Restraints
- Polysilicon supply concentration:Raw material sourcing remains concentrated among Chinese ingot producers, exposing Saudi developers to input cost volatility and logistics disruption.
- Land access fragmentation:Complex tribal land tenure systems in Najd province delay site preparation timelines and compress module delivery windows.
- Grid interconnection queues:SECRA approval timelines for hybrid configurations extend project commissioning by 8-14 months beyond module installation completion.
Strategic Opportunities
- Tabuk province green hydrogen integration:Electrolyzer off-take agreements are creating captive demand for high-capacity factor solar arrays with 25-year module performance guarantees.
- National Industrial Development Center incentives:Domestic manufacturing subsidies are attracting cell and module assembly investments to King Abdullah Economic City.
- Building-integrated photovoltaics:Thin-film flexible modules are penetrating commercial facade applications in Jeddah's King Abdullah Financial District where weight constraints dominate.
Industry Challenges
- Desert-proven technician scarcity:Local workforce development lags behind installation velocity, forcing EPCs to import commissioning specialists from India and South Korea.
- SASO certification timeline compression:Extended laboratory testing protocols for UV degradation and sand abrasion delay product qualification by 4-6 months versus IEC baseline.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Solar PV Module Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $6.11 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Module Type: Monocrystalline, Polycrystalline, Bifacial, Thin Film Installation Type: Grid-Tied, Off-Grid, Hybrid, Rooftop End User: Residential, Commercial, Industrial, Utility Scale Technology: Photovoltaic, Concentrated Solar Power, Organic Photovoltaics, Building-Integrated Photovoltaics |
| Companies Covered | Trina Solar, Abdul Latif Jameel Energy & Environmental Services, Alfanar, TAQA Arabia, Nesma & Partners, ACWA Power, GTek Solar, Sharp, JinkoSolar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Solar PV Module Market Strategic Shifts & Innovations
Module-level power electronics and predictive analytics are penetrating Saudi utility-scale installations as developers seek to maximize yield from constrained land parcels. These embedded intelligence layers are compressing operations expenditure and reshaping supplier qualification criteria.
Module-integrated microinverters and DC optimizers are digitizing performance monitoring at the string level. ACWA Power and Abdul Latif Jameel Energy are mandating embedded sensors in 500MW-plus tenders to enable real-time degradation tracking. This granularity is digitizing warranty claim verification and shifting supplier liability toward availability-based contracting.
SASO's 2024 update to thermal cycling test protocols exceeds IEC 61215 baseline by 40% additional cycles. The Saudi Standards, Metrology and Quality Organization is disqualifying modules without desert climate validation from utility-scale eligibility. Manufacturers with existing Middle East reference installations are accelerating product requalification to maintain tender access.
Direct procurement between IPPs and tier-one manufacturers is displacing distributor intermediaries in Riyadh and the Eastern Province. Project sponsors are consolidating volume commitments into 3-5 year framework agreements to lock supply security. This channel rationalization is most visible in the 1.5GW Sudair and 2GW Al Shuaibah developments where single-source module procurement dominates.
Saudi Arabia Solar PV Module Market Segmentation
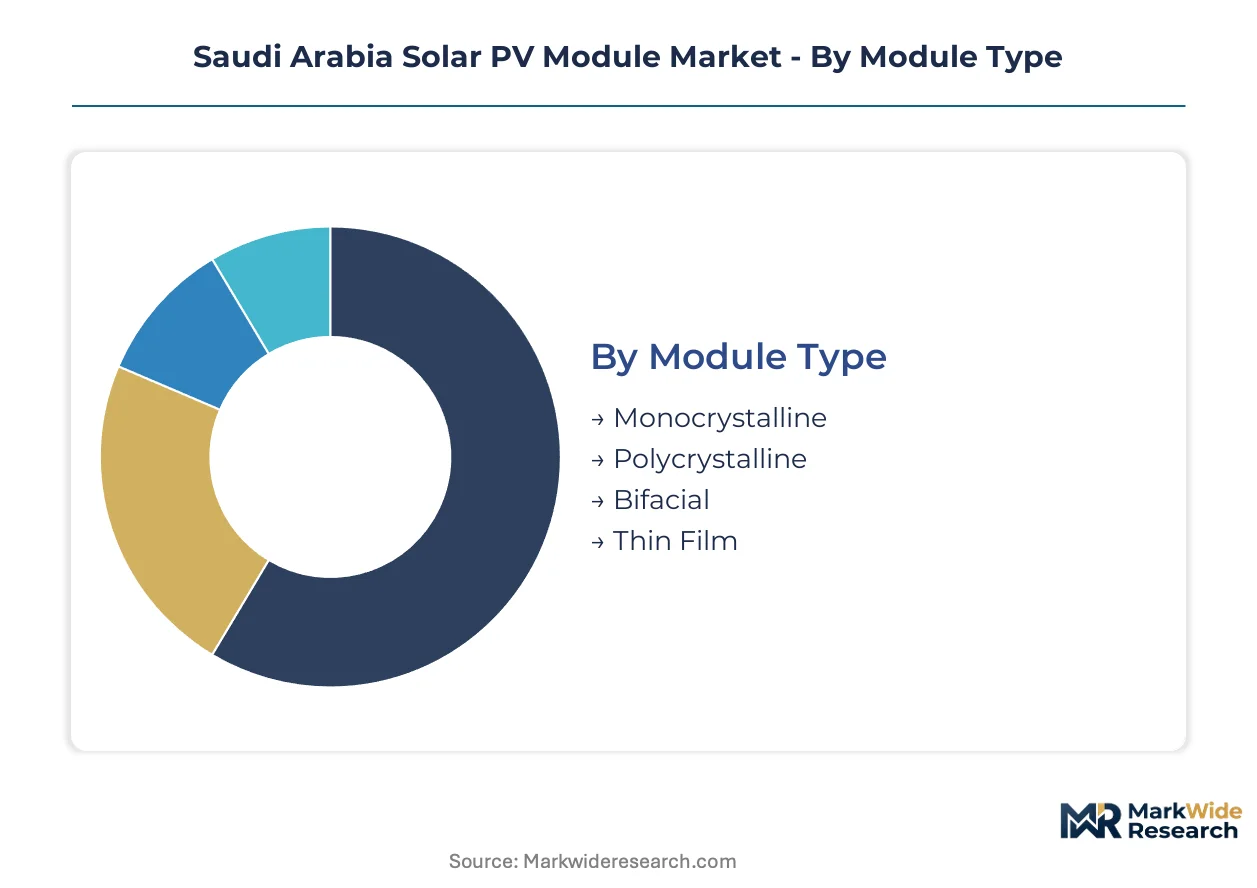
Saudi Arabia's solar PV module procurement patterns diverge sharply across installation scale and technology type. SASO certification requirements and Vision 2030 land allocation priorities are compressing supplier qualification timelines for some segments while extending them for others.
Module Type:
Cycle times vary from 18-month requalification windows for desert-proven bifacial architectures to 4-6 month delays for thin-film entrants lacking regional reference data.
- Monocrystalline:Silicon ingots sliced from single-crystal boules deliver conversion efficiencies exceeding 21% under standard test conditions. Demand concentrates in Riyadh province gigawatt-scale parks where land scarcity rewards maximum output density and developers prioritize modules with 25-year linear performance warranties.
- Bifacial:Double-sided cell architectures capture direct and reflected irradiance through transparent rear encapsulation. Neom and Red Sea coastal installations exploit sandy albedo to boost yield premiums, with procurement cycles accelerating as EPCs validate rear-side gain assumptions in Saudi desert conditions.
- Polycrystalline:Multi-crystalline silicon wafers trade efficiency for cost positioning in distributed commercial rooftops across Jeddah's industrial zones.
- Thin Film:Cadmium telluride and CIGS layers on flexible substrates serve building-integrated applications where weight constraints dominate efficiency metrics.
Monocrystalline anchors the volume base while bifacial gains share at the steepest rate.
Installation Type:
Cost tiers separate utility-scale grid-tied configurations from premium-priced hybrid systems requiring dual inverter architectures and battery integration.
- Grid-Tied:Direct utility interconnection without storage buffers dominates procurement volume under SECRA tariff frameworks. Makkah region solar parks prioritize this architecture for its capital efficiency and streamlined commissioning protocols.
- Hybrid:DC-coupled battery integration enables evening discharge and grid stabilization services. Tabuk province green hydrogen developers specify hybrid configurations to maximize electrolyzer capacity factors and secure 24/7 renewable offtake.
- Off-Grid:Stand-alone systems with integrated storage serve remote agricultural pumping and telecom towers in Najd province.
- Rooftop:Distributed commercial installations on Jeddah and Dammam warehouse structures face fragmented permitting timelines.
Grid-tied commands the dominant cost tier while hybrid climbs fastest in project value per megawatt.
End User:
Application scale determines procurement channel structure, from direct manufacturer-IPP frameworks for utility volumes to distributor-mediated residential transactions.
- Utility Scale:Single-source procurement of 500MW-plus blocks under 3-5 year framework agreements. ACWA Power and Sudair project sponsors negotiate direct tier-one manufacturer relationships, bypassing distributor margins entirely.
- Industrial:Captive power for desalination, petrochemical, and mining operations in Jubail and Yanbu industrial cities. Offtakers prioritize availability-based contracting with embedded performance guarantees.
- Commercial:Distributed generation for retail, hospitality, and logistics facilities across Riyadh and Jeddah metropolitan areas.
- Residential:Smallest volume segment with highest customer acquisition costs and longest payback periods in Saudi tariff structures.
Utility scale concentrates procurement power while industrial expands most quickly behind corporate renewable targets.
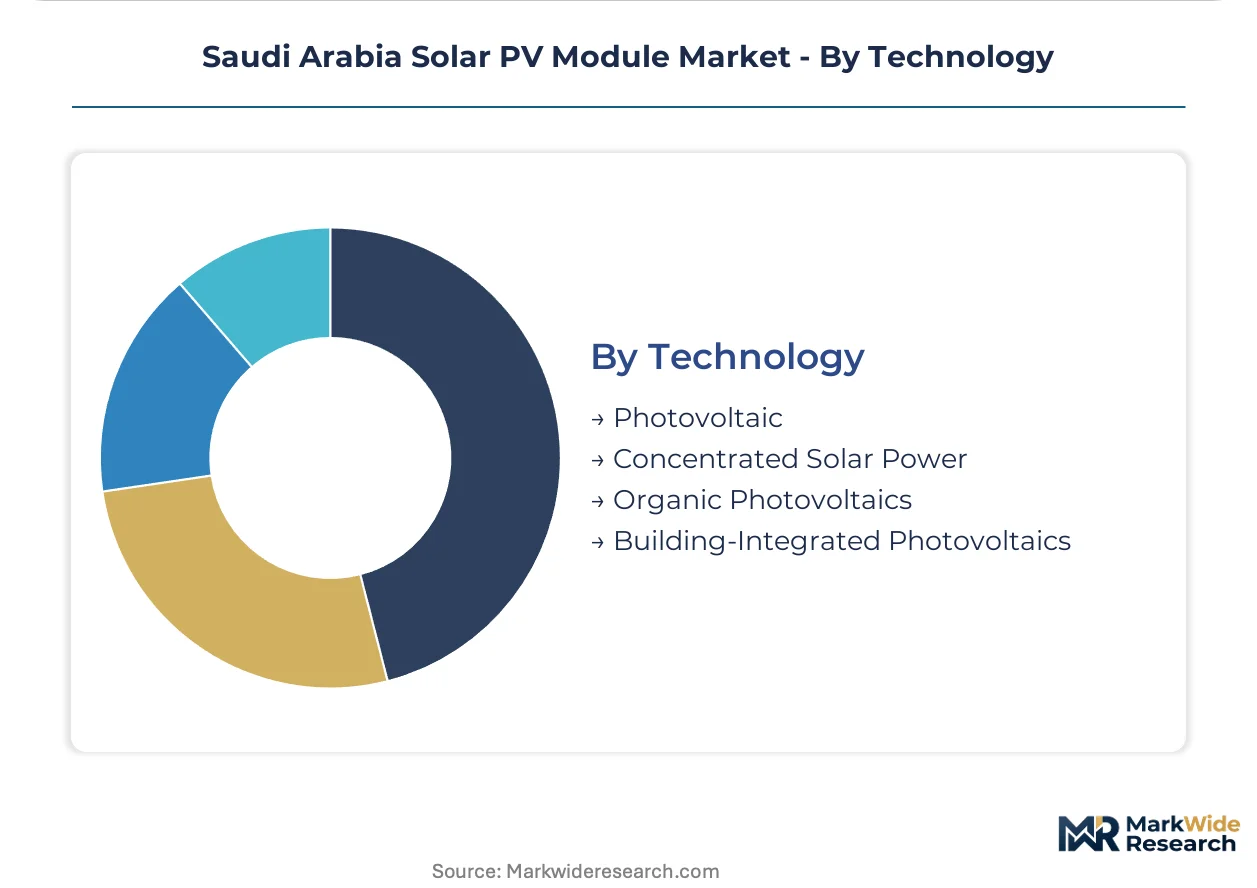
Technology:
Supply concentration separates crystalline silicon photovoltaic dominance from nascent organic and building-integrated alternatives with limited domestic manufacturing scale.
- Photovoltaic:Crystalline silicon cell architectures account for procurement volumes across all Saudi installation scales. King Abdullah Economic City manufacturing incentives are attracting cell and module assembly investments to localize supply.
- Building-Integrated Photovoltaics:Thin-film and transparent electrode configurations replace conventional facade materials. King Abdullah Financial District towers in Jeddah specify BIPV for aesthetic integration and thermal load reduction.
- Concentrated Solar Power:Parabolic trough and tower configurations with thermal storage serve grid-firming roles in hybrid renewable parks.
- Organic Photovoltaics:Polymer-based cells remain pre-commercial for Saudi applications, constrained by UV degradation rates in desert climates.
Photovoltaic dominates installed capacity while building-integrated photovoltaics shows the steepest expansion trajectory in premium commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh province commands pricing leverage over Eastern Province developers due to concentrated gigawatt-scale procurement volumes and streamlined land allocation under Vision 2030. The kingdom's solar deployment clusters in four distinct sub-regions, each shaped by unique regulatory frameworks and industrial specialization.
Riyadh
The central province anchors Saudi module demand through the 1.5GW Sudair solar park and adjacent gigawatt-scale developments. SASO certification timelines compress here due to proximity to testing laboratories and regulatory headquarters. King Abdullah City for Atomic and Renewable Energy coordinates project origination from its Riyadh base, accelerating procurement cycles for utility-scale sponsors.
Eastern Province
Jubail and Yanbu industrial cities generate captive demand for high-availability modules serving petrochemical and desalination complexes. SECRA grid interconnection protocols for industrial self-generation create specialized procurement channels distinct from utility-scale frameworks. The Dammam metropolitan corridor concentrates EPC technical resources and module warehousing infrastructure.
Western Region
Makkah province solar parks exploit high irradiance levels along the Red Sea coastal plain. Bifacial module deployment accelerates here as developers validate rear-side gain assumptions on sandy terrain. The Jeddah Islamic Port serves as the primary import gateway for containerized module shipments from Asian manufacturing bases.
NEOM Northwest
The Tabuk province green hydrogen complex creates integrated demand for high-capacity-factor solar arrays with 25-year performance guarantees. Hybrid configurations dominate procurement specifications to maximize electrolyzer utilization rates. NEOM's regulatory sandbox enables accelerated project timelines outside standard SECRA approval queues.
Saudi Arabia Solar PV Module Market Key Industry Players
Integrated energy conglomerates and specialized solar developers split the market into distinct capability tiers. Consolidation pressure intensifies as multi-year offtake frameworks favor suppliers with captive project pipelines and in-house EPC resources. Three archetypes dominate: state-linked utilities with development origination control, diversified industrial groups with financing integration, and pure-play module manufacturers with high-volume manufacturing scale. Competitive moves center on securing land access rights and locking polysilicon supply through upstream partnerships.
Within the integrated developer tier, ACWA Power and Abdul Latif Jameel Energy exemplify the convergence of project origination, construction execution, and long-term asset ownership. Trina Solar anchors the manufacturer-direct procurement channel, leveraging high-volume production capacity to secure framework agreements with Saudi IPPs. Alfanar occupies a position bridging domestic EPC execution with regional module supply relationships.
| Leading Market Players |
|---|
| Trina Solar |
| Abdul Latif Jameel Energy & Environmental Services |
| Alfanar |
| TAQA Arabia |
| Nesma & Partners |
| ACWA Power |
| GTek Solar |
| Sharp |
| JinkoSolar |
| Others |
Cost & Logistics Intelligence
Chinese polysilicon ingot concentration funnels margin capture downstream toward module manufacturers with captive wafer supply and long-term offtake contracts with Saudi IPPs. This upstream chokepoint amplifies pricing power for tier-one suppliers while compressing margins for distributors bypassed in direct procurement frameworks.
Pricing Analysis
Configured-to-order pricing for SASO-certified bifacial modules commands a premium against standard monocrystalline units lacking desert validation. Project-based long-term offtake agreements dominate utility-scale procurement, with price differentiation driven by certification grade and volume scale. Cost compression in standard-tier modules is intensifying as Chinese manufacturers absorb polysilicon volatility through backward integration. Industrial self-generators in Jubail and Yanbu exhibit highest price sensitivity, while NEOM green hydrogen developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between China and Saudi Arabia's trading partners dominates supply chain risk calculus for module importers. Manufacturing concentrates in China, Vietnam, and Malaysia, with raw material dependencies spanning polysilicon, silver paste, and aluminum frames. Single-source vulnerability around high-purity silicon feedstock threatens delivery continuity for projects with compressed commissioning windows. Distribution runs through Jeddah Islamic Port container terminals directly to project sites, bypassing traditional warehousing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi solar PV module market is entering a cyclical recovery phase driven by gigawatt-scale auction rounds under Vision 2030 capacity targets. Procurement velocity will accelerate as grid interconnection backlogs clear and land allocation frameworks stabilize.
For Market Incumbents: Build certification moats by accelerating SASO desert durability requalification ahead of 2024 protocol updates. Incumbents should lock polysilicon supply through upstream partnerships in China and co-locate technical support teams in Riyadh to defend against distributor bypass. Securing captive land access rights in Tabuk province insulates project pipeline visibility from tribal tenure fragmentation. For New Entrants and Emerging Players: Pursue white-space opportunities in thin-film building-integrated modules for Jeddah commercial facades, where weight constraints and aesthetic requirements filter out crystalline competition. The most penetrable entry point lies in hybrid configuration DC-optimizers and module-level power electronics, with go-to-market traction through EPC technical specification influence rather than direct manufacturer competition. For Investors and Strategic Acquirers: Capital is best deployed toward integrated developers controlling origination-through-operations timelines with captive module demand pipelines. Long-term viability across the analysis window favors asset owners with SECRA grid queue priority and National Industrial Development Center manufacturing incentives. The signal to watch is SASO certification timeline compression for bifacial entrants, which would indicate qualification barrier elevation and incumbent margin protection.| Strategic Initiative | Industry Significance |
|---|---|
| Desert Durability Certification Investment | SASO protocol compliance secures utility-scale tender eligibility against underqualified competitors. |
| Polysilicon Supply Backward Integration | Upstream control over Chinese ingot sourcing buffers margin compression from raw material volatility. |
| Direct IPP Framework Agreements | Multi-year offtake contracts with ACWA Power and Abdul Latif Jameel Energy displace distributor intermediaries. |
| Technical Support Co-location | Riyadh and Jeddah engineering teams accelerate commissioning timelines and warranty claim resolution. |
| Hybrid Configuration DC-Optimizer Integration | Embedded power electronics capture premium pricing in Tabuk green hydrogen electrolyzer projects. |
Research Approach
The analysis maps module technology tiers, installation scale configurations, and regional deployment clusters, each validated through IPP procurement officers, EPC project directors, and SASO certification engineers. Primary fieldwork combined structured interviews across Riyadh, Jeddah, and Dammam with secondary validation from SECRA regulatory filings, Ministry of Energy auction disclosures, and customs import manifests. Bottom-up project pipeline aggregation triangulates against top-down capacity target trajectories under Vision 2030 frameworks.
Forecast assumptions hold Saudi renewable capacity targets and SASO certification timelines fixed while varying polysilicon supply concentration and grid interconnection queue velocity. Segmentation dimensions span module type, installation architecture, end-user scale, and regional regulatory cluster. CAGRs derive from installed capacity build-out curves calibrated against historical auction award patterns and EPC construction timelines. Key inputs include bifacial gain validation data from Neom pilot installations and domestic manufacturing incentive utilization rates at King Abdullah Economic City.
Sensitivities concentrate around polysilicon price volatility, SECRA approval timeline extensions, and tribal land access negotiations in Najd province. Forecasts reflect documented assumptions regarding technology cost curves and regulatory enforcement consistency. Material shifts in Chinese export policy or SASO protocol stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
North America Solar Photovoltaic (PV) Market
Solar Power Systems
United Kingdom Distributed Solar Power Generation Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Global EV Solar Modules Market