
 United Arab Emirates Solar Energy Market | 2026-2036
United Arab Emirates Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Solar Energy Market Analytics
Multi-source EPC contracting is recalibrating how developers allocate engineering risk across the UAE project pipeline. Masdar leverages its integrated development platform to control project returns from origination through operations. ACWA Power anchors its regional footprint through long-term offtake structures with Emirates Water and Electricity Company. JinkoSolar competes on module supply scale, sustaining cost advantages across Gulf Cooperation Council tenders.
United Arab Emirates solar energy encompasses photovoltaic and concentrated solar power systems that convert incident radiation into electricity through semiconductor junctions or thermal-to-mechanical cycles, typically operating at 15-22% module efficiency in desert conditions with ambient temperatures exceeding 40°C. The primary commercial purpose is displacing gas-fired generation in a grid where air-conditioning loads drive peak demand curves. Photovoltaic installations dominate current capacity additions, while concentrated solar power with molten salt storage captures premium dispatch value in evening peak periods. Residential end-user adoption remains nascent relative to utility-scale procurement, though Dubai's Shams Dubai net-metering framework is expanding distributed participation.
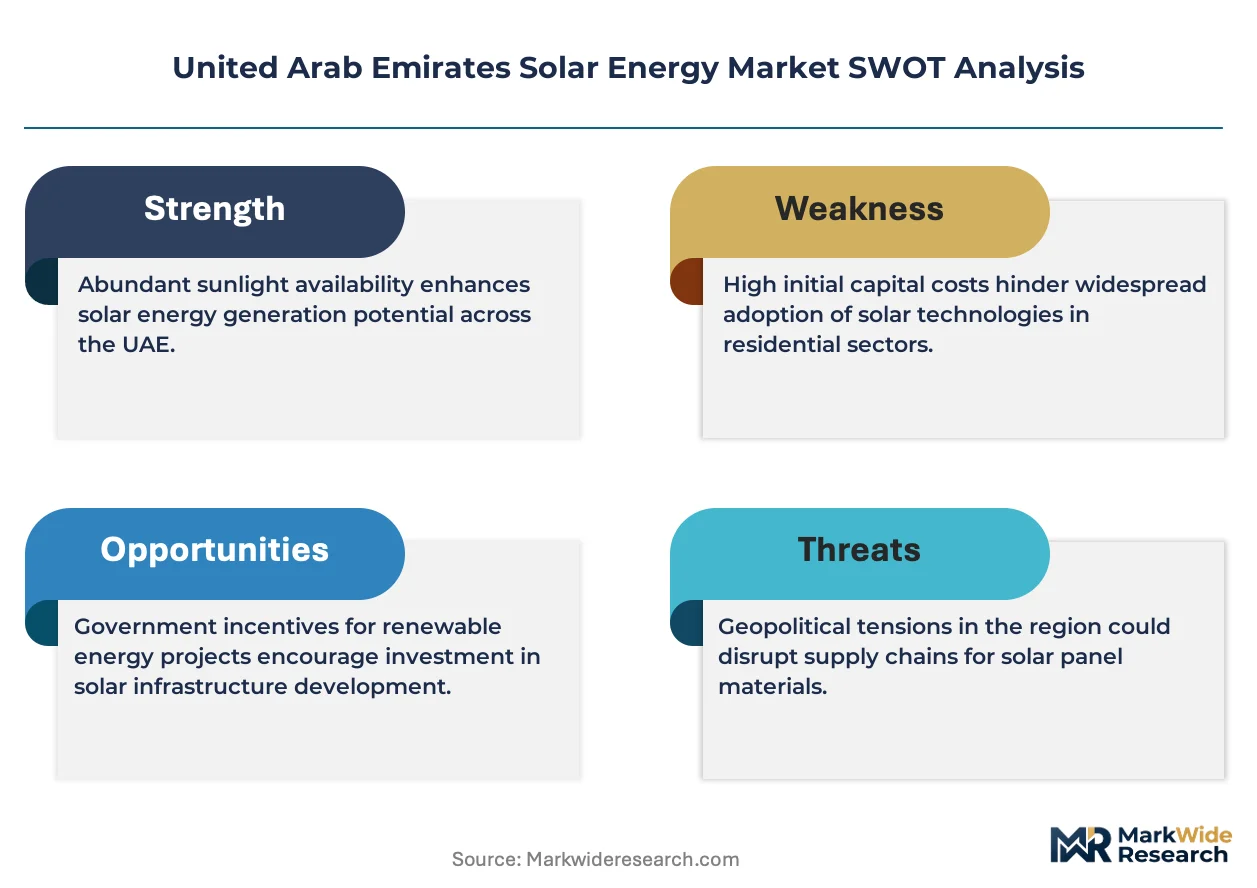
MOHAP oversees occupational safety standards for solar construction crews, while the Emirates Authority for Standardization and Metrology mandates module testing protocols under UAE-specific thermal cycling regimes. Dubai Electricity and Water Authority's regulatory mandate for 75% clean energy by 2050 institutionalizes procurement quotas that de-risk developer capital commitments. Stakeholders must track interconnection queue dynamics and land-use permitting timelines as the pipeline of gigawatt-scale projects strains available grid infrastructure and desert lease parcels.
Market Dynamics
Utility-scale procurement quotas from Emirates Water and Electricity Company are compressing developer returns while accelerating project timelines across the UAE pipeline. This single-buyer concentration is reshaping risk allocation between EPC contractors and equity sponsors.
Growth Catalysts
- Emirates Authority for Standardization and Metrology certification:Streamlined module testing protocols under UAE-specific thermal cycling regimes reduce time-to-grid for new installations.
- Al Dhafra region land availability:Vast contiguous desert parcels enable gigawatt-scale single-site developments with shared transmission infrastructure.
- Dubai Electricity and Water Authority clean energy mandate:The 75% clean energy by 2050 target institutionalizes long-term procurement visibility for utility-scale developers.
Market Restraints
- Polysilicon supply concentration:Input cost volatility from concentrated upstream refining capacity in specific geographies compresses module margin forecasts.
- Molten salt storage technical limitation:Concentrated solar power systems face efficiency degradation above 550°C, capping dispatch duration extensions.
- Grid interconnection queue friction:Emirates Water and Electricity Company approval timelines for transmission access create development bottlenecks.
Strategic Opportunities
- Shams Dubai net-metering expansion:Distributed photovoltaic participation remains underpenetrated relative to utility-scale procurement, opening residential and commercial rooftop segments.
- Abu Dhabi clean energy certificate trading:Regulatory tailwind creates new revenue streams for project sponsors beyond power purchase agreements.
- Photovoltaic-concentrated solar power hybrid convergence:Technology pairing captures both daytime baseload and evening peak dispatch premiums in single developments.
Industry Challenges
- High-voltage direct current integration complexity:Grid-forming inverter deployment for desert solar farms requires specialized commissioning expertise that outpaces local workforce supply.
- Desert soiling compliance certification:Module performance warranties under extreme dust conditions demand extended testing timelines that delay financial close.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Solar Energy Market |
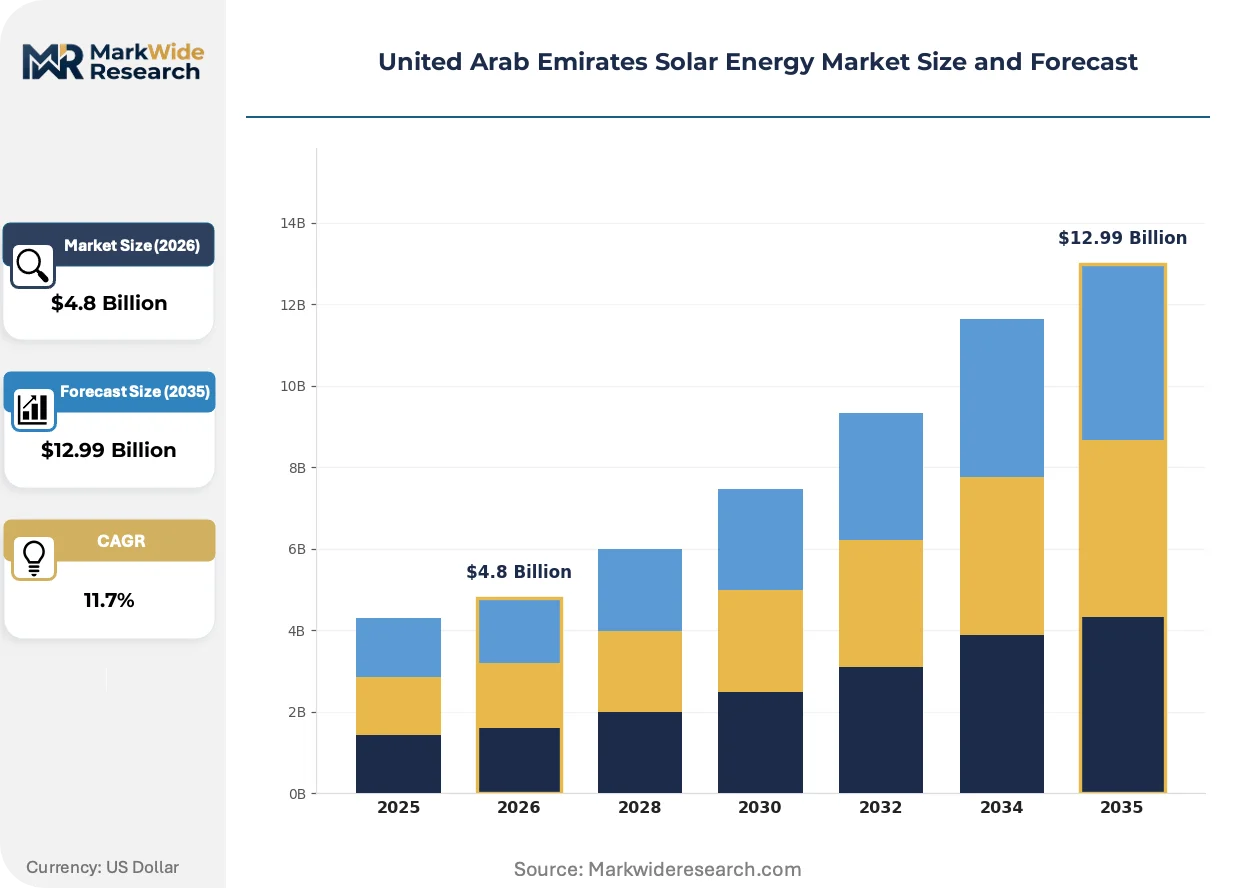
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic, Concentrated Solar Power, Solar Thermal, BIPV Technology: Solar Modules, Inverters, Mounting Systems, Tracking Systems End User: Residential, Commercial, Government, Industrial Installation Type: On-Grid, Off-Grid, Hybrid, Community Solar |
| Companies Covered | Enerwhere, First Solar, Masdar, ACWA Power, SunPower, DEWA, JinkoSolar, Scatec Solar, Yellow Door Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Solar Energy Market Evolving Landscape
Bifacial photovoltaic modules and automated robotic cleaning systems are overtaking conventional single-sided designs across the UAE project pipeline. These shifts respond to extreme soiling rates and high albedo desert surfaces.
Bifacial photovoltaic technology captures reflected irradiance from sandy terrain, boosting effective energy yield per installed watt. Emirates Water and Electricity Company procurement evaluations now weight bifacial gain assumptions in tariff bids. This specification is overtaking monofacial designs in new tender requirements, compressing competitive differentiation around tracking system precision.
Dubai's net-zero building codes mandate rooftop solar integration for new commercial structures above specific floor-area thresholds. The regulation forces developers to pre-wire electrical infrastructure during construction rather than retrofitting. Commercial real estate in Dubai Design District and Dubai South free zones faces accelerated compliance timelines.
Long-term offtake contracting with Emirates Water and Electricity Company is consolidating buyer decision authority away from distributed commercial consumers. Industrial offtakers in Jebel Ali Free Zone and Khalifa Industrial Zone Abu Dhabi now defer procurement to centralized utility scheduling. This concentration is most visible in aluminum smelting and desalination verticals where 20-year power purchase agreements anchor operational cost planning.
United Arab Emirates Solar Energy Market Segmentation
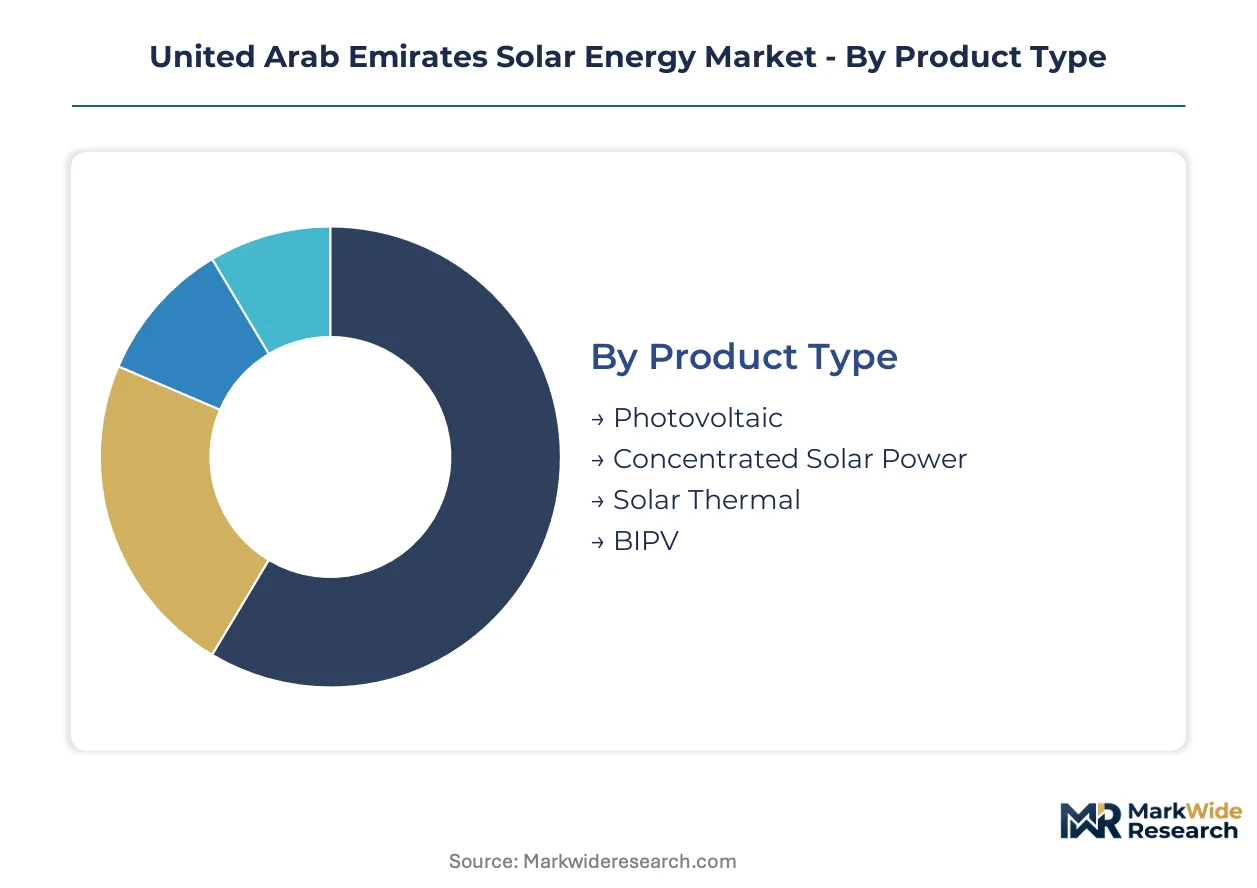
Technology and procurement configuration diverge sharply across buyer types in the UAE solar market. Emirates Water and Electricity Company tenders favor utility-scale installations with standardized equipment packages, while distributed segments demand flexible system architectures.
Product Type:
Buyers in this category differentiate by dispatch requirements and storage integration needs rather than upfront capital cost alone.
- Photovoltaic:Semiconductor junctions convert incident radiation directly to electricity at 15-22% module efficiency under desert conditions exceeding 40°C ambient temperature. Demand concentrates in Dubai's Mohammed bin Rashid Al Maktoum Solar Park and Abu Dhabi's Al Dhafra region, where Emirates Water and Electricity Company procurement quotas anchor gigawatt-scale deployment timelines.
- Concentrated Solar Power:Parabolic troughs and power towers drive thermal-to-mechanical cycles with molten salt storage capturing evening peak dispatch premiums. Al Dhafra's Noor Abu Dhabi complex exemplifies this technology's role in displacing gas-fired generation during air-conditioning load peaks.
- Solar Thermal:Low-temperature collectors address water heating loads in residential and hospitality verticals across Dubai's net-zero building code compliance zones.
- BIPV:Building-integrated photovoltaic systems embed generation capacity within facade and roofing materials, serving Dubai Design District commercial structures facing accelerated rooftop mandates.
Photovoltaic leads volumes today; concentrated solar power is gaining share fastest in evening dispatch premium capture.
Technology:
Equipment selection in this category tracks the tension between standardized procurement efficiency and site-specific performance optimization.
- Solar Modules:Bifacial designs capturing reflected irradiance from high-albedo desert terrain now dominate Emirates Water and Electricity Company tender evaluations. Module performance warranties under extreme dust soiling conditions demand extended testing timelines through Emirates Authority for Standardization and Metrology certification protocols.
- Inverters:Grid-forming inverter deployment for desert solar farms requires specialized commissioning expertise that outpaces local workforce supply. Central inverters anchor utility-scale installations while string architectures serve distributed commercial rooftops under Shams Dubai net-metering frameworks.
- Mounting Systems:Fixed-tilt aluminum structures predominate in cost-optimized utility procurement, with single-axis tracking commanding premium positioning in high-direct-normal-irradiance zones.
- Tracking Systems:Precision-driven dual-axis configurations capture premium yield assumptions in bifacial procurement bids, though mechanical complexity elevates operational expenditure forecasts.
Solar modules dominate procurement spend today; tracking systems are expanding most quickly as bifacial specifications tighten competitive differentiation.
End User:
Customer type in this category determines offtake contract structure, with centralized utility procurement displacing direct commercial engagement in energy-intensive verticals.
- Residential:Distributed photovoltaic participation remains underpenetrated relative to utility-scale procurement, though Dubai's Shams Dubai net-metering framework is expanding rooftop adoption. Individual households face interconnection queue friction and upfront capital barriers.
- Commercial:Real estate developers in Dubai South and Dubai Design District free zones confront accelerated compliance timelines under net-zero building codes mandating pre-wired solar infrastructure. Long-term offtake contracting with Emirates Water and Electricity Company is consolidating buyer decision authority away from direct commercial procurement.
- Government:Federal and emirate-level entities anchor demonstration projects and regulatory pilot programs, with Dubai Electricity and Water Authority's 75% clean energy mandate institutionalizing procurement quotas.
- Industrial:Aluminum smelting and desalination verticals in Jebel Ali Free Zone and Khalifa Industrial Zone Abu Dhabi defer procurement to centralized utility scheduling through 20-year power purchase agreements.
Industrial end users anchor contract volumes today; residential participation is climbing the fastest as net-metering frameworks mature.
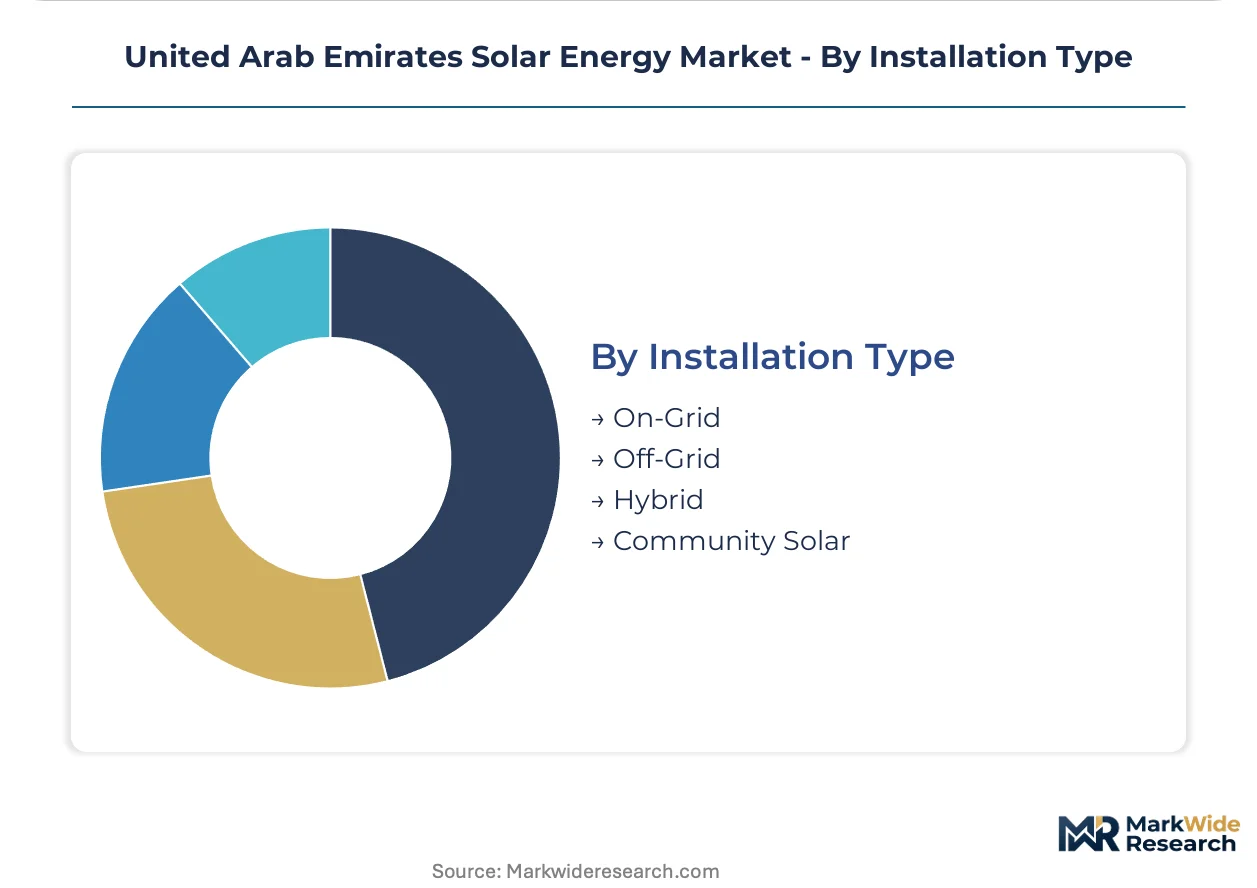
Installation Type:
Grid connection configuration in this category reflects infrastructure availability and regulatory access rather than technical preference alone.
- On-Grid:Utility-interconnected systems dominate the UAE pipeline, with Emirates Water and Electricity Company transmission access approvals creating development bottlenecks. Grid interconnection queue friction strains gigawatt-scale project timelines.
- Off-Grid:Remote desert installations and islanded industrial facilities deploy standalone photovoltaic-diesel hybrid configurations where transmission extension proves economically unviable.
- Hybrid:Photovoltaic-concentrated solar power pairings capture both daytime baseload and evening peak dispatch premiums in single developments, with molten salt storage extending dispatch duration.
- Community Solar:Shared generation models serve multi-tenant commercial structures and residential compounds, though regulatory frameworks for virtual net metering remain underdeveloped relative to direct ownership structures.
On-grid installations command absolute volume leadership today; hybrid configurations show the steepest expansion trajectory as storage economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between emirates are redistributing project origination activity across the UAE federation. Developers arbitrage permitting timelines and land-lease rates by shifting pipeline focus between Dubai's established procurement frameworks and Abu Dhabi's emerging clean energy certificate markets.
Dubai
Mohammed bin Rashid Al Maktoum Solar Park anchors gigawatt-scale deployment with phased capacity targets through 2030. Dubai Electricity and Water Authority's 75% clean energy mandate institutionalizes procurement quotas that compress developer return expectations. Jebel Ali Free Zone industrial offtakers defer to centralized utility scheduling through long-term power purchase agreements.
Abu Dhabi
Al Dhafra region offers contiguous desert parcels enabling single-site developments exceeding two gigawatts with shared transmission infrastructure. Emirates Water and Electricity Company procurement quotas reshape risk allocation between EPC contractors and equity sponsors. Khalifa Industrial Zone hosts aluminum smelting and desalination verticals tied to 20-year centralized contracts.
Sharjah
Industrial diversification away from hydrocarbon processing creates captive solar demand from manufacturing investments in Hamriyah Free Zone. Sharjah Electricity and Water Authority net-metering pilots lag Dubai's Shams Dubai framework maturity. Residential rooftop penetration remains underdeveloped relative to utility-scale procurement concentration.
Northern Emirates
Fujairah and Ras Al Khaimah exploit lower land-lease rates to attract remote industrial offtakers seeking behind-the-meter generation. Federal Ministry of Energy and Infrastructure grid extension timelines create interconnection bottlenecks for islanded project concepts. Hospitality and cement verticals in these emirates pursue hybrid photovoltaic-diesel configurations where transmission proves uneconomic.
United Arab Emirates Solar Energy Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue distributed commercial rooftop segments outside utility procurement concentration. The market structure bifurcates between integrated development platforms controlling project returns from origination through operations, and pure-play EPC contractors competing on construction cost efficiency. Three archetypes dominate: state-affiliated developers leveraging sovereign balance sheet access, regional IPPs anchoring footprint through long-term offtake structures, and Chinese module suppliers sustaining cost advantages across Gulf Cooperation Council tenders. Competitive moves concentrate on multi-source EPC contracting to allocate engineering risk, and strategic partnerships to secure land access and grid interconnection priority.
Within the integrated development platform tier, Masdar and ACWA Power exemplify archetypes that control project economics across the value chain. Masdar leverages sovereign-linked capital structures to originate utility-scale pipelines, while ACWA Power anchors regional presence through Emirates Water and Electricity Company offtake relationships. JinkoSolar represents the module supply-scale archetype, competing on equipment cost positioning in bifacial procurement evaluations.
| Leading Market Players |
|---|
| Enerwhere |
| First Solar |
| Masdar |
| ACWA Power |
| SunPower |
| DEWA |
| JinkoSolar |
| Scatec Solar |
| Yellow Door Energy |
| Others |
Value Network & Pricing Analysis
Sovereign-backed developers like Masdar and ACWA Power anchor procurement discipline through Emirates Water and Electricity Company offtake structures, compressing EPC contractor margins while stabilizing long-term tariff visibility across bifacial module and molten salt storage tiers.
Pricing Analysis
Direct-to-utility procurement discounts dominate the UAE solar market, with Emirates Water and Electricity Company tenders compressing distributor margins entirely out of the value chain. Three-tier pricing structure across premium bifacial tracking systems, standard fixed-tilt configurations, and economy-grade monofacial modules tracks certification grade and performance warranty duration under Emirates Authority for Standardization and Metrology protocols. Cost compression in economy tiers is intensifying because Chinese module suppliers sustain Gulf Cooperation Council cost advantages. Industrial offtakers in Jebel Ali Free Zone exhibit lowest price sensitivity due to 20-year power purchase agreement anchoring, while residential rooftop adopters under Shams Dubai face highest upfront capital barriers.
Supply Chain Analysis
Polysilicon supply rests on concentrated upstream refining capacity in China, with module assembly drawing from Chinese, Malaysian, and Vietnamese manufacturing hubs. Silver paste, aluminum frames, and tempered glass constitute critical raw material dependencies alongside semiconductor-grade silicon. Single-source vulnerability in high-purity polysilicon refining creates tariff exposure and logistics chokepoint risk through Strait of Malacca shipping lanes. Distribution runs through direct EPC-to-developer contracting for utility-scale projects, with specialized inverter and tracking system components sourced through regional logistics centers in Jebel Ali Port.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE solar market represents a late-cycle quality story as Emirates Water and Electricity Company procurement specifications tighten around bifacial gain assumptions and desert soiling performance warranties.
For Market Incumbents: Deploy multi-source EPC contracting to distribute engineering risk across the Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park pipelines. Incumbents must secure captive land-lease parcels ahead of grid interconnection queue bottlenecks, while investing in automated robotic cleaning system integration to defend margin position against emerging pure-play O&M specialists. For New Entrants and Emerging Players: Bifacial tracking precision technology offers entry wedge into underserved commercial rooftop segments in Dubai Design District and Dubai South free zones. Sharjah's Hamriyah Free Zone manufacturing investments and Northern Emirates behind-the-meter industrial configurations represent penetrable white-space targets, with Shams Dubai net-metering framework expansion providing regulatory tailwind for distributed generation go-to-market positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play EPC contractors lacking integrated development platforms or sovereign balance sheet access. Long-term viability over the next decade hinges on securing Emirates Water and Electricity Company offtake relationships and Al Dhafra land access. Grid interconnection approval timeline acceleration serves as the critical inflection signal warranting portfolio reweighting toward development-stage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Securement | Long-term Emirates Water and Electricity Company contracts de-risk developer capital commitments and anchor project finance. |
| Bifacial Module Technology Licensing | Access to desert-optimized designs with enhanced albedo capture secures competitive positioning in procurement evaluations. |
| Backward Integration into Tracking Systems | In-house production of precision-driven single-axis configurations captures yield premium assumptions in tariff bids. |
| Green Certification Program Enrollment | Abu Dhabi clean energy certificate trading creates incremental revenue streams beyond contracted power prices. |
| Molten Salt Storage Capacity Buildout | Evening peak dispatch premium capture displaces gas-fired generation during air-conditioning load periods. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and the Northern Emirates, with primary inputs from each emirate's regulatory and project development ecosystem. The analysis combines structured interviews with utility planning officers at Emirates Water and Electricity Company, IPP project developers, EPC contractors, and grid operators with secondary validation through IEA renewable energy reports, IRENA capacity databases, FERC-style regulatory filings, and project finance tracking databases. Bottom-up installation capacity modeling and top-down policy target reconciliation ensure cross-verified output integrity.
Rate-of-change decomposition across the analysis window isolates procurement quota acceleration, technology cost curves, and regulatory mandate enforcement timelines. Segmentation dimensions modeled include photovoltaic versus concentrated solar power technology, utility-scale versus distributed installation type, and Dubai versus Abu Dhabi versus emerging emirate regulatory frameworks. CAGRs derive from installed capacity buildout schedules against Emirates Water and Electricity Company tender pipelines and Dubai Electricity and Water Authority clean energy mandate trajectories.
The model holds under sustained Emirates Water and Electricity Company procurement quotas and Dubai Electricity and Water Authority mandate enforcement; deviation in federal grid extension timelines or polysilicon supply disruption would shift capacity addition trajectories. Forecasts reflect documented assumptions around land-lease availability and interconnection queue processing rates. A small set of triggers—bifacial module tariff adjustments, molten salt storage efficiency breakthroughs, and Sharjah net-metering framework maturation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Solar System in Kuwait Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Germany Solar Energy Market