
 Thin Film Solar PV Market | 2026-2036
Thin Film Solar PV Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Film Solar PV Market Outlook
Utility-scale procurement is hardening as the dominant demand channel for thin film modules, while building-integrated applications soften amid higher balance-of-system costs. First Solar leverages its vertically integrated cadmium telluride platform to anchor North American utility pipelines. Solar Frontier K.K. competes through specialized CIGS technology for distributed commercial rooftops across Japan.
Thin Film Solar PV denotes photovoltaic cells manufactured by depositing one or more thin layers of semiconductor material onto a substrate, typically achieving thicknesses below 10 micrometers with absorber layers of cadmium telluride, amorphous silicon, or copper indium gallium selenide. These devices convert sunlight to electricity at lower manufacturing energy intensity than crystalline silicon alternatives, serving utility-scale generation, building-integrated facades, and off-grid rural electrification. Cadmium telluride modules dominate installed capacity owing to mature manufacturing economics and First Solar's production scale. Copper indium gallium selenide segments capture premium pricing in weight-constrained applications such as aerospace and portable power. Organic photovoltaics remain experimental with niche research institute demand despite laboratory efficiency improvements.
The US Inflation Reduction Act production tax credits and domestic content bonuses shape manufacturing location decisions, while India's BIS certification mandates and PLI scheme incentives localize supply chain investments. The EU Green Deal and F-Gas Regulation constrain fluorinated gas use in semiconductor deposition processes, elevating equipment upgrade costs for European producers. Stakeholders must monitor evolving domestic content thresholds across major demand centers to calibrate manufacturing footprints and qualification timelines.
Market Dynamics
Utility-scale procurement is hardening as the dominant demand channel for thin film modules, while building-integrated applications soften amid higher balance-of-system costs. The US Inflation Reduction Act production tax credits are accelerating domestic manufacturing commitments. India and China are concentrating demand for cadmium telluride and copper indium gallium selenide installations.
Growth Catalysts
- Domestic Content Bonuses:The US IRA production tax credits with domestic content adders are pulling manufacturing investment toward American soil. Equipment suppliers are qualifying local content thresholds to capture full incentive stacks.
- Cadmium Telluride Efficiency Gains:Laboratory advances in CdTe cell architecture are narrowing the efficiency gap with crystalline silicon. First Solar's vertically integrated platform is translating these gains into utility-scale deployment economics.
- India PLI Scheme:India's production-linked incentive scheme for solar module manufacturing is localizing thin film supply chain investments. BIS certification mandates are accelerating qualification timelines for domestic producers.
Market Restraints
- Tellurium Supply Concentration:Cadmium telluride production depends on tellurium refining concentrated in copper smelting byproduct streams. Primary tellurium sources cluster in specific mining jurisdictions, creating input price volatility exposure.
- Indium Cost Structure:Copper indium gallium selenide manufacturing requires indium, a byproduct of zinc mining with concentrated primary supply. Indium price spikes transmit directly to CIGS module cost structures.
- F-Gas Regulatory Friction:The EU F-Gas Regulation constrains fluorinated gas use in semiconductor deposition processes. European producers face equipment upgrade costs to comply with phasedown schedules.
Strategic Opportunities
- Building-Integrated Photovoltaics:Thin film's lightweight, flexible form factor creates white space in facade-integrated commercial construction. Aesthetic uniformity and weight advantages penetrate premium architectural segments where crystalline silicon cannot compete.
- Agrivoltaics Convergence:Thin film's partial light transmission properties enable dual-use agricultural installations. Japan's FIT successor programs are piloting agrivoltaic tariffs that favor spectral-tunable thin film technologies.
- Off-Grid Rural Electrification:Distributed thin film installations address electrification gaps in sub-Saharan Africa and Southeast Asian archipelagos. Low manufacturing energy intensity reduces embodied carbon for climate-financed development projects.
Industry Challenges
- Semiconductor Deposition Talent Scarcity:Vacuum deposition and chemical vapor deposition expertise concentrates in legacy semiconductor and display manufacturing regions. Thin film scale-up requires competing for process engineers against established chip fabrication employers.
- Module Recycling Infrastructure:Cadmium-containing end-of-life modules require specialized hazardous waste handling. Collection and recycling networks remain underdeveloped relative to crystalline silicon recovery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Film Solar PV Market |
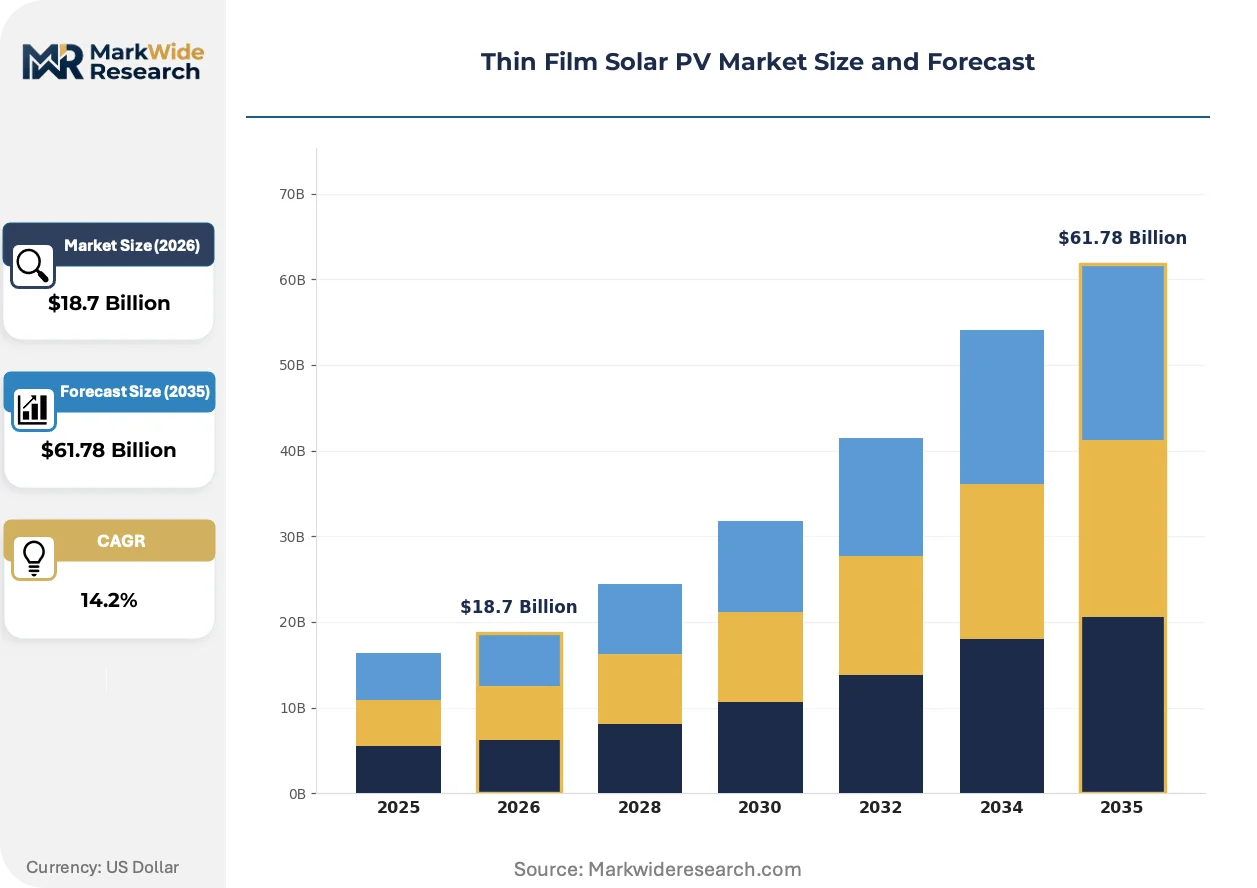
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cadmium Telluride, Amorphous Silicon, Copper Indium Gallium Selenide, Organic Photovoltaics Application: Building Integrated, Utility Scale, Residential, Commercial End User: Energy Producers, Industrial Sector, Government Projects, Research Institutes Installation: On-Grid, Off-Grid, Rooftop, Ground Mounted |
| Companies Covered | First Solar, Kaneka Corporation, Solar Frontier K.K., Hanergy Thin Film Power Group, Ascent Solar Technologies, Sharp Corporation, MiaSolé Hi-Tech Corp., Oxford PV, Avancis GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Film Solar PV Market Strategic Shifts
Perovskite tandem architectures are converging with commercial thin film manufacturing roadmaps, while regulatory frameworks accelerate supply chain regionalization. Procurement patterns are fragmenting across domestic content requirements and carbon border adjustments.
Tandem perovskite-cadmium telluride cell architectures are converging with utility-scale module design. First Solar and research consortiums are piloting two-terminal tandems that stack wide-bandgap perovskite top cells atop CdTe bottom junctions. These configurations target efficiency thresholds above single-junction limits while preserving thin film's manufacturing cost structure.
The EU F-Gas Regulation is compressing fluorinated greenhouse gas use in photovoltaic manufacturing equipment. Deposition tool suppliers are retrofitting process chambers to eliminate sulfur hexafluoride and nitrogen trifluoride chemistries. European thin film producers face capital expenditure decisions between equipment replacement and process chemistry transitions.
Utility offtakers are unbundling engineering-procurement-construction contracts from module supply agreements. Independent power developers are negotiating direct module purchase agreements with manufacturers, then competitively tendering installation services. This disintermediation is most visible in US utility-scale pipelines where IRA domestic content bonuses require traceable supply chain documentation.
Thin Film Solar PV Market Segmentation
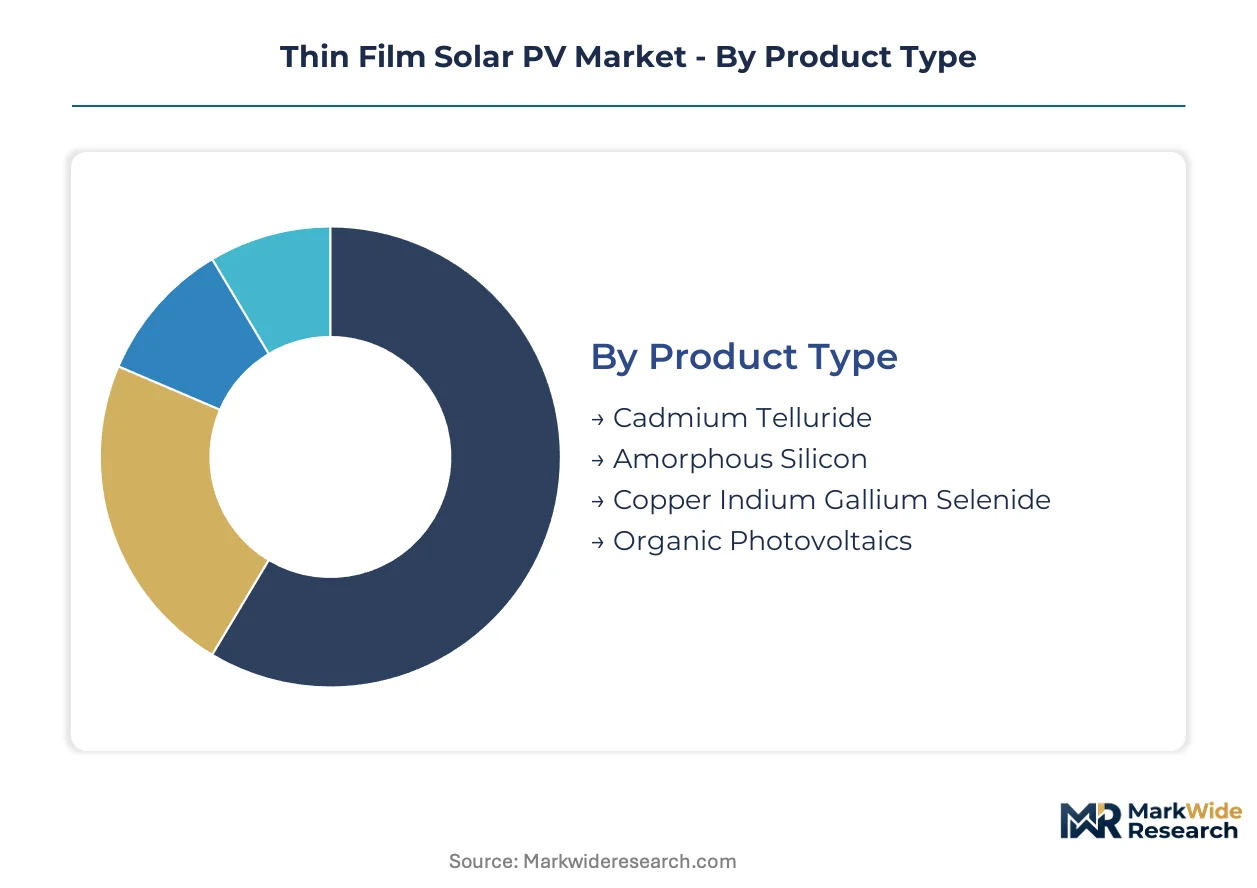
Thin film solar PV technologies occupy distinct economic niches shaped by material constraints, manufacturing scale, and regulatory incentives. Segmentation reveals where efficiency premiums justify higher input costs versus where mature process economics dominate procurement decisions.
Product Type:
Buyers differentiate primarily by module efficiency thresholds versus total installed cost targets across utility and distributed applications.
- Cadmium Telluride:Semiconductor layers deposit onto glass substrates at temperatures below 600°C, yielding modules with superior temperature coefficients. Utility-scale developers in the US and India specify CdTe for gigawatt-scale installations where First Solar's vertically integrated supply chain meets domestic content requirements.
- Copper Indium Gallium Selenide:Quaternary chalcopyrite absorbers achieve higher laboratory efficiencies than CdTe through bandgap engineering. Weight-constrained applications in aerospace and portable power absorb CIGS production despite indium cost volatility.
- Amorphous Silicon:Hydrogenated silicon deposits at low temperatures onto flexible polymer substrates. Consumer electronics and building-integrated facades in Japan leverage its spectral tunability and manufacturing versatility.
- Organic Photovoltaics:Solution-processed donor-acceptor blends enable roll-to-roll fabrication on lightweight substrates. Research institutes in Germany and South Korea pilot indoor energy harvesting and disposable electronics applications.
Volume sits with Cadmium Telluride; growth tilts toward tandem architectures integrating perovskite top cells.
Application:
Project scale determines balance-of-system cost sensitivity and module specification priorities.
- Utility Scale:Centrally controlled generation assets exceeding 50 MW capacity dominate procurement volumes. Independent power developers negotiate long-term supply agreements with CdTe manufacturers to secure IRA domestic content bonuses.
- Building Integrated:Facade and skylight installations prioritize aesthetic uniformity and weight loading limits. European commercial construction specifies thin film for heritage building retrofits where crystalline silicon imposes structural reinforcement costs.
- Commercial:Distributed rooftop systems between 100 kW and 5 MW capacity balance efficiency and installation labor costs. Japanese FIT successor programs favor spectral-tunable thin film for agrivoltaic dual-use configurations.
- Residential:Single-family and small multi-family installations compete directly with crystalline silicon on dollar-per-watt metrics. Off-grid rural electrification in sub-Saharan Africa absorbs flexible thin film modules for pay-as-you-go deployment models.
Procurement concentrates in Utility Scale; architectural specifications expand fastest in Building Integrated.
End User:
Contract structures and financing mechanisms separate institutional buyers from speculative developers.
- Energy Producers:Vertically integrated utilities and independent power producers sign 15-25 year power purchase agreements. US regulated utilities specify thin film modules with traceable domestic content to maximize IRA tax credit stacks.
- Industrial Sector:Corporate offtakers pursue renewable energy certificates and scope 2 emissions reductions. Heavy manufacturing facilities in India negotiate open access solar procurement under state-level regulations.
- Government Projects:Public sector tenders incorporate local content mandates and carbon accounting requirements. Indian Railways and defense installations specify BIS-certified thin film under federal procurement guidelines.
- Research Institutes:National laboratories and university consortia pilot next-generation cell architectures. US Department of Energy facilities validate perovskite-tandem stability under accelerated degradation protocols.
Energy Producers command procurement volume; Research Institutes drive technology transition timelines.
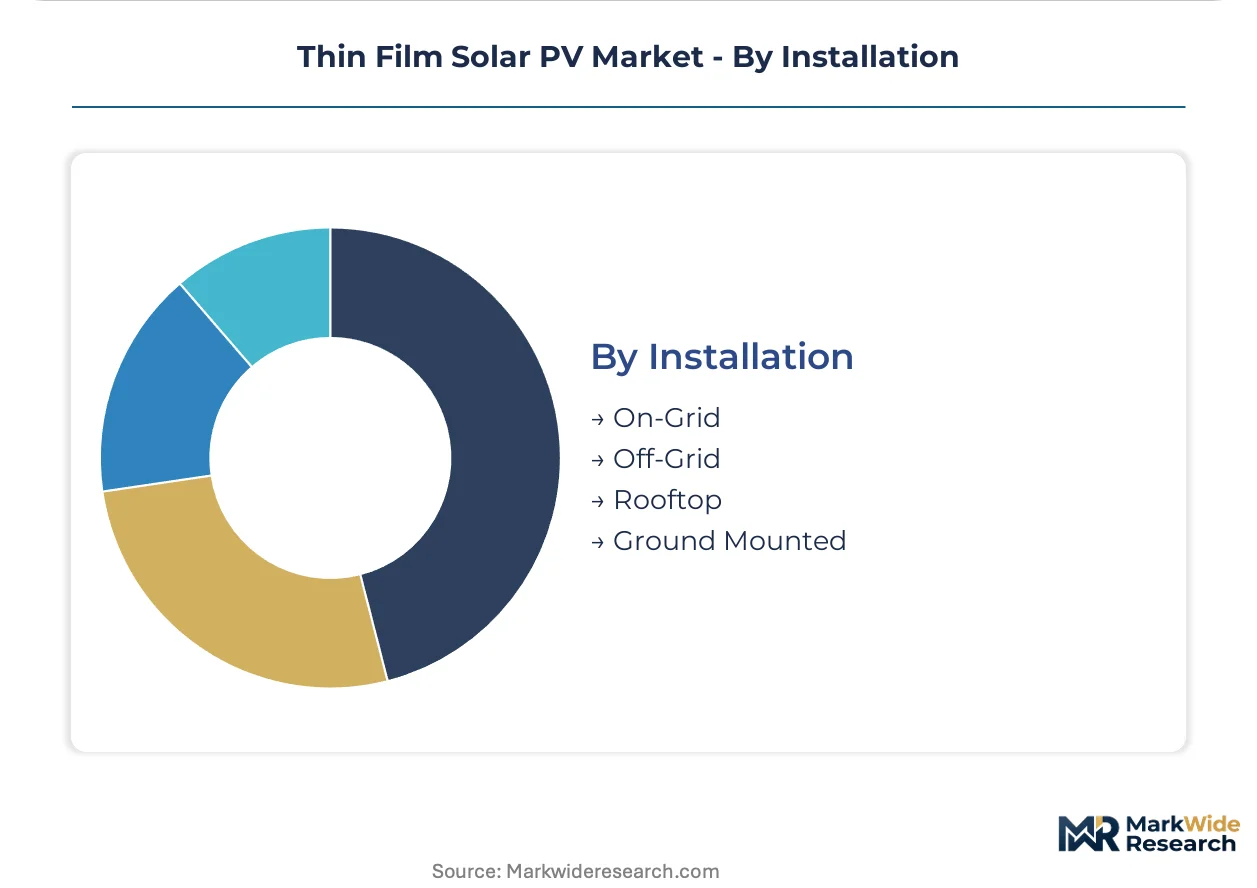
Installation:
Grid connectivity and mounting configuration determine permitting complexity and revenue structures.
- Ground Mounted:Fixed-tilt and tracking systems on agricultural or brownfield land dominate utility-scale deployment. US utility interconnection queues favor ground-mounted CdTe for streamlined permitting under FERC jurisdiction.
- On-Grid:Net-metered or feed-in-tariff connected systems sell electricity to distribution utilities. Indian state electricity boards specify on-grid thin film for agricultural pump electrification under KUSUM scheme subsidies.
- Rooftop:Building-attached and building-integrated configurations serve behind-the-meter consumption. Japanese commercial buildings deploy lightweight CIGS to avoid structural reinforcement of aging concrete substrates.
- Off-Grid:Standalone systems with battery storage serve unelectrified rural populations. Development finance institutions in Kenya and Nigeria finance pay-as-you-go thin film kits for household electrification.
Ground Mounted installations absorb manufacturing volume; Off-Grid configurations gain share fastest under climate finance mobilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's domestic content bonus zones are concentrating manufacturing investment in Ohio and Alabama, while India's PLI scheme clusters thin film capacity in Gujarat and Tamil Nadu.
United States
Utility-scale developers in Arizona and Texas specify cadmium telluride modules for gigawatt-scale solar farms. IRA production tax credits with domestic content adders require traceable supply chain documentation. First Solar's vertically integrated manufacturing in Perrysburg, Ohio anchors North American CdTe production.
India
State electricity boards in Rajasthan and Karnataka tender thin film capacity for agricultural pump electrification under KUSUM scheme subsidies. BIS certification mandates accelerate qualification timelines for domestic producers. PLI scheme incentives concentrate module assembly investments in Mundra and Sri City special economic zones.
China
Inner Mongolia and Qinghai provinces deploy cadmium telluride in utility-scale desert solar complexes. MIIT industrial policy guides thin film manufacturing toward western provinces with lower electricity costs. Hohhot and Xining host deposition equipment clusters serving domestic module producers.
Japan
Commercial building owners in Tokyo and Osaka specify copper indium gallium selenide for rooftop retrofits avoiding structural reinforcement. METI's FIT successor programs pilot agrivoltaic tariffs favoring spectral-tunable thin film. Kobe and Nagoya maintain chemical vapor deposition expertise from legacy display manufacturing.
Germany
Research consortia in Dresden and Munich pilot perovskite-tandem architectures atop cadmium telluride bottom junctions. EU F-Gas Regulation constrains fluorinated gas use in deposition equipment, elevating upgrade costs. Freiburg's Fraunhofer ISE validates next-generation cell stability under accelerated degradation protocols.
Thin Film Solar PV Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated producers commanding utility-scale procurement while research-stage players occupy tandem architecture development. The vendor base concentrates around cadmium telluride platforms and copper indium gallium selenide specialists, with limited fragmentation in organic photovoltaic niches. Two strategic archetypes dominate: scale-driven CdTe manufacturers with captive semiconductor supply, and technology licensors pursuing perovskite integration roadmaps. Competitive moves center on backward integration into tellurium refining and strategic partnerships with deposition equipment suppliers.
Among US-based vertically integrated producers, First Solar exemplifies the scale-driven archetype with in-house CdTe semiconductor production. Japanese specialists Kaneka Corporation and Solar Frontier K.K. occupy positions within the CIGS technology tier, representing alternative thin film chemistry pathways. These three anchors illustrate divergent strategic postures across material platforms and geographic demand centers.
| Leading Market Players |
|---|
| First Solar |
| Kaneka Corporation |
| Solar Frontier K.K. |
| Hanergy Thin Film Power Group |
| Ascent Solar Technologies |
| Sharp Corporation |
| MiaSolé Hi-Tech Corp. |
| Oxford PV |
| Avancis GmbH |
| Others |
Value Chain & Pricing Dynamics
First Solar's vertically integrated manufacturing model, combining in-house semiconductor deposition with captive glass substrate supply, anchors pricing discipline across North American utility procurement. This ownership structure insulates contract pricing from tellurium spot volatility while compressing balance-of-system premiums for domestic content-compliant developers.
Pricing Analysis
Short lead-time premiums command pricing separation in utility-scale offtake negotiations, with developers paying contract escalators for modules deliverable within compressed interconnection schedules. Three-tier pricing structure across premium, standard, and economy levels reflects efficiency binning, domestic content qualification status, and warranty term bundling. Cost compression in standard-tier CdTe modules is intensifying because Chinese equipment vendors are qualifying deposition tool alternatives at lower capital intensity. Price-sensitive independent power developers in India exhibit highest elasticity, while US regulated utilities with rate-base recovery mechanisms absorb premium pricing for IRA-compliant supply.
Supply Chain Analysis
Workforce availability constraints in Ohio and Alabama deposition clusters are elevating equipment operator wages above legacy semiconductor manufacturing regions. Supply concentrates in the United States, China, and India for module assembly, while tellurium refining draws from copper smelting byproduct streams in Canada, Japan, and Peru. Indium and gallium sourcing rests on zinc mining concentrates concentrated in Chinese and Korean metallurgical processing. Single-source vulnerability in high-purity tellurium creates input price volatility exposure. Distribution runs through direct manufacturer-to-developer contracts disintermediating traditional EPC bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
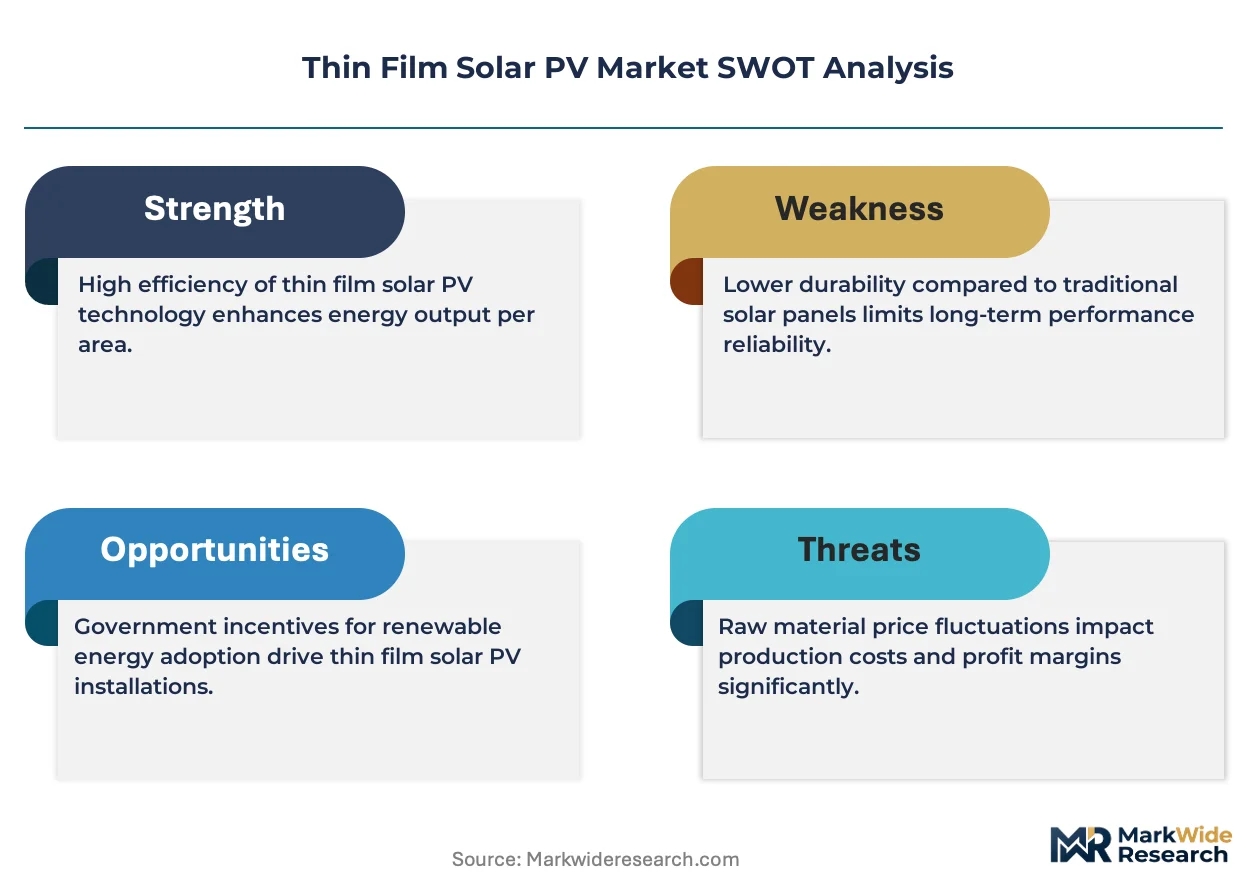
Thin film solar PV is consolidating around scale-driven CdTe platforms as indium cost volatility and domestic content mandates force CIGS specialists into niche positioning or exit.
For Market Incumbents: Anticipate perovskite-tandem disruption by piloting two-terminal architectures with research consortium partners before efficiency thresholds commoditize single-junction CdTe. Secure captive tellurium supply through offtake agreements with copper smelter byproduct streams, as primary tellurium concentration in specific mining jurisdictions creates procurement chokepoints. Backward integration into semiconductor deposition equipment qualification will defend margin position against Chinese tool vendor cost compression. For New Entrants and Emerging Players: The US IRA domestic content bonus in American utility-scale procurement opens a window for module assembly investments co-located with First Solar's Ohio and Alabama clusters. Target agrivoltaic dual-use configurations in Japan's FIT successor programs, where spectral-tunable CIGS commands tariff premiums unavailable to crystalline silicon competitors. Pursue technology licensing rather than manufacturing scale, as capital intensity of deposition equipment creates insurmountable barriers to greenfield entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor CIGS technology licensors with perovskite integration roadmaps in Japanese and German research corridors. Long-term viability hinges on tandem cell commercialization timelines and stability validation under accelerated degradation protocols. Acquisition targets should demonstrate deposition process IP and equipment supplier relationships rather than manufacturing scale. Watch US Treasury guidance on domestic content threshold calculations as the inflection signal determining qualified module pricing premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tellurium Refining | Captive supply from copper smelter byproduct streams insulates CdTe producers from spot price volatility in concentrated mining jurisdictions. |
| Perovskite-Tandem Pilot Programs | Two-terminal cell architectures with US Department of Energy validation target efficiency thresholds above single-junction CdTe limits. |
| Domestic Content Qualification Investment | IRA bonus capture requires traceable supply chain documentation through Ohio and Alabama manufacturing clusters. |
| Agrivoltaic Tariff Positioning | Japan's METI successor programs favor spectral-tunable thin film for dual-use agricultural installations with premium FIT structures. |
| Deposition Equipment Supplier Partnerships | Chemical vapor deposition expertise from legacy display manufacturing regions in Kobe and Nagoya anchors process scale-up. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining primary interviews with utility procurement officers, IPP project developers, EPC contractors, and deposition equipment suppliers with bottom-up and top-down triangulation. Secondary validation drew from FERC interconnection queue filings, EIA generation capacity databases, SEC 10-K disclosures from listed manufacturers, and India's CEA project registration records. Primary fieldwork captured contract structure evolution, domestic content qualification timelines, and tellurium procurement practices across North American and Asian supply chains.
Segmentation granularity modeled technology type, application scale, end-user contract structure, and installation configuration at the country level across the projection horizon. CAGRs were derived from utility-scale procurement pipeline analysis, manufacturing capacity expansion announcements, and regulatory incentive quantification. Industry-specific forecast inputs included IRA domestic content bonus uptake rates, India PLI scheme disbursement trajectories, and perovskite-tandem stability validation milestones from DOE national laboratory testing protocols.
Caveats apply where US Treasury guidance revisions on domestic content thresholds, EU F-Gas Regulation phase-down acceleration, or tellurium supply disruptions from copper smelter operational changes could materially shift the outlook. Forecasts reflect assumptions around continued IRA incentive continuity, India state electricity board procurement discipline, and deposition equipment cost reduction curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Chile Solar Energy Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
India Solar Inverter Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
APAC Solar Micro Inverters Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Canada Distributed Solar Power Generation Market