
 Perovskite Solar Module Market | 2026-2036
Perovskite Solar Module Market Size, Share, and Industry Trends Forecast 2026-2036
Perovskite Solar Module Market Insights
Tandem cell architecture is reshaping photovoltaic manufacturing by layering perovskite absorbers atop silicon substrates to push conversion efficiencies past single-junction limits. Oxford PV anchors European development through dedicated perovskite-on-silicon pilot facilities in Germany and the United Kingdom. Swift Solar competes in lightweight flexible module segments with solution-processed active layers optimized for building-integrated applications. Hanwha Q CELLS extends its crystalline silicon dominance into tandem development through internal perovskite R&D programs in South Korea.
A perovskite solar module employs an active layer of organometal halide perovskite crystals deposited via spin-coating, slot-die coating, or vapor deposition onto conductive substrates, typically achieving bandgaps between 1.5 and 1.7 eV that enable high absorption coefficients across visible spectra. Tandem Cells command premium positioning as the technology pathway bridging laboratory efficiency records toward commercial viability, while Flexible Modules attract capital from building-integrated photovoltaics and mobility applications where weight constraints dominate. Residential Application demand lags Utility-Scale procurement due to durability certification gaps, though this gap narrows as IEC stability testing protocols mature.
The International Electrotechnical Commission develops accelerated stress tests specific to perovskite thermal cycling and humidity degradation, while China's National Energy Administration enforces GB/T photovoltaic standards that now incorporate perovskite-specific efficiency measurement conditions. The European Union's F-Gas Regulation and REACH chemical frameworks constrain solvent choices in perovskite precursor formulations, pushing manufacturers toward greener deposition chemistries. Stakeholders must monitor which certification body first establishes a bankability standard for 25-year perovskite module warranties, as this milestone will unlock institutional project finance currently withheld from unproven degradation profiles.
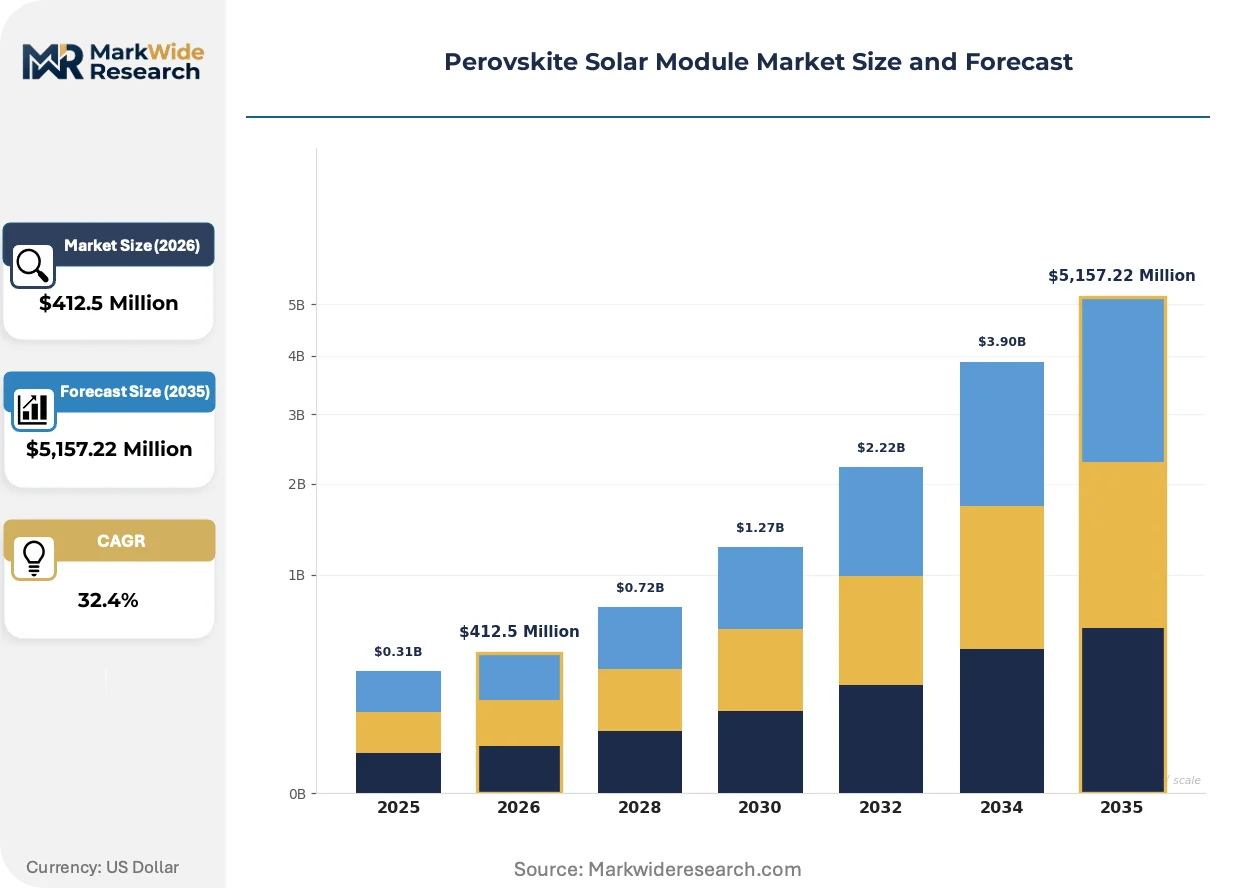
Market Dynamics
Tandem cell architecture is compressing commercialization timelines as efficiency thresholds force single-junction silicon into commodity positioning. Module procurement contracts now specify perovskite-silicon performance guarantees, rewiring supplier qualification criteria across utility-scale solar development.
Growth Catalysts
- China's GB/T photovoltaic standards:Updated certification protocols for perovskite-specific efficiency measurement create import compliance pathways that accelerate manufacturing investment in Jiangsu Province pilot lines.
- Building-integrated photovoltaics:Lightweight flexible modules unlock rooftop and facade applications where crystalline silicon weight constraints previously excluded solar deployment.
- Slot-die coating:Roll-to-roll deposition methods reduce active layer material waste versus spin-coating, improving manufacturing economics at pilot production scale.
Market Restraints
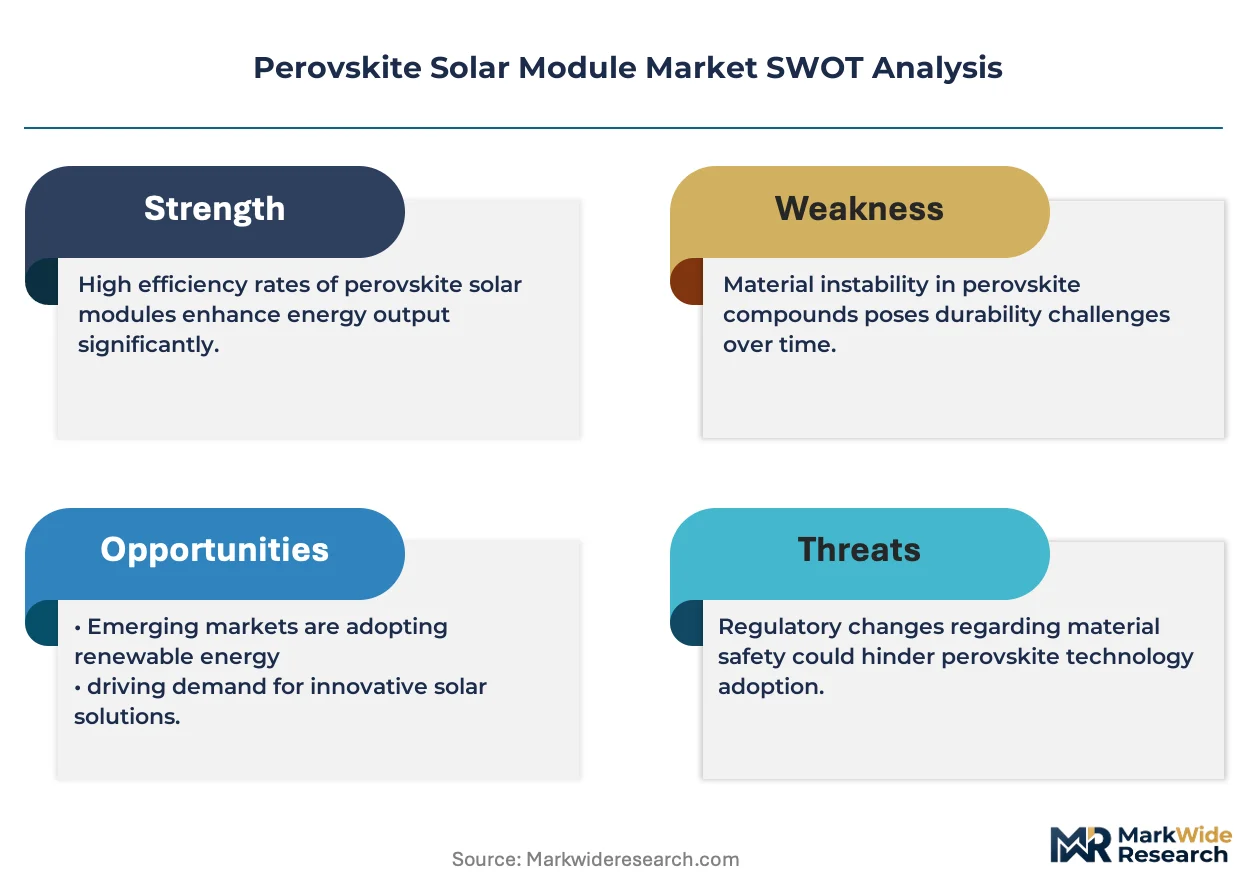
- Lead halide precursor toxicity:REACH chemical frameworks and EU F-Gas Regulation constrain solvent choices, forcing reformulation of deposition chemistries and extending qualification timelines.
- East Asian manufacturing concentration:Greater Tokyo Area and Jiangsu Province cluster over 80% of pilot tandem capacity, creating geographic supply vulnerability to regional logistics disruptions.
- Humidity-induced degradation:Moisture sensitivity of organometal halide crystals limits outdoor deployment without hermetic encapsulation, adding material cost and processing complexity.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Production-linked incentives for advanced photovoltaic technology attract perovskite module assembly investment outside current East Asian clusters.
- Mobility-integrated solar:Electric vehicle roof-integrated charging and drone applications demand ultra-lightweight power generation that silicon cannot deliver.
- Perovskite-silicon tandem + bifacial architecture:Stacking technologies capture diffuse rear-side irradiance, opening agrivoltaic and floating solar deployments with dual land-use economics.
Industry Challenges
- 25-year bankability certification:Absence of IEC accelerated stress test protocols specific to perovskite thermal cycling blocks institutional project finance for utility-scale deployment.
- Deposition technician scarcity:Solution-processed active layer manufacturing requires hybrid materials science and thin-film engineering skills rarely combined in conventional photovoltaic workforce training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perovskite Solar Module Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $5,157.22 Million |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Modules, Rigid Modules, Bifacial Modules, Tandem Cells Application: Residential, Commercial, Utility-Scale, Off-Grid Technology: Single-Junction, Multi-Junction, Hybrid, Thin-Film End User: OEMs, System Integrators, Energy Providers, Research Institutions |
| Companies Covered | Oxford PV, Saule Technologies, Microquanta Semiconductor, Hanwha Q CELLS, Greatcell Energy, Swift Solar, UtmoLight Co., Ltd., Hiking PV Technology Co., Ltd., Hubei Wonder Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perovskite Solar Module Market Trends and Innovations
Vapor deposition techniques are displacing wet chemistry methods as manufacturers prioritize uniformity control over capital cost minimization. This shift reconfigures equipment supplier relationships and cleanroom facility specifications.
Atomic layer deposition of electron transport layers is rendering obsolete spin-coated metal oxide interfaces that suffered from pinhole defects and thickness non-uniformity. European pilot facilities now specify ALD-equipped production lines for tandem cell manufacturing. The technology compresses yield loss rates and enables thinner perovskite absorber layers without efficiency penalty.
The European Union's F-Gas Regulation amendment restricts hydrofluorocarbon solvents in perovskite precursor formulations, forcing manufacturers toward aqueous or ionic liquid alternatives. This chemical substitution increases deposition equipment corrosion risk and requires stainless steel process line upgrades. German and UK pilot facilities are first-movers in retrofitting vapor recovery systems to comply with the tightened framework.
Utility-scale developers now require module-level power output guarantees backed by third-party degradation testing, displacing traditional cell-level efficiency specifications in procurement contracts. This contractual evolution forces manufacturers to invest in extended outdoor testing arrays before commercial shipment. The practice is most visible in East Asian markets where state-backed solar parks specify 30-year performance warranties.
Perovskite Solar Module Market Segmentation
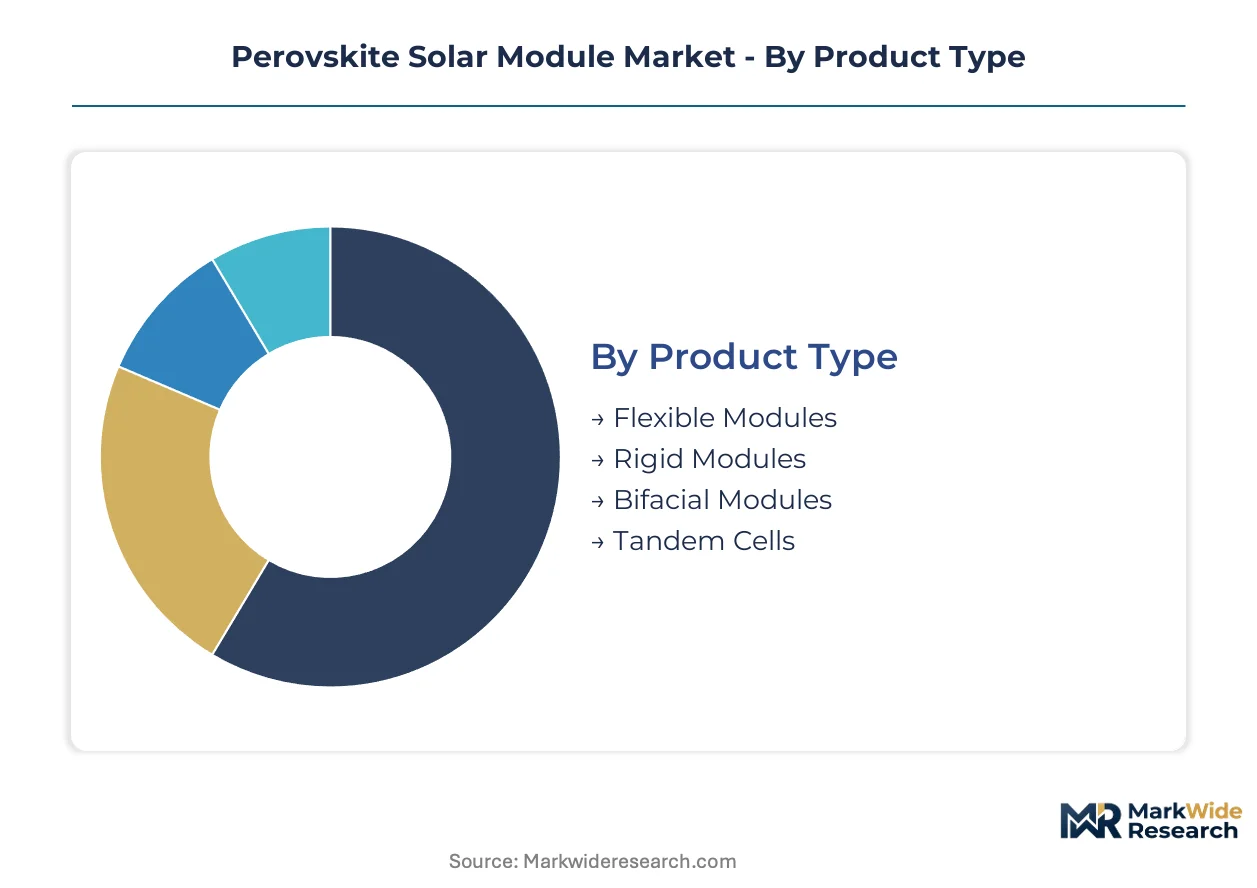
Perovskite solar module segmentation reveals how manufacturing techniques and installation contexts dictate commercial pathways. Product architecture determines deposition equipment requirements, while application verticals impose distinct certification and warranty demands.
Product Type:
Mature rigid formats dominate procurement volumes, yet emerging flexible architectures are capturing design-intensive building-integrated applications.
- Tandem Cells:Layered perovskite-silicon architectures achieve conversion efficiencies beyond single-junction limits through optimized bandgap stacking. Utility-scale developers in Jiangsu Province and the Greater Tokyo Area specify tandem performance guarantees in procurement contracts, compressing supplier qualification timelines.
- Flexible Modules:Polymer substrate-based designs employ solution-processed active layers under 500 grams per square meter. Building-integrated photovoltaic demand in European retrofit markets favors lightweight formats where crystalline silicon weight constraints previously excluded solar deployment.
- Bifacial Modules:Dual-sided light capture architectures capture diffuse rear-side irradiance for agrivoltaic and floating solar configurations.
- Rigid Modules:Glass-glass encapsulated formats prioritize hermetic sealing against humidity-induced degradation for conventional rooftop installations.
Tandem Cells retain volume leadership; Flexible Modules hold the steepest expansion curve.
Application:
Cost tier stratification separates premium utility-scale procurement from price-sensitive off-grid deployments.
- Utility-Scale:Ground-mounted solar parks exceeding 50 megawatts demand bankable 25-year performance warranties backed by IEC accelerated stress testing. China's National Energy Administration enforces GB/T standards that now incorporate perovskite-specific efficiency measurement conditions for grid-connected installations.
- Residential:Distributed rooftop systems under 20 kilowatts face durability certification gaps that lag utility-scale protocols. IEC stability testing maturation is narrowing this deployment gap as hermetic encapsulation solutions prove field reliability.
- Commercial:Mid-scale rooftop and carport installations balance space constraints against energy arbitrage economics.
- Off-Grid:Remote power systems prioritize capital cost minimization over efficiency maximization for rural electrification.
Utility-Scale commands procurement value; Residential is climbing the fastest as certification barriers erode.
Technology:
Volume concentration favors established deposition methods, while margin capture shifts toward hybrid process innovations.
- Single-Junction:Homogeneous perovskite absorber layers deposited via slot-die coating achieve manufacturing economics at pilot production scale. Roll-to-roll methods reduce active layer material waste versus spin-coating in Jiangsu Province pilot lines.
- Hybrid:Combined solution and vapor-phase deposition integrates organic and inorganic transport layers for tandem architectures. European pilot facilities specify atomic layer deposition equipment to compress yield loss rates.
- Multi-Junction:Triple-layer bandgap engineering targets concentrated photovoltaic applications.
- Thin-Film:Legacy chalcogenide alternatives face displacement as perovskite absorption coefficients enable thinner active layers.
Single-Junction retains manufacturing scale; Hybrid holds the steepest expansion curve.
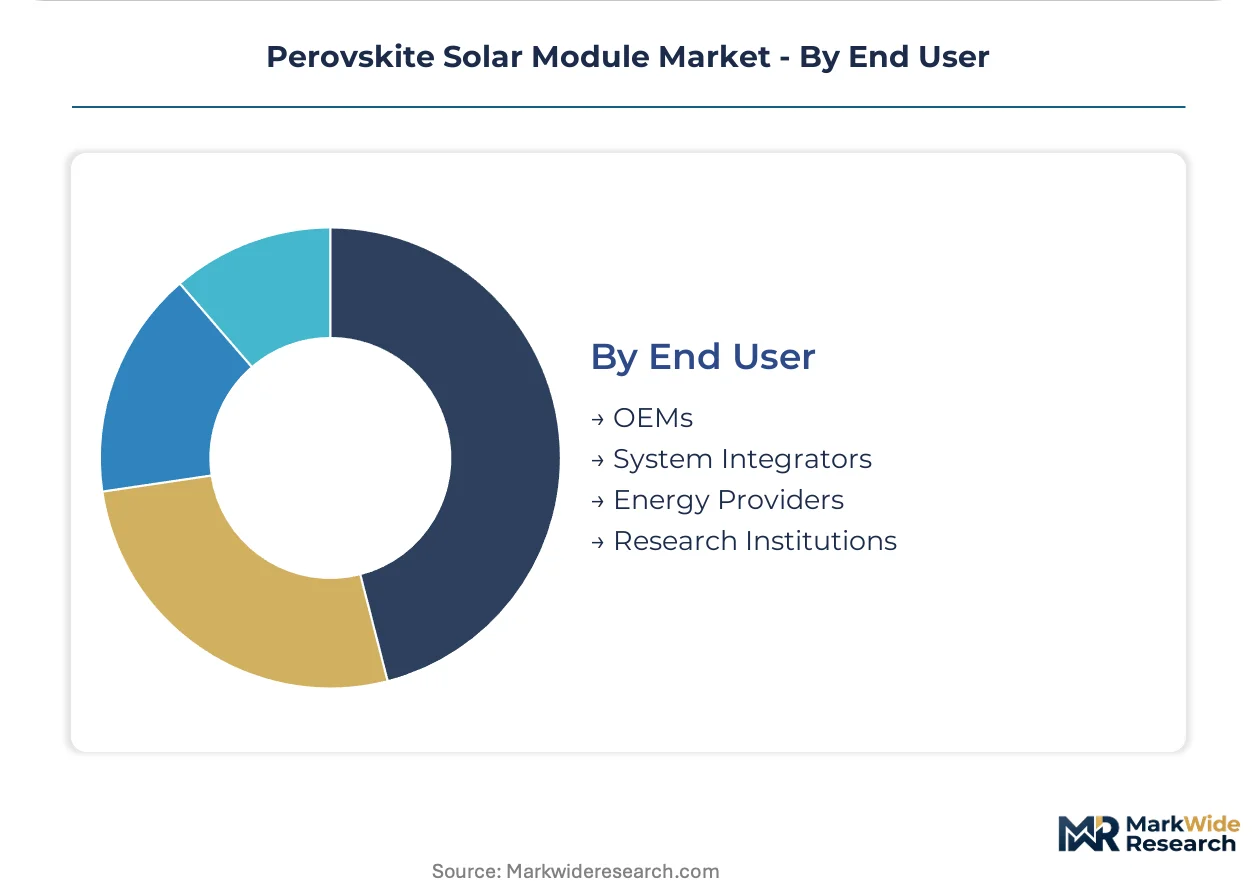
End User:
Customer type determines technical specification depth and procurement contract structure across the value chain.
- System Integrators:Engineering-procurement-construction firms bundle modules with inverter and mounting systems for turnkey solar park delivery. India's PLI scheme for solar manufacturing attracts assembly investment outside East Asian clusters for integrators serving domestic utility-scale pipelines.
- OEMs:Original equipment manufacturers incorporate modules into electric vehicle roof-integrated charging and drone mobility applications where weight constraints dominate specification requirements.
- Energy Providers:Utility and independent power producer procurement desks specify module-level power output guarantees displacing traditional cell-level efficiency metrics.
- Research Institutions:National laboratories and university consortia validate extended outdoor testing arrays before commercial shipment authorization.
System Integrators retain procurement volume; OEMs are gaining share fastest in mobility-integrated segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility-scale developers and building-integrated photovoltaic installers drive procurement across concentrated manufacturing clusters. China's Jiangsu Province pilot lines and Japan's Greater Tokyo Area facilities anchor current capacity. Regulatory divergence between IEC stability protocols and national certification standards shapes investment location decisions.
China
State-backed solar parks and dual carbon targets accelerate tandem cell procurement from domestic manufacturers. The National Energy Administration enforces GB/T photovoltaic standards incorporating perovskite-specific efficiency measurement conditions. Jiangsu Province hosts scaling pilot production lines for perovskite-silicon tandems serving both domestic utility-scale deployment and export qualification.
Japan
Corporate renewable energy procurement and building-integrated retrofit demand concentrate in metropolitan construction markets. METI coordinates with JIS standards bodies to adapt certification frameworks for emerging thin-film technologies. The Greater Tokyo Area manufacturing cluster advances vapor deposition equipment integration for tandem cell pilot production.
Germany
Industrial decarbonization mandates and commercial rooftop leasing drive flexible module adoption in retrofit applications. ECHA REACH chemical frameworks and EU F-Gas Regulation constrain solvent choices in precursor formulations, forcing equipment retrofits. Bavarian and North Rhine-Westphalian pilot facilities lead European atomic layer deposition adoption for electron transport layer manufacturing.
United States
Independent power producers and engineering-procurement-construction firms specify module-level performance guarantees in utility-scale procurement. The Inflation Reduction Act production tax credits attract perovskite manufacturing investment outside East Asian supply chains. California and Texas utility-scale pipelines incorporate tandem performance specifications in developer qualification criteria.
South Korea
Electric vehicle roof-integrated charging and mobility applications create OEM demand for ultra-lightweight power generation. MFDS chemical safety standards intersect with environmental ministry regulations governing lead halide precursor handling. Seoul Capital Area R&D programs extend crystalline silicon manufacturing expertise into internal perovskite tandem development initiatives.
Perovskite Solar Module Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base segmented by deposition technology and application focus. Consolidation pressure intensifies as utility-scale procurement contracts specify tandem performance guarantees that favor integrated manufacturers with captive testing infrastructure. Three archetypes dominate: silicon incumbents extending into perovskite tandem development, pure-play perovskite specialists pursuing building-integrated niches, and equipment-integrated solution providers controlling deposition process IP. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing pilot line equipment allocation and third-party degradation testing relationships ahead of bankability certification milestones.
Among European specialists, Oxford PV and Saule Technologies occupy positions representing distinct strategic archetypes in tandem versus flexible module development. Chinese manufacturers including Microquanta Semiconductor and Hiking PV Technology Co., Ltd. exemplify scale-oriented players leveraging domestic pilot line infrastructure. South Korea's Hanwha Q CELLS represents silicon incumbent extension into perovskite R&D, while Swift Solar anchors North American lightweight flexible module specialization. These companies illustrate how geographic clustering around Jiangsu Province, Greater Tokyo Area, and European pilot facilities shapes competitive positioning without yet producing clear market share hierarchies.
| Leading Market Players |
|---|
| Oxford PV |
| Saule Technologies |
| Microquanta Semiconductor |
| Hanwha Q CELLS |
| Greatcell Energy |
| Swift Solar |
| UtmoLight Co., Ltd. |
| Hiking PV Technology Co., Ltd. |
| Hubei Wonder Solar |
| Others |
Pricing and Supply Chain Analysis
Lead halide precursor toxicity exposure under REACH chemical frameworks and EU F-Gas Regulation constraints determines both pricing tier spreads across certified versus uncertified module grades and supply chain shape through forced solvent reformulation and equipment retrofit requirements.
Pricing Analysis
Cost-plus contracts with lead halide precursor indexation dominate procurement agreements between Jiangsu Province pilot lines and utility-scale developers. Pricing stratifies across IEC-certified premium tiers, GB/T-compliant standard tiers for Chinese domestic deployment, and uncertified economy tiers for early-stage pilot shipments. Cost compression in economy tiers is intensifying because deposition technician scarcity extends qualification timelines and inflates yield loss penalties. Residential installers exhibit highest price sensitivity due to durability certification gaps, while utility-scale IPPs prioritize bankable performance guarantees over unit cost minimization.
Supply Chain Analysis
Upstream feedstock for organometal halide precursors draws from Chinese rare earth processing clusters, German chemical synthesis facilities, and South Korean electronic-grade solvent refiners. Methylammonium iodide, lead iodide, and spiro-OMeTAD hole transport materials constitute critical input dependencies. Single-source vulnerability concentrates in Jiangsu Province for slot-die coating equipment and Greater Tokyo Area for vapor deposition chambers. Distribution runs through engineering-procurement-construction firms bundling modules with inverter systems for turnkey solar park delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perovskite solar module market sits at a high-growth disruption inflection where IEC bankability certification for 25-year warranties will unlock institutional project finance currently withheld from unproven degradation profiles.
For Market Incumbents: Harden supply chain resilience through backward integration into lead halide precursor synthesis and captive atomic layer deposition equipment production. Oxford PV and Hanwha Q CELLS should accelerate extended outdoor testing array investments ahead of competitor qualification, as vapor deposition technician scarcity creates bottlenecks that favor first-movers with established cleanroom workforces. For New Entrants and Emerging Players: Build out lightweight flexible module assembly capacity targeting India's PLI scheme for solar manufacturing, where production-linked incentives attract investment outside East Asian clusters. Building-integrated photovoltaic retrofit markets in Germany offer the most penetrable white-space, with polymer substrate-based designs under 500 grams per square meter displacing crystalline silicon where weight constraints previously excluded deployment. Partner with automotive OEMs for electric vehicle roof-integrated charging specifications. For Investors and Strategic Acquirers: The market sits at a pre-bankability phase that favors equipment-integrated solution providers controlling deposition process IP over pure-play module assemblers. Long-term viability over a five-to-ten year window hinges on which certification body first establishes 25-year warranty standards. Monitor IEC accelerated stress test protocol finalization as the critical signal for institutional capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bankability Certification Investment | IEC 25-year warranty standards unlock project finance from institutional lenders. |
| Backward Integration into Precursors | Lead halide synthesis control reduces REACH compliance cost volatility. |
| ALD Equipment Partnership | Atomic layer deposition adoption compresses yield loss in tandem manufacturing. |
| Extended Outdoor Testing Arrays | Utility-scale procurement now mandates module-level degradation validation. |
| PLI Scheme Manufacturing Localization | India's incentives diversify supply chains beyond Jiangsu and Tokyo clusters. |
Research Methodology
Cross-validation between primary interviews with utility-scale developers, EPC contractors, deposition equipment suppliers, and GB/T certification auditors anchors the qualitative findings against secondary validation from IEC standard drafts, China's National Energy Administration policy circulars, EU F-Gas Regulation amendments, and SEC filings from photovoltaic equipment manufacturers. Bottom-up module shipment estimates from Jiangsu Province and Greater Tokyo Area pilot lines triangulate against top-down utility-scale procurement pipeline data.
Calibration against historical silicon photovoltaic penetration curves and thin-film cadmium telluride commercialization timelines informs the analytical framework across the projection horizon. Segmentation dimensions span product architecture, application vertical, deposition technology, and end-user archetype. CAGRs derive from installed capacity buildout assumptions tied to dual carbon goal trajectories and production tax credit eligibility under the Inflation Reduction Act.
Practitioners should monitor IEC accelerated stress test protocol finalization, REACH chemical framework amendments, and India's PLI scheme disbursement rates for early signals of forecast revision. Cross-checking against IEA photovoltaic technology roadmaps and BloombergNEF levelized cost of electricity benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
US Residential Solar PV Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Egypt Solar Energy Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market