
 Turkey Solar Energy Market | 2026-2036
Turkey Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Turkey Solar Energy Market Outlook
Project finance through long-term power purchase agreements is rewriting competitive access for developers without balance-sheet depth. Kalyon PV leverages integrated polysilicon-to-module manufacturing to sustain cost leadership across domestic tenders. Borusan EnBW Enerji anchors its position through utility-scale pipeline control in western Anatolia. CW Enerji specializes in distributed commercial installations, navigating regional permitting complexity that slows smaller competitors.
Turkey Solar Energy encompasses photovoltaic systems converting solar irradiance into electricity through semiconductor junctions, with monocrystalline panels achieving conversion efficiencies exceeding 21% under standard test conditions. These installations serve grid-connected generation, industrial self-consumption, and rural electrification where distribution infrastructure remains sparse. Utility-scale ground-mounted deployments dominate installed capacity, though residential roof-mounted segments are expanding fastest as net metering improves payback periods. Bifacial technology adoption is rising in the private sector end-user category, where entrepreneurs seek differentiated yield profiles for commercial projects.
EMRA licensing requirements and the Ministry of Energy's YEKDEM tariff framework shape project economics and grid access timelines for developers nationwide. BIS-equivalent testing protocols and CEA-aligned grid codes enforce module quality and inverter compatibility standards that filter out uncertified suppliers. Stakeholders must monitor auction design changes and local content rules that determine which technology configurations qualify for premium tariffs.
Market Dynamics
Industrial self-consumption tariffs under EMRA's revised net metering framework are compressing payback periods for commercial rooftop installations across Anatolia.
Growth Catalysts
- YEKDEM tariff guarantees:The Renewable Energy Support Mechanism provides 10-year fixed purchase agreements that de-risk project finance for utility-scale developers in high-irradiance provinces.
- Polysilicon-to-module localization:Domestic manufacturing clusters in Ankara and Konya are reducing import dependency for crystalline silicon components used in monocrystalline panel assembly.
- Industrial electricity hedging:Textile and ceramics manufacturers in western Anatolia are deploying captive rooftop systems to offset volatile grid pricing from state utility tariffs.
Market Restraints
- Land use permitting friction:Agricultural protection zones in Konya Plain block utility-scale ground-mounted development despite superior solar resource profiles.
- Inverter supply concentration:Power electronics sourcing remains concentrated among East Asian suppliers, exposing Turkish EPCs to shipping cost volatility and customs clearance delays.
- Grid interconnection queues:TEIAS transmission infrastructure upgrades lag behind generation capacity additions, creating multi-year connection backlogs for projects in eastern regions.
Strategic Opportunities
- Agrivoltaics in Mediterranean provinces:Dual-use installations combining photovoltaic canopies with greenhouse cultivation remain underdeployed in Antalya and Mersin despite compatible agronomic conditions.
- Energy storage co-location:Lithium-ion battery integration with existing solar farms opens ancillary service revenue streams under EMRA's emerging frequency regulation market rules.
- Commercial PPA origination:Direct bilateral contracts between developers and large industrials bypass wholesale market exposure, creating captive offtake structures for new capacity.
Industry Challenges
- Electrical engineering talent scarcity:Grid integration specialists and SCADA technicians command premium wages, constraining EPC execution timelines for complex commercial installations.
- BIS-equivalent certification delays:Module testing protocols aligned with EU standards create 4-6 month approval bottlenecks for new supplier market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Turkey Solar Energy Market |
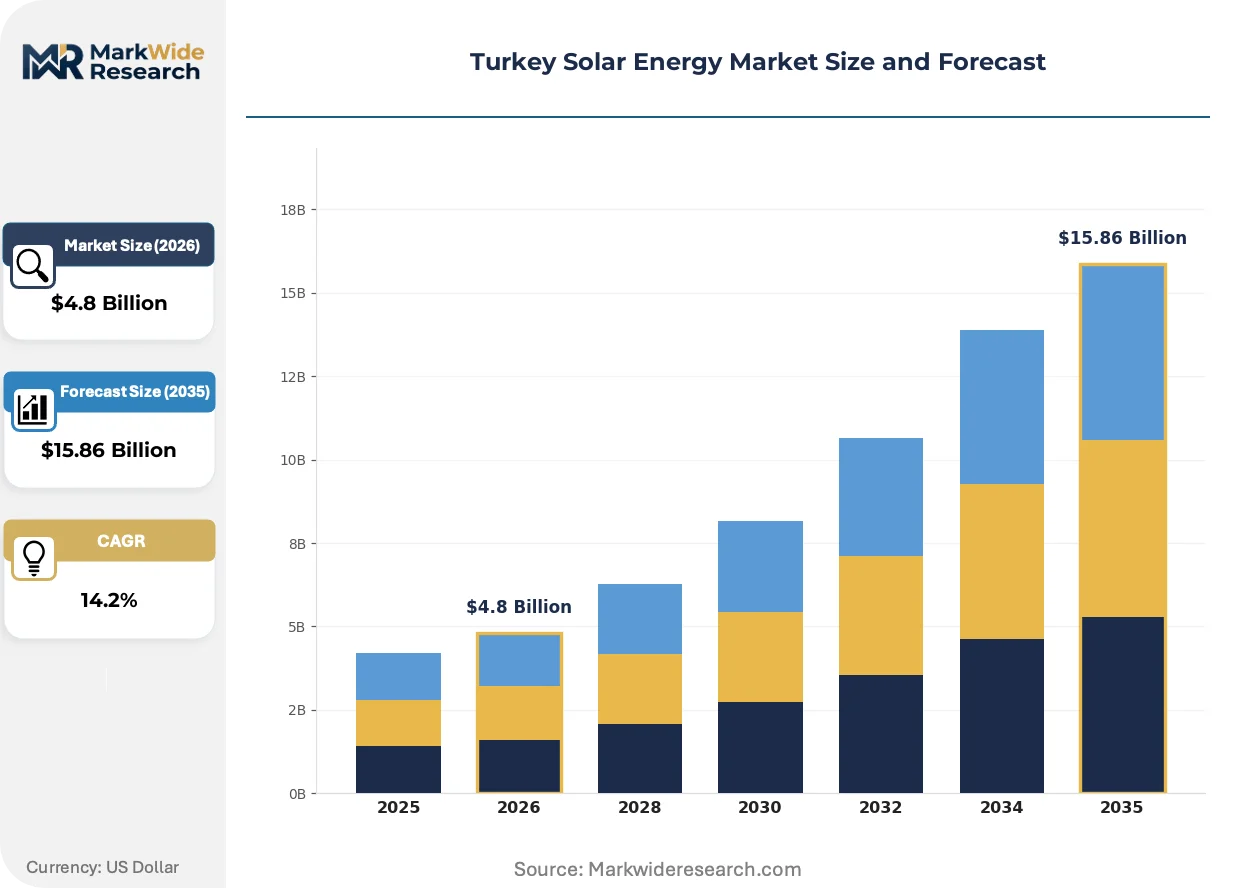
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin Film, BIFACIAL Application: Utility Scale, Residential, Commercial, Off-Grid Installation Type: Ground Mounted, Roof Mounted, Floating, Hybrid End User: Government, Utilities, Private Sector, Entrepreneurs |
| Companies Covered | Borusan EnBW Enerji, HT Solar Energy, Kalyon PV, Ankara Solar A.Ş., CW Enerji, PV Hardware (PVH), Smart Solar, ODTÜ-GÜNAM, Schmid Pekintaş, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Turkey Solar Energy Market Strategic Shifts
Technology convergence between power electronics and digital controls is reconfiguring how Turkish solar assets are monitored, optimized, and traded.
Bifacial photovoltaic modules with dual-sided light capture are digitizing yield forecasting and performance benchmarking across commercial portfolios. Industrial offtakers in Konya and Ankara are specifying bifacial configurations for new ground-mounted installations. Real-time irradiance modeling and predictive maintenance algorithms are compressing operational expenditure assumptions in project finance models.
EMRA's updated licensing framework for unlicensed generation is accelerating distributed deployment below 1 MW threshold. The regulation exempts smaller commercial installations from full generation license requirements, reducing administrative burden. Manufacturing facilities in Bursa and Izmir are restructuring energy procurement teams to exploit this streamlined pathway.
Industrial buyers are consolidating vendor relationships around integrated EPC-plus-O&M service contracts. Single-source accountability is displacing fragmented subcontractor management for multi-site commercial portfolios. Textile clusters in Denizli and Gaziantep are piloting 10-year comprehensive agreements that bundle construction with performance-guaranteed operations.
Turkey Solar Energy Market Segmentation
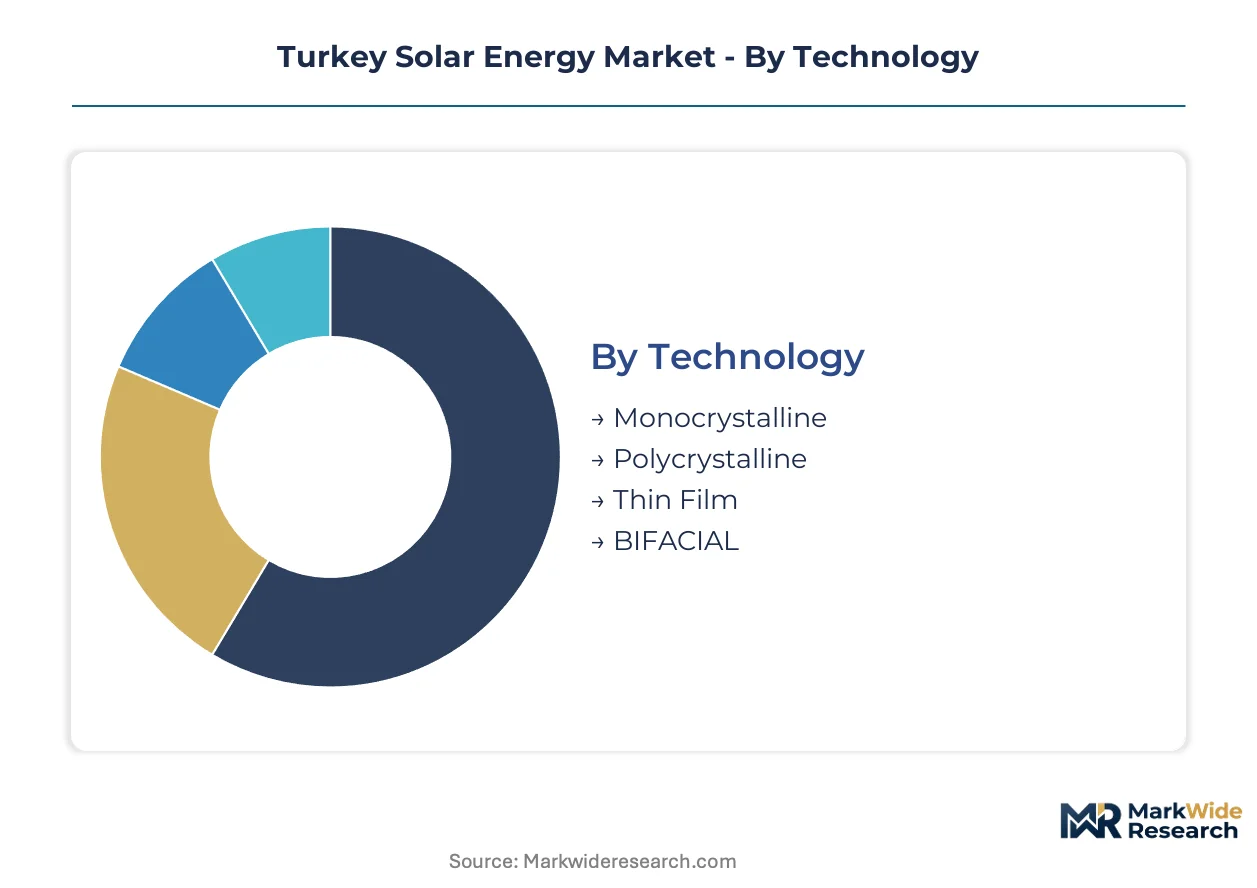
Technology choices in Turkey's solar market are hardening around conversion efficiency and local manufacturing capability. Application patterns diverge sharply between utility-scale pipeline control and distributed commercial deployment. Installation type selection hinges on land availability constraints in Anatolia's agricultural zones.
Technology:
Conversion efficiency and supply chain localization determine technology selection across Turkish project development.
- Monocrystalline:Single-crystal silicon wafers achieve conversion efficiencies exceeding 21% under standard test conditions. Konya and Ankara provinces concentrate demand where high irradiance justifies premium module costs for utility-scale ground-mounted installations.
- BIFACIAL:Dual-sided light capture architectures digitize yield forecasting through rear-side albedo optimization. Industrial offtakers in Konya specify bifacial configurations for commercial projects seeking differentiated energy output profiles.
- Polycrystalline:Multi-crystal silicon construction offers lower capital intensity for budget-constrained distributed generation.
- Thin Film:Cadmium-telluride and amorphous silicon alternatives occupy niche applications with specific temperature coefficient requirements.
Monocrystalline holds installed capacity. BIFACIAL is rotating up the share rankings.
Application:
Project scale dictates financing structures, regulatory pathways, and offtake contracting strategies.
- Utility Scale:Ground-mounted installations above 1 MW capacity access YEKDEM tariff guarantees through 10-year power purchase agreements. Developers in Konya Plain navigate agricultural protection zone restrictions to secure land for high-irradiance deployment.
- Commercial:Industrial self-consumption systems leverage EMRA's revised net metering framework to compress payback periods. Textile and ceramics manufacturers in Bursa and Izmir deploy captive rooftop installations to hedge against volatile state utility tariffs.
- Residential:Roof-mounted systems below 10 kW benefit from streamlined unlicensed generation pathways under updated EMRA regulations.
- Off-Grid:Standalone systems serve rural electrification where TEIAS distribution infrastructure remains sparse in eastern Anatolia.
Utility Scale dominates megawatt-hours generated. Commercial is climbing the fastest among application categories.
Installation Type:
Physical mounting configuration responds to land use regulations, structural load constraints, and water surface access.
- Ground Mounted:Fixed-tilt and tracking structures on open terrain deliver lowest levelized cost of energy for utility-scale pipelines. Konya province attracts developers despite agricultural protection zone friction.
- Roof Mounted:Ballasted and penetrating systems on industrial and commercial buildings exploit existing structural assets. Manufacturing clusters in Denizli and Gaziantep consolidate multi-site portfolios under integrated EPC-plus-O&M contracts.
- Floating:Pontoon-mounted arrays on reservoirs and irrigation ponds remain underdeployed despite cooling efficiency advantages.
- Hybrid:Co-located solar-plus-storage configurations access ancillary service revenue streams under EMRA's emerging frequency regulation market rules.
Ground Mounted anchors capacity additions. Roof Mounted is gaining share fastest as net metering improves.
End User:
Procurement authority and risk tolerance segment the demand base across public and private counterparties.
- Private Sector:Industrial manufacturers in western Anatolia deploy captive generation to offset electricity cost volatility. Textile clusters pilot 10-year comprehensive service agreements bundling construction with performance-guaranteed operations.
- Utilities:TEIAS and distribution companies procure capacity through competitive auctions and bilateral contracts to meet renewable portfolio obligations.
- Government:Public buildings and military installations deploy solar through centralized procurement frameworks with local content requirements.
- Entrepreneurs:Independent power producers and project developers originate commercial PPAs and aggregate distributed portfolios for institutional investors.
Private Sector leads deployment volume. Entrepreneurs are expanding fastest as PPA origination structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkey's solar equipment trade flows reveal a structural deficit in upstream polysilicon and cell manufacturing that domestic ingot-to-module facilities are working to close. Import dependency for wafers and power electronics shapes procurement strategies across Anatolian project clusters.
Marmara Region
Industrial electricity demand from automotive and textile manufacturers in Bursa and Izmir drives commercial rooftop deployment under EMRA's streamlined unlicensed generation pathway. The region's grid interconnection infrastructure supports distributed generation aggregation for virtual power plant participation. Manufacturing facilities in Gebze and Dilovasi consolidate multi-site solar portfolios under integrated EPC-plus-O&M contracts.
Central Anatolia
High irradiance levels exceeding 1,500 kWh/m² annually attract utility-scale developers to Konya Plain despite agricultural protection zone restrictions. YEKDEM tariff guarantees anchor project finance for ground-mounted installations above 1 MW capacity. Kalyon PV operates integrated manufacturing in Ankara province, supplying monocrystalline modules to domestic tenders.
Aegean Region
Denizli textile clusters and ceramic manufacturers deploy captive rooftop systems to hedge against volatile state utility tariffs. Net metering improvements compress payback periods for industrial self-consumption configurations. The region's distribution network capacity accommodates distributed generation expansion without transmission upgrade delays.
Mediterranean Region
Antalya and Mersin provinces present underdeployed agrivoltaics potential combining photovoltaic canopies with greenhouse cultivation. TEIAS grid infrastructure in coastal zones supports utility-scale pipeline development with shorter interconnection queues than eastern regions. Tourism sector energy demand creates commercial PPA origination opportunities for hospitality portfolios.
Southeastern Anatolia
Rural electrification gaps and sparse TEIAS distribution infrastructure sustain off-grid solar deployment for agricultural pumping and remote settlements. Land availability constraints are less severe than in western agricultural zones, though lower irradiance profiles reduce project economics. Development finance institutions support standalone system deployment in provinces with limited grid extension plans.
Turkey Solar Energy Market Competitive Environment
On the supply side, the industry is consolidating around integrated manufacturers with captive polysilicon-to-module capabilities and specialized EPC providers with regional permitting expertise. Three archetypes dominate: vertically integrated domestic producers controlling upstream material flows, utility-scale pipeline developers securing land and grid access, and distributed generation specialists navigating commercial rooftop complexity. Competitive moves center on backward integration into wafer manufacturing and long-term service contract bundling that locks in O&M revenue streams.
Among Turkey-based integrated producers, Kalyon PV and Ankara Solar A.Ş. exemplify the domestic manufacturing archetype with ingot-to-module operations serving government tenders. CW Enerji occupies a position within the distributed commercial specialist tier, leveraging regional permitting knowledge across Anatolian industrial zones. Borusan EnBW Enerji anchors the utility-scale developer category through western Anatolia pipeline control and bilateral industrial offtake relationships.
| Leading Market Players |
|---|
| Borusan EnBW Enerji |
| HT Solar Energy |
| Kalyon PV |
| Ankara Solar A.Ş. |
| CW Enerji |
| PV Hardware (PVH) |
| Smart Solar |
| ODTÜ-GÜNAM |
| Schmid Pekintaş |
| Others |
Value Chain & Pricing Dynamics
Polysilicon import dependency from East Asian suppliers compresses module pricing tiers while exposing Turkish EPCs to customs clearance volatility and shipping cost swings. This single-source concentration simultaneously widens spreads between premium domestic-manufactured monocrystalline panels and economy-grade imports while forcing developers toward captive upstream control.
Pricing Analysis
Industrial OEM buyers anchor project-based long-term offtake pricing across Turkish solar deployment. Three-tier pricing structure across premium certified, standard utility-grade, and economy import tiers separates YEKDEM-eligible configurations with local content compliance from uncertified alternatives. Cost compression in economy tiers is intensifying because of wafer oversupply from Chinese manufacturers and customs duty arbitrage. Textile and ceramics manufacturers in Bursa demonstrate highest price sensitivity, while utility-scale developers securing YEKDEM guarantees accept premium positioning for bankability.
Supply Chain Analysis
Export-control regimes limiting semiconductor-grade polysilicon technology transfers have concentrated crystalline silicon cell manufacturing in China, Vietnam, and Malaysia. Turkish module assemblers draw from Malaysian wafer sources, Chinese cell production, and domestic glass and aluminum framing. Single-source vulnerability in inverter power electronics from East Asian suppliers exposes EPCs to logistics chokepoints at Mersin and Izmir ports. Distribution runs through integrated domestic manufacturers with captive ingot-to-module capability and fragmented import-dependent assemblers serving commercial rooftop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Turkey's solar market sits at a regulatory inflection where EMRA's unlicensed generation threshold expansion and YEKDEM auction redesign are compressing development timelines and rewiring competitive access.
For Market Incumbents: Harden domestic manufacturing moats through backward integration into wafer production before import dependency erodes cost positioning. Lock in multi-year EPC-plus-O&M service contracts with industrial offtakers in Denizli and Gaziantep to capture recurring revenue streams that emerging competitors cannot replicate. Prioritize TEIAS grid interconnection queue positioning in Konya Plain to defend pipeline control against new entrants with superior balance-sheet access. For New Entrants and Emerging Players: Build out agrivoltaics capabilities in Antalya and Mersin provinces where agricultural protection zones block pure ground-mounted competitors and greenhouse cultivation creates differentiated offtake structures. Target commercial PPA origination between 1-5 MW scale where incumbent utility developers lack granular permitting expertise. Lead with integrated storage co-location proposals under EMRA's emerging frequency regulation rules to bypass saturated pure-play solar procurement channels. For Investors and Strategic Acquirers: The market sits at a growth acceleration phase that favors vertically integrated manufacturers with captive polysilicon-to-module capability and distributed generation specialists with regional permitting depth. Long-term viability hinges on exposure to YEKDEM-eligible project pipelines and EMRA-compliant unlicensed generation pathways. Watch for TEIAS transmission infrastructure upgrade announcements as the signal indicating grid interconnection backlog resolution and utility-scale deployment velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Manufacturing | Captive polysilicon supply from Kalyon PV's Ankara facility reduces import exposure for YEKDEM-compliant tenders. |
| Power Purchase Agreement Origination | Direct bilateral contracts with Bursa textile manufacturers bypass wholesale market volatility for developers. |
| Agrivoltaics Pilot Development | Dual-use installations in Antalya greenhouse zones unlock land-constrained deployment where ground-mounted projects face agricultural protection blocks. |
| Energy Storage Co-location | Lithium-ion integration with existing Konya solar farms accesses ancillary service revenue under EMRA frequency regulation market rules. |
| Integrated EPC-plus-O&M Contracting | Single-source accountability for Denizli manufacturing clusters displaces fragmented subcontractor management. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility-scale project developers, EPC contractors, TEIAS grid planning officers, and industrial energy procurement managers at textile and ceramics manufacturers. Secondary validation drew from EMRA licensing databases, YEKDEM auction records, TEIAS interconnection queue disclosures, and customs trade data on module and inverter imports. Bottom-up project pipeline aggregation across Konya, Ankara, and western Anatolia clusters was triangulated against top-down capacity installation estimates from regulatory filings.
Calibration against historical installation trajectories and announced manufacturing capacity additions shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology conversion efficiency tier, application scale threshold, installation type configuration, and end-user procurement authority. CAGRs were derived from capacity-weighted average deployment velocities across high-irradiance provinces. Forecast inputs incorporated YEKDEM tariff schedule revisions, EMRA unlicensed generation threshold adjustments, and TEIAS transmission upgrade timelines.
Stress conditions across polysilicon price volatility, TEIAS interconnection queue duration, and YEKDEM auction participation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory continuity and technology cost curves. Material shifts in EMRA licensing frameworks or TEIAS infrastructure investment pacing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Italy Distributed Solar Power Generation Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
North America Single Axis Solar Tracker Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Netherlands Solar Energy Market