
 Germany Solar Energy Market | 2026-2036
Germany Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Solar Energy Market Foresight
German photovoltaic module assembly capacity is realigning toward heterojunction and TOPCon cell architectures. SMA Solar Technology AG leverages its inverter software stack to dominate grid-tied system integration. RWE AG anchors utility-scale project pipelines across Brandenburg and Saxony-Anhalt. Enerparc AG specializes in commercial rooftop engineering, while BayWa r.e competes through agricultural land lease structures for ground-mounted developments.
Germany Solar Energy encompasses photovoltaic conversion systems, thermal collectors, power electronics, and storage assets engineered to capture electromagnetic radiation across the 300–1100 nm spectrum for electricity generation or thermal extraction. Crystalline silicon modules constitute the dominant technology platform, with conversion efficiencies typically ranging from 20–23% for commercial monocrystalline units. Photovoltaic panels command the largest installed base, though solar batteries capture expanding margin pools as merchant and self-consumption models displace feed-in dependence. Rooftop installations retain volume leadership in urban zones, while ground-mounted arrays scale faster in eastern federal states with lower land costs.
The Bundesnetzagentur administers auction mechanisms under the EEG framework, while KBA certifies building-integrated mounting systems for structural compliance. The EU Green Deal's solar energy targets and Germany's national solar package tighten local content and sustainability criteria for project eligibility. Stakeholders must monitor EEG amendment trajectories and carbon border adjustment mechanics to calibrate capital allocation between merchant, PPA, and subsidy-dependent development pathways.
Market Dynamics
The EEG feed-in tariff reform is compressing project economics and forcing developers toward merchant power structures and corporate PPAs, fundamentally restructuring how solar assets monetize across German federal states.
Growth Catalysts
- EU Green Deal solar targets:Binding national quotas under the EU solar energy framework mandate capacity additions, channeling institutional capital into photovoltaic deployment pipelines.
- Industrial self-consumption:Baden-Württemberg's automotive and machinery clusters are deploying behind-the-meter systems to hedge against volatile wholesale electricity prices.
- Heterojunction cell efficiency gains:Conversion improvements above 24% are reducing levelized cost of energy for commercial rooftop installations in Bavaria.
Market Restraints
- Polysilicon supply concentration:German module assemblers remain dependent on Xinjiang-origin feedstock, exposing project timelines to carbon border adjustment enforcement.
- Grid connection queuing:Bundesnetzagentur permitting backlogs in northern federal states delay utility-scale energization by 18-24 months.
- Land use competition:Agricultural lease rates in Brandenburg are rising as solar developers compete with food production and biodiversity mandates.
Strategic Opportunities
- Agrivoltaic deployment:Dual-use installations on Saxony-Anhalt cropland unlock subsidy stacking under rural development funds and EEG premiums.
- Building-integrated photovoltaics:KBA-certified mounting systems for commercial facades in North Rhine-Westphalia address urban land scarcity.
- Electrolyzer co-location:Green hydrogen off-take agreements in Lower Saxony's chemical corridor anchor 24/7 renewable supply contracts.
Industry Challenges
- Electrical engineering talent scarcity:Grid integration specialists for inverter commissioning and medium-voltage substation design command premium compensation in industrial zones.
- EEG amendment uncertainty:Quarterly legislative revisions to auction price caps and degression rates complicate multi-year project financing structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Solar Energy Market |
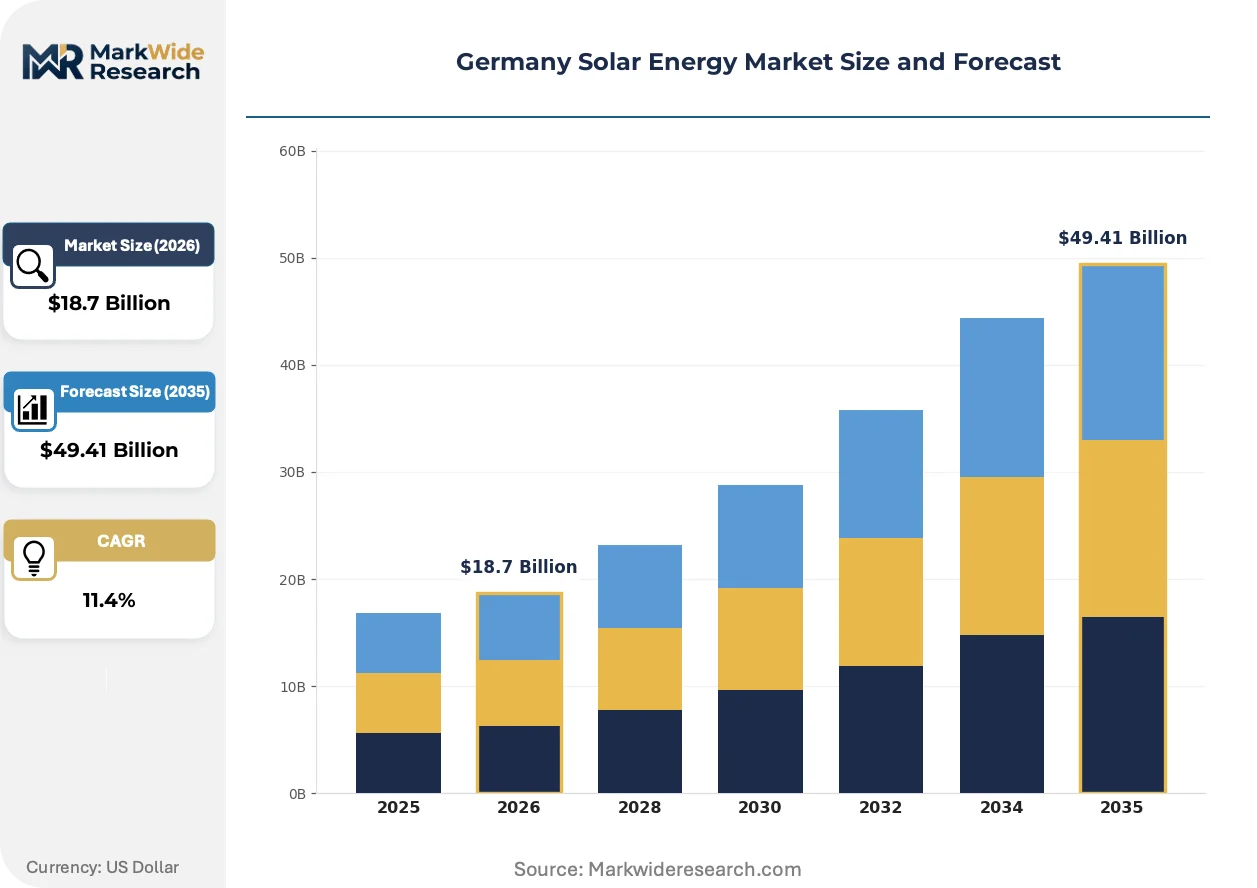
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
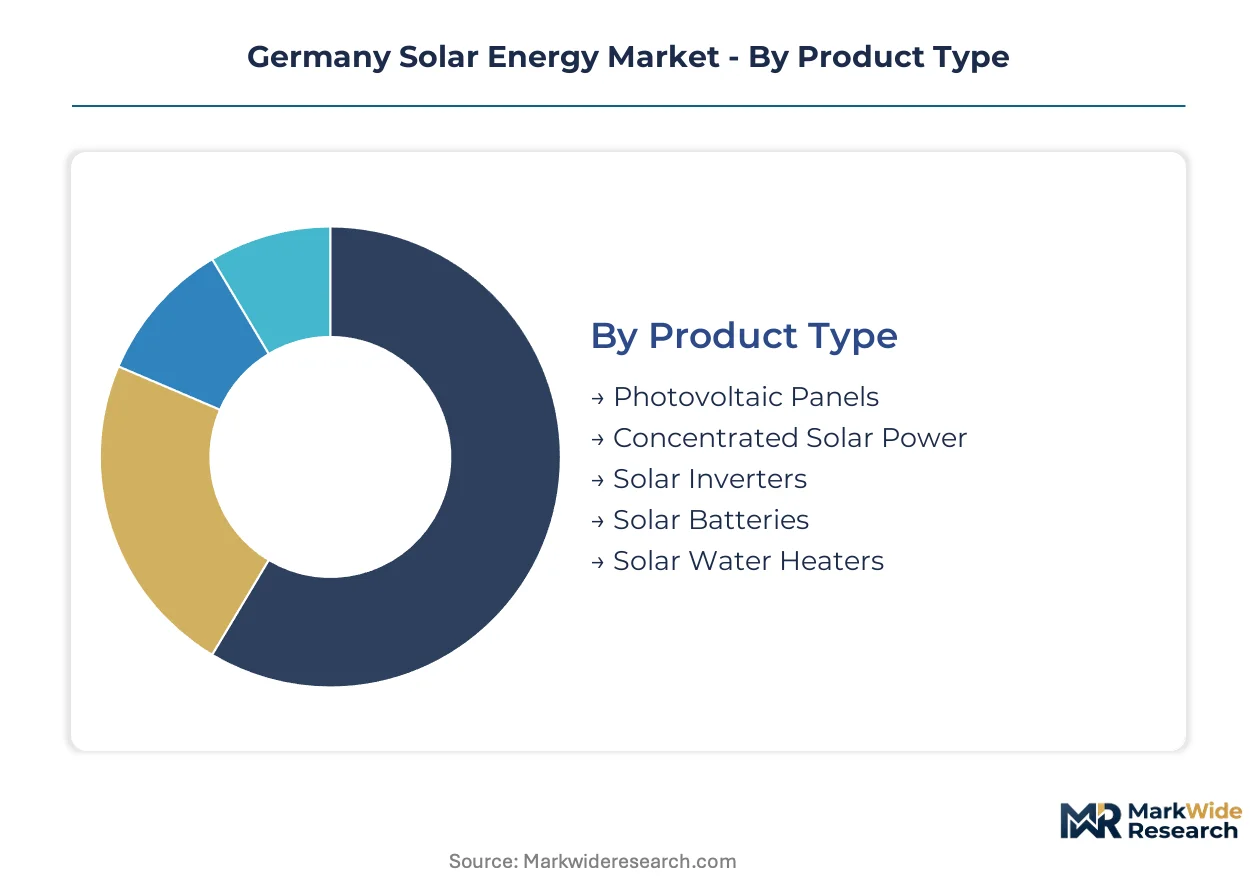
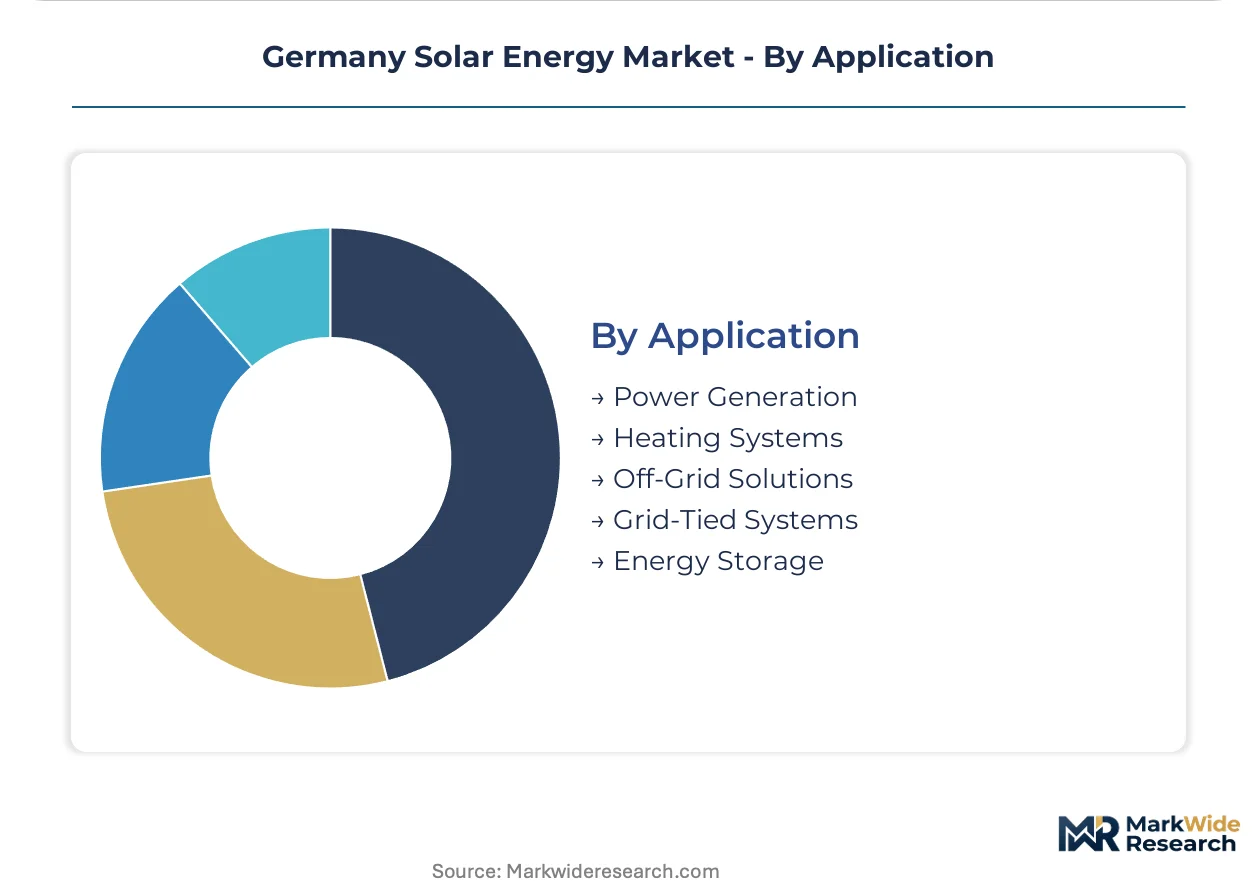
| Segmentation | Product Type: Photovoltaic Panels, Concentrated Solar Power, Solar Inverters, Solar Batteries, Solar Water Heaters Installation Type: Rooftop, Ground-Mounted, Floating, Building-Integrated, Carport End User: Residential Users, Commercial Enterprises, Public Sector Facilities, Agricultural Operators, Research Institutions Application: Power Generation, Heating Systems, Off-Grid Solutions, Grid-Tied Systems, Energy Storage |
| Companies Covered | ABO Energy, Enerparc AG, RWE AG, SMA Solar Technology AG, Wpd AG, EnBW AG, Belectric, GP Joule, BayWa r.e, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Solar Energy Market Shifts & Advancements
Module technology, auction mechanics, and offtake contracting are converging to reshape German solar deployment patterns, with efficiency gains and policy volatility driving simultaneous acceleration and consolidation.
TOPCon cell architectures are overtaking PERC dominance in utility-scale procurement. These tunnel oxide passivated contact designs reduce temperature coefficient losses, enabling higher energy yield in eastern Germany's continental climate. EPC contractors in Saxony-Anhalt are specifying TOPCon exclusively for ground-mounted arrays exceeding 50 MWp.
Amendments to the EEG framework are compressing feed-in tariff windows and elevating merchant exposure. The Bundesnetzagentur's switch to technology-neutral auctions forces solar bidders to compete directly with onshore wind, squeezing developer margins. Project sponsors in Brandenburg are responding with longer-term corporate PPA structures to bridge revenue certainty gaps.
Direct power purchase agreements are displacing traditional utility intermediation for commercial offtakers. Industrial clusters in Bavaria's manufacturing belt are contracting directly with project developers, bypassing incumbent supply tariffs. This bilateral contracting trend concentrates in energy-intensive sectors with 24-hour load profiles and sustainability disclosure obligations under CSRD.
Germany Solar Energy Market Segmentation
Technology specifications and installation geometries determine capital efficiency and regulatory eligibility across German solar deployment. Each segmentation axis reveals distinct margin structures, permitting pathways, and customer procurement behaviors that shape competitive positioning.
Product Type:
Cell architecture and power electronics specifications differentiate performance warranties, degradation curves, and grid integration complexity for German project developers.
- Photovoltaic Panels:Crystalline silicon modules with heterojunction and TOPCon architectures dominate utility-scale procurement in Brandenburg and Saxony-Anhalt. Bavarian commercial rooftops specify these units for conversion efficiencies exceeding 23% that compress levelized cost of energy.
- Solar Batteries:Lithium-ion storage assets with power conversion systems enable 24/7 renewable supply contracts for Lower Saxony chemical corridor offtakers. Merchant power models and EEG tariff compression drive behind-the-meter deployment.
- Concentrated Solar Power:Parabolic trough and tower configurations with molten salt thermal storage occupy niche industrial heat applications where direct steam generation serves process industries.
- Solar Inverters:String and central inverter topologies with grid-forming capabilities address Bundesnetzagentur stability requirements for utility-scale energization.
- Solar Water Heaters:Flat-plate and evacuated tube collectors for residential thermal extraction compete with heat pump economics in Baden-Württemberg's building stock renovations.
Photovoltaic panels lead on scale; solar batteries lead on momentum.
Installation Type:
Mounting geometry and land use classification determine permitting jurisdiction, agricultural lease structures, and KBA structural compliance obligations.
- Rooftop:Commercial installations across Bavaria and North Rhine-Westphalia exploit existing building footprints to circumvent land use competition. KBA-certified mounting systems address structural load requirements for industrial superstructures.
- Ground-Mounted:Eastern federal states with lower agricultural lease rates host utility-scale arrays exceeding 50 MWp. EPC contractors specify TOPCon exclusively for these configurations.
- Building-Integrated:Facade-integrated systems in North Rhine-Westphalia urban zones substitute conventional cladding materials while generating behind-the-meter supply.
- Floating:Reservoir-mounted arrays on quarry lakes and water treatment basins circumvent land scarcity constraints in densely populated regions.
- Carport:Dual-purpose parking infrastructure with overhead canopy generation serves commercial enterprises with fleet electrification requirements.
Ground-mounted installations concentrate volume; building-integrated systems expand most quickly.
End User:
Load profile characteristics and procurement sophistication determine contracting structures, from standardized residential feed-in tariffs to bespoke corporate power purchase agreements.
- Commercial Enterprises:Baden-Württemberg automotive and machinery clusters deploy behind-the-meter systems to hedge volatile wholesale electricity prices. Direct bilateral contracting with developers bypasses incumbent utility intermediation.
- Residential Users:Self-consumption optimization with battery coupling displaces EEG feed-in dependence for single-family homeowners in suburban zones.
- Agricultural Operators:Saxony-Anhalt cropland hosts agrivoltaic dual-use installations unlocking subsidy stacking under rural development funds.
- Public Sector Facilities:Municipal building portfolios procure through centralized tendering frameworks with sustainability disclosure obligations.
- Research Institutions:Testbed installations for next-generation cell architectures and grid integration protocols receive federal innovation funding.
Commercial enterprises lead on procurement sophistication; agricultural operators lead on subsidy access.
Application:
System architecture and grid interconnection topology determine revenue certainty, from regulated feed-in tariffs to merchant exposure and corporate offtake structures.
- Power Generation:Grid-tied and off-grid photovoltaic conversion systems dominate installed capacity, with EEG auction mechanics and merchant models restructuring monetization pathways.
- Energy Storage:Battery assets and green hydrogen electrolyzer co-location enable 24/7 renewable supply contracts with industrial offtakers.
- Grid-Tied Systems:Utility-scale and commercial rooftop installations feed into distribution networks under Bundesnetzagentur interconnection protocols.
- Heating Systems:Solar thermal collectors and photovoltaic-to-heat conversion serve building sector decarbonization mandates.
- Off-Grid Solutions:Standalone systems with battery backup serve remote agricultural operations and telecommunications infrastructure.
Power generation leads on installed base; energy storage leads on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in utility-scale auction volumes while Spain's merchant solar exposure exceeds both markets. Eastern federal states attract capital through lower land costs and streamlined permitting.
Bavaria
Industrial self-consumption drives commercial rooftop deployment across Munich-Augsburg manufacturing corridors. The EEG feed-in tariff reform pushes Baden-Württemberg automotive suppliers toward behind-the-meter systems. SMA Solar Technology AG anchors inverter supply chains for Bavarian EPC contractors.
North Rhine-Westphalia
Ruhr Valley chemical processors contract direct bilateral PPAs to hedge volatile wholesale electricity prices. KBA-certified building-integrated mounting systems address structural compliance for commercial facades. Dortmund-Essen industrial zones concentrate merchant power offtake agreements.
Brandenburg
Eastern Germany's lowest agricultural lease rates attract utility-scale ground-mounted arrays exceeding 50 MWp. Bundesnetzagentur auction mechanics compress developer margins against onshore wind competition. RWE AG pipelines dominate project origination across Spree-Neisse industrial basins.
Lower Saxony
Green hydrogen electrolyzer co-location anchors 24/7 renewable supply contracts for chemical corridor offtakers. Agrivoltaic dual-use installations unlock subsidy stacking under rural development funds. Wolfsburg automotive clusters deploy battery-coupled systems for load-shifting optimization.
Saxony-Anhalt
TOPCon-exclusive procurement for ground-mounted arrays exceeds 50 MWp capacity thresholds. Grid connection queuing delays energization by 18-24 months despite lower land competition. Magdeburg-Halle logistics hubs host testbed installations for next-generation cell architectures.
Germany Solar Energy Market Competitive Landscape
German producers anchor utility-scale development; inverter specialists hold technology differentiation. The vendor base concentrates around five integrated developers controlling auction pipelines. Strategic archetypes include vertically integrated utilities, commercial rooftop engineers, and agricultural lease aggregators. Capacity expansion and corporate PPA origination dominate competitive moves as feed-in tariff compression accelerates.
Among Germany-based developers, RWE AG and EnBW AG exemplify utility-scale auction dominance through integrated project pipelines. Enerparc AG occupies a position within commercial rooftop engineering specialization. SMA Solar Technology AG represents power electronics differentiation for grid-tied system integration. These three entities anchor distinct competitive vectors across the EEG reform transition.
| Leading Market Players |
|---|
| ABO Energy |
| Enerparc AG |
| RWE AG |
| SMA Solar Technology AG |
| Wpd AG |
| EnBW AG |
| Belectric |
| GP Joule |
| BayWa r.e |
| Others |
Supply & Pricing Matrix
Polysilicon feedstock costs cascade through module assembly margins into three-tier pricing structures across premium, standard, and economy levels for German project developers. EEG auction compression forces EPC contractors to absorb upstream volatility while maintaining bid competitiveness for Bundesnetzagentur tenders.
Pricing Analysis
Retailer markup on solar inverters compresses as SMA Solar Technology AG and competitors bypass distribution layers through direct-to-EPC contracting. Price differentiation rests on grid-forming capability certification and software stack integration depth. Pricing pressure stems from EEG tariff degression rates that squeeze developer margins. Commercial offtakers in Baden-Württemberg exhibit lowest price sensitivity due to sustainability disclosure obligations, while residential segments remain most cost-conscious.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for crystalline silicon modules entering German ports. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module assembly. Raw material dependencies include Xinjiang-origin polysilicon, silver paste metallization, and aluminum framing. Supply chain risk centers on carbon border adjustment enforcement against Chinese feedstock. Distribution runs through specialized solar wholesalers serving Bavarian and North Rhine-Westphalia EPC networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German solar energy functions as a stable compounder anchored by binding EU Green Deal capacity quotas that institutionalize deployment pipelines regardless of wholesale price volatility.
For Market Incumbents: Hedge against EEG amendment uncertainty by elongating corporate PPA tenors beyond traditional utility contracting windows. Prioritize backward integration into inverter software stacks to defend margin position against hardware commoditization. Consolidate agricultural lease aggregators in Brandenburg before land competition intensifies. For New Entrants and Emerging Players: Launch via agrivoltaic dual-use installations in Saxony-Anhalt cropland to exploit subsidy stacking under rural development funds. Target building-integrated photovoltaics in North Rhine-Westphalia urban zones where KBA certification creates incumbent friction. Pursue direct bilateral contracting with automotive clusters bypassing utility intermediation. For Investors and Strategic Acquirers: Consolidation pressure builds where project pipelines exceed development velocity in eastern federal states. Long-term viability favors vertically integrated utilities with captive EPC capabilities over pure-play developers. Acquisition target archetype: commercial rooftop engineering specialists with KBA-certified mounting system portfolios. Watch Bundesnetzagentur auction clearing prices as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Corporate PPA Origination | Long-term offtake contracts with Baden-Württemberg automotive clusters bypass EEG tariff dependence. |
| Backward Integration into Storage | Battery-coupled system capabilities capture merchant power margin pools as feed-in tariffs compress. |
| Agrivoltaic Deployment | Dual-use installations on Saxony-Anhalt cropland unlock stacked subsidies under EU rural development frameworks. |
| Building-Integrated Certification | KBA-approved mounting systems address structural compliance for North Rhine-Westphalia commercial facades. |
| Grid-Forming Inverter Development | Software-enabled stability functions meet Bundesnetzagentur interconnection requirements for utility-scale arrays. |
Research Methodology
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators grounded qualitative assessments in operational realities. Secondary validation drew from Bundesnetzagentur auction databases, EEG amendment legislative texts, and EU Green Deal implementation guidelines. Bottom-up project pipeline enumeration triangulated against top-down capacity targets across federal state boundaries.
Installed capacity and revenue trajectories emerged from technology-specific deployment curves calibrated to auction mechanics and merchant power price assumptions. Segmentation dimensions span cell architecture, installation geometry, end-user procurement sophistication, and regulatory framework eligibility. CAGRs derived from year-over-year capacity additions reconciled with EPC contractor order book visibility and polysilicon supply contract tenors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under carbon border adjustment enforcement severity and grid connection queuing duration. Outputs reflect documented assumptions regarding EEG amendment trajectories and EU solar target ratcheting. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
India Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Laminator Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Off-Grid Solar Energy Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Global Crystalline Solar Cells Market