
 Perovskite Solar Cell Market | 2026-2036
Perovskite Solar Cell Market Size, Share, and Industry Trends Forecast 2026-2036
Perovskite Solar Cell Market Intelligence
The IEC 61215 stability testing protocol is unwinding the gap between lab-scale efficiency and commercial bankability for new photovoltaic technologies. This critical standard defines performance, safety, and long-term degradation requirements for terrestrial PV modules. Oxford Photovoltaics leads in developing tandem cells that pair perovskite with silicon for ultra-high-efficiency applications. Saule Technologies specializes in manufacturing flexible, printed perovskite sheets for building-integrated and low-power IoT device applications.
A perovskite solar cell is a photovoltaic device featuring a compound with the ABX3 crystal structure as its light-harvesting active layer. These cells are designed to convert sunlight into electricity, offering a path to higher efficiencies and lower manufacturing costs compared to conventional silicon PV. Tandem cell architectures, which combine perovskite with silicon, represent the highest performance segment. Building Integrated Photovoltaics is the fastest-growing application, leveraging the material's versatility in form and transparency.
Regulatory compliance, particularly with Europe's RoHS directive concerning the use of lead, fundamentally shapes material selection and encapsulation strategies. In parallel, China's national GB standards for photovoltaic products and international ISO quality benchmarks govern module performance, safety, and reliability. Long-term operational stability and the successful commercialization of lead-free alternatives remain the central challenges that will determine widespread market adoption.
Market Dynamics
The central dynamic shaping the market is the intense push to bridge the gap between record lab-scale efficiencies and commercially viable, long-term operational stability. This effort is governed by stringent international standards like IEC 61215, which dictate bankability for terrestrial solar modules.
Growth Catalysts
- Tandem Cell Architectures:The development of perovskite-on-silicon tandem cells enables conversion efficiencies that surpass the theoretical limits of single-junction silicon, attracting investment for high-performance applications where power density is critical.
- National Decarbonization Policies:China's dual carbon goals provide significant state-level support for manufacturing scale-up and domestic deployment, creating a concentrated hub for both production and demand.
- Building Integrated Photovoltaics (BIPV):Demand from the BIPV sector leverages the material's unique properties, including semi-transparency, light weight, and flexibility, for applications in building facades, windows, and roofing materials.
Market Restraints
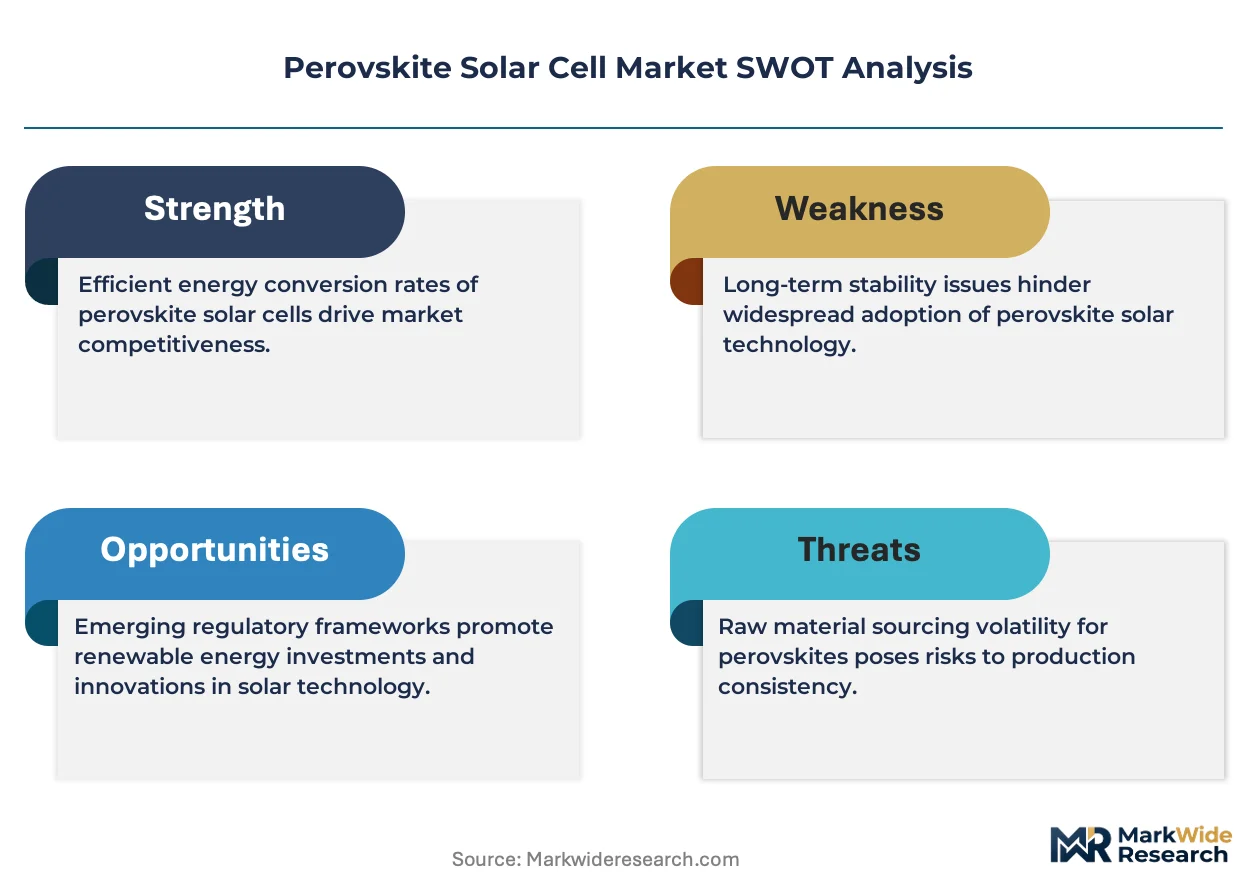
- Material Degradation:Perovskite compounds exhibit inherent instability when exposed to moisture, oxygen, and heat, leading to rapid degradation that shortens operational lifetime and complicates warranty and financing for large-scale projects.
- Regulatory Material Restrictions:The European Union's RoHS directive restricts the use of hazardous substances, including lead, which is a core component of the highest-efficiency perovskite materials, creating a significant barrier to market entry.
- Manufacturing Scalability:Reproducing the high efficiencies achieved in small-area lab cells across large-area commercial modules remains a significant technical hurdle, limiting yield and increasing production costs for manufacturers.
Strategic Opportunities
- Lead-Free Material Development:Investing in the research and commercialization of stable, efficient, lead-free perovskite alternatives creates a direct path to bypass RoHS compliance issues and unlock the European market.
- Low-Power Electronics Integration:Flexible and printed perovskite solar cells can power a new generation of low-energy Internet of Things (IoT) sensors, wearables, and indoor electronic devices, opening non-traditional energy markets.
- Targeting Space-Constrained Markets:High-efficiency tandem cells offer a compelling value proposition in dense urban environments and countries like Japan, where limited rooftop and land area places a premium on maximum power generation per square meter.
Industry Challenges
- Bankability and Certification:Achieving certification under the IEC 61215 standard for terrestrial modules is a time-consuming and capital-intensive process that requires demonstrating long-term stability, which remains a primary operational hurdle for new entrants.
- Encapsulation Technology:Developing cost-effective, durable encapsulation materials and processes that can completely prevent moisture and oxygen ingress over a multi-decade lifespan is critical for ensuring module reliability in diverse climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Perovskite Solar Cell Market |
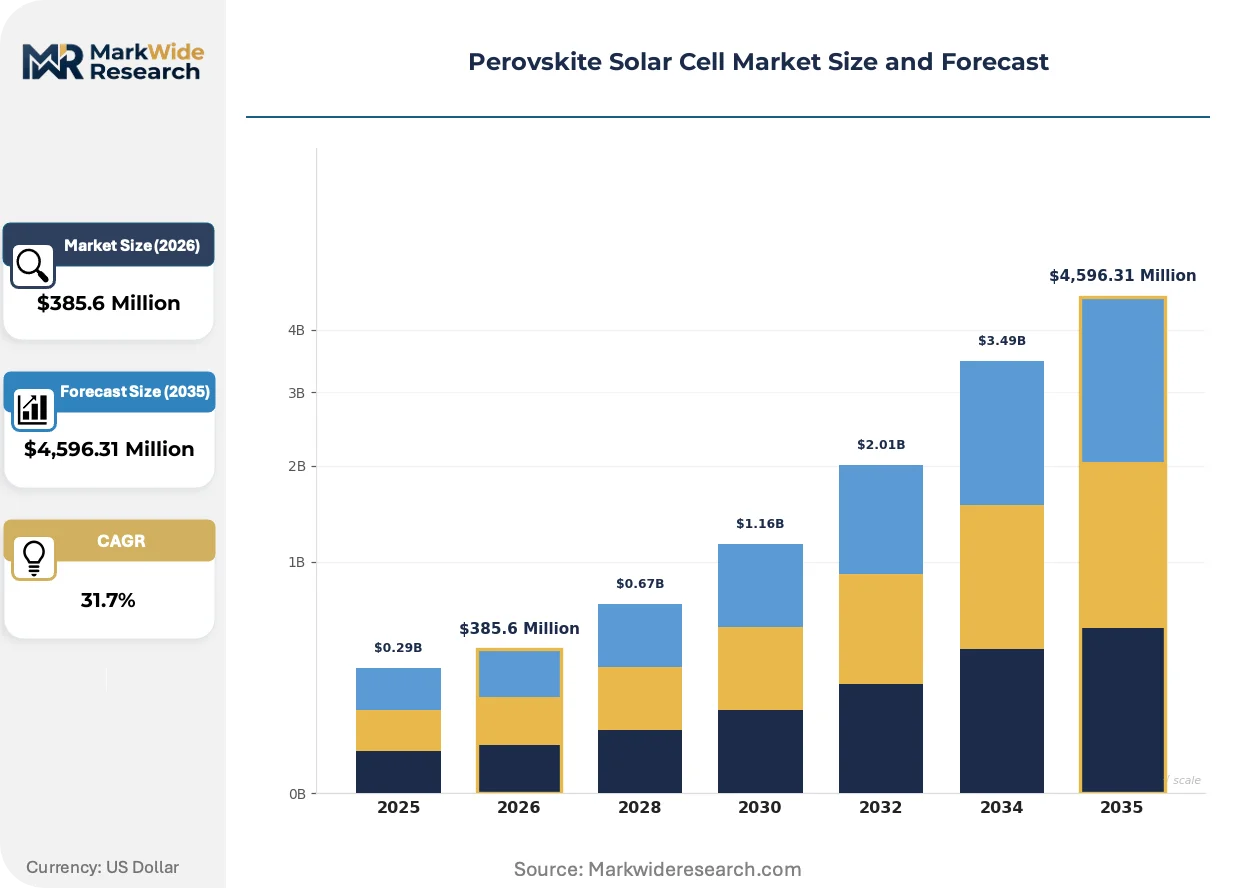
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $4,596.31 Million |
| CAGR (2026 – 2036) | 31.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cell Architecture: Planar, Mesoscopic, Tandem, Hybrid Application: Building Integrated Photovoltaics, Power Generation, Portable Electronics, Wearable Devices End User: Residential Consumers, Commercial Enterprises, Research Institutes, Government Agencies Technology Type: Thin Film, Flexible, Coated Film, Spray Deposited |
| Companies Covered | Hunt Perovskite Technologies, Oxford Photovoltaics, Saule Technologies, Greatcell Energy, EneCoat Technologies, GCL-SI, Microquanta Semiconductor, Panasonic Corporation, UtmoLight Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Perovskite Solar Cell Market Strategic Shifts & Innovations
A clear trend toward industrial standardization is defining the market's evolution from academic research to commercial production. This shift prioritizes module-level reliability and manufacturability over cell-level efficiency records, aligning technology development with the bankability requirements of project financiers.
Tandem cell architecture, which layers a perovskite cell on top of a traditional silicon cell, captures a broader spectrum of sunlight. This technology is being adopted by utility-scale solar developers seeking to maximize energy output from a fixed land area. The higher power density of tandem modules is supplanting the exclusive reliance on single-junction silicon for premium installations.
Europe's Restriction of Hazardous Substances (RoHS) directive is a powerful force shaping material science. The regulation's strict limits on lead content are compelling researchers and manufacturers to accelerate the development of lead-free perovskite compositions or advanced encapsulation to ensure compliance. The building-integrated and consumer electronics segments are most affected, driving innovation in alternative material formulations.
A notable shift in evaluation criteria is occurring among utility and commercial-scale buyers. The focus is moving from peak laboratory efficiency metrics to certified, third-party validated data on long-term energy yield and degradation rates under real-world conditions. This change disrupts the vendor landscape by favoring manufacturers with proven IEC 61215 test results over those with only R&D credentials. This is most visible in procurement for large-scale solar farms.
Perovskite Solar Cell Market Segmentation
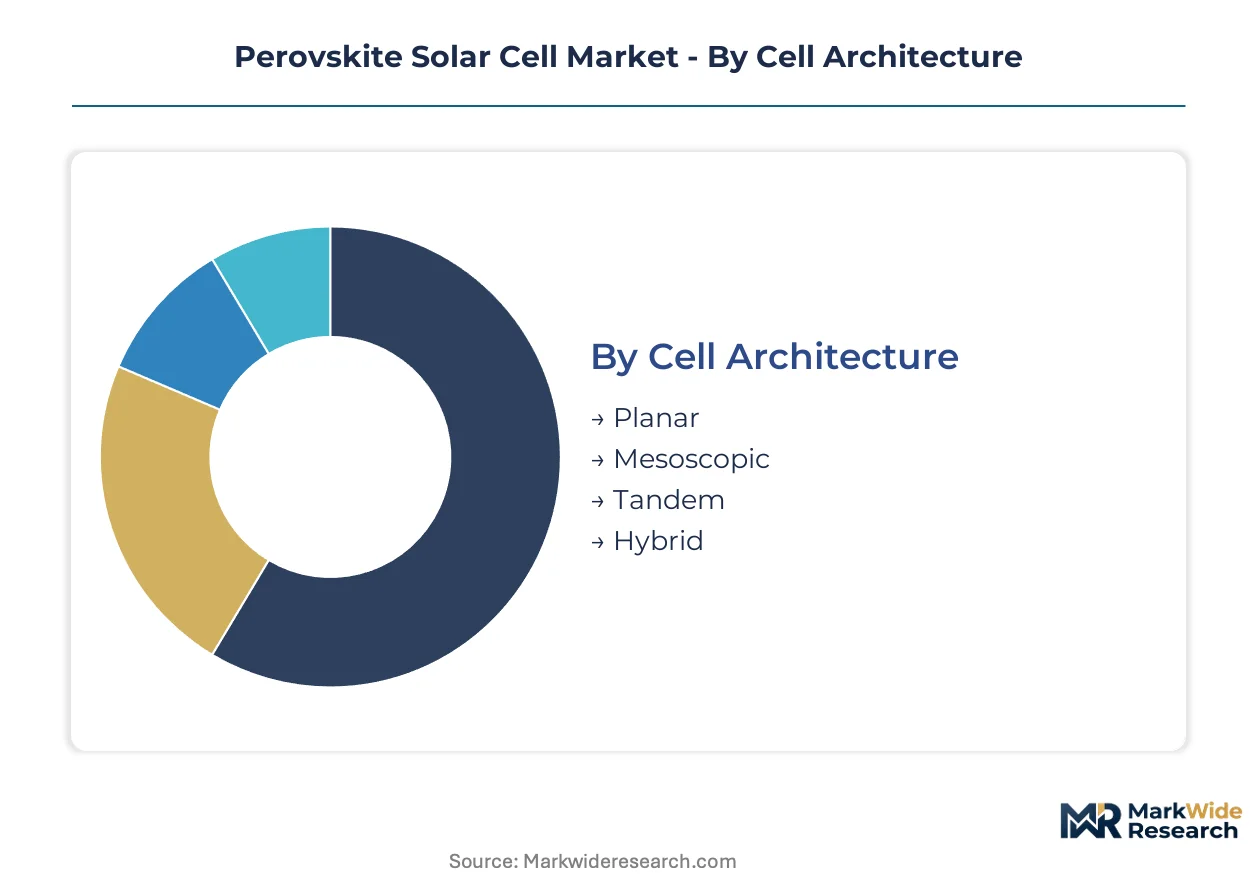
The Perovskite Solar Cell Market is analyzed across distinct segments to understand demand drivers and technological preferences. This segmentation highlights the diverse applications and material configurations shaping market growth. Understanding these categories reveals specific opportunities for commercialization and strategic investment across the value chain.
Cell Architecture:
Margin pools within cell architecture gravitate towards solutions offering superior performance and integration capabilities.
- Tandem:These architectures layer a perovskite cell onto a conventional silicon cell, capturing a broader solar spectrum. Demand concentrates in utility-scale power generation projects in China, driven by national decarbonization policies requiring high power density from limited land area.
- Planar:Planar cells feature a simple, flat layer structure for charge transport, facilitating easier manufacturing processes. These cells find demand in early-stage research and specialized transparent BIPV applications, where aesthetic integration is paramount.
- Mesoscopic:Mesoscopic cells incorporate a porous metal oxide scaffold to enhance electron collection and device stability.
- Hybrid:Hybrid structures combine features from both planar and mesoscopic designs to optimize efficiency and stability trade-offs.
The dominant share belongs to Tandem cells, while Planar cells are closing the gap fastest.
Application:
The maturity of various applications dictates current commercial viability and future growth trajectories for perovskite solar cells.
- Building Integrated Photovoltaics:BIPV integrates perovskite solar cells directly into building materials like windows, facades, and roofing, leveraging their transparency and flexibility. Demand is strong in European urban development projects, driven by EU Green Deal mandates for energy-efficient buildings.
- Power Generation:This segment encompasses large-scale utility and commercial solar farms, where high-efficiency tandem cells maximize electricity output per square meter. Large-scale power generation projects in Japan prioritize high power density due to land constraints.
- Portable Electronics:Perovskite cells offer lightweight, flexible power solutions for devices such as e-readers and small sensors.
- Wearable Devices:These cells provide discrete and efficient power sources for smartwatches and other body-worn technologies.
Building Integrated Photovoltaics is expanding most quickly, demonstrating significant market traction.
End User:
Customer type significantly influences product specifications and purchasing criteria within the perovskite solar cell market.
- Commercial Enterprises:Businesses deploy perovskite solar solutions for rooftop installations, BIPV projects, and powering remote industrial sensors. Procurement is shifting towards suppliers demonstrating IEC 61215 certification for long-term reliability and bankability.
- Residential Consumers:Homeowners adopt perovskite solar for home energy generation, particularly in BIPV applications such as transparent windows and aesthetic facades. Demand in Germany is influenced by incentives for sustainable home improvements.
- Research Institutes:Academic and private research institutions drive innovation in material science and cell design.
- Government Agencies:Public entities invest in pilot projects and infrastructure, often focusing on energy security and sustainable development goals.
Commercial Enterprises currently hold the largest share, with Residential Consumers showing rapid gains.
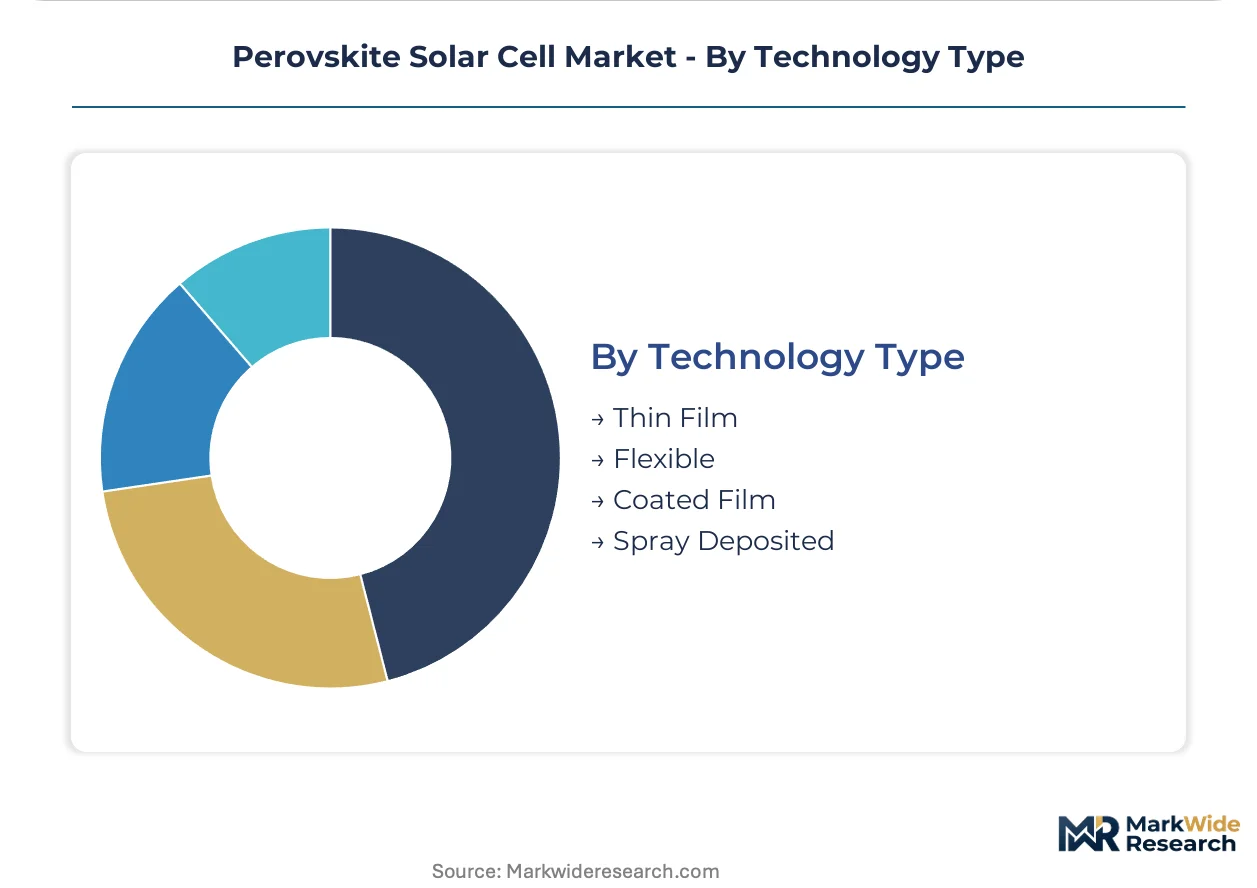
Technology Type:
Supply concentration within technology types is shaped by manufacturing scalability and material processing requirements.
- Thin Film:This technology involves depositing very thin layers of perovskite material onto a substrate, enabling flexible and transparent solar cells. Production is concentrating in facilities capable of roll-to-roll processing for cost-effective, large-area applications.
- Flexible:Flexible perovskite cells are manufactured on pliable substrates, allowing for integration into curved surfaces and wearable electronics. Development is accelerating in China, supported by extensive government-backed manufacturing infrastructure for advanced materials.
- Coated Film:Coated film methods involve applying perovskite solutions onto various substrates using techniques like blade coating.
- Spray Deposited:Spray deposition offers a scalable and cost-effective approach for applying perovskite layers over large areas.
Thin Film technologies command the largest segment, while Flexible solutions exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National decarbonization policies and stringent energy efficiency mandates significantly influence the geographic distribution of perovskite solar cell demand. Government incentives for renewable energy deployment and building integration drive market expansion. These regulatory frameworks accelerate both research investment and commercial adoption.
China
China's dual carbon goals drive high-efficiency perovskite solar cell adoption in utility-scale power generation. Extensive government-backed manufacturing infrastructure supports domestic deployment and technological advancement. The Yangtze River Delta region concentrates significant production capacity for advanced photovoltaic materials.
Germany
Germany exhibits strong demand for Building Integrated Photovoltaics, driven by EU Green Deal mandates for energy-efficient structures. The RoHS directive shapes material selection and encapsulation strategies for market entry within the European Union. Urban development projects in Bavaria actively integrate transparent perovskite solar cells into new buildings.
Japan
Japan's limited land area places a premium on maximum power generation per square meter, fueling demand for high-efficiency tandem cells. Policies from METI support the deployment of advanced energy technologies to enhance energy security. The Kanto region sees early adoption of high-performance perovskite modules in commercial installations.
United States
United States commercial enterprises deploy perovskite solar solutions for rooftop installations and large-scale solar farms, seeking long-term reliability. The Inflation Reduction Act (IRA) provides significant incentives for domestic clean energy manufacturing and deployment. California's solar development sector explores high-efficiency perovskite modules to maximize energy output.
South Korea
South Korea's robust electronics manufacturing sector drives demand for lightweight, flexible perovskite cells in portable electronics and IoT devices. Government initiatives support advanced materials research and the commercialization of next-generation photovoltaic technologies. The Seoul Capital Area actively prototypes perovskite applications in consumer electronics.
Perovskite Solar Cell Market Key Industry Players
Player mix skews toward specialized technology developers and material science innovators, creating a fragmented yet highly competitive landscape. The market functions with a tiered structure, encompassing early-stage R&D firms, established solar manufacturers, and new entrants focused on niche applications. Strategic archetypes include high-efficiency tandem cell specialists and flexible film producers. Key competitive moves involve strategic partnerships for commercialization and significant investment in R&D to address stability challenges.
Among the specialized technology developers, Oxford Photovoltaics exemplifies leadership in high-efficiency tandem cell architectures, targeting ultra-high-efficiency applications. Saule Technologies, a Poland-based firm, represents the archetype of a flexible, printed perovskite sheet manufacturer, specializing in building-integrated and low-power IoT device applications. Meanwhile, Panasonic Corporation, a diversified Japanese electronics conglomerate, occupies a position focused on integrating advanced materials into broader energy and consumer electronics portfolios, leveraging its established manufacturing capabilities for potential scale-up. This mix of pure-play innovators and established industry players defines the current competitive dynamics.
| Leading Market Players |
|---|
| Hunt Perovskite Technologies |
| Oxford Photovoltaics |
| Saule Technologies |
| Greatcell Energy |
| EneCoat Technologies |
| GCL-SI |
| Microquanta Semiconductor |
| Panasonic Corporation |
| UtmoLight Co., Ltd. |
Cost & Logistics Intelligence
Extended lead times for specialized encapsulation materials directly influence the supply chain's responsiveness, impacting pricing power for high-stability perovskite modules. This dynamic fosters a market where material innovation and robust manufacturing infrastructure determine competitive advantage.
Pricing Analysis
IEC 61215 certification creates the primary spread in perovskite solar cell pricing, commanding premiums for proven long-term stability. The market operates with a hybrid pricing model, combining project-based contracts for large-scale BIPV and utility applications with per-unit transactional pricing for portable electronics. Price differentiation also stems from lead-free compliance, particularly for European market entry. Pricing softness stems from manufacturing scalability challenges across large-area modules. Residential consumers exhibit the highest price sensitivity, while commercial enterprises prioritize certified long-term energy yield.
Supply Chain Analysis
China anchors the supply chain for advanced perovskite materials and manufacturing capacity, supporting extensive domestic deployment. Raw material dependencies center on lead precursors and specialized encapsulation films. Regulatory restrictions, such as the EU's RoHS directive on lead content, represent a structural supply chain risk. Distribution for BIPV and power generation typically involves direct sales to project developers and system integrators. Specialized distributors serve the portable electronics and IoT device markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The perovskite solar cell market is in an early-cycle expansion, driven by the increasing penetration of Building Integrated Photovoltaics. This growth trajectory offers significant opportunities for strategic positioning across the value chain.
For Market Incumbents: Fortify core technology by investing in advanced encapsulation solutions that mitigate material degradation. Secure long-term supply agreements for lead-free precursors to ensure RoHS compliance and market access in Europe. This defends against emerging entrants offering niche lead-free solutions and strengthens bankability for utility-scale projects.
For New Entrants and Emerging Players: Lead with differentiated offerings in underserved segments, such as transparent BIPV windows or flexible cells for low-power IoT devices. The flexible, printed cell market in South Korea offers a penetrable segment due to its robust electronics manufacturing sector. Partner with established building material suppliers or electronics OEMs for an accelerated go-to-market strategy.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electronics conglomerates or material science firms with under-commercialized perovskite IP. The market exhibits significant long-term viability over the next decade as stability challenges are overcome. Watch for widespread adoption of IEC 61215 certified lead-free modules as a key inflection indicator for broader market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Lead-Free Material R&D | Bypassing RoHS compliance issues unlocks significant European market access. |
| Develop Advanced Encapsulation Technologies | Improving long-term module stability enhances bankability for large-scale projects. |
| Form Strategic Partnerships for BIPV Integration | Accelerating market penetration into construction and urban development sectors. |
| Scale Up Flexible Cell Manufacturing in China | Leveraging existing infrastructure for cost-effective production of niche applications. |
| Pursue IEC 61215 Certification Aggressively | Achieving bankability status is critical for commercial enterprise procurement decisions. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings of this analysis. This approach integrates insights from R&D directors, procurement managers, BIPV architects, and utility project developers with information from IEC standards documents, national energy agency reports, and corporate financial filings. Bottom-up and top-down triangulation ensures comprehensive market sizing.
Sensitivity analysis informs the forecast framework, modeling various scenarios across the projection horizon. Segmentation dimensions included cell architecture, application, end-user, technology type, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends, market drivers, and expert consensus. Perovskite conversion efficiency improvements and lead-free material commercialization timelines served as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside the current regulatory or technological landscape would require recalibration. Forecasts reflect underlying assumptions regarding material stability and manufacturing cost reductions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Distributed Solar Energy Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Parabolic Solar Cookers Market