
 Hybrid Solar Panel Market | 2026-2036
Hybrid Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Solar Panel Market Intelligence
Module distribution through utility-scale EPC contractors is reconfiguring as procurement shifts toward integrated photovoltaic-thermal packages. LONGi Green Energy Technology leverages captive polysilicon capacity to anchor cost positions across crystalline silicon hybrid lines. JinkoSolar Holding competes through geographic diversification of module assembly, while JA Solar Technology specializes in high-efficiency PERC-Thermal architectures for rooftop segments.
A hybrid solar panel combines electricity generation with thermal energy harvesting in a single aperture, typically achieving combined efficiencies above 80% through fluid-cooled photovoltaic substrates that capture waste heat for water or space heating. Photovoltaic-thermal panels dominate current manufacturing volumes due to proven supply chains and compatibility with standard rooftop racking, while perovskite cell technology represents the fastest-growing R&D channel as laboratory efficiencies approach 33% in tandem architectures. Concentrated hybrid panels occupy niche margin pools in desert utility installations where dual-axis tracking justifies capital intensity.
China's MIIT enforces GB standards that mandate minimum conversion thresholds for building-integrated photovoltaics, effectively filtering low-efficiency imports from provincial tenders. The EU Green Deal's revised F-Gas Regulation and CE marking requirements for thermal-fluid compatibility are reshaping export specifications for manufacturers serving European municipal bodies. Stakeholders must monitor how national renewable portfolio standards in India and Brazil evolve to credit hybrid thermal-electric output, as these rules will determine which technology configurations secure long-term offtake contracts.
Market Dynamics
China's MIIT enforcement of updated GB standards for building-integrated photovoltaics is compressing the supplier base, forcing manufacturers to absorb thermal-electric efficiency upgrades or exit provincial tender pools entirely.
Growth Catalysts
- EU F-Gas Regulation:Thermal-fluid compatibility mandates under the revised regulation are accelerating R&D into non-fluorinated coolants for European municipal deployments.
- Utility-scale EPC procurement:Integrated photovoltaic-thermal packages are displacing discrete component purchasing as grid operators seek unified performance warranties.
- Perovskite tandem architectures:Laboratory efficiency breakthroughs approaching 33% are pulling capital into pilot manufacturing lines for next-generation substrates.
Market Restraints
- Polysilicon price volatility:Crystalline silicon hybrid lines remain exposed to ingot cost swings that compress module margins during upstream supply crunches.
- Jiangsu supply concentration:Integrated production campuses in a single province create geographic risk for buyers dependent on just-in-time thermal collector delivery.
- Dual-axis tracking capital intensity:Concentrated hybrid panels require mechanical infrastructure that limits deployment to desert utility installations with patient capital.
Strategic Opportunities
- India renewable portfolio standards:Evolving credit mechanisms for hybrid thermal-electric output could unlock long-term offtake contracts for configurations meeting CEA guidelines.
- Brazil distributed generation:Net metering expansion for rooftop segments favors compact PVT modules over separate thermal and electric installations.
- Perovskite-silicon convergence:Tandem cell integration with fluid-cooled substrates offers a pathway to 80%+ combined efficiency in building-integrated applications.
Industry Challenges
- CE thermal-fluid certification timelines:European conformity assessment delays for new coolant chemistries extend product launch windows by 8-14 months.
- Building code integration complexity:Municipal permitting departments lack standardized protocols for hybrid aperture structural load calculations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Solar Panel Market |
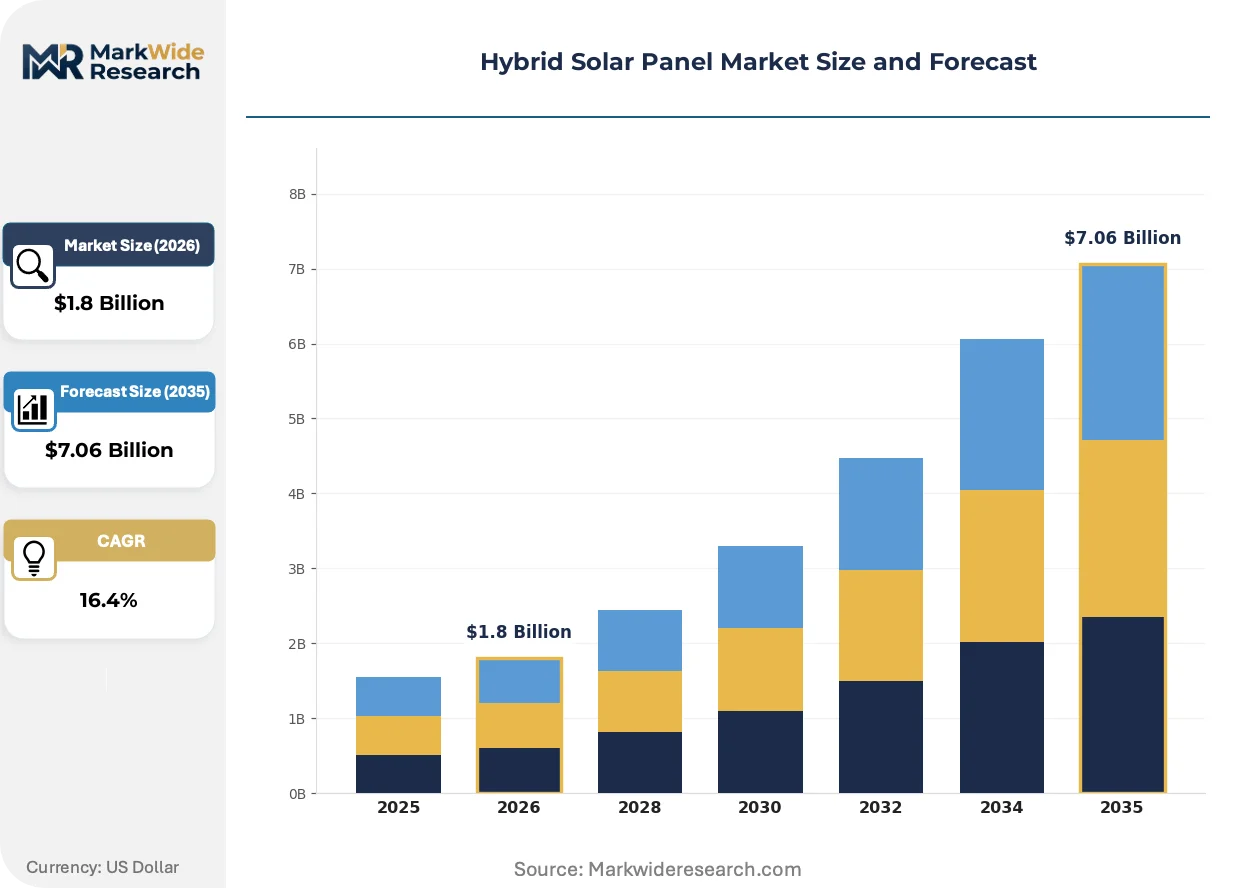
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic-Thermal Panels, Concentrated Hybrid Panels, Building-Integrated Photovoltaics, Thin-Film Hybrid Panels, Organic Hybrid Panels Technology: Crystalline Silicon, Amorphous Silicon, Gallium Arsenide, Perovskite Cells, Dye-Sensitized Solar Cells Application: Residential Rooftops, Commercial Complexes, Off-Grid Systems, Agricultural Irrigation, Public Infrastructure End User: Utility Companies, Residential Developers, Agricultural Enterprises, Commercial Property Managers, Municipal Bodies |
| Companies Covered | LONGi Green Energy Technology Co. Ltd, Tongwei Solar, JinkoSolar Holding Co. Ltd, Hanwha Q CELLS, Risen Energy Co. Ltd, JA Solar Technology Co. Ltd, Canadian Solar Inc., DAS Solar Co. Ltd, Trina Solar Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Solar Panel Market Strategic Shifts & Innovations
Fluid-cooled photovoltaic substrates are virtualizing the boundary between electricity and thermal infrastructure, enabling manufacturers to sell energy services rather than hardware components.
Perovskite tandem cell technology is virtualizing the efficiency ceiling for hybrid panels by stacking wide-bandgap absorbers atop silicon junctions. Residential and commercial installers in Germany and the Netherlands are piloting these modules for building-integrated applications where roof area constraints dominate. The technology is virtualizing the traditional trade-off between electrical output and thermal harvest, compressing payback periods for dual-use installations.
China's MIIT is tightening GB standard efficiency thresholds for building-integrated photovoltaics, filtering low-efficiency imports from provincial tender pools. Domestic manufacturers with captive polysilicon capacity are absorbing compliance costs through backward integration into ingot production. Export-oriented suppliers serving European municipal bodies are reconfiguring thermal-fluid specifications to satisfy F-Gas Regulation compatibility requirements.
Aggregated procurement through utility-scale EPC contractors is consolidating buyer power and compressing supplier margins. Integrated photovoltaic-thermal packages are displacing discrete component purchasing as grid operators seek unified performance warranties and single-point accountability. This concentration is most visible across Asia-Pacific utility companies expanding grid-scale deployment of hybrid systems.
Hybrid Solar Panel Market Segmentation
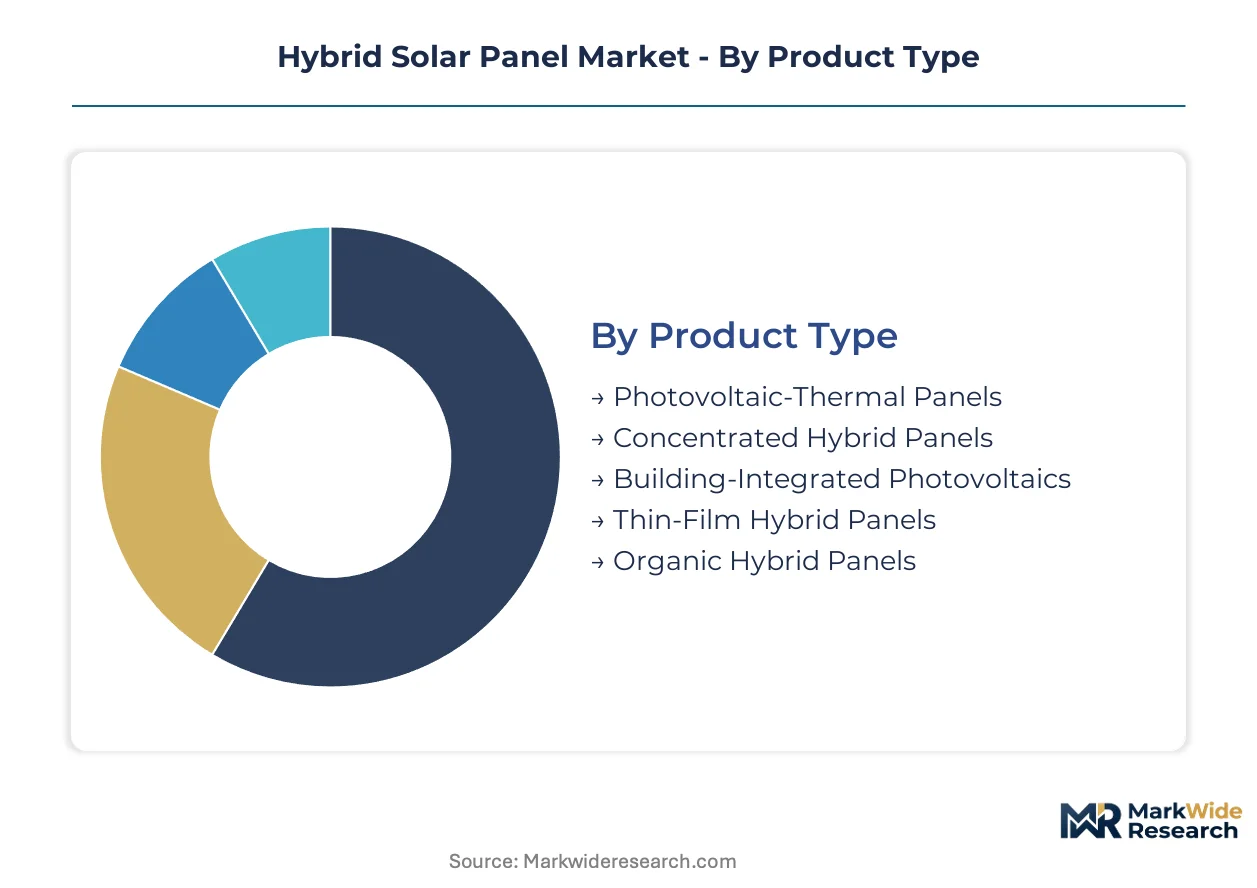
Hybrid solar panel segmentation reveals how technical architectures align with distinct procurement logics across utility-scale and distributed generation contexts. Product configurations vary sharply in capital intensity and thermal-electric output ratios, while technology choices determine compatibility with existing racking infrastructure and building codes.
Product Type:
Mature rooftop-compatible formats dominate installed base volumes, while emerging concentrated architectures occupy niche utility deployments requiring patient capital and dual-axis tracking infrastructure.
- Photovoltaic-Thermal Panels:Fluid-cooled crystalline silicon substrates capture waste heat through integrated thermal collectors for water or space heating. Demand concentrates across German and Dutch residential installers where roof area constraints favor dual-output density over discrete thermal-electric installations.
- Concentrated Hybrid Panels:Dual-axis tracking mirrors focus sunlight onto multi-junction cells with active thermal extraction, achieving the highest combined efficiencies in desert utility installations. Capital intensity limits procurement to Middle Eastern and Australian grid operators with long-dated power purchase agreements.
- Building-Integrated Photovoltaics:Architectural substrates replacing conventional cladding materials with embedded thermal-electric harvesting. China's MIIT GB standards mandate minimum conversion thresholds that filter low-efficiency imports from provincial tender pools.
- Thin-Film Hybrid Panels:Flexible cadmium telluride or copper indium gallium selenide layers on thermal substrates for weight-constrained commercial rooftops.
- Organic Hybrid Panels:Polymer-based absorbers with integrated thermal management for disposable or temporary off-grid applications in humanitarian and military contexts.
Photovoltaic-thermal panels retain volume leadership; concentrated hybrid panels hold the steepest expansion curve among utility-scale configurations.
Technology:
Cost tiers separate incumbent silicon architectures from emerging thin-film and tandem cell approaches competing on efficiency breakthroughs versus manufacturing scale.
- Crystalline Silicon:Mature supply chains anchored by captive polysilicon capacity in Jiangsu province manufacturing corridors. LONGi and Tongwei leverage backward integration into ingot production to absorb thermal-electric efficiency upgrade costs.
- Perovskite Cells:Laboratory tandem architectures approaching 33% efficiency are pulling capital into pilot manufacturing lines. Residential and commercial pilots in Germany and the Netherlands target building-integrated applications where roof area constraints dominate procurement decisions.
- Amorphous Silicon:Lower-temperature deposition enables flexible substrates for curved commercial rooftops and vehicle-integrated applications.
- Gallium Arsenide:Multi-junction concentrator cells for space-constrained satellite and high-altitude platform deployments.
- Dye-Sensitized Solar Cells:Organic liquid electrolyte architectures for indoor and diffuse-light building-integrated scenarios.
Crystalline silicon commands manufacturing scale; perovskite tandem architectures are climbing the fastest toward commercial viability thresholds.
Application:
Customer type determines whether procurement prioritizes unified performance warranties from EPC contractors or discrete component flexibility for self-managed installations.
- Residential Rooftops:Compact PVT modules displace separate thermal and electric installations where net metering policies credit hybrid output. Brazil's distributed generation expansion favors integrated packages over discrete component purchasing.
- Commercial Complexes:High-efficiency PERC-thermal architectures from JA Solar Technology target rooftop segments where structural load calculations complicate municipal permitting.
- Off-Grid Systems:Standalone hybrid configurations with battery thermal management for remote telecommunications and mining operations.
- Agricultural Irrigation:Solar-thermal pumping systems with diurnal thermal storage for water-scarce farming regions.
- Public Infrastructure:Municipal procurement through aggregated EPC channels seeking single-point accountability for airport, hospital, and school deployments.
Residential rooftops anchor distributed generation volumes; commercial complexes are gaining share fastest as building-integrated efficiency thresholds tighten.
End User:
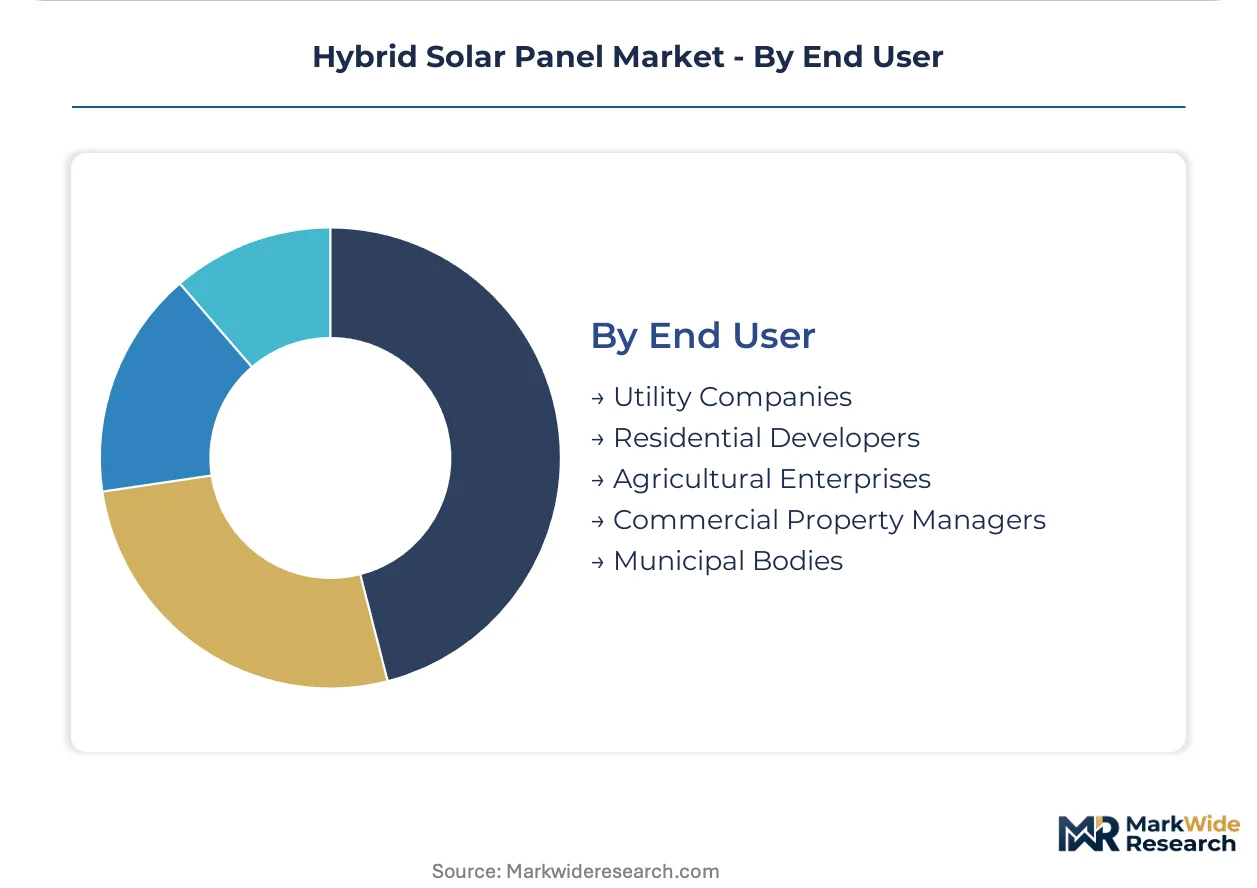
Procurement scale separates centralized utility buyers from fragmented commercial and residential decision-makers with divergent warranty and financing requirements.
- Utility Companies:Asia-Pacific grid operators are expanding procurement of photovoltaic-thermal hybrid systems for grid-scale deployment. Aggregated EPC contracting consolidates buyer power and compresses supplier margins through unified performance warranty demands.
- Municipal Bodies:European city governments under EU Green Deal F-Gas Regulation mandates require thermal-fluid compatibility certification, extending product launch windows by 8-14 months for new coolant chemistries.
- Residential Developers:Prefabricated housing integrators specifying standardized PVT modules across multi-unit construction portfolios.
- Commercial Property Managers:Lease-structured energy service agreements favoring outcome-based thermal-electric output contracts over hardware ownership.
- Agricultural Enterprises:Irrigation cooperatives pooling procurement for solar-thermal pumping with seasonal thermal storage.
Utility companies retain procurement scale leadership; municipal bodies are expanding fastest as F-Gas Regulation compliance reshapes European tender specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT anchors the dominant geography through GB standard enforcement that filters low-efficiency imports from provincial tender pools. Jiangsu province's manufacturing corridor concentrates integrated production campuses where domestic manufacturers absorb compliance costs through backward integration.
China
Utility companies across Jiangsu and Anhui provinces are expanding procurement of photovoltaic-thermal hybrid systems for grid-scale deployment. MIIT's updated GB standards for building-integrated renewables mandate minimum conversion thresholds that force thermal-electric efficiency upgrades. Tongwei Solar and LONGi operate integrated production campuses in Jiangsu's manufacturing corridor, anchoring cost positions through captive polysilicon capacity.
Germany
Residential and commercial installers in Bavaria and North Rhine-Westphalia are piloting perovskite tandem modules for building-integrated applications where roof area constraints dominate. The EU Green Deal's revised F-Gas Regulation mandates thermal-fluid compatibility certification, extending product launch windows for new coolant chemistries. Municipal procurement in the Ruhr region favors aggregated EPC contracting with unified performance warranties.
United States
Utility-scale EPC contractors in California and Texas are consolidating buyer power through integrated photovoltaic-thermal package procurement. FERC grid interconnection standards and state-level renewable portfolio standards shape technology configuration requirements. The Southwest's desert utility installations accommodate concentrated hybrid panels with dual-axis tracking infrastructure and patient capital structures.
India
CEA guidelines for hybrid thermal-electric output crediting are evolving across Maharashtra and Gujarat, unlocking long-term offtake contracts for compliant configurations. State-level renewable portfolio standards in Rajasthan and Karnataka are tightening eligibility criteria for hybrid system installations. Manufacturing clusters in Pune and Ahmedabad are developing localized supply chains for PVT module assembly.
Brazil
Net metering expansion for rooftop segments in São Paulo and Minas Gerais favors compact PVT modules over separate thermal and electric installations. ANVISA and national energy regulator ANEEL are coordinating standards for distributed generation equipment certification. Agricultural irrigation cooperatives in the Northeast are pooling procurement for solar-thermal pumping systems with seasonal thermal storage.
Hybrid Solar Panel Market Key Industry Players
Vertically integrated polysilicon producers and specialized module assemblers split the market along cost-structure and technology-differentiation vectors. The supplier base compresses around manufacturers with captive ingot production capacity versus those dependent on spot-market feedstock. Three archetypes dominate: backward-integrated giants controlling upstream polysilicon, geographic diversifiers with distributed assembly networks, and efficiency specialists targeting premium building-integrated segments. Competitive moves concentrate on thermal-electric efficiency upgrades to satisfy tightening GB standards and strategic partnerships with utility-scale EPC contractors seeking unified performance warranties.
Among Chinese manufacturers, LONGi Green Energy Technology Co. Ltd and Tongwei Solar exemplify the backward-integrated archetype through positions in Jiangsu province's manufacturing corridor. JinkoSolar Holding Co. Ltd occupies a geographic diversification position within the competitive landscape. These three entities anchor the supply-side structure that utility-scale EPC contractors and municipal procurement bodies navigate when sourcing integrated photovoltaic-thermal packages.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co. Ltd |
| Tongwei Solar |
| JinkoSolar Holding Co. Ltd |
| Hanwha Q CELLS |
| Risen Energy Co. Ltd |
| JA Solar Technology Co. Ltd |
| Canadian Solar Inc. |
| DAS Solar Co. Ltd |
| Trina Solar Co. Ltd |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port freight corridors carry polysilicon ingots and thermal collector substrates from Jiangsu manufacturing campuses to European EPC contractors, with container rate volatility compressing margins for non-integrated assemblers while amplifying cost advantages for producers with captive upstream capacity.
Pricing Analysis
The customization-premium spread between configured-to-order PVT packages and standard crystalline silicon modules runs wide, with project-based long-term offtake contracts dominating utility procurement while spot-market transactions persist for distributed generation. Price differentiation hinges on thermal-electric efficiency certification tier and volume scale, with GB standard compliance commanding premium positioning. Cost compression in standard-tier modules is intensifying because polysilicon spot price swings transmit directly to non-integrated buyers. Utility companies exhibit lowest price sensitivity due to unified performance warranty requirements, while residential installers in Brazil remain most responsive to per-watt pricing.
Supply Chain Analysis
Polysilicon feedstock draws from China, South Korea, and Germany, with metallurgical-grade silicon refining concentrated in Xinjiang and Inner Mongolia before ingot pulling in Jiangsu corridor facilities. Critical dependencies include high-purity quartz crucibles, thermal transfer fluids, and aluminum racking extrusions. Single-source vulnerability around Jiangsu province integrated campuses creates geographic concentration risk for just-in-time thermal collector delivery. Distribution runs through utility-scale EPC contractors consolidating procurement into aggregated photovoltaic-thermal packages with unified performance warranties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid solar panel market fragmentation creates white-space opportunity as building-integrated efficiency thresholds splinter procurement requirements across residential, commercial, and utility segments with divergent certification and warranty demands.
For Market Incumbents: Entrench cost positions through backward integration into polysilicon ingot production, mirroring LONGi and Tongwei's Jiangsu corridor model. Lock in EPC contractor relationships with multi-year unified performance warranties before perovskite tandem architectures mature. Defend against emerging thin-film specialists by accelerating thermal-electric efficiency upgrades to satisfy tightening MIIT GB standards.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian distributed generation rooftop segments where net metering expansion favors compact PVT modules over incumbent crystalline silicon configurations. Target agricultural irrigation cooperatives in India's Maharashtra and Gujarat with solar-thermal pumping systems featuring seasonal thermal storage. Pursue outcome-based energy service agreements rather than hardware sales to bypass incumbent scale advantages.
For Investors and Strategic Acquirers: Efficiency-specialist module assemblers with pilot perovskite-silicon tandem lines represent prime acquisition targets as laboratory breakthroughs approach commercial viability thresholds. Long-term viability over the coming decade hinges on successful thermal-fluid compatibility certification under EU F-Gas Regulation timelines. Watch CEA guideline evolution for hybrid thermal-electric output crediting as the inflection signal for India market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive ingot production in Jiangsu corridor absorbs GB standard compliance costs for Tongwei and LONGi. |
| Perovskite Tandem Pilot Manufacturing | Laboratory efficiency approaching 33% pulls capital into German and Dutch building-integrated residential pilots. |
| EPC Contractor Partnership Lock-in | Unified performance warranties consolidate buyer power across Asia-Pacific utility procurement channels. |
| Thermal-Fluid Certification Investment | EU F-Gas Regulation compliance extends product launch windows by 8-14 months for European municipal tenders. |
| Geographic Diversification of Assembly | JinkoSolar's distributed manufacturing network mitigates Jiangsu supply concentration risk for thermal collector delivery. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA renewable energy reports, MIIT GB standard filings, and FERC interconnection records. Primary interviews engaged utility planning officers, EPC contractor procurement leads, solar module manufacturing executives, and municipal energy directors across China, Germany, India, and Brazil. Bottom-up module shipment data triangulates against top-down capacity installation tracking from grid operator disclosures.
Forecast inputs span technology segmentation by cell architecture, application tier from residential rooftop to desert utility, and end-user procurement scale from fragmented commercial property managers to consolidated Asia-Pacific grid operators. CAGRs derive from installed base growth trajectories, replacement cycle assumptions, and efficiency upgrade penetration curves. Industry-specific variables include polysilicon price volatility transmission, perovskite tandem commercialization timelines, and renewable portfolio standard evolution across India and Brazil.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments for project finance, freight rate volatility on Asia-Europe corridors, or currency fluctuation in emerging market procurement would shift the trajectory. Forecasts embed assumptions around MIIT GB standard enforcement continuity, EU F-Gas Regulation implementation pace, and CEA guideline finalization. Cross-checking against IEA World Energy Outlook renewable deployment benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
PV Solar Data Logger Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Perovskite Solar Cell Market
Solar Power Systems
PERC Solar Panels Market
Solar Power Systems
Japan Solar Energy Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Thin Film Photovoltaic Modules Market