
 US Solar Market | 2026-2036
US Solar Market Size, Share, and Industry Trends Forecast 2026-2036
US Solar Market Insights
The capital-intensity divergence between thin-film specialists and silicon-module assemblers is collapsing as polysilicon price volatility forces both camps toward integrated wafer-cell-module strategies. First Solar leverages its Ohio cadmium-telluride verticality to bypass Chinese polysilicon exposure entirely. Hanwha Q CELLS USA anchors its Georgia factory expansion on domestic content compliance for IRA bonus credits. NextEra Energy sustains the largest utility-scale development pipeline through captive offtake agreements and regulated utility balance sheets.
US solar encompasses photovoltaic energy systems that convert sunlight into direct-current electricity through semiconductor junctions, with monocrystalline silicon cells now achieving laboratory efficiencies exceeding 26% and commercial modules routinely surpassing 21%. These systems serve grid-connected generation, distributed commercial rooftops, and residential self-consumption with or without co-located battery storage. Photovoltaic panels dominate installed value but battery storage commands the fastest expansion as utility procurement shifts toward dispatchable solar-plus-storage configurations. Rooftop installations face margin compression from interconnection delays and net-metering policy reversals in several states, while ground-mounted utility projects capture economies of scale through bifacial tracking architectures. Thin-film technology retains strategic relevance in utility procurement where temperature coefficients and spectral response advantages offset efficiency gaps.
FERC Order 2023 reforms interconnection queue processes while EPA greenhouse gas standards for power plants effectively mandate solar displacement of coal baseload. OSHA lockout-tagout and fall-protection enforcement shapes installation labor costs and contractor qualification requirements across state jurisdictions. State renewable portfolio standards in California, New York, and Illinois create layered demand mandates with divergent eligibility rules for distributed versus utility-scale assets. Stakeholders must monitor evolving domestic content interpretations from the Department of Treasury and corresponding supply chain reconfiguration timelines.
Market Dynamics
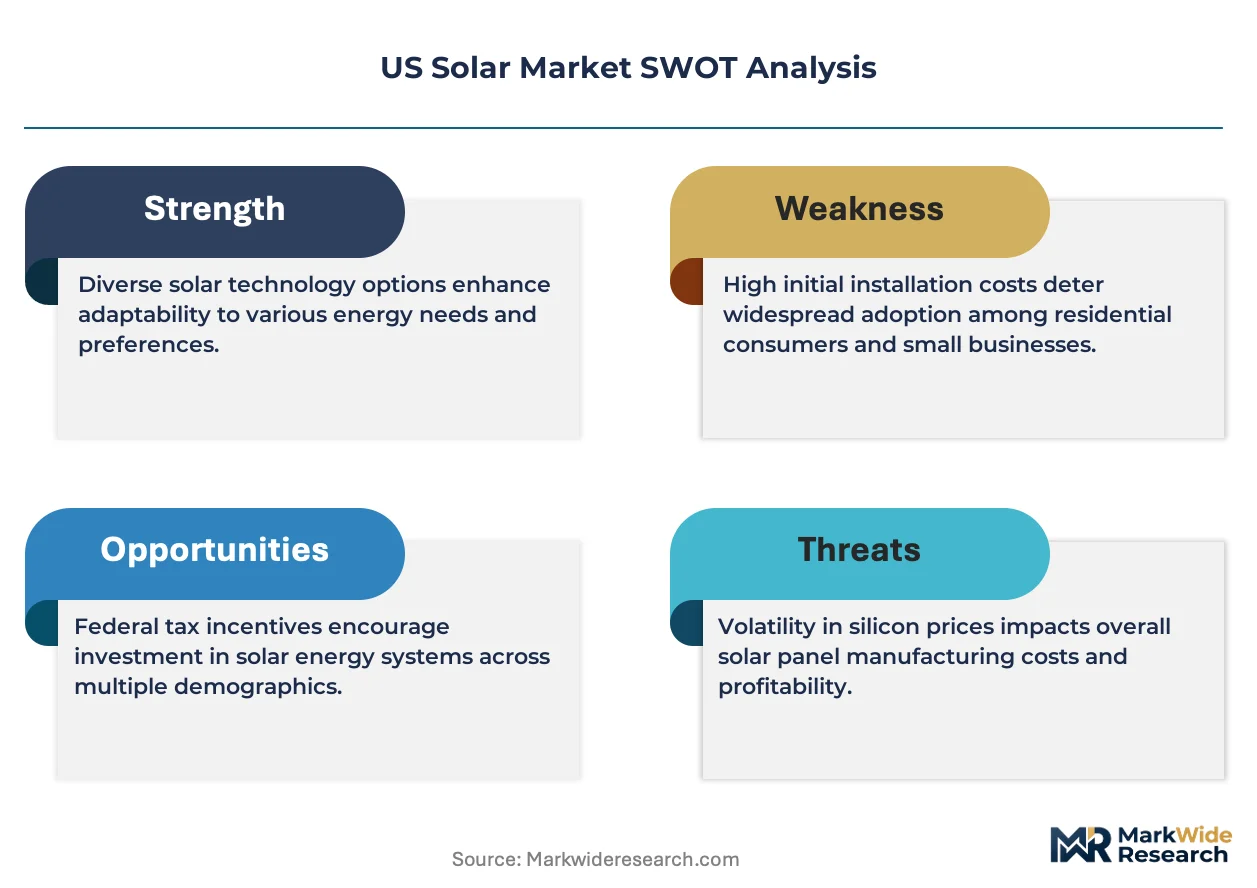
The US solar market restructures around the Inflation Reduction Act's domestic content thresholds, forcing developers to requalify supply chains for bonus credit eligibility while interconnection queue reforms compress project timelines.
Growth Catalysts
- IRA Investment Tax Credits:The 30% base credit plus domestic content adders redirects capital toward American manufacturing facilities.
- Utility-Scale Procurement:Investor-owned utilities in Texas and California sign long-term power purchase agreements for bifacial tracking installations.
- FERC Order 2023:Reformed interconnection study processes reduce queue backlog delays for grid-connected solar-plus-storage projects.
Market Restraints
- Polysilicon Price Volatility:Chinese ingot and wafer concentration exposes module assemblers to input cost swings.
- Land Interconnection Constraints:Transmission availability in the Southwest limits project economics despite irradiance advantages.
- Net-Metering Policy Reversals:California's NEM 3.0 reduces export compensation rates and compresses residential payback periods.
Strategic Opportunities
- Agrivoltaic Deployment:Dual-use solar installations on agricultural land unlocks new site categories in the Midwest.
- Virtual Power Plant Aggregation:Distributed battery networks participate in wholesale markets through FERC Order 2222 compliance.
- Domestic Cell Manufacturing:Thin-film and silicon cell fabs in Ohio and Georgia capture IRA advanced manufacturing credits.
Industry Challenges
- Electrical Trade Labor Scarcity:Licensed electricians for utility-scale DC field wiring command premium wages across Texas and Arizona.
- OSHA Fall-Protection Compliance:Residential rooftop contractors face elevated insurance costs from elevated work platform mandates.
- Domestic Content Interpretation:Treasury Department guidance uncertainty delays financing for projects targeting bonus credit thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Solar Market |
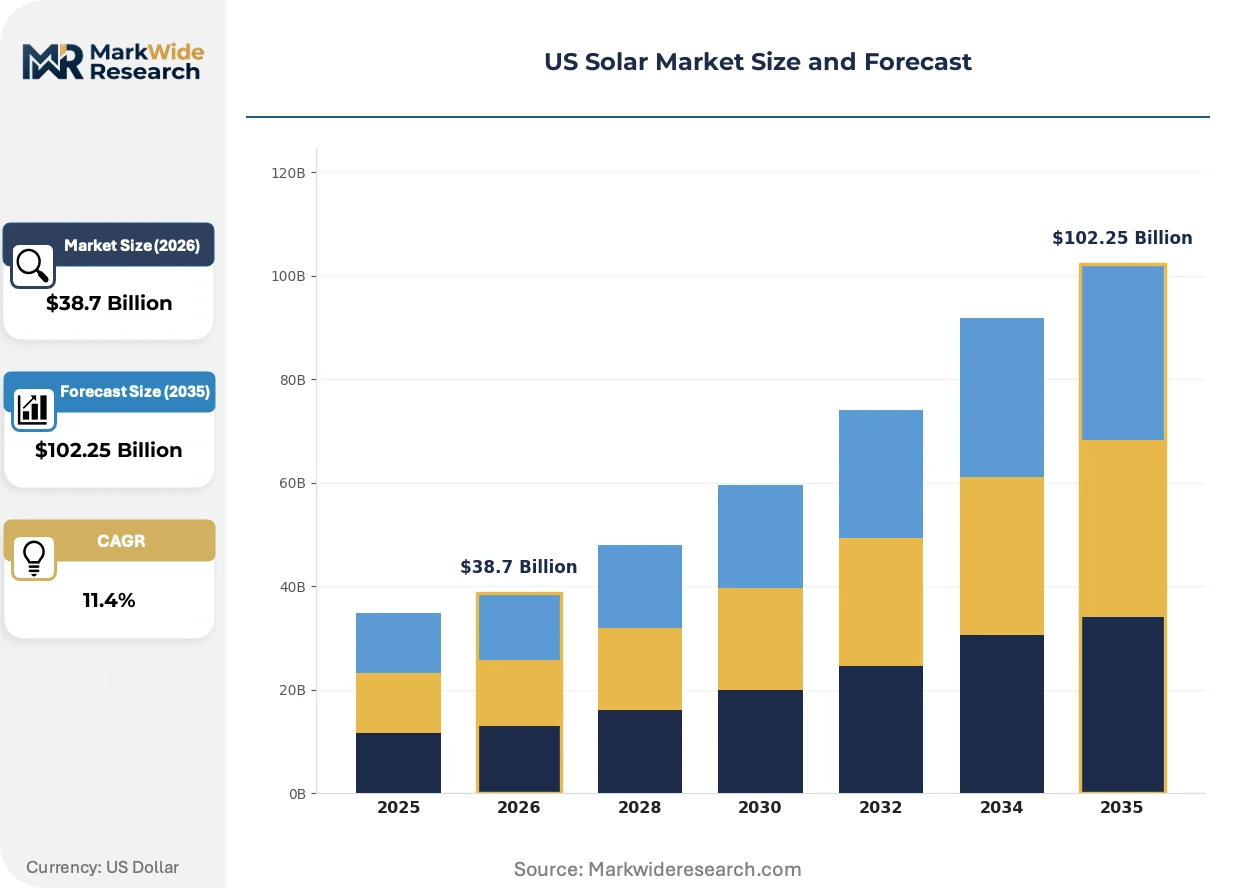
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Mounting Systems, Battery Storage End User: Residential, Commercial, Utility, Government Installation Type: Ground-Mounted, Rooftop, Carport, Building-Integrated Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial |
| Companies Covered | First Solar, NextEra Energy, Hanwha Q CELLS USA, Canadian Solar, Sunrun, Invenergy, EDF Renewables North America, Cypress Creek Renewables, Tesla Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Solar Market Trends and Innovations
Bifacial module architectures and co-located battery systems reshape competitive differentiation, while supply chain regionalization accelerates under tariff and incentive pressures.
Cadmium-telluride thin-film technology is displacing imported silicon modules in utility procurement where temperature coefficients and spectral response offset efficiency gaps. Arizona and Nevada developers specify CdTe for desert installations where heat degradation erodes silicon performance. The shift compresses polysilicon exposure and insulates project returns from Chinese supply disruptions.
EPA greenhouse gas standards for existing power plants mandate solar displacement of coal baseload across the Ohio River Valley. Coal-dependent utilities in West Virginia and Kentucky accelerate procurement timelines to meet compliance deadlines. The rule forces regulated utilities to preference solar-plus-storage over gas peaker replacements in integrated resource plans.
Corporate offtakers now require hourly matching certificates rather than annual renewable energy credits. Data center operators in Virginia and Texas contract for dispatchable solar-plus-storage to meet 24/7 carbon-free electricity pledges. The behavioral shift concentrates procurement in markets with robust battery co-location economics.
US Solar Market Segmentation
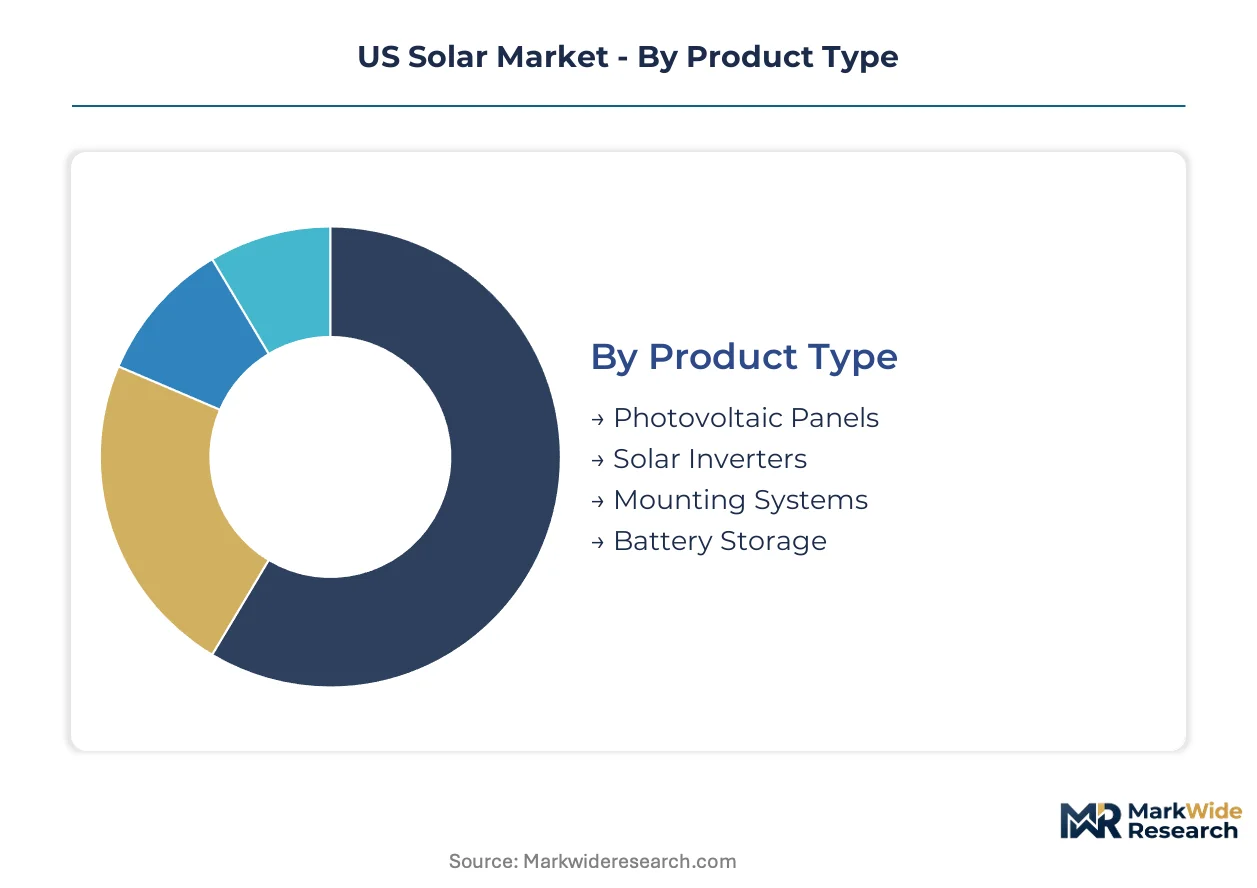
US solar market segmentation reveals divergent margin pools across hardware categories and customer archetypes. Procurement patterns bifurcate between price-sensitive residential installers and regulated utilities with captive balance sheets.
Product Type:
Margin pools concentrate in power electronics and energy storage rather than commoditized module assembly.
- Photovoltaic Panels:Semiconductor junctions converting sunlight to direct-current electricity, with monocrystalline silicon achieving laboratory efficiencies exceeding 26%. Utility-scale developers in Texas and California prioritize bifacial architectures for enhanced rear-side energy harvest on reflective desert terrain.
- Battery Storage:Lithium-ion electrochemical systems enabling dispatchable solar output through DC-coupled or AC-coupled configurations. IRA standalone storage credits and FERC Order 841 market participation rules accelerate co-location economics in Southwest wholesale markets.
- Solar Inverters:Power electronics converting DC panel output to grid-synchronous alternating current.
- Mounting Systems:Structural hardware securing panels to rooftops or ground foundations.
Photovoltaic panels hold installed capacity. Battery storage is rotating up the share rankings.
End User:
Customer-type segmentation maps directly to financing structures and regulatory exposure.
- Utility:Investor-owned and public power entities procuring solar-plus-storage through competitive solicitations and integrated resource plans. FERC Order 2023 interconnection reforms and EPA greenhouse gas standards compress procurement timelines in the Ohio River Valley and Southeast.
- Residential:Single-family and multifamily rooftop installations financed through loans, leases, or power purchase agreements. California NEM 3.0 export compensation reductions and interconnection queue delays compress payback periods and contractor margins.
- Commercial:On-site generation for retail, industrial, and institutional facilities.
- Government:Federal, state, and municipal procurement through simplified acquisition vehicles.
Utility-scale deployment commands capital deployment. Residential is climbing the fastest as financing products mature.
Installation Type:
Site configuration determines labor intensity, permitting complexity, and land-use constraints.
- Ground-Mounted:Fixed-tilt or tracking arrays on dedicated land parcels achieving economies of scale through bifacial module deployment and automated cleaning systems. Southwest developers face transmission availability bottlenecks despite superior irradiance profiles.
- Rooftop:Distributed generation on residential and commercial structures with net-metering or behind-the-meter self-consumption economics. OSHA fall-protection mandates and licensed electrician scarcity elevate soft costs across Arizona and Texas contractor markets.
- Carport:Elevated canopy structures serving dual parking and generation functions.
- Building-Integrated:Photovoltaic materials replacing conventional building envelope components.
Ground-mounted arrays dominate megawatt-hour additions. Carport configurations are gaining share fastest in constrained urban sites.
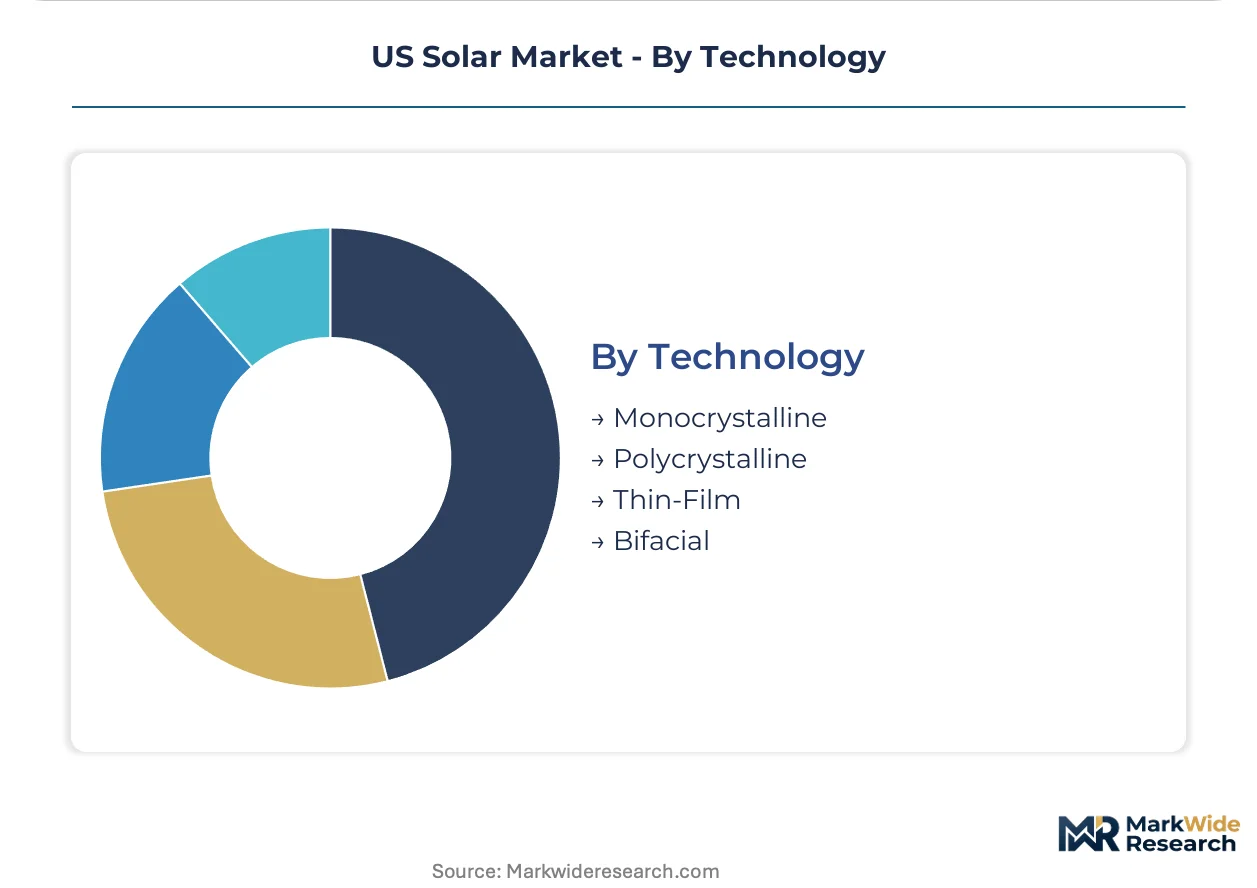
Technology:
Cell architecture selection hinges on efficiency, temperature coefficient, and supply chain concentration risk.
- Monocrystalline:Single-crystal silicon cells with commercial module efficiencies routinely surpassing 21%. Domestic wafer and cell manufacturing investments in Ohio and Georgia target IRA domestic content thresholds for bonus credit eligibility.
- Thin-Film:Cadmium-telluride and other non-silicon absorber layers with superior spectral response and temperature coefficients. First Solar's Ohio verticality bypasses Chinese polysilicon exposure entirely while capturing utility procurement in desert climates.
- Polycrystalline:Multi-crystal silicon cells with lower efficiency but reduced manufacturing energy intensity.
- Bifacial:Double-glass architectures harvesting rear-side albedo reflection.
Monocrystalline silicon commands manufacturing investment. Thin-film is rotating up the share rankings through supply chain risk mitigation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US solar market exhibits pronounced regional specialization, with domestic module assembly concentrated in the Southeast and Ohio River Valley while project development clusters in high-irradiance Southwestern states. Export dynamics remain minimal given tariff structures, though inter-state component flows reshape procurement economics.
Texas
ERCOT wholesale market volatility and interconnection queue reforms attract utility-scale developers to West Texas solar zones. FERC Order 2023 streamlines grid access studies for battery-co-located projects in the Permian Basin. The Abilene-Sweetwater corridor hosts multiple gigawatt-scale tracking installations serving corporate offtakers in Dallas-Fort Worth.
California
CPUC resource adequacy mandates and NEM 3.0 export compensation cuts bifurcate deployment between utility procurement and strained residential economics. CEC Title 24 building standards mandate solar readiness in new construction across Central Valley counties. The Imperial Valley-Ivanpah cluster maintains concentrated utility-scale development despite transmission constraints.
Georgia
Georgia Power integrated resource plans and PSC-approved renewable expansion targets anchor Southeast manufacturing investment. IRA domestic content bonuses incentivize wafer and cell fabrication in the Atlanta exurbs. The Dalton-Rome corridor hosts vertically integrated module assembly serving regulated utility procurement across the Southeast.
Arizona
APS and SRP renewable energy standards drive procurement in Maricopa County despite escalating land-use conflicts. OSHA fall-protection enforcement shapes residential contractor qualification requirements in Phoenix-Tucson metro areas. The Gila Bend-Casa Grande zone concentrates tracking installations on federal land with streamlined BLM permitting.
Ohio
Industrial electricity demand from automotive electrification and data center expansion supports solar procurement in PJM West. EPA greenhouse gas standards for existing power plants accelerate coal displacement timelines for Ohio Valley utilities. The Toledo-Perrysburg corridor anchors domestic thin-film manufacturing with captive cadmium-telluride supply chains.
US Solar Market Competitive Landscape
Concentration sits with vertically integrated thin-film specialists and regulated utility-affiliated developers. The vendor base separates into three strategic tiers: domestic-content-compliant manufacturers capturing IRA bonus credits, independent power producers with captive offtake pipelines, and distributed installation platforms facing margin compression. Competitive moves center on backward integration into polysilicon bypass strategies and strategic partnerships with electrical trade unions to secure installation labor.
Among domestic-content-focused manufacturers, First Solar exemplifies thin-film verticality with Ohio-based cadmium-telluride production. Hanwha Q CELLS USA occupies a position within the silicon-module tier through Georgia fabrication targeting IRA compliance thresholds. NextEra Energy anchors the utility-affiliated developer archetype through regulated balance sheet deployment and long-term power purchase agreement origination.
| Leading Market Players |
|---|
| First Solar |
| NextEra Energy |
| Hanwha Q CELLS USA |
| Canadian Solar |
| Sunrun |
| Invenergy |
| EDF Renewables North America |
| Cypress Creek Renewables |
| Tesla Energy |
| Others |
Pricing and Supply Chain Analysis
Ninety-day module inventory cycles in domestic warehouses compress pricing power for silicon-module assemblers while amplifying margins for thin-film verticalists with captive cadmium-telluride supply. IRA domestic content bonuses reshape procurement premiums as developers requalify supply chains for bonus credit eligibility. The feedback loop between inventory positioning and pricing leverage concentrates among Ohio and Georgia manufacturing clusters.
Pricing Analysis
The customization-premium spread between standard utility-scale module contracts and configured-to-order bifacial tracking systems runs three to five percentage points on levelized cost of energy terms. Project-based long-term offtake agreements dominate utility procurement, with price differentiation driven by domestic content compliance tier and module efficiency certification. Cost compression in residential rooftop segments intensifies as NEM 3.0 export compensation cuts force installers to absorb interconnection delays. Investor-owned utilities exhibit lowest price sensitivity due to regulated cost recovery mechanisms, while residential contractors face acute margin pressure from licensed electrician scarcity.
Supply Chain Analysis
Just-in-time inventory strategies prevail among module assemblers dependent on Chinese ingot and wafer inputs, while strategic stockpiling characterizes thin-film specialists with Ohio-based verticality. Geographic supply concentration centers on China for polysilicon purification, Malaysia for cell fabrication, and Vietnam for module assembly. Raw material dependencies span high-purity silicon metal, silver metallization paste, and aluminum framing extrusions. Tariff exposure on Southeast Asian cell imports constitutes the primary structural risk. Distribution runs through utility-scale EPC contractors and residential installation platforms with divergent working capital requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Operations and maintenance service contracts represent the fastest-expanding recurring-revenue layer in US solar, outpacing hardware sales as asset owners prioritize performance guarantees over capital expenditure optimization.
For Market Incumbents: Compound defensive positioning through backward integration into polysilicon bypass strategies and captive cell manufacturing in Ohio and Georgia. First Solar's cadmium-telluride verticality demonstrates how supply chain insulation preserves margin pools against Chinese input volatility. Expand strategic partnerships with International Brotherhood of Electrical Workers locals to secure installation labor pipelines across Texas and Arizona contractor markets. For New Entrants and Emerging Players: Post-installation monitoring and predictive maintenance software layers present under-served white space where incumbents prioritize hardware shipment over asset performance optimization. Agrivoltaic deployment in Midwest corn and soybean regions offers the most penetrable geography given streamlined USDA dual-use permitting and landowner revenue diversification appetite. Pursue direct origination with rural electric cooperatives bypassing congested interconnection queues that constrain investor-owned utility projects. For Investors and Strategic Acquirers: Carve-out targets emerge from regulated utility-affiliated developers seeking to monetize development pipelines without balance sheet consolidation. Long-term viability hinges on IRA domestic content interpretation stability and FERC interconnection reform implementation velocity. Acquisition screening should prioritize Ohio and Georgia manufacturing footprints with Treasury-compliant supply chain documentation. Watch Treasury Department guidance on domestic content thresholds as the critical inflection indicator for financing availability.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cell Manufacturing Buildout | Ohio and Georgia fabs capture IRA advanced manufacturing credits while bypassing tariff exposure. |
| Solar-Plus-Storage Power Purchase Agreements | Corporate offtakers in Virginia and Texas contract for dispatchable output meeting hourly matching requirements. |
| Agrivoltaic Site Development | Dual-use installations unlock USDA-simplified permitting across Midwest agricultural counties. |
| Electrical Trade Union Partnerships | IBEW training pipeline agreements address licensed electrician scarcity in Arizona and Texas markets. |
| Bifacial Tracking Technology Licensing | Desert installations in Nevada and Arizona leverage albedo-enhanced rear-side energy harvest. |
Research Methodology
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against EIA generation data, FERC interconnection filings, IEA technology roadmaps, and project development databases. Bottom-up capacity and deployment modeling triangulated against top-down macroeconomic scenario analysis.
Sensitivity analysis across module price, interconnection timeline, and IRA credit availability scenarios framed the forecast framework. Segmentation dimensions modeled span technology architecture, installation type, end-user category, and regional regulatory cluster. CAGRs derived from deployment run-rate analysis and manufacturing capacity expansion schedules. Key inputs include FERC Order 2023 implementation velocity and Treasury domestic content guidance evolution across the projection horizon.
Forecasts assume regulatory continuity in IRA credit structures and FERC interconnection reforms; material policy shifts would require re-modeling. Revision becomes warranted when polysilicon price volatility or Treasury guidance uncertainty crosses thresholds that alter project finance availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Software Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
DSC Solar Technologies Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Concentrated Photovoltaic System Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
High-Efficiency Solar Modules Market