
 Solar Panel Market | 2026-2036
Solar Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Market Intelligence
The transition from PERC to next-generation TOPCon and HJT cell architectures is fragmenting the previously uniform technology landscape. Chinese manufacturers like JinkoSolar and LONGi Green Energy are scaling up TOPCon production to secure technology leadership. In contrast, First Solar leverages its proprietary thin-film cadmium telluride (CdTe) technology, creating a distinct competitive position. Canadian Solar navigates this shift by offering a diversified portfolio across multiple cell types and end-markets.
A solar panel is an assembly of photovoltaic cells designed to convert sunlight into direct current (DC) electricity through the photovoltaic effect. These cells are typically made from crystalline silicon wafers doped to create a p-n junction. Its primary purpose is electricity generation for a range of applications. Monocrystalline panels, known for higher efficiency ratings, dominate the premium residential and commercial segments. The utility-scale installation type represents the largest market segment by volume, driven by large-scale power purchase agreements.
Global policy frameworks are critical to market expansion, with the US Inflation Reduction Act (IRA) providing significant manufacturing tax credits. In parallel, the EU Green Deal and China's dual carbon goals create long-term demand certainty and support for renewable energy projects. Navigating divergent regional incentives and managing supply chain resilience for critical materials like polysilicon remain central strategic challenges for all manufacturers.
Market Dynamics
The global solar panel market's structure is defined by the tension between rapid technological advancement and geopolitical supply chain management. The transition to next-generation cell architectures is fragmenting the technology landscape, while demand is concentrating in key geographies with strong decarbonization policies.
Growth Catalysts
- Supportive Government Policies:The US Inflation Reduction Act (IRA) provides significant tax credits for domestic manufacturing, while China's dual carbon goals and the EU Green Deal create long-term demand certainty for utility-scale and distributed generation projects.
- Technology Efficiency Gains:Innovations in high-efficiency cell technologies, particularly TOPCon, are improving energy conversion rates. This allows for greater power output from a smaller footprint, which is critical for residential and commercial rooftop installations.
- Corporate Sustainability Mandates:A growing number of corporations are adopting aggressive renewable energy targets, driving demand for large-scale solar installations through power purchase agreements to offset their carbon emissions and improve their ESG ratings.
Market Restraints
- Input Material Volatility:The market's heavy reliance on polysilicon creates vulnerability to price fluctuations and supply disruptions, as production is heavily concentrated in specific regions of China, posing a geopolitical risk for global manufacturers.
- Grid Integration Hurdles:The intermittent nature of solar power generation requires significant investment in grid modernization and energy storage solutions. Delays in grid interconnection approvals can stall large-scale project development in many regions.
- Land Use and Permitting Conflicts:Utility-scale solar farms require large tracts of land, leading to conflicts with agricultural or conservation interests. Complex and lengthy permitting processes in jurisdictions across the United States and Europe act as a significant barrier.
Strategic Opportunities
- Building-Integrated Photovoltaics:The development of BIPV solutions, where solar cells are integrated into building materials like glass and roofing, opens new markets in urban construction and high-end architecture, moving beyond traditional panel installations.
- Agrivoltaics Systems:Co-locating solar installations on agricultural land to provide shade for crops and generate power presents a dual-use opportunity. This approach addresses land-use conflicts and creates value for the agricultural sector, especially in Europe and Japan.
- Green Hydrogen Production:Pairing large-scale solar farms with electrolyzers to produce green hydrogen offers a pathway to decarbonize heavy industry and transportation. This creates a new, large-volume demand segment for dedicated solar capacity.
Industry Challenges
- Skilled Labor Scarcity:A shortage of trained technicians and engineers for the installation, operation, and maintenance of solar facilities poses a significant operational bottleneck, particularly in markets experiencing rapid expansion.
- Recycling and End-of-Life Management:Establishing cost-effective and scalable recycling processes for decommissioned solar panels remains a major challenge. The lack of a mature circular economy for panel materials presents a future environmental and regulatory risk.
- Capital-Intensive Technology Transitions:The shift to next-generation cell technologies like HJT and TOPCon requires substantial capital investment in new manufacturing lines, creating a high barrier to entry and financial risk for smaller producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Market |
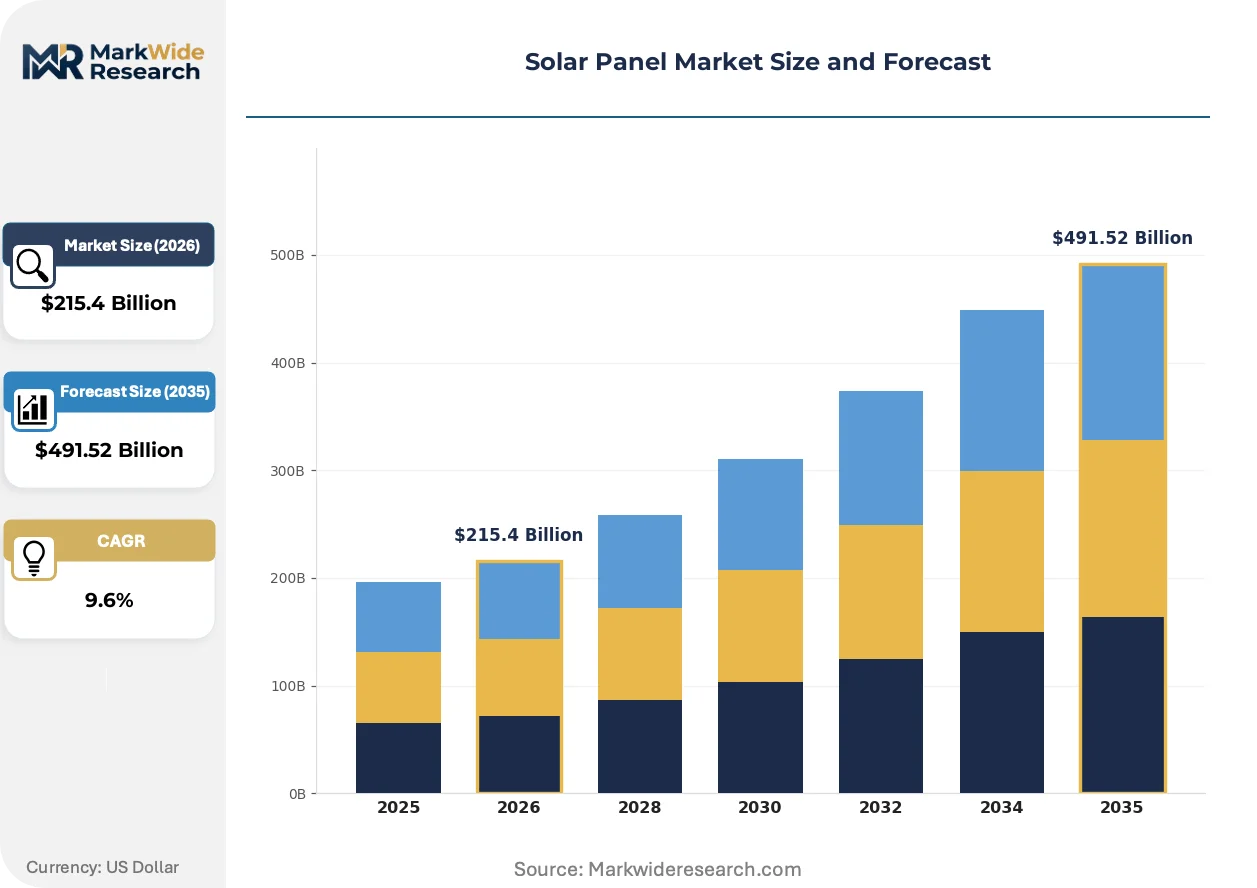
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $491.52 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Bifacial, Thin-Film Installation Type: Residential, Commercial, Industrial, Utility-Scale End User: Households, Businesses, Government Facilities, Educational Institutions Technology: Concentrated Photovoltaics, Photovoltaic Thermal, Integrated Photovoltaics, Smart Solar Panels |
| Companies Covered | JinkoSolar, JA Solar, Trina Solar, LONGi Green Energy, Tongwei Co., Ltd., Canadian Solar, First Solar, Waaree Energies, Hanwha Qcells, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Market Strategic Shifts & Innovations
The market's evolution is being defined by the industrialization of advanced cell technologies and the formalization of solar power as a mainstream energy asset class. This shift is reshaping supply chain dependencies and altering procurement models for large-scale energy buyers.
TOPCon, or tunnel oxide passivated contact, is a cell architecture that adds an ultra-thin layer of silicon dioxide to improve energy conversion efficiency over legacy PERC cells. Utility-scale developers and commercial installers are rapidly adopting this technology to maximize energy yield per unit of area. The aggressive scaling of TOPCon production is collapsing the cost premium that previously separated it from mainstream panel types.
Frameworks like the EU Green Deal establish binding targets for renewable energy deployment across member states. This policy creates durable, long-term demand for solar projects by setting clear national goals and providing mechanisms to streamline permitting for designated renewable energy zones. The commercial and industrial rooftop segment in countries like Germany and Poland is responding with accelerated installation rates to meet compliance and cost-saving objectives.
Corporate buyers are increasingly moving away from direct equipment purchases and toward sophisticated power purchase agreements (PPAs) for their energy needs. This procurement model shifts the focus from panel specifications to the guaranteed delivery of electricity at a fixed price over a long term. This pattern is most prominent in the data center and manufacturing verticals across North America and Europe.
Solar Panel Market Segmentation
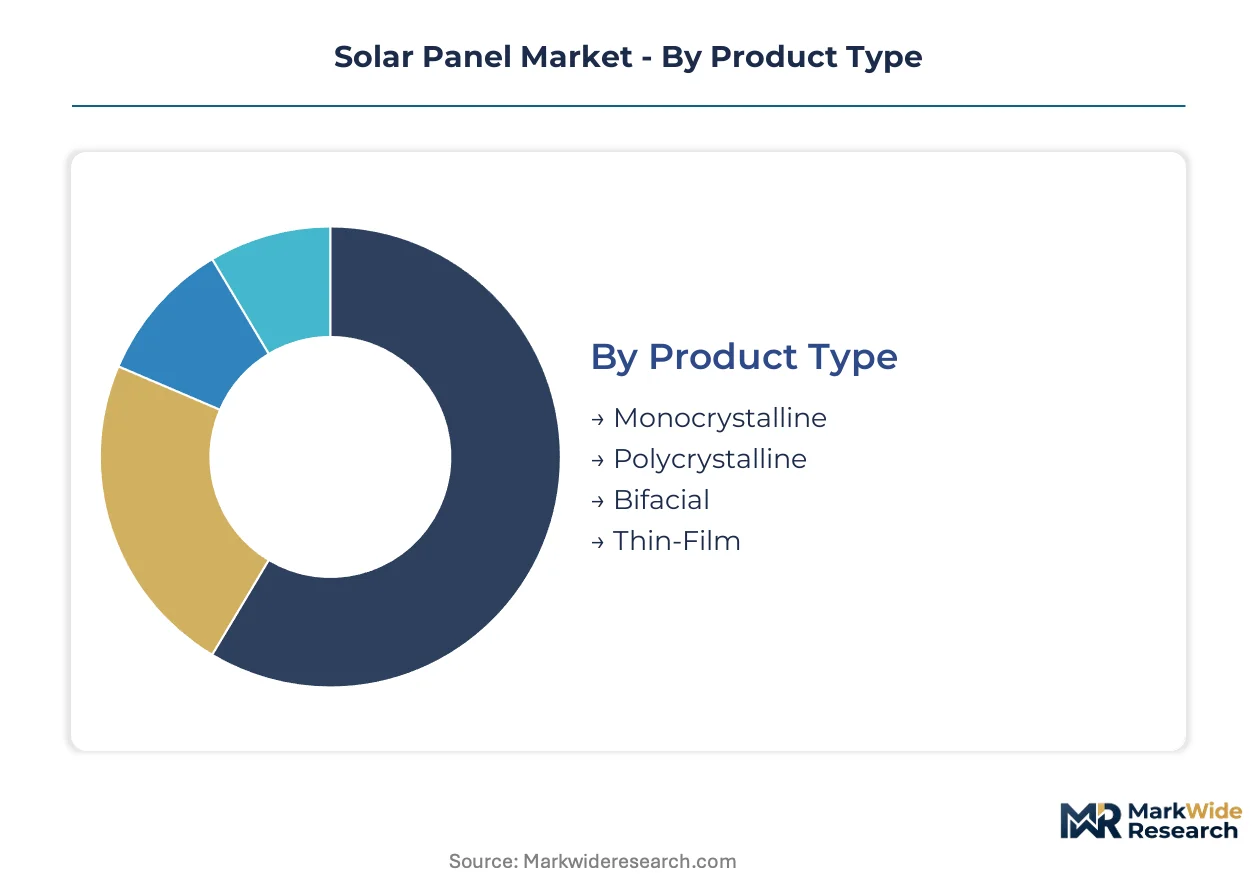
The solar panel market segments highlight the diverse applications and technological nuances driving energy transition. Understanding these distinct segments allows manufacturers to tailor product offerings and deployment strategies, addressing specific demands from residential rooftops to vast utility-scale projects. Each segment presents unique challenges and opportunities for innovation and market penetration.
Product Type:
The product type segmentation reveals a dynamic landscape where new technologies are rapidly displacing older ones, influencing the investment cycle for manufacturing facilities.
- Monocrystalline:These panels feature a single, continuous crystal structure, offering high efficiency and a sleek, uniform appearance. Demand for monocrystalline panels is concentrating in premium residential and commercial rooftop installations across Germany and the United States, where space constraints prioritize maximum power output per square meter.
- Polycrystalline:Composed of multiple silicon crystals, polycrystalline panels are generally less efficient but more cost-effective to produce. This product type finds significant application in large-scale solar farms in India and Brazil, balancing upfront cost with overall energy generation capacity for grid integration.
- Bifacial:Bifacial panels capture sunlight from both their front and rear sides, increasing energy yield by up to 30% compared to traditional panels. Utility-scale developers in China and Australia are increasingly deploying bifacial technology to optimize land use and enhance project economics.
- Thin-Film:Thin-film panels use ultra-thin layers of semiconductor materials like cadmium telluride (CdTe) or amorphous silicon, making them flexible and lightweight. Their distinct properties position them for niche applications such as building-integrated photovoltaics (BIPV) and portable power solutions.
Monocrystalline anchors the volume base while Bifacial gains share at the steepest rate.
Installation Type:
Installation type reflects the varied scales and regulatory environments that shape solar project development, from individual home systems to national energy infrastructure.
- Residential:These installations involve solar panels mounted on individual homes, typically ranging from 3 kW to 15 kW in capacity. Homeowners in California and Australia are increasingly adopting residential solar to reduce electricity bills and enhance energy independence, often supported by local incentive programs.
- Commercial:Commercial installations power businesses, schools, and public buildings, often utilizing larger rooftop arrays or ground-mounted systems. Enterprises in Japan and the Netherlands are installing commercial solar to meet corporate sustainability goals and achieve long-term operational cost savings.
- Industrial:Industrial solar projects serve manufacturing plants, warehouses, and other large industrial facilities, requiring robust and scalable energy solutions. Companies in Texas and the Middle East are leveraging industrial solar to power energy-intensive operations and mitigate exposure to volatile energy prices.
- Utility-Scale:Utility-scale projects are massive ground-mounted solar farms designed to feed electricity directly into the power grid, often exceeding hundreds of megawatts. These projects in Arizona and Spain secure long-term power purchase agreements with utilities, forming a critical component of national decarbonization strategies.
Utility-scale projects represent the largest market segment by volume, while residential installations are expanding most quickly in distributed generation capacity.
End User:
End user segmentation distinguishes the specific customer groups driving demand, each with unique procurement processes and motivations for adopting solar energy solutions.
- Households:Individual residential consumers constitute this segment, purchasing solar panels for personal electricity consumption and grid export. Households in Germany and the United Kingdom are motivated by energy bill savings and environmental concerns, often benefiting from feed-in tariffs.
- Businesses:Commercial and industrial enterprises fall into this category, deploying solar to power operations, reduce carbon footprints, and hedge against energy price volatility. Businesses across North America and Europe are increasingly signing power purchase agreements for large-scale solar projects.
- Government Facilities:This segment includes municipal buildings, military bases, and other public sector entities installing solar to achieve public sustainability mandates and reduce taxpayer-funded energy expenditures. Public sector bodies in Canada and South Korea are integrating solar into their infrastructure development plans.
- Educational Institutions:Universities, colleges, and K-12 schools utilize solar power to lower operating costs, provide educational opportunities, and demonstrate environmental leadership. Campuses in the United States and France are installing solar arrays as visible commitments to renewable energy.
Businesses drive the largest share of demand by value, with households representing a significant and consistent volume base.
Technology:
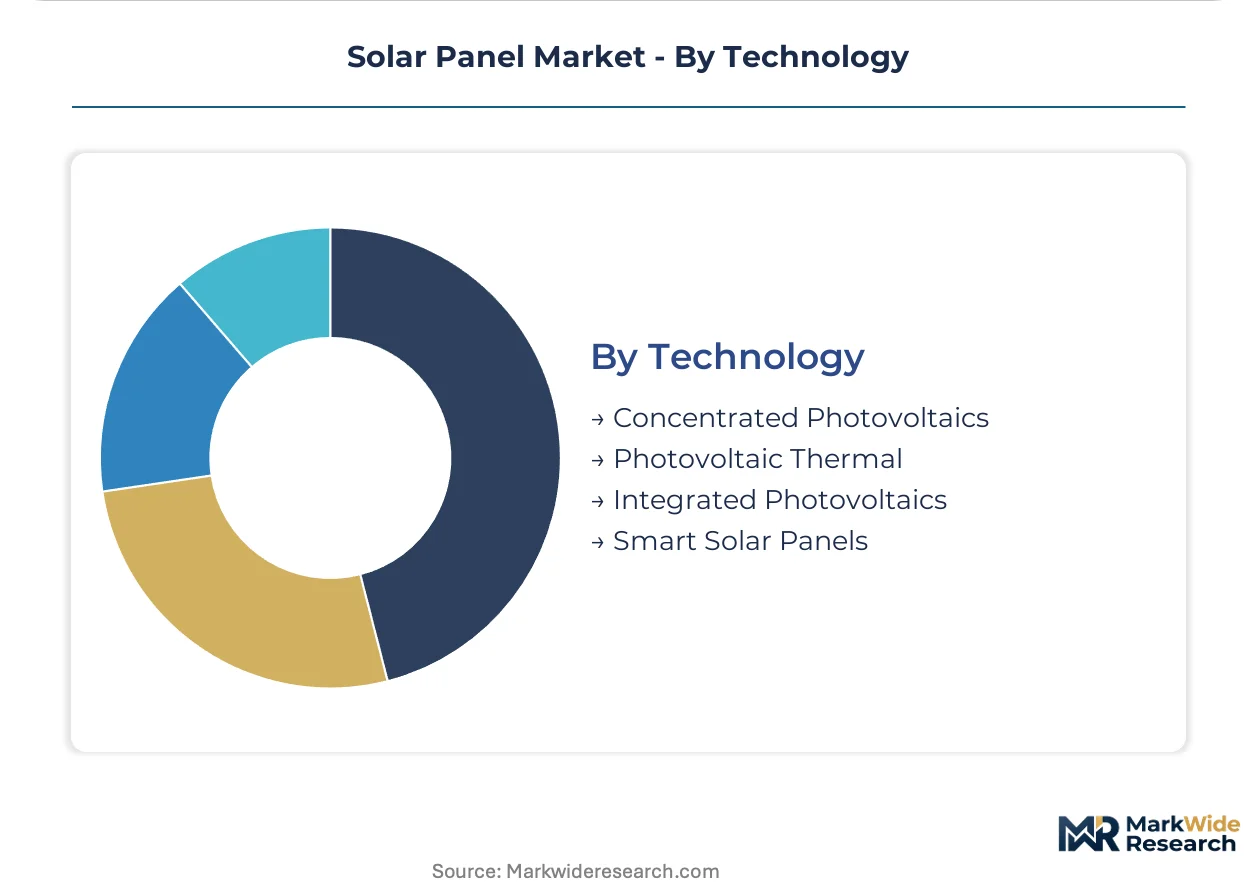
The technology segment reveals the innovation pathways in solar energy, from specialized light concentration to integrated smart grid functionalities.
- Concentrated Photovoltaics:CPV systems use lenses or mirrors to focus a large amount of sunlight onto small, highly efficient multi-junction solar cells. These systems are most effective in regions with high direct normal irradiance, such as deserts in the Middle East and North Africa, where they maximize energy capture.
- Photovoltaic Thermal:PVT systems combine solar photovoltaic and solar thermal technologies into a single integrated system, producing both electricity and heat simultaneously. This dual output makes PVT systems attractive for residential and commercial buildings in colder climates like Northern Europe, optimizing overall energy efficiency.
- Integrated Photovoltaics:Integrated photovoltaics refer to solar cells seamlessly incorporated into building materials, such as roof tiles, facades, or windows. This technology facilitates aesthetic integration and space optimization in urban environments, particularly in dense cities like Tokyo and Singapore.
- Smart Solar Panels:Smart solar panels incorporate embedded electronics, such as microinverters and optimizers, to monitor performance at the module level. These intelligent systems enhance energy yield, improve fault detection, and enable remote management for installations in complex environments.
Concentrated Photovoltaics addresses niche high-irradiance applications, while Smart Solar Panels are gaining traction for system optimization across diverse deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's aggressive scaling of solar panel manufacturing capacity drives significant exports to global markets, particularly to Europe and the United States. This export-driven model is fueling large-scale utility projects and distributed generation installations worldwide. Demand concentration in key geographies reflects strong decarbonization targets and supportive policy frameworks.
China
Domestic demand for solar panels in China is driven by ambitious dual carbon goals and large-scale renewable energy targets. The national energy administration supports massive solar farm development in western provinces, integrating with grid expansion plans. Manufacturing hubs in Jiangsu and Zhejiang provinces are scaling TOPCon production, securing global technology leadership.
United States
The US Inflation Reduction Act (IRA) provides substantial manufacturing tax credits, stimulating domestic solar panel production and deployment. Utility-scale projects across the Southwest, particularly in Arizona and California, secure long-term power purchase agreements. Federal land agencies streamline permitting for renewable energy zones, accelerating project timelines.
Germany
Germany's Energiewende policy drives strong demand for residential and commercial rooftop solar installations. The EU Green Deal establishes binding renewable energy targets, further supporting solar deployment across the country. Bavarian and Baden-Württemberg regions lead in distributed generation, responding to local energy independence initiatives.
India
India's national solar mission targets significant capacity additions, primarily for large-scale solar parks and agricultural applications. The PLI scheme (Production Linked Incentive) encourages domestic solar manufacturing, reducing reliance on imports. Rajasthan and Gujarat states are rapidly expanding utility-scale solar farms, leveraging high solar insolation.
Australia
Australia exhibits high residential solar penetration, driven by strong consumer interest in reducing electricity bills and abundant sunlight. State government incentives support battery storage integration with rooftop solar systems. New South Wales and Queensland are developing large-scale bifacial solar projects to optimize land use and energy yield.
Solar Panel Market Key Industry Players
Channel-controlling players compete with product-specialist players across the solar panel market, creating a tiered structure. The market exhibits a fragmented competitive landscape, with numerous manufacturers vying for market share. Strategic archetypes include integrated module producers, specialized cell technology developers, and regional project developers. Capacity expansion and technology licensing are dominant competitive moves.
On the scale-driven end, Chinese manufacturers such as JinkoSolar and LONGi Green Energy exemplify the rapid industrialization of advanced cell technologies. These companies anchor the volume base of the market, leveraging extensive manufacturing capabilities. First Solar, a US-based company, occupies a distinct position by specializing in thin-film cadmium telluride technology, offering an alternative to crystalline silicon panels.
| Leading Market Players |
|---|
| JinkoSolar |
| JA Solar |
| Trina Solar |
| LONGi Green Energy |
| Tongwei Co., Ltd. |
| Canadian Solar |
| First Solar |
| Waaree Energies |
| Hanwha Qcells |
| Others |
Cost & Logistics Intelligence
Polysilicon production, heavily concentrated in specific regions of China, influences global solar panel prices and manufacturer profitability. This supply concentration directly impacts pricing power across the entire value chain.
Pricing Analysis
The pricing gap between legacy PERC and next-generation TOPCon cells is rapidly collapsing. Contract-based long-term offtake agreements dominate utility-scale procurement, while residential installations often involve project-based pricing. Efficiency ratings and brand premium differentiate panel prices. Pricing softness stems from aggressive capacity expansion and technological advancements, making utility-scale developers highly price-sensitive compared to premium residential buyers.
Supply Chain Analysis
Polysilicon production, the foundational feedstock for solar panels, largely originates from China, creating significant upstream concentration. The supply chain further depends on silicon wafers, glass, and aluminum frames. Geopolitical risks and commodity price volatility for polysilicon pose a structural risk to manufacturers. Distribution runs through direct sales channels for utility-scale projects and regional distributor networks for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel market requires sophisticated manufacturing and project management capabilities. A scarcity of trained technicians and engineers for installation and maintenance creates an operational bottleneck across many regions.
For Market Incumbents:Build a technological moat through continuous investment in next-generation cell R&D, particularly TOPCon and HJT. Secure long-term polysilicon supply contracts to mitigate input material volatility, a significant threat from geopolitical risks. Leverage technology licensing agreements to expand market reach and accelerate innovation cycles. Vertical integration into energy storage solutions enhances product offerings.
For New Entrants and Emerging Players:Building-Integrated Photovoltaics (BIPV) in urban construction represents a high-value white space. Agrivoltaics systems in agricultural regions like Europe offer another dual-use opportunity. The residential rooftop segment in rapidly expanding distributed generation markets presents a penetrable entry point. Go-to-market strategies should emphasize partnerships with local construction firms and specialized installers.
For Investors and Strategic Acquirers:Capital is best deployed toward specialized cell technology developers or project developers with deep regional permitting expertise. The long-term viability over the next 5-10 years is secured by global decarbonization targets and policy support. Target acquisition profiles include companies with proprietary HJT or CdTe technologies. Watch grid integration policy advancements as a key inflection indicator for large-scale project development.
| Strategic Initiative | Industry Significance |
|---|---|
| TOPCon Manufacturing Scale-Up | This initiative secures technology leadership and meets the growing utility-scale demand for high-efficiency panels. |
| Agrivoltaics Project Development | Co-locating solar with agriculture addresses land-use conflicts and creates value for the agricultural sector. |
| Long-Term Power Purchase Agreements | These agreements provide demand certainty for large-scale solar farms, supporting national decarbonization strategies. |
| Skilled Workforce Development Programs | Addressing the scarcity of trained technicians ensures efficient installation and maintenance of solar facilities. |
| Circular Economy Recycling Investment | Developing scalable recycling processes mitigates future environmental risks from decommissioned solar panels. |
Research Approach
Initial hypotheses were tested against primary input from solar panel manufacturers, utility project developers, government energy officials, and residential installers. Secondary validation drew from IEA reports, EIA data, national energy administration statistics, and company financial filings. This approach combined bottom-up market sizing with top-down validation, ensuring robust data integrity.
The demand-supply-balance framework projected market evolution across the analysis window. Segmentation dimensions modeled included product type, installation type, end user, technology, and regional policy impacts. Compound annual growth rates were derived from historical trends and anticipated technology adoption curves. Decarbonization targets and new cell efficiency benchmarks served as critical forecast inputs.
Practitioners should monitor geopolitical trade policies and raw material supply disruptions for early signals of market shifts. Forecasts reflect assumptions about technology adoption and policy stability across the projection horizon. Cross-checking against IEA and national energy agency benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Asia-Pacific Solar Concentrator Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Building Integrated Photovoltaics Module Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
South America Solar PV Inverters Market