
 Europe Exhaust Heat Recovery System Market | 2026-2036
Europe Exhaust Heat Recovery System Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Exhaust Heat Recovery System Market Insights
Stainless steel is expanding its share in exhaust heat recovery system construction as manufacturers phase out lower-grade alloys vulnerable to thermal fatigue. Robert Bosch GmbH leverages its automotive thermal management heritage to compete in industrial heat exchanger applications. MAHLE GmbH anchors its position through specialized recuperator designs for power generation clients. Continental AG differentiates via integrated sensor-heat recovery modules that optimize real-time thermal efficiency.
An exhaust heat recovery system captures thermal energy from industrial flue gases, engine exhaust streams, and process off-gases through heat exchangers, boilers, or thermo-electric generators operating at temperatures typically ranging from 150°C to 600°C, then converts this waste heat into usable power, steam, or preheated combustion air. The technology reduces primary fuel consumption and carbon emissions across energy-intensive operations. Heat exchangers occupy the largest product category due to their deployment flexibility across manufacturing and power generation applications, while thermo-electric generators represent the fastest-growing segment as solid-state energy conversion gains traction in distributed power settings. Advanced technology configurations command premium positioning as end users prioritize systems with integrated controls and predictive maintenance capabilities.
The EU Green Deal and F-Gas Regulation establish binding emissions reduction trajectories that directly mandate waste heat recovery investments in covered industrial installations, while ECHA oversight of material safety standards shapes heat exchanger coating and sealing specifications. CE marking requirements under the MDR and machinery directives govern system certification pathways for cross-border equipment trade within the European Economic Area. Stakeholders must monitor evolving national transpositions of the EU Energy Efficiency Directive and assess how member-state incentive structures for industrial decarbonization will redirect procurement priorities across the value chain.
Market Dynamics
The EU Green Deal's binding emissions trajectories are forcing industrial operators across Germany, Poland, and Italy to retrofit existing plants with exhaust heat recovery infrastructure ahead of statutory deadlines, compressing procurement cycles and reshaping vendor qualification criteria.
Growth Catalysts
- EU Energy Efficiency Directive transposition:Member states are mandating waste heat audits in energy-intensive installations, creating compliance-driven procurement pipelines for heat exchanger and boiler systems.
- Steel sector decarbonization:Arc furnaces and rolling mills in Germany's Ruhr region are deploying recuperators to capture exhaust streams above 400°C, reducing Scope 1 emissions intensity.
- Nickel superalloy advances:Improved creep resistance at 600°C-plus operating temperatures is extending heat exchanger service intervals in cement and glass manufacturing.
Market Restraints
- Stainless steel price volatility:Nickel and molybdenum input costs fluctuate with LME trading patterns, squeezing fabrication margins for recuperator producers.
- Specialized welder scarcity:TIG and orbital welding certification for high-pressure heat exchanger joints concentrates qualified labor in northern Italy and western Germany.
- F-Gas Regulation retrofit friction:Existing refrigeration-integrated heat recovery systems face refrigerant phase-out timelines that accelerate capital write-offs.
Strategic Opportunities
- Polish industrial corridor expansion:Silesian steel and chemical clusters lack saturation in exhaust heat recovery deployment relative to German benchmarks, presenting first-mover installation contracts.
- CE marking digitalization:Electronic technical documentation and remote conformity assessment are compressing cross-border equipment approval timelines from months to weeks.
- Thermo-electric generator integration:Solid-state modules paired with conventional heat exchangers enable distributed power generation in off-grid manufacturing sites.
Industry Challenges
- Legacy DCS integration complexity:Heat recovery control systems must interface with decades-old distributed control architectures in established chemical plants, extending commissioning timelines.
- MDR certification backlog:Notified body capacity constraints for pressure equipment directive compliance are delaying market entry for new heat exchanger designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Exhaust Heat Recovery System Market |
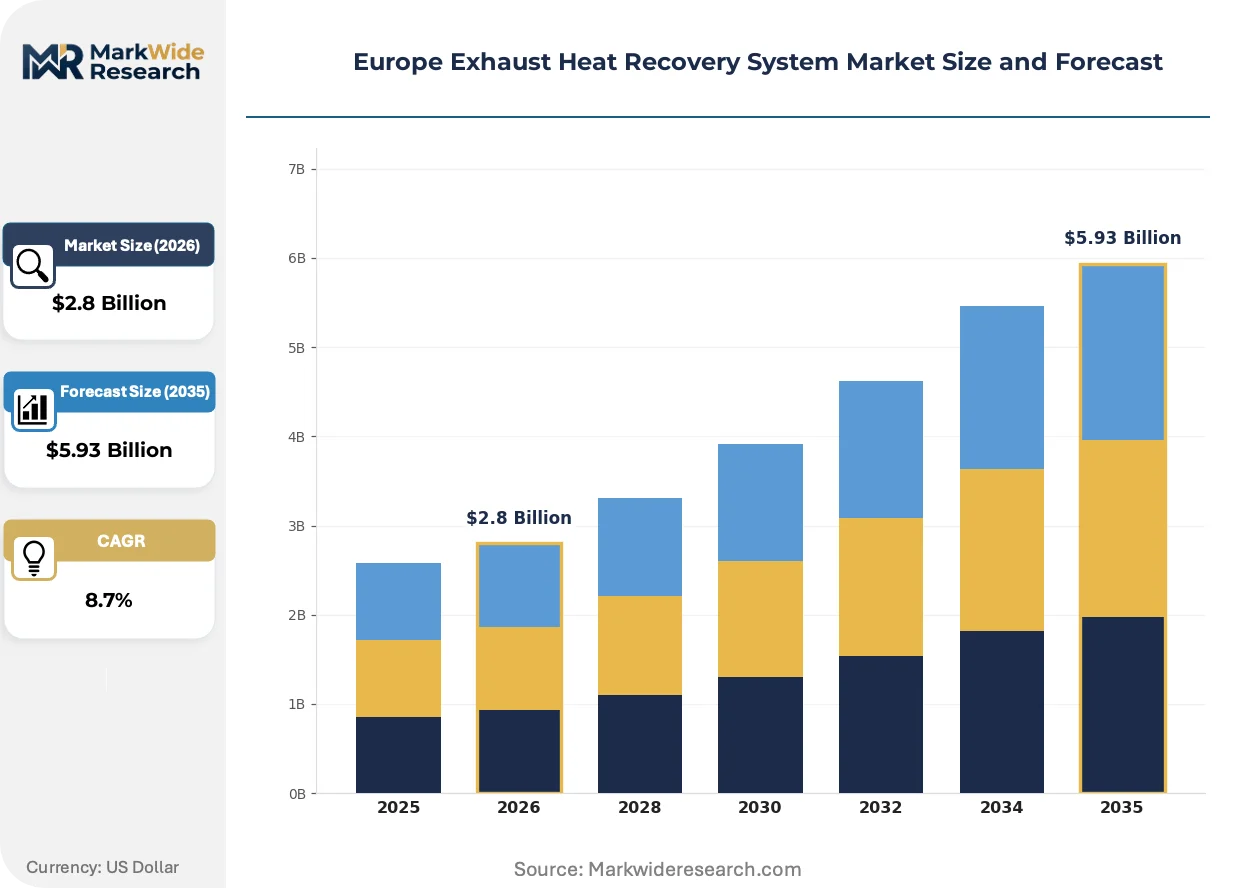
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Exchangers, Boilers, Thermo-Electric Generators, Recuperators Application: Industrial Processes, Power Generation, HVAC Systems, Food Processing End User: Manufacturing, Energy, Transportation, Hospitality Technology: Conventional, Advanced, Hybrid, Waste Heat Recovery |
| Companies Covered | General Electric, Robert Bosch GmbH, Climeon, MAHLE GmbH, Continental AG, Mitsubishi Heavy Industries, Cochran, Denso Corporation, Dürr Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Exhaust Heat Recovery System Market Trends and Innovations
Equipment specification is pivoting toward predictive-enabled architectures as end-users prioritize uptime guarantees over unit cost, while material science advances and regulatory digitization reshape competitive differentiation.
Additive manufacturing is absorbing complex heat exchanger geometries that conventional brazing cannot achieve, particularly in compact recuperators for marine and offshore power applications. Shipbuilders in Norway and the Netherlands are specifying topology-optimized core designs that reduce footprint by 30% while maintaining thermal duty. This capability is absorbing market share from stamped-sheet producers who lack electron beam melting capacity.
REACH authorization timelines for chromium(VI) surface treatments are forcing coating suppliers to accelerate plasma-sprayed ceramic alternatives for high-temperature corrosion protection. Heat exchanger fabricators in Belgium and France face 18-month qualification cycles for new barrier layers. The power generation segment is responding by consolidating procurement around vendors with pre-certified material libraries.
Energy service companies are capturing long-term heat recovery contracts through performance-guarantee structures that transfer operational risk from industrial operators to equipment providers. German chemical parks and Dutch refinery clusters are the primary adoption geographies, with contracts spanning 10-15 years and payments tied to verified thermal output. This model is displacing traditional capex purchase cycles in facilities with constrained balance sheets.
Europe Exhaust Heat Recovery System Market Segmentation
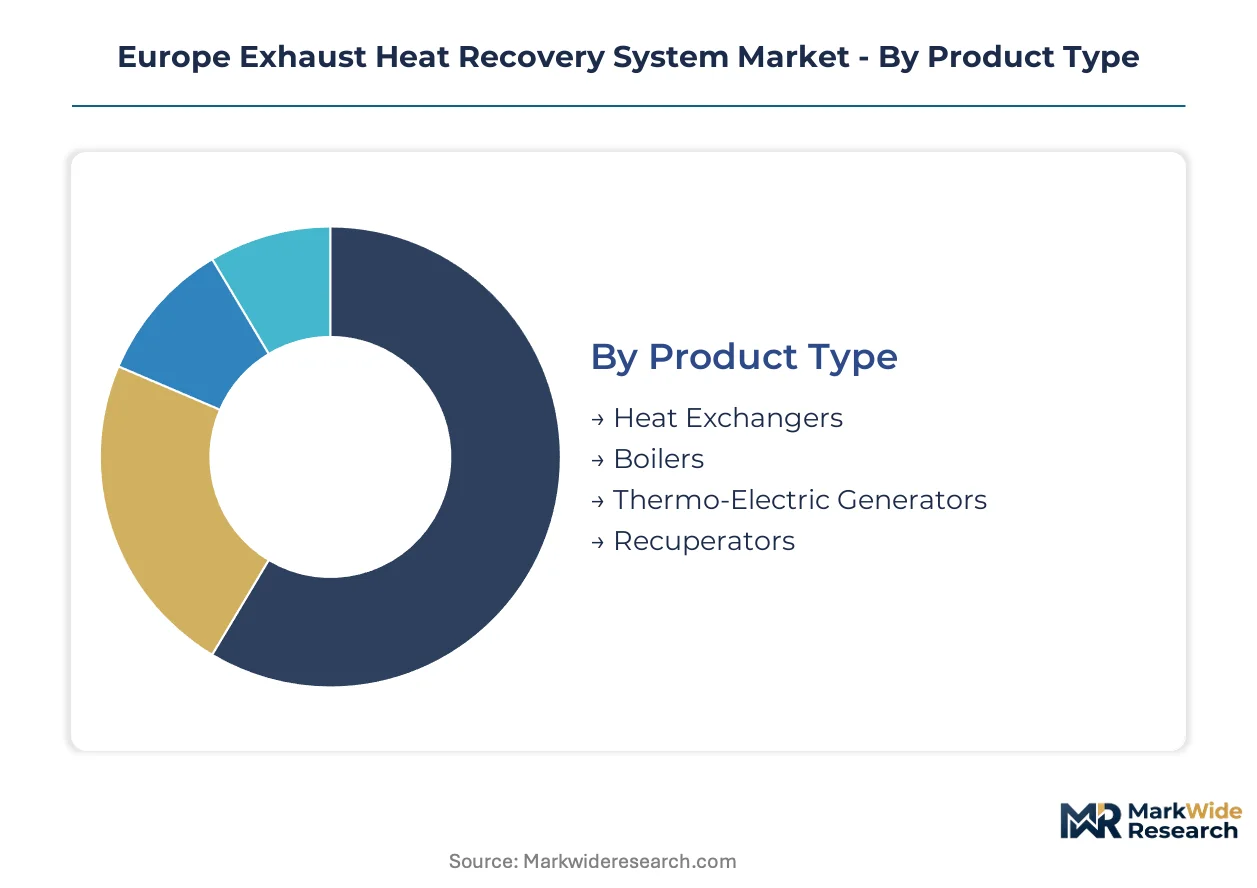
Equipment specification in exhaust heat recovery systems varies sharply by thermal duty, integration complexity, and regulatory exposure. Procurement decisions cluster around heat exchanger architectures for heavy industry, while emerging solid-state conversion technologies target distributed power applications.
Product Type:
Heat transfer surface geometry and operating temperature bands determine equipment selection across cement, steel, and chemical installations.
- Heat Exchangers:Shell-and-tube and plate-fin configurations dominate industrial flue gas applications, with surface areas engineered for 150°C to 600°C gas streams. German steel mills in the Ruhr corridor specify nickel-alloy tube bundles to withstand thermal cycling above 400°C under EU Green Deal emissions mandates.
- Thermo-Electric Generators:Solid-state bismuth telluride and skutterudite modules convert waste heat directly to electricity without moving parts, enabling off-grid deployment. Polish Silesian chemical clusters are piloting these systems for auxiliary power in distributed process units where steam infrastructure is absent.
- Boilers:Waste heat boilers generate saturated or superheated steam from exhaust streams above 300°C, common in combined cycle power plants.
- Recuperators:Metallic or ceramic regenerative heat exchangers preheat combustion air in high-temperature furnaces, reducing fuel input.
Mature deployment sits with heat exchangers. Newer deployment is concentrated in thermo-electric generators.
Application:
Process temperature profiles and integration feasibility shape adoption patterns across energy-intensive operations.
- Industrial Processes:Cement kilns, glass furnaces, and steel reheating operations generate continuous exhaust streams above 400°C suitable for recuperator installation. Italian ceramic tile manufacturers in the Sassuolo district are retrofitting roller kilns with exhaust heat recovery to meet national transpositions of the EU Energy Efficiency Directive.
- Power Generation:Combined cycle gas turbines and reciprocating engine plants deploy heat recovery steam generators to boost thermal efficiency. Dutch combined heat and power facilities along the Rotterdam-Antwerp corridor integrate exhaust boilers for district heating networks.
- HVAC Systems:Building-scale heat recovery ventilation captures thermal energy from exhaust air streams.
- Food Processing:Spray dryers and baking ovens utilize low-temperature heat exchangers for preheating combustion air or water.
Volume concentration rests with industrial processes. Technology differentiation is sharpest in power generation.
End User:
Capital intensity and emissions exposure drive procurement prioritization across sectoral boundaries.
- Manufacturing:Steel, cement, chemicals, and pulp and paper operations face binding emissions thresholds under EU Green Deal trajectories. Arc furnace operators in Poland's Upper Silesian Industrial District are accelerating heat exchanger procurement ahead of statutory compliance deadlines.
- Energy:Utilities and independent power producers deploy exhaust heat recovery to improve plant heat rates and extend asset life.
- Transportation:Marine engine builders in Norway specify compact recuperators for auxiliary power generation aboard offshore vessels.
- Hospitality:Hotels and commercial kitchens utilize small-scale heat recovery for domestic hot water preheating.
Procurement scale concentrates in manufacturing. Regulatory pressure is most acute in energy.
Technology:
Control system sophistication and predictive capability separate equipment tiers in vendor selection.
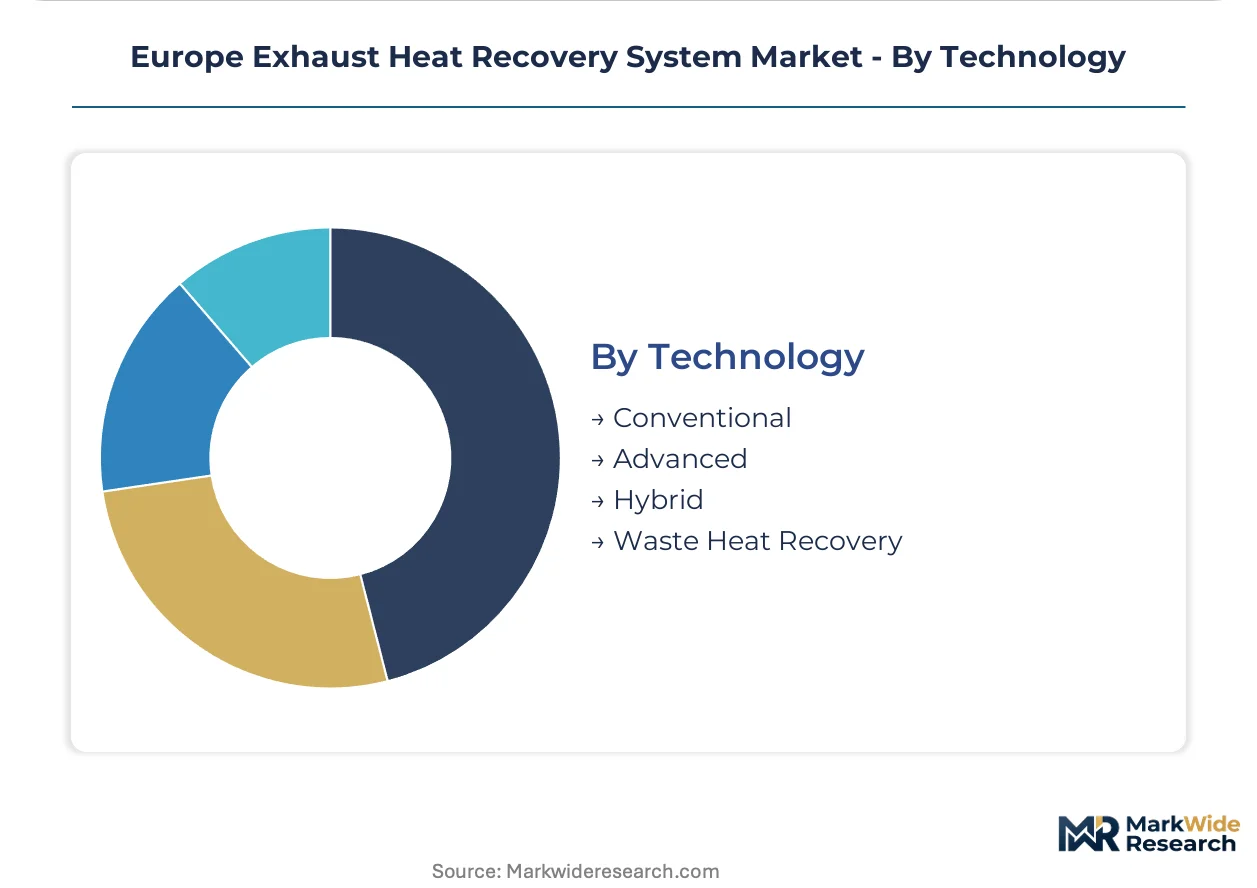
- Advanced:Sensor-integrated architectures with real-time thermal optimization and predictive maintenance algorithms command premium positioning. German chemical parks specify these configurations for 10-15 year performance contracts with energy service companies.
- Hybrid:Combinations of conventional heat exchangers with thermo-electric modules or organic Rankine cycle expanders target mid-size industrial facilities seeking incremental efficiency gains.
- Conventional:Static heat exchanger designs without integrated controls serve cost-sensitive retrofit applications.
- Waste Heat Recovery:Dedicated systems engineered specifically for exhaust stream capture, distinct from process-integrated heat recovery.
Margin expansion aligns with advanced configurations. Volume shipments favor conventional systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for exhaust heat recovery systems concentrates in Germany's industrial corridor, where steel and chemical installations face binding EU Green Deal compliance deadlines. Poland's Silesian basin and Italy's ceramic districts are emerging as secondary growth poles as national transpositions of the Energy Efficiency Directive tighten.
Germany
Ruhr steel mills and Lower Saxony chemical parks drive procurement of nickel-alloy recuperators for exhaust streams above 400°C. The EU Green Deal's emissions trajectories mandate retrofit timelines that compress vendor qualification cycles. Arc furnace operators in Duisburg and Dortmund are accelerating heat exchanger deployment ahead of statutory deadlines.
Poland
Upper Silesian steel clusters and chemical installations in the Katowice region generate concentrated demand for waste heat recovery infrastructure. National transpositions of the EU Energy Efficiency Directive mandate waste heat audits in energy-intensive facilities. Silesian industrial zones lack saturation relative to German benchmarks, creating first-mover installation opportunities.
Italy
Sassuolo ceramic tile manufacturers and Lombardy steel mills retrofit roller kilns and reheating furnaces with exhaust heat capture systems. The EU F-Gas Regulation shapes refrigerant-integrated heat recovery specifications for process cooling applications. Emilia-Romagna's ceramic district is deploying recuperators to meet national efficiency mandates.
Netherlands
Rotterdam-Antwerp corridor refineries and combined heat and power facilities integrate exhaust boilers for district heating networks. CE marking requirements under the Pressure Equipment Directive govern cross-border equipment trade within the European Economic Area. Dutch chemical parks are pioneering 10-15 year performance contracts with energy service companies.
France
Belgian and French heat exchanger fabricators face REACH authorization timelines for chromium(VI) surface treatments, accelerating plasma-sprayed ceramic alternatives. The EU Green Deal's binding emissions thresholds mandate waste heat recovery investments in covered industrial installations. Northern France's cement and glass manufacturing clusters are extending heat exchanger service intervals through nickel superalloy advances.
Europe Exhaust Heat Recovery System Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators scale electron beam melting capacity for topology-optimized heat exchanger cores. The vendor base stratifies across three tiers: diversified industrial conglomerates with thermal management heritage, specialized heat exchanger fabricators with certified material libraries, and additive manufacturing specialists serving marine and offshore niches. Strategic partnerships and technology licensing are displacing pure product sales as energy service companies capture long-term performance contracts.
Among diversified industrial groups, General Electric and Mitsubishi Heavy Industries occupy positions anchored in power generation equipment heritage. Robert Bosch GmbH and MAHLE GmbH represent the automotive-to-industrial thermal management archetype, leveraging sensor integration capabilities. Continental AG exemplifies the control-systems-integrated tier, while Climeon anchors the solid-state thermo-electric specialist segment. Cochran, Denso Corporation, and Dürr Group sit within specialized fabrication and process equipment tiers, with geographic origins reflecting concentrated industrial demand in their respective home markets.
| Leading Market Players |
|---|
| General Electric |
| Robert Bosch GmbH |
| Climeon |
| MAHLE GmbH |
| Continental AG |
| Mitsubishi Heavy Industries |
| Cochran |
| Denso Corporation |
| Dürr Group |
| Others |
Pricing and Supply Chain Analysis
Nickel and molybdenum alloy feedstock costs cascade through three distinct pricing tiers for exhaust heat recovery equipment, with German steel mills absorbing premium positioning for nickel-superalloy recuperators while Polish chemical clusters negotiate standard-grade stainless configurations and cost-sensitive Italian ceramic producers default to economy-tier static heat exchangers without predictive controls.
Pricing Analysis
Volume shipments cluster in conventional heat exchanger configurations where margin compression runs deepest, while advanced sensor-integrated systems with predictive maintenance algorithms capture expanded margins through 10-15 year performance contracts. Price differentiation hinges on CE marking tier under the Pressure Equipment Directive and nickel-alloy grade specification, with German Ruhr steel operators showing lowest price sensitivity due to EU Green Deal compliance deadlines and Polish Silesian installations exhibiting highest elasticity where national transpositions of the Energy Efficiency Directive remain partially implemented. Cost compression in standard-grade equipment is intensifying because stainless steel price volatility on LME trading patterns squeezes fabrication margins for recuperator producers serving mid-market chemical plants.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg anchor hub-and-spoke patterns for heat exchanger component logistics across the European Economic Area. Manufacturing concentration rests on Germany, Italy, and Belgium, with electron beam melting capacity for topology-optimized cores clustering in Dutch and Norwegian marine equipment corridors. Raw material dependencies draw from Indonesian nickel ore, South African chromium, and Chinese rare earth elements for thermo-electric generator modules. Single-source vulnerability concentrates in qualified TIG and orbital welding labor certified for high-pressure heat exchanger joints, with notified body capacity constraints under the MDR delaying market entry for new designs. Distribution runs through energy service companies capturing long-term performance contracts that displace traditional capex purchase cycles in Dutch and German chemical parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe exhaust heat recovery system market sits in a technology-transition phase as solid-state thermo-electric generators displace conventional steam-cycle equipment in distributed power applications across Polish Silesian chemical clusters and offshore Norwegian marine installations.
For Market Incumbents: Cement market position through backward integration into nickel-superalloy tube bundle supply and captive electron beam melting capacity for topology-optimized recuperator cores, defending against additive manufacturing specialists absorbing share in marine and offshore niches. Prioritize certification investment for plasma-sprayed ceramic barrier layers ahead of REACH authorization timelines for chromium(VI) surface treatments. For New Entrants and Emerging Players: The mid-tier pricing gap between premium German sensor-integrated systems and economy Italian static configurations offers white-space entry for hybrid thermo-electric heat exchanger combinations targeting Polish steel decarbonization mandates. Target Upper Silesian arc furnace retrofits ahead of statutory compliance deadlines through energy service company partnership structures rather than direct equipment sales. For Investors and Strategic Acquirers: Notified body MDR certification backlogs extending commissioning timelines is the leading indicator that consolidation opportunities exist among specialized heat exchanger fabricators with pre-certified material libraries and established CE marking pathways. Long-term viability favors vendors with integrated control-system capabilities and 10-15 year performance contract track records in Dutch and German chemical parks over pure fabrication plays exposed to stainless steel commodity cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Superalloy Supply | Captive sourcing of creep-resistant tube bundles secures margin expansion for 400°C-plus exhaust stream applications in German steel mills. |
| Additive Manufacturing Capacity Buildout | Electron beam melting for topology-optimized cores absorbs market share from stamped-sheet producers lacking marine certification. |
| Energy Service Company Partnership | Long-term performance contracts transfer operational risk from industrial operators to equipment providers in Dutch refinery clusters. |
| Plasma-Sprayed Ceramic Certification | Pre-qualified barrier layers accelerate procurement cycles as REACH timelines force coating supplier transitions. |
| Thermo-Electric Generator Integration | Solid-state modules paired with conventional heat exchangers enable off-grid deployment in Polish distributed process units. |
Research Methodology
EU Energy Efficiency Directive transposition documents, ECHA REACH authorization timelines, and national emissions audit records formed the secondary backbone, combined with primary interviews across plant engineers at German steel mills, procurement leads at Polish chemical installations, notified body certification officers, and energy service company contract managers. Bottom-up and top-down triangulation validated equipment shipment volumes and installation project pipelines.
The analytical lens weighted bottom-up project tracking of retrofit timelines against top-down emissions reduction trajectories mandated under EU Green Deal implementation across the analysis window. Segmentation dimensions modeled include product type architecture, application temperature band, end-user capital intensity, and technology control sophistication, with CAGRs derived from equipment replacement cycles compressed by statutory compliance deadlines and nickel-alloy service interval extensions.
Inputs from EEA member state regulatory filings and industrial emissions databases were available through the study window; gaps in early-stage thermo-electric generator pilot deployment data introduce uncertainty bands around solid-state adoption curves. Forecasts reflect documented assumptions regarding F-Gas Regulation retrofit friction and MDR certification capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management
Energy ESO Market
Energy Management
Heat Meter Market
Energy Management
European Building Energy Management Systems Market
Energy Management
Industrial Demand Response Management Systems Market
Energy Management
Connected Energy Market
Energy Management
Global Energy Consumption Market
Energy Management
Middle East and Africa Energy Management Systems Market
Energy Management
Europe Energy Management Systems Market
Energy Management
Electric Service Companies (Escos) Market
Energy Management
APAC Energy Management Systems (EMS) Market
Energy Management
Australia Energy-As-A-Service Market
Energy Management
Testing, Inspection, and Certification (TIC) in the Energy and Power Market
Energy Management
Global Utility Asset Management Market
Energy Management
Energy Management Market
Energy Management
Residential Demand Response Management Systems Market
Energy Management
South Korea Residential Heat Pump Market