
 South Korea Solar Energy Market | 2026-2036
South Korea Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Solar Energy Market Outlook
The gap between premium high-efficiency modules and commodity-grade panels is repositioning procurement strategies across South Korea's solar value chain. Hanwha Q Cells leverages its PERC and TOPCon cell technology to sustain margin premiums in the premium tier. SK E&S anchors its project development portfolio through integrated EPC capabilities and long-term power purchase agreements. Hansol Technics competes aggressively on cost in the standard module segment, dominating domestic distribution channels for price-sensitive commercial buyers.
South Korea solar energy encompasses photovoltaic power generation systems that convert sunlight into electricity through semiconductor-based cells, with crystalline silicon modules achieving conversion efficiencies between 20-24% in commercial deployment. The technology serves national decarbonization targets and industrial baseload substitution. Crystalline silicon technology leads installed capacity due to mature domestic supply chains and proven bankability. Bifacial modules represent the fastest-expanding technology category as Korean manufacturers exploit rear-side gain coefficients for utility-scale deployments. Energy storage systems command concentrated margin pools where lithium-ion integration with solar farms addresses grid stability mandates from Korea Electric Power Corp.
MFDS standards govern battery safety certification for co-located storage systems, while KEMCO efficiency regulations mandate minimum performance thresholds for modules eligible for national feed-in tariffs. The Green New Deal framework accelerates permitting for renewable zones, directly expanding addressable market access for developers. Stakeholders must track evolving land-use restrictions around agricultural zones and coastal areas where solar deployment faces competing regulatory priorities from the Ministry of Environment.
Market Dynamics
The bifacial module transition is compressing legacy PERC margins while concentrating procurement power among EPC-integrated developers who control land access and grid interconnection queues.
Growth Catalysts
- Renewable Portfolio Standard mandates:Industrial facilities face binding clean energy quotas that accelerate rooftop deployment timelines and expand addressable project volumes for domestic installers.
- Utility-scale clustering near KEPCO transmission nodes:Gyeongsang region infrastructure density reduces interconnection costs and attracts capital toward bankable project pipelines.
- TOPCon cell efficiency gains:Domestic manufacturing upgrades to tunnel oxide passivated contact architecture are narrowing the cost-per-watt gap with imported premium modules.
Market Restraints
- Polysilicon feedstock volatility:Raw material cost swings from Chinese smelter concentration transmit directly into Korean module assembler margins with limited hedging instruments.
- Land-use regulatory friction:Ministry of Environment restrictions on agricultural zone conversion and coastal development compress available siting options for greenfield projects.
- Grid absorption ceilings:KEPCO stability mandates limit solar penetration rates in Jeolla and Chungcheong provinces where renewable saturation approaches technical thresholds.
Strategic Opportunities
- Agrivoltaic deployment in Gangwon alpine zones:Dual-use solar installations on elevated structures enable agricultural coexistence while accessing untapped high-irradiance mountain terrain.
- Industrial park microgrid integration:Combined solar-plus-storage systems at Busan and Ulsan manufacturing complexes capture peak demand charge arbitrage under revised electricity tariff structures.
- Green New Deal permitting acceleration:Fast-track renewable zone designation in Saemangeum reclaimed land area unlocks gigawatt-scale development with streamlined environmental review timelines.
Industry Challenges
- MFDS battery certification bottlenecks:Co-located lithium-ion storage systems face extended safety testing timelines that delay project commercialization and strain developer working capital.
- Specialized EPC labor scarcity:Bifacial installation expertise and floating solar mooring engineering skills command wage premiums that inflate construction costs beyond original project pro formas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Solar Energy Market |
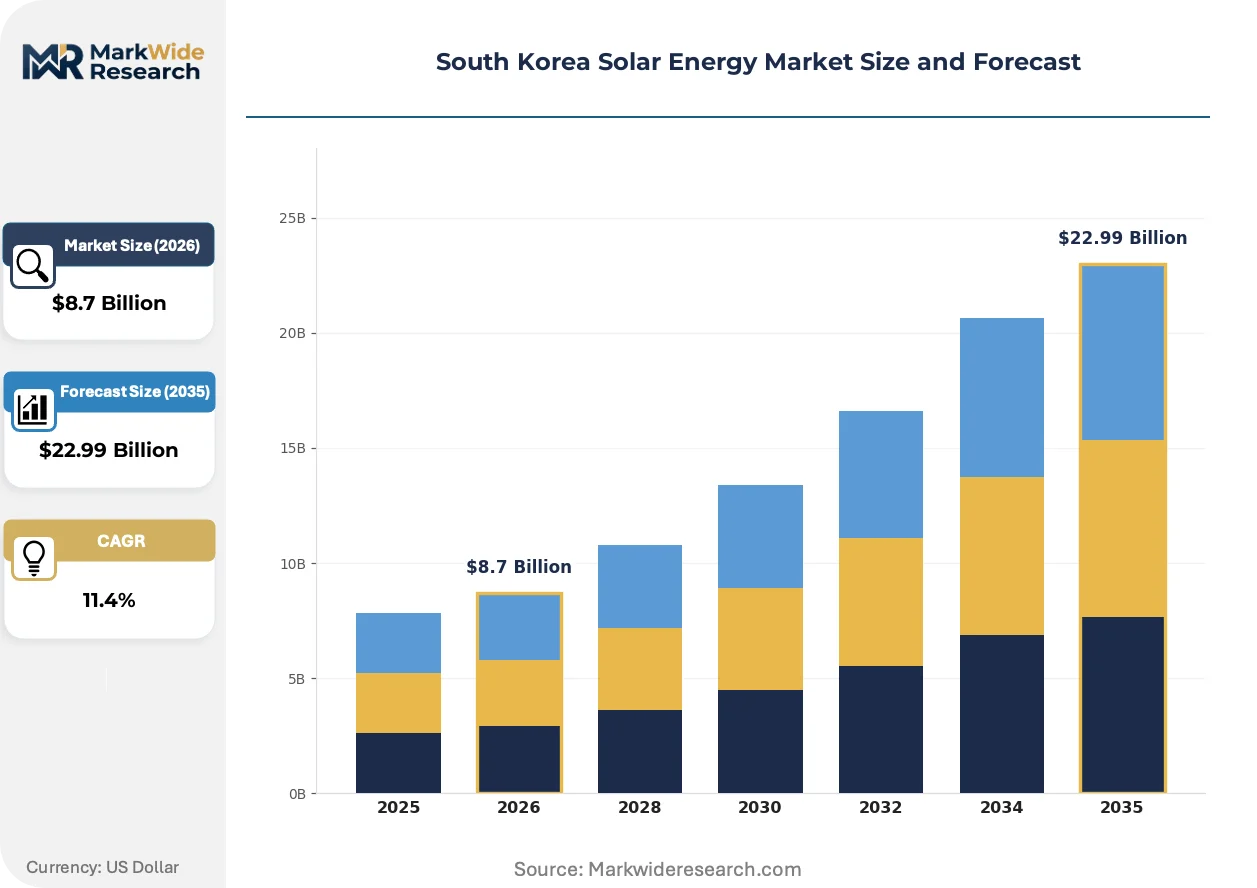
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Modules, Solar Inverters, Mounting Systems, Energy Storage Systems Application: Residential, Commercial, Utility-Scale, Off-Grid Technology: Thin-Film, Crystalline Silicon, Concentrated Solar Power, Bifacial Modules End User: Energy Providers, Municipalities, Industrial Facilities, Homeowners |
| Companies Covered | LS Electric Co. Ltd, SK E&S, Hanwha Q Cells, Korea Electric Power Corp., Hansol Technics Co., Ltd., S Energy Co. Ltd, OCI Holdings, Shinsegae Energy, Hyundai Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Solar Energy Market Strategic Shifts
Technology trajectories and procurement recalibrations are fragmenting the module supply base while elevating system-integration capabilities as the primary competitive differentiator.
Tunnel oxide passivated contact architecture is expanding into utility-scale procurement specifications as Korean developers prioritize energy yield density over upfront capital minimization. Major IPP offtakers now mandate bifacial gain coefficients in RFP technical evaluations, compressing demand for legacy monofacial inventory. This technology shift is expanding into project finance structures where higher DC/AC ratios and enhanced revenue modeling justify premium module procurement.
KEMCO efficiency threshold revisions are disqualifying sub-21% conversion modules from national feed-in tariff eligibility, forcing domestic distributors to purge aging inventory. The regulation compresses pricing power for standard-tier suppliers while accelerating factory retooling toward half-cut cell and multi-busbar architectures. Hansol Technics and mid-tier assemblers face the steepest compliance cost burden as their legacy equipment bases require capital-intensive upgrades.
Power purchase agreement tenor compression is reshaping developer risk allocation as offtakers resist 20-year commitments amid electricity market restructuring uncertainty. Industrial buyers in Gyeonggi and South Chungcheong provinces now prefer 7-10 year contracts with renewal options, transferring merchant price exposure back to project sponsors. This contractual evolution is most visible among petrochemical and semiconductor load facilities where procurement teams prioritize operational flexibility over long-term price certainty.
South Korea Solar Energy Market Segmentation
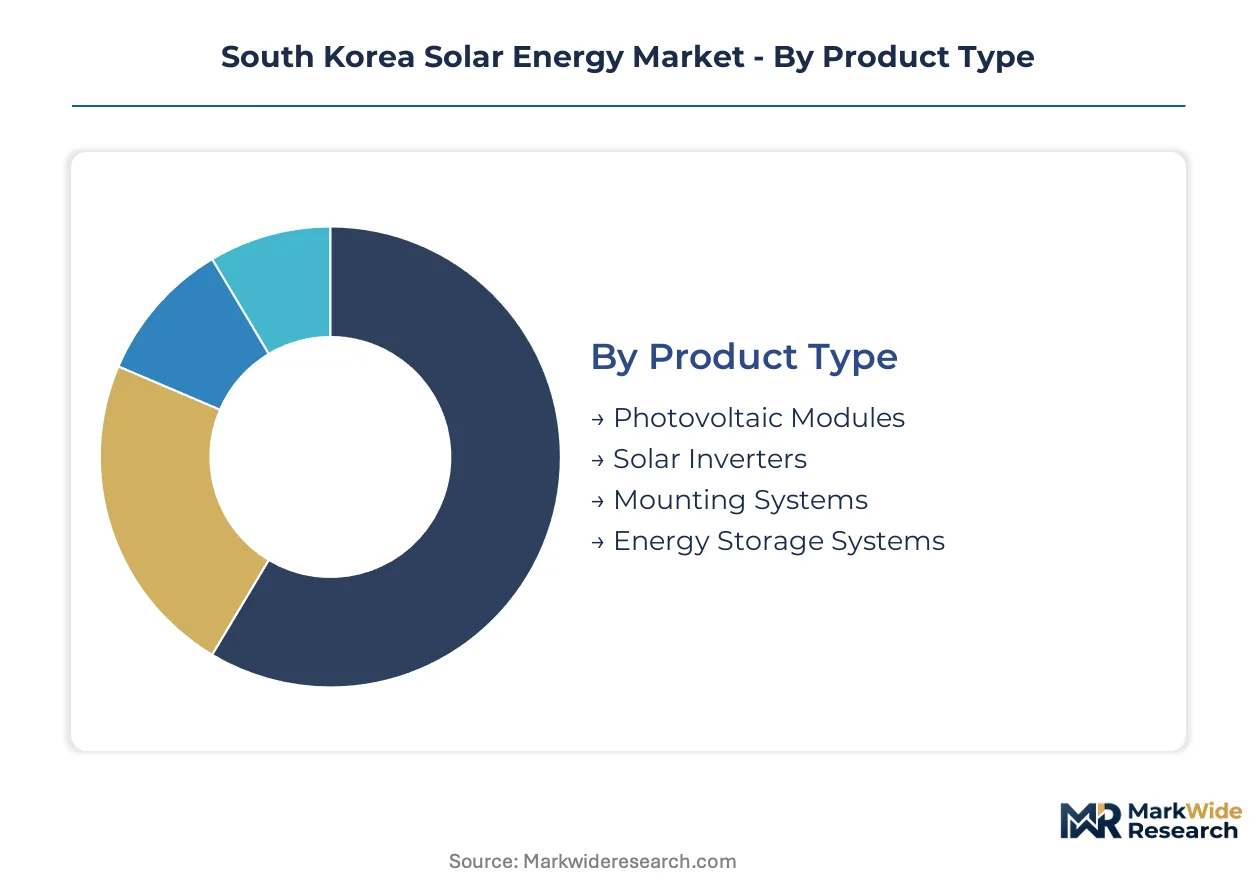
Technology heterogeneity across South Korea's solar value chain demands granular segmentation to isolate margin pools and procurement patterns. Each dimension reveals distinct competitive dynamics: module technology determines bankability for KEPCO interconnection, while end-user concentration shapes contract structures and tariff exposure.
Product Type:
Standalone hardware dominates utility-scale procurement, whereas embedded subsystems concentrate in distributed commercial installations where space constraints favor integrated designs.
- Photovoltaic Modules:Semiconductor-based panels converting sunlight to electricity through crystalline silicon or thin-film architectures. Gyeongsang utility-scale clusters specify bifacial configurations to exploit rear-side albedo gain near coastal and industrial surfaces. KEMCO efficiency mandates above 21% disqualify legacy inventory from feed-in tariff eligibility.
- Energy Storage Systems:Lithium-ion battery arrays co-located with solar farms to address grid stability mandates from Korea Electric Power Corp. Industrial park microgrids in Busan and Ulsan capture peak demand charge arbitrage under revised electricity tariff structures. MFDS certification timelines extend project commercialization schedules.
- Solar Inverters:Power electronics converting DC module output to grid-synchronous AC voltage.
- Mounting Systems:Structural frameworks securing panels to rooftops, ground arrays, or floating platforms.
Photovoltaic modules lead volumes today; energy storage systems are gaining share fastest.
Application:
Project scale determines capital access, with utility-scale developments tapping project finance while residential segments rely on retail lending and national subsidy programs.
- Utility-Scale:Ground-mounted solar farms exceeding 100 MW capacity feeding directly into KEPCO transmission infrastructure. Saemangeum reclaimed land area attracts gigawatt-scale development under Green New Deal fast-track permitting. Land-use restrictions from the Ministry of Environment compress available greenfield siting options.
- Commercial:Rooftop and carport installations serving industrial facilities, retail complexes, and logistics centers. Renewable Portfolio Standard binding quotas accelerate deployment timelines across Gyeonggi and South Chungcheong manufacturing bases. Power purchase agreement tenors compress to 7-10 years with renewal options.
- Residential:Distributed rooftop systems serving single-family homes and multi-unit dwellings.
- Off-Grid:Standalone solar-plus-storage systems operating without KEPCO interconnection.
Utility-scale deployments anchor installed capacity; commercial applications show the steepest expansion trajectory.
Technology:
Cell architecture choices bifurcate the supply base between premium efficiency leaders and cost-optimized assemblers.
- Crystalline Silicon:Mature photovoltaic technology employing monocrystalline or polycrystalline silicon wafers achieving 20-24% commercial conversion efficiency. Domestic supply chain maturity supports proven bankability for project finance. Tunnel oxide passivated contact upgrades narrow cost-per-watt gaps with imported premium modules.
- Bifacial Modules:Double-sided panels harvesting direct and reflected irradiance through transparent rear-side encapsulation. Major IPP offtakers now mandate bifacial gain coefficients in RFP technical evaluations. This technology is displacing legacy monofacial inventory from utility-scale procurement pipelines.
- Thin-Film:Cadmium telluride or copper indium gallium selenide semiconductor layers deposited on glass substrates.
- Concentrated Solar Power:Thermal generation systems using mirrors to focus sunlight for steam turbine operation.
Crystalline silicon dominates installed base; bifacial modules are climbing the fastest.
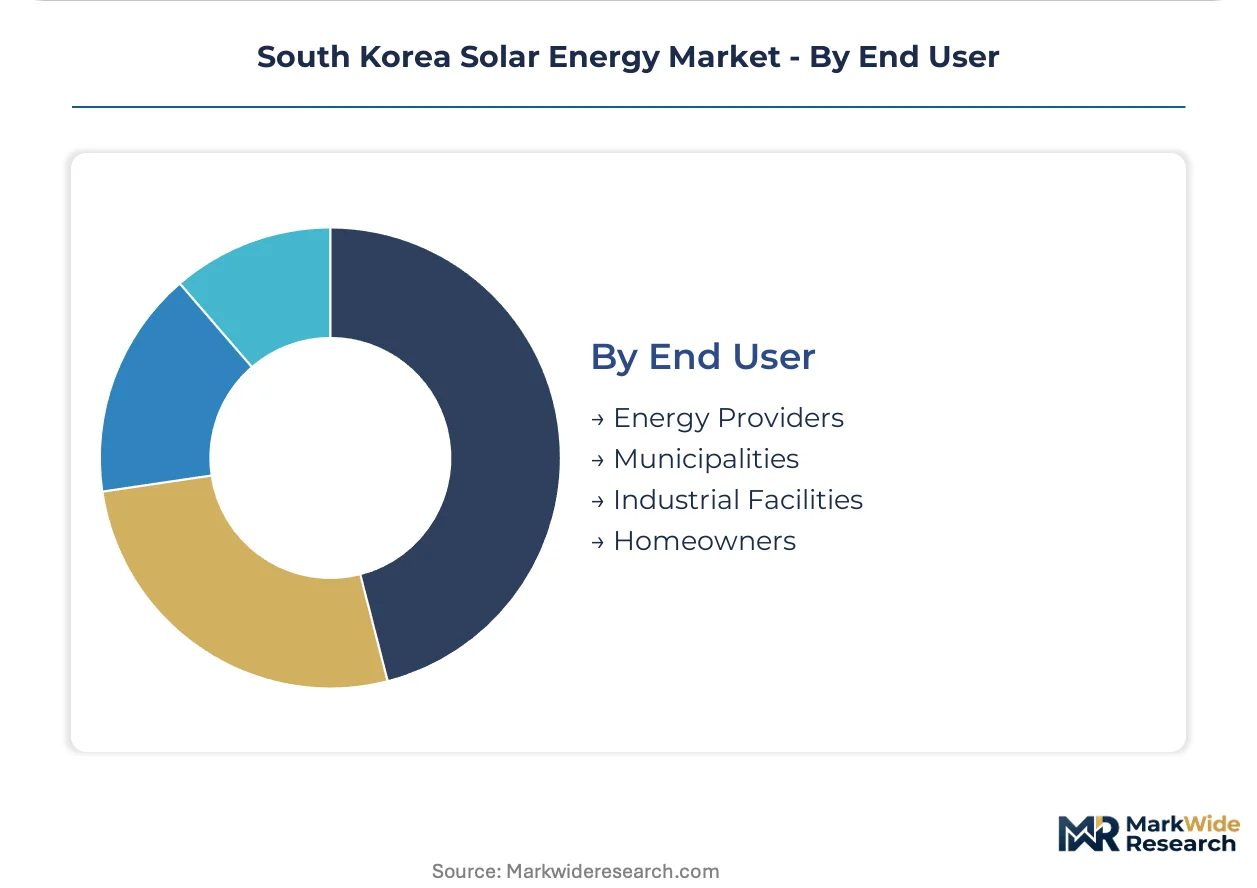
End User:
Procurement sophistication varies sharply: energy providers negotiate long-term offtake structures while homeowners depend on installer recommendations and national incentive alignment.
- Industrial Facilities:Petrochemical, semiconductor, and steel manufacturing complexes sourcing solar for baseload substitution and Renewable Portfolio Standard compliance. Procurement teams prioritize operational flexibility over long-term price certainty amid electricity market restructuring uncertainty. Combined solar-plus-storage systems target peak demand charge reduction.
- Energy Providers:Independent power producers and KEPCO-affiliated generation companies developing utility-scale project pipelines. Control over land access and grid interconnection queues concentrates procurement power among EPC-integrated developers. Enhanced revenue modeling justifies premium module procurement with higher DC/AC ratios.
- Municipalities:Local government entities deploying solar on public buildings and waste treatment facilities.
- Homeowners:Residential consumers purchasing systems through installer networks and national subsidy programs.
Industrial facilities lead current demand; energy providers are expanding their share most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's photovoltaic workforce clusters around Gyeongsang manufacturing belts and Seoul Capital Area R&D centers, with specialized EPC talent commanding wage premiums in bifacial installation and floating solar mooring engineering.
Gyeongsang Region
Utility-scale developers exploit high irradiance and KEPCO transmission density near Daegu and Pohang. The Green New Deal fast-tracks permitting for renewable zones in this southeastern corridor. Gimhae and Changwon host module assembly operations feeding domestic project pipelines.
Seoul Capital Area
Corporate procurement teams in Seoul and Incheon negotiate compressed PPA tenors under electricity market restructuring uncertainty. KEMCO efficiency regulations above 21% disqualify aging inventory from national feed-in tariffs. Pangyo tech corridors drive demand for integrated solar-plus-storage microgrids.
Busan-Ulsan Industrial Belt
Petrochemical and steel complexes source bifacial configurations for baseload substitution under Renewable Portfolio Standard mandates. MFDS battery safety certification extends timelines for co-located lithium-ion storage commercialization. Onsan and Ulsan harbors anchor floating solar pilot projects.
Gangwon Alpine Zone
Agrivoltaic installations on elevated structures enable agricultural coexistence while accessing untapped mountain terrain. Ministry of Environment land-use restrictions compress greenfield siting options elsewhere, redirecting capital toward dual-use deployment. Wonju and Gangneung emerge as testbeds for elevated tracking systems.
Saemangeum Reclaimed Land
Gigawatt-scale development accelerates under streamlined environmental review timelines for the southwestern coastal zone. Grid absorption ceilings in Jeolla province limit penetration rates, concentrating interconnection investment here. Buan and Gunsan anchor the nation's largest contiguous solar development pipeline.
South Korea Solar Energy Market Competitive Environment
Top-tier vendors anchor premium module supply, while mid-tier assemblers compete on cost in standard segments. Domestic manufacturing upgrades to tunnel oxide passivated contact architecture are narrowing efficiency gaps with imported alternatives. Three archetypes dominate: integrated energy conglomerates with captive project pipelines, pure-play module specialists leveraging distribution scale, and polysilicon feedstock suppliers backward-integrated into wafer production. Capacity expansion and strategic EPC partnerships constitute the dominant competitive moves.
Among Korea-based integrated energy groups, Hanwha Q Cells, SK E&S, and LS Electric Co. Ltd occupy positions spanning module manufacturing through project development. Hanwha Q Cells exemplifies premium-tier positioning through advanced cell architecture specialization. SK E&S anchors utility-scale origination through integrated development capabilities. LS Electric Co. Ltd represents industrial electrification incumbents extending into renewable EPC and grid infrastructure.
| Leading Market Players |
|---|
| LS Electric Co. Ltd |
| SK E&S |
| Hanwha Q Cells |
| Korea Electric Power Corp. |
| Hansol Technics Co., Ltd. |
| S Energy Co. Ltd |
| OCI Holdings |
| Shinsegae Energy |
| Hyundai Corporation |
| Others |
Value Chain & Pricing Dynamics
KEMCO efficiency mandates above 21% conversion thresholds gate qualified supply access and concentrate premium-tier pricing power among certified domestic manufacturers. These regulatory floors bifurcate procurement pools, forcing distributors to purge substandard inventory while certified module assemblers command margin premiums.
Pricing Analysis
Bundled EPC-plus-module contracts dominate utility-scale procurement, while unbundled hardware transactions concentrate in commercial rooftop segments where installers optimize component mix independently. Pricing stratifies across premium, standard, and economy tiers based on cell architecture sophistication and KEMCO certification status. Cost compression in standard-tier modules intensifies as Hansol Technics and mid-tier assemblers compete for price-sensitive commercial buyers. Industrial facilities in Gyeonggi province exhibit lowest price sensitivity, prioritizing operational flexibility and long-term reliability over upfront capital minimization.
Supply Chain Analysis
Workforce scarcity for bifacial installation expertise and floating solar mooring engineering in Gimhae and Changwon manufacturing belts inflates construction costs beyond original project pro formas. Polysilicon feedstock draws from Chinese smelter concentration, while lithium-ion cell supply rests on South Korean and Japanese manufacturing bases. Single-source vulnerability in polysilicon procurement transmits raw material cost volatility directly into domestic module assembler margins. Distribution runs through EPC-integrated developers who control land access and grid interconnection queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea solar energy functions as a stable compounder where Renewable Portfolio Standard mandates institutionalize demand visibility across industrial procurement cycles.
For Market Incumbents: Acquire specialized EPC labor pools in bifacial installation and floating solar engineering to lock in execution capacity before wage premiums escalate further. Secure backward integration into polysilicon procurement or long-term supply agreements to hedge against Chinese smelter concentration risk. Defend margin position by accelerating tunnel oxide passivated contact retooling ahead of KEMCO threshold revisions that disqualify legacy inventory. For New Entrants and Emerging Players: Green New Deal fast-track permitting in Saemangeum reclaimed land area opens a window for gigawatt-scale project origination with streamlined environmental review timelines. Target agrivoltaic deployment in Gangwon alpine zones where Ministry of Environment land-use restrictions redirect capital toward dual-use installations. Establish EPC partnerships with industrial park operators in Busan and Ulsan to capture solar-plus-storage microgrid integration demand under revised electricity tariff structures. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier module assemblers because KEMCO efficiency mandates are forcing capital-intensive upgrades that strain standalone balance sheets. Five-to-ten year viability hinges on successful technology transition to half-cut cell and multi-busbar architectures. Watch for MFDS battery certification timeline compression as the inflection signal indicating co-located storage project financeability improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands addressable project pipeline under Green New Deal fast-track renewable zone designation. |
| Power Purchase Agreement | Locks in offtake revenue for utility-scale developments near KEPCO transmission infrastructure in Gyeongsang. |
| Technology Licensing | Accelerates domestic manufacturing upgrade to tunnel oxide passivated contact cell architecture. |
| Vertical Integration into Storage | Captures concentrated margin pools where lithium-ion integration addresses KEPCO grid stability mandates. |
| Green Certification Program | Secures KEMCO eligibility above 21% efficiency threshold for national feed-in tariff access. |
Study Parameters
Multiple input streams — primary interviews with IPP project developers and EPC contractors, secondary validation through KEPCO interconnection databases and KEMCO efficiency filings, and customs data on polysilicon import flows — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations included utility planning officers, grid operators, module procurement leads at industrial facilities, and MFDS certification specialists. Secondary sources encompassed FERC-equivalent Korean regulatory filings, IEA renewable energy reports, and project development pipeline databases.
Historical capacity deployment patterns were cross-referenced against panel input from industry participants to construct the analytical framework across the projection horizon. Segmentation dimensions modeled include module technology tier, project scale category, end-user archetype, and regional grid absorption capacity. CAGRs were derived from installed capacity buildout trajectories, technology substitution curves for bifacial module penetration, and feed-in tariff eligibility adjustments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polysilicon price volatility, MFDS certification timeline extensions, or Ministry of Environment land-use restriction tightening. Forecasts reflect documented assumptions regarding KEPCO grid absorption ceilings and Green New Deal permitting velocity. Material deviation in Renewable Portfolio Standard enforcement intensity or KEMCO threshold revision timing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Solar Shed Light Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Grid Connected PV Systems Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar Software Market
Solar Power Systems
Mexico Solar Photovoltaic (PV) Market