
 Australia Solar Market | 2026-2036
Australia Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Solar Market Insights
The utility-scale procurement channel is reconfiguring as developers bundle solar generation with battery storage to secure long-term offtake contracts. JinkoSolar anchors its position through module supply agreements with Australian project developers, while Fronius differentiates via inverter system integration tailored to harsh climate conditions. LONGi Green Energy leverages its monocrystalline wafer scale to compete on cost-per-watt across commercial and utility segments.
Australia solar encompasses photovoltaic energy systems that convert sunlight into electricity through semiconductor cells, typically silicon-based modules rated between 400 and 700 watts under standard test conditions, deployed to offset grid consumption or export power through net metering arrangements. Photovoltaic panels dominate installed capacity, though batteries represent the fastest-expanding product category as households and utilities pursue energy independence. The utility-scale application segment leads capital deployment, while residential installations sustain volume through rooftop mandates in new building codes across multiple states.
The Clean Energy Council administers product accreditation that determines eligibility for federal small-scale technology certificates, while state regulators including the Essential Services Commission of Victoria and IPART in New South Wales set feed-in tariff structures that shape residential payback periods. The Australian Energy Market Commission continues revising network connection standards to accommodate distributed energy resource penetration. Stakeholders must track evolving grid access protocols and storage co-location requirements as the market transitions from subsidy-dependent deployment to merchant and corporate PPA-driven investment.
Market Dynamics
Grid-scale battery co-location is forcing solar developers to reconfigure project economics around firm capacity contracts rather than energy-only revenue streams. This structural shift is compressing development timelines and reshaping equipment procurement priorities across the National Electricity Market.
Growth Catalysts
- Queensland Renewable Energy Zones:State government-designated solar corridors with streamlined planning approvals are unlocking transmission-constrained project pipelines in the state's north.
- Small-scale Technology Certificates:Federal accreditation administered by the Clean Energy Council sustains residential payback periods through upfront capital offsets on rooftop installations.
- Corporate Power Purchase Agreements:Mining and data center operators are contracting directly with solar-battery hybrids to hedge against volatile wholesale electricity prices.
Market Restraints
- Polysilicon Supply Concentration:Australian developers remain exposed to Chinese polysilicon processing bottlenecks that amplify module price volatility and contract renegotiation risk.
- Network Connection Queues:The Australian Energy Market Commission's revised connection standards have lengthened technical assessment timelines for utility-scale projects seeking grid access.
- Distribution Network Hosting Capacity:Essential Energy and Ausgrid face physical constraints integrating distributed solar exports during midday generation peaks, triggering export curtailment protocols.
Strategic Opportunities
- Agrivoltaics in New South Wales:Dual-use solar installations on grazing land are qualifying for regional development grants while diversifying landholder revenue streams.
- Virtual Power Plant Aggregation:Tesla and Sonnen are enrolling residential battery systems into dispatchable capacity markets, creating new software-layer revenue pools.
- Green Hydrogen Offtake:The Hydrogen Headstart program is catalyzing electrolyzer-solar coupling in the Pilbara and Gladstone hydrogen hubs.
Industry Challenges
- Electrical Trades Shortage:Master Electricians Australia reports insufficient accredited installers to meet rooftop demand surges in Victoria and South Australia.
- Integrated Resource Plan Alignment:Developers must synchronize solar commissioning with transmission augmentation timelines that span multiple regulatory approval cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Solar Market |
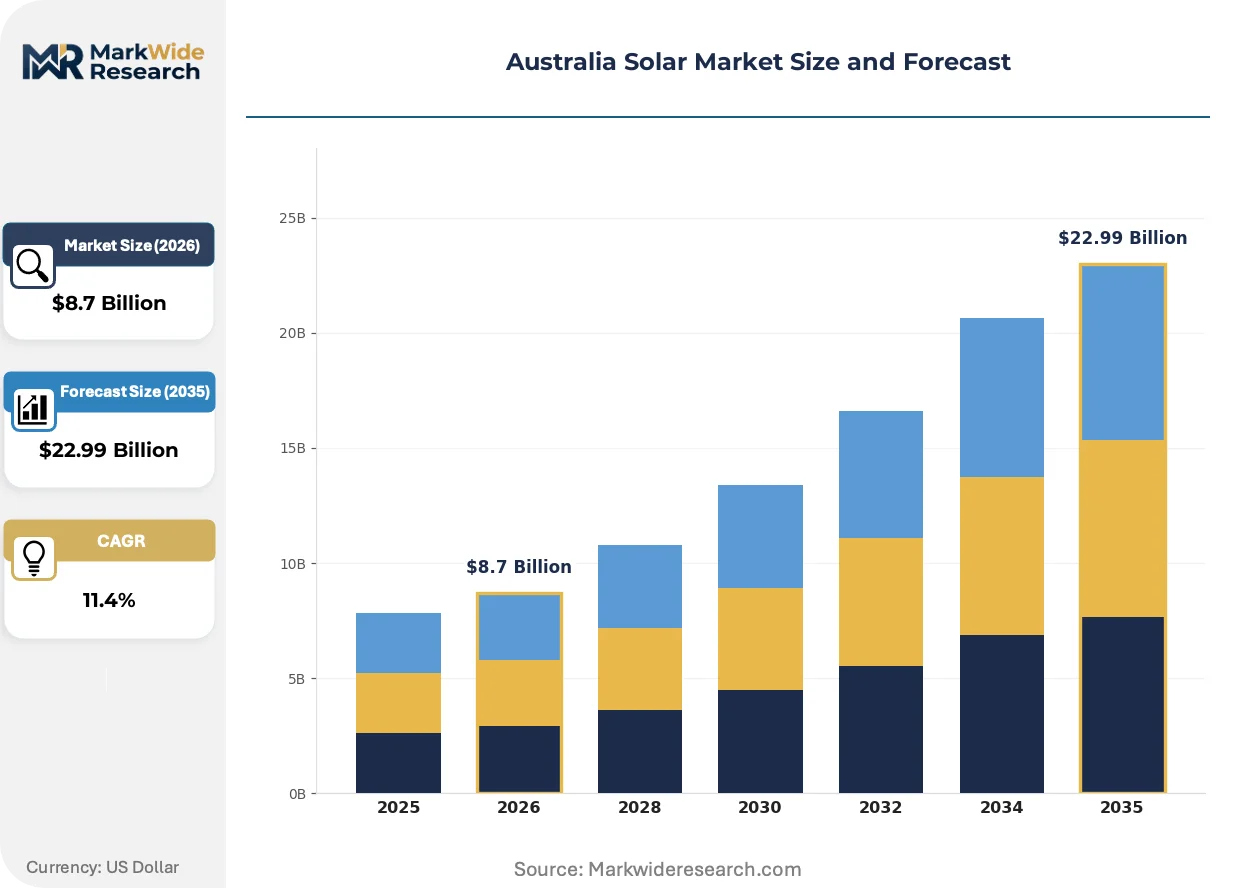
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Mounting Systems, Batteries Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial Application: Residential, Commercial, Industrial, Utility Scale Distribution Channel: Direct Sales, Retail, Online, Wholesale |
| Companies Covered | Trina Solar, JinkoSolar, LONGi Green Energy, Canadian Solar, Tindo Solar, Fronius, Sungrow, Enphase Energy Australia, Redback Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Solar Market Trends and Innovations
Bifacial module architecture and string inverter topology are converging to reshape performance optimization strategies. Equipment selection now prioritizes degradation resistance and grid-forming capability over upfront capital minimization.
Bifacial photovoltaic modules are capturing reflected irradiance from ground surfaces to boost energy yield per watt-peak. Utility-scale developers in Queensland and New South Wales are specifying double-glass frameless designs as standard. This technology is hybridizing with single-axis tracking systems to compress levelized cost of energy benchmarks below fixed-tilt configurations.
The Australian Energy Market Operator's Integrated System Plan is mandating grid-forming inverter standards for new solar connections. This regulatory shift requires hardware capable of providing synthetic inertia and voltage support during network disturbances. Remote and fringe-of-grid installations in Western Australia face the most stringent compliance timelines and are accelerating procurement of advanced power electronics.
Large energy users are bypassing traditional retailers to contract directly with solar-battery project developers. Mining operations in the Pilbara and Hunter Valley are leading this channel disintermediation, negotiating 10-15 year offtake agreements with embedded optionality for green hydrogen offtake. This behavioral shift is most visible in Western Australia where grid isolation amplifies energy security premiums.
Australia Solar Market Segmentation
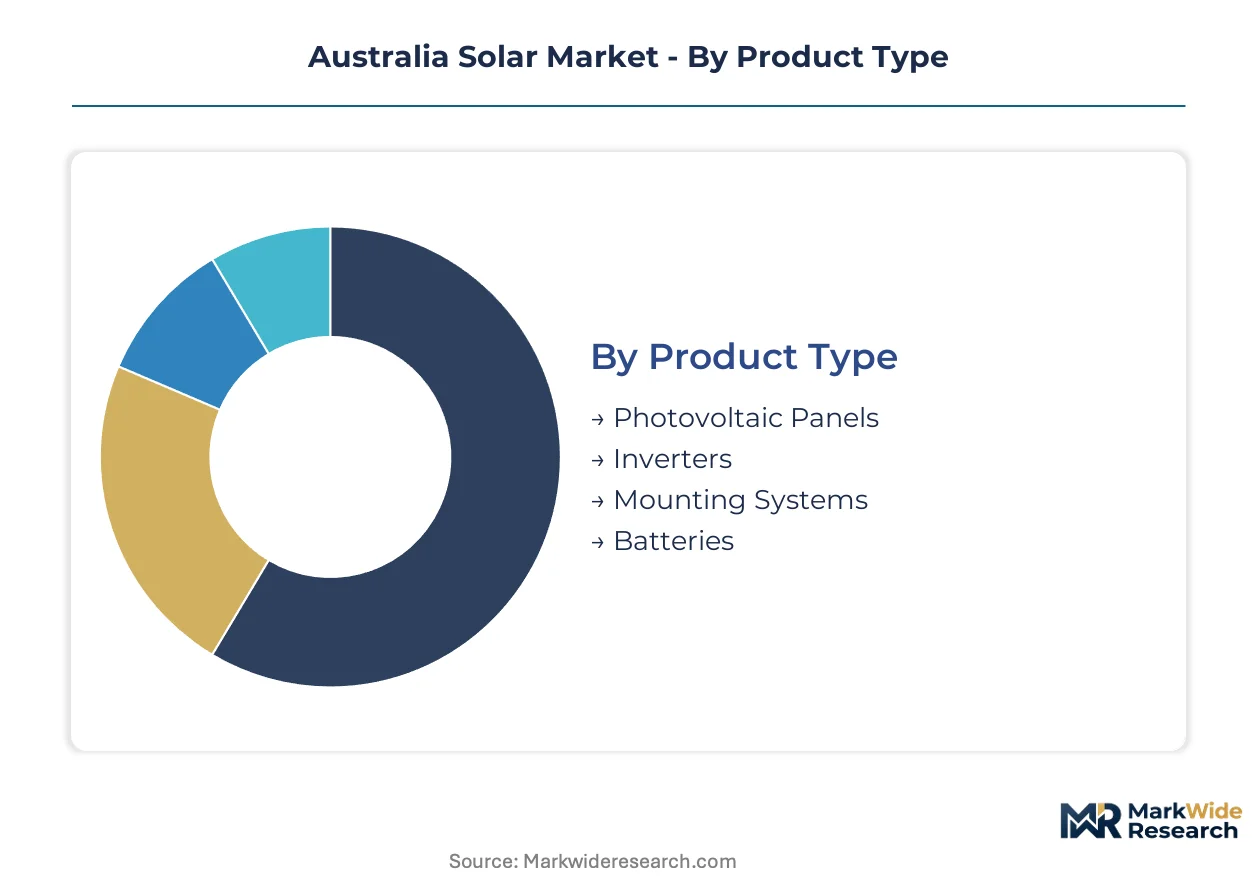
Segmentation in the Australia solar market reveals divergent procurement cycles and margin structures across equipment categories. Understanding these patterns helps stakeholders align inventory strategies with project development timelines and regulatory accreditation windows.
Product Type:
Photovoltaic panels and batteries operate on fundamentally different replacement cycles, with the former measured in decades and the latter in single-digit years as energy density improves.
- Photovoltaic Panels:Silicon-based semiconductor assemblies rated between 400 and 700 watts under standard test conditions. Queensland and New South Wales utility-scale developers are specifying double-glass frameless designs as baseline requirements for new solar zone projects.
- Inverters:Power electronics converting DC module output to grid-synchronous AC, with string topology displacing central inverters in commercial applications. The Australian Energy Market Operator's grid-forming standards are accelerating procurement of synthetic inertia-capable units in Western Australia fringe-of-grid zones.
- Mounting Systems:Structural hardware securing panels to rooftops or ground arrays, with single-axis tracking commanding premium positioning in Queensland's renewable energy corridors.
- Batteries:Lithium-ion electrochemical storage systems scaling from 5 kilowatt-hour residential units to hundred-megawatt-hour grid assets. Virtual power plant aggregation through Tesla and Sonnen enrollment programs is creating software-layer revenue pools beyond hardware sales.
Photovoltaic panels anchor the volume base while batteries gain share at the steepest rate.
Technology:
Cost tiers separate established wafer architectures from emerging high-yield configurations, with bifacial modules commanding manufacturing premiums that developers recover through energy yield guarantees.
- Monocrystalline:Single-crystal silicon wafers delivering highest conversion efficiency in commercial and utility deployments. LONGi Green Energy leverages wafer scale to compete on cost-per-watt across Australian market segments.
- Polycrystalline:Multi-crystal silicon formed through melt-casting processes, retaining residual demand in price-sensitive residential retrofits where roof space constraints are less severe.
- Thin Film:Cadmium telluride or copper indium gallium selenide deposited on glass substrates, occupying niche applications in building-integrated photovoltaics where weight and flexibility outweigh efficiency penalties.
- Bifacial:Double-sided cells capturing direct and reflected irradiance, with ground-mounted installations in Queensland achieving yield premiums over monofacial equivalents through albedo optimization on light-colored surfaces.
Monocrystalline technology dominates installed capacity while bifacial configurations expand most quickly in utility procurement.
Application:
Customer type determines project scale, financing structure, and regulatory pathway, with utility-scale developments navigating Australian Energy Market Commission connection queues that residential installers bypass through standardized net metering.
- Residential:Rooftop systems typically below 10 kilowatts capacity, sustained by Small-scale Technology Certificate offsets and state-level feed-in tariffs. New building codes across multiple states mandate solar-ready construction, embedding volume into housing starts.
- Commercial:Behind-the-meter installations serving office buildings, warehouses, and retail premises, with payback periods sensitive to Essential Services Commission of Victoria and IPART tariff structures.
- Industrial:Megawatt-scale systems offsetting process energy for manufacturing and cold storage facilities, frequently paired with battery buffers to manage network demand charges.
- Utility Scale:Grid-connected solar farms exceeding 5 megawatts, increasingly co-located with storage to secure firm capacity contracts under revised National Electricity Market rules.
Utility-scale deployment leads capital deployment while residential installations sustain volume through building code integration.
Distribution Channel:
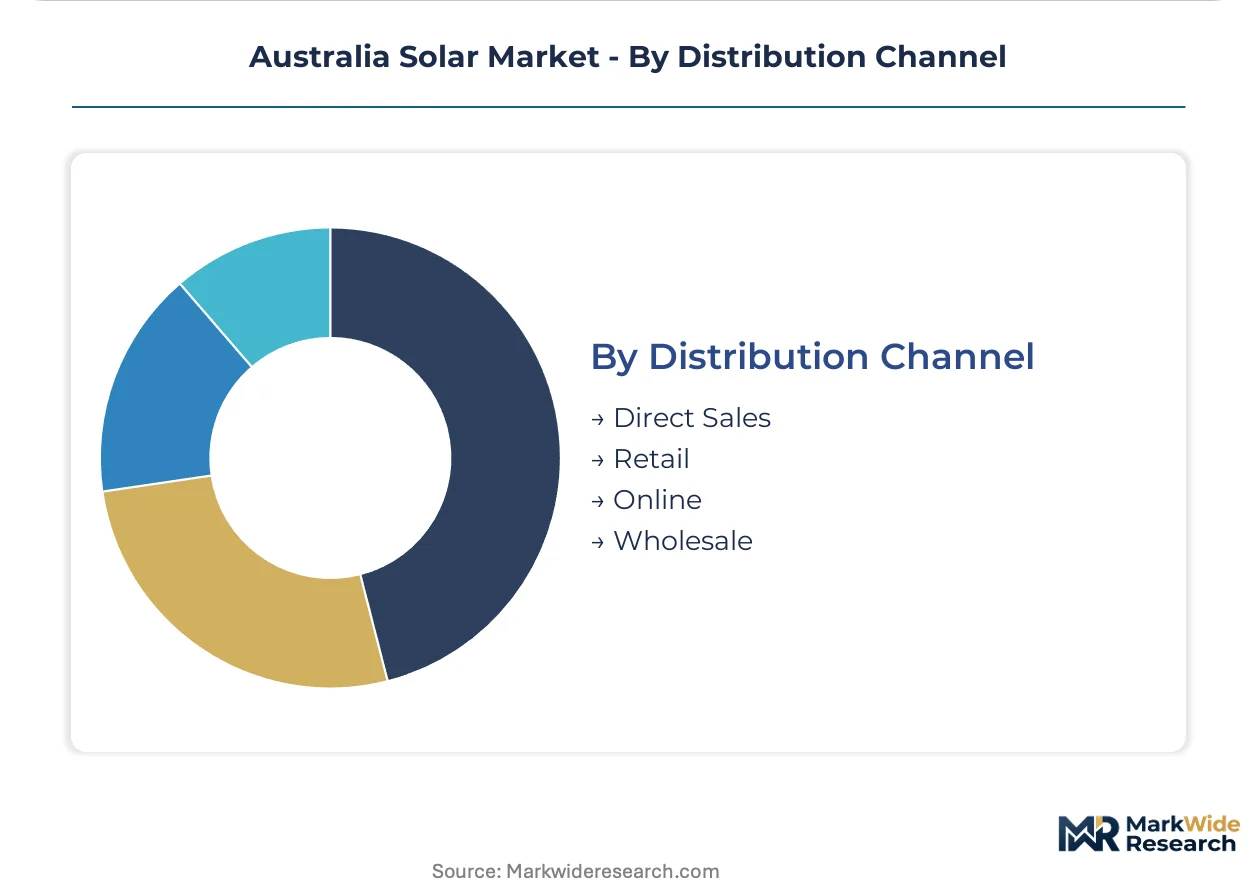
Channel selection reflects buyer sophistication and project complexity, with direct relationships dominating gigawatt-scale procurement while retail and digital channels fragment residential acquisition patterns.
- Direct Sales:Manufacturer-to-developer contracting for utility-scale equipment procurement, compressing development timelines through bundled module-inverter-storage packages.
- Retail:Bricks-and-mortar and digital storefronts serving residential and small commercial buyers, with Clean Energy Council accreditation determining product eligibility for certificate programs.
- Online:E-commerce platforms aggregating comparison tools and financing options, capturing younger demographics in metropolitan markets.
- Wholesale:Distributor networks supplying electrical contractors and installation firms, with inventory positioning in Melbourne and Brisbane warehouses determining regional availability.
Direct sales capture the largest transaction values while online channels are climbing the fastest in customer acquisition metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Clean Energy Council accreditation framework governs equipment eligibility across Australian states, while state-level renewable energy targets and transmission upgrades drive deployment geography. Queensland and New South Wales lead utility-scale procurement through designated solar zones.
New South Wales
Agrivoltaic installations on grazing land qualify for regional development grants, diversifying landholder revenue beyond traditional agriculture. IPART sets feed-in tariff structures that shape residential solar payback periods across the state. The Central West Orana Renewable Energy Zone near Dubbo hosts gigawatt-scale project pipelines unlocked by transmission augmentation timelines.
Queensland
State government-designated solar corridors with streamlined planning approvals accelerate transmission-constrained project development in the state's north. The Queensland Renewable Energy Zones framework mandates coordinated infrastructure investment across multiple shires. The Darling Downs and North Queensland regions concentrate utility-scale bifacial tracking installations on high-albedo grazing land.
Victoria
The Essential Services Commission of Victoria administers feed-in tariff structures that sustain residential installation economics despite network hosting capacity constraints. New building codes mandate solar-ready construction, embedding rooftop volume into metropolitan housing starts. The Latrobe Valley transition corridor attracts utility-scale battery-solar hybrids repurposing former coal transmission infrastructure.
Western Australia
Grid isolation amplifies energy security premiums for mining operations contracting directly with solar-battery developers. The Australian Energy Market Operator's grid-forming inverter standards impose stringent compliance timelines for fringe-of-grid installations in the Pilbara and Kimberley regions. The Pilbara hydrogen hub couples electrolyzer demand with dedicated solar generation under the Hydrogen Headstart program.
South Australia
Virtual power plant aggregation through Tesla and Sonnen enrollment programs creates software-layer revenue pools from residential battery dispatch. Master Electricians Australia reports insufficient accredited installers to meet rooftop demand surges in Adelaide metropolitan areas. The state's high distributed energy resource penetration triggers network connection queue management protocols through SA Power Networks.
Australia Solar Market Competitive Landscape
Chinese module manufacturers and European inverter specialists split the market along equipment-category lines. Tier-one solar panel suppliers with integrated wafer-to-module operations occupy procurement shortlists for utility-scale developers seeking bankability assurances. Inverter and battery system providers differentiate through grid-forming compliance and virtual power plant software integration. Competitive positioning crystallizes around bundled supply agreements and co-location project development partnerships.
Among Chinese photovoltaic manufacturers, Trina Solar, JinkoSolar, and LONGi Green Energy exemplify the scale-driven archetype that dominates module procurement channels. These entities leverage polysilicon-to-module integration to compete on cost-per-watt benchmarks across Australian utility and commercial segments. European and Australian specialists occupy differentiated positions: Fronius represents the climate-hardened inverter segment, while Tindo Solar anchors domestic manufacturing credentials for public procurement preferences. Sungrow and Enphase Energy Australia sit within the power electronics tier, with the former emphasizing utility-scale storage integration and the latter targeting residential microinverter deployment.
| Leading Market Players |
|---|
| Trina Solar |
| JinkoSolar |
| LONGi Green Energy |
| Canadian Solar |
| Tindo Solar |
| Fronius |
| Sungrow |
| Enphase Energy Australia |
| Redback Technologies |
| Others |
Pricing and Supply Chain Analysis
Chinese polysilicon processing concentration anchors module cost structures, with Australian developers absorbing volatility through long-term offtake contracts that lock margin pools at the project finance layer rather than equipment procurement. This upstream bottleneck feeds directly into developer procurement strategies, compressing supplier choice while elevating bankability requirements for tier-one module manufacturers.
Pricing Analysis
Queensland and New South Wales project developers observe wider module price spreads than Victorian residential installers due to bulk procurement scale and shipping logistics. Three-tier pricing structure across premium, standard, and economy levels separates bifacial tracking configurations from fixed-tilt polycrystalline retrofits, with Clean Energy Council accreditation acting as the primary quality differentiator. Pricing pressure stems from Chinese polysilicon supply bottlenecks that amplify contract renegotiation risk during procurement cycles. Utility-scale developers exhibit lowest price sensitivity due to long-term PPA revenue certainty, while residential retrofit buyers face compressed payback calculations under evolving feed-in tariff structures.
Supply Chain Analysis
Extended payment terms from Chinese module manufacturers have become standard practice, with supply-chain finance facilities bridging working capital gaps for Australian EPC contractors awaiting grid connection commissioning. Manufacturing concentrates in China, Vietnam, and Malaysia for cell and module assembly, while inverter production centers on Germany and China. Polysilicon feedstock, silver metallization paste, and aluminum framing constitute critical input dependencies. Single-source vulnerability persists for Australian developers locked into JinkoSolar and LONGi Green Energy supply agreements without qualified secondary suppliers. Distribution runs through Melbourne and Brisbane wholesale hubs serving electrical contractor networks across the National Electricity Market.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where Clean Energy Council accreditation creates regulatory entrenchment, raising switching costs for developers locked into approved product lists and certificate-eligible supply chains.
For Market Incumbents: Entrench market position by securing exclusive module supply agreements with Queensland Renewable Energy Zone developers before transmission augmentation timelines compress procurement windows. Deepen backward integration into polysilicon sourcing through offtake contracts with Chinese suppliers, insulating margin exposure to raw material volatility. The threat of emerging Southeast Asian module manufacturers with lower carbon footprints requires proactive bankability investment to maintain tier-one status. For New Entrants and Emerging Players: Pursue agrivoltaic development opportunities in New South Wales regional corridors where grazing land dual-use qualifies for development grants with streamlined planning approvals. Target Western Australia fringe-of-grid installations where grid-forming inverter compliance mandates create technology differentiation openings against established string inverter suppliers. A software-layer go-to-market angle through virtual power plant aggregation platforms offers faster customer acquisition than hardware-only positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed EPC contractors holding contracted project pipelines in Queensland and New South Wales solar zones awaiting final investment decision. Long-term viability over a multi-year horizon hinges on successful grid connection queue navigation and storage co-location execution. The signal to watch is Australian Energy Market Commission connection standard revisions that could accelerate or delay project commissioning timelines across the development pipeline.| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Development | Bundling solar generation with battery assets secures firm capacity contracts under revised National Electricity Market rules. |
| Grid-forming Inverter Certification | Compliance with Australian Energy Market Operator synthetic inertia standards unlocks Western Australia fringe-of-grid procurement. |
| Agrivoltaic Project Structuring | Dual-use solar installations on New South Wales grazing land qualify for regional development grant funding streams. |
| Virtual Power Plant Platform Buildout | Tesla and Sonnen enrollment programs create software-layer revenue pools beyond residential battery hardware sales. |
| Polysilicon Supply Contracting | Long-term offtake agreements with Chinese processors mitigate module price volatility and contract renegotiation exposure. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration against project development timelines and connection queue dynamics. Primary interviews with Clean Energy Council accreditation specialists and state regulator technical staff combined with secondary validation from Australian Energy Market Operator Integrated System Plan documents, Clean Energy Council accreditation databases, Essential Services Commission of Victoria tariff determinations, and IPART pricing reviews. Bottom-up project pipeline aggregation triangulated against top-down National Electricity Market capacity forecasts.
Scenario-bracketing framed projections across the analysis window, modeling demand trajectories under varying transmission augmentation timelines and storage co-location adoption curves. Segmentation dimensions included product type, technology architecture, application scale, and distribution channel, with regional grid constraints and state renewable energy target compliance schedules as additional industry-specific variables. CAGRs derived from installed capacity buildout rates, equipment replacement cycles, and certificate program eligibility windows.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese module manufacturers with captive polysilicon supply would shift outcomes through accelerated cost compression. Macroeconomic deviation in Australian dollar exchange rates, regulatory revision to Small-scale Technology Certificate eligibility, or breakthroughs in perovskite tandem cell commercialization would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Bench Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Turkey Solar Energy Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Organic PV Solar Cells Market